
 Spinal Pumps Market | 2026-2036
Spinal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Pumps Market Outlook
Hospital procurement of intrathecal delivery systems is hardening as integrated delivery networks consolidate purchasing decisions. Medtronic leverages its vertically integrated manufacturing footprint to sustain dominant positions in programmable pump platforms. Flowonix Medical specializes in micro pump technology for niche spasticity applications, while Teleflex Incorporated competes through catheter-pump system innovation.
Spinal pumps are implantable or external drug delivery devices that administer medication directly into the intrathecal space via precision-calibrated reservoirs and programmable flow mechanisms, primarily serving chronic pain management and neurological spasticity treatment in clinical and home care settings. Programmable pumps command premium positioning due to titration flexibility, whereas non-programmable pumps occupy cost-sensitive segments in emerging facilities. Intrathecal delivery technology anchors the largest value pool, with micro pump technology representing the fastest-growing innovation frontier as miniaturization improves patient ambulation.
The FDA enforces stringent premarket approval pathways for implantable pumps, while the EU MDR imposes enhanced clinical evidence requirements under CE marking protocols that reshape market access timelines. ISO 13485 quality management standards govern manufacturing consistency across all major production jurisdictions. Stakeholders must monitor evolving reimbursement thresholds for home care infusion as payors recalibrate coverage for long-term intrathecal therapy.
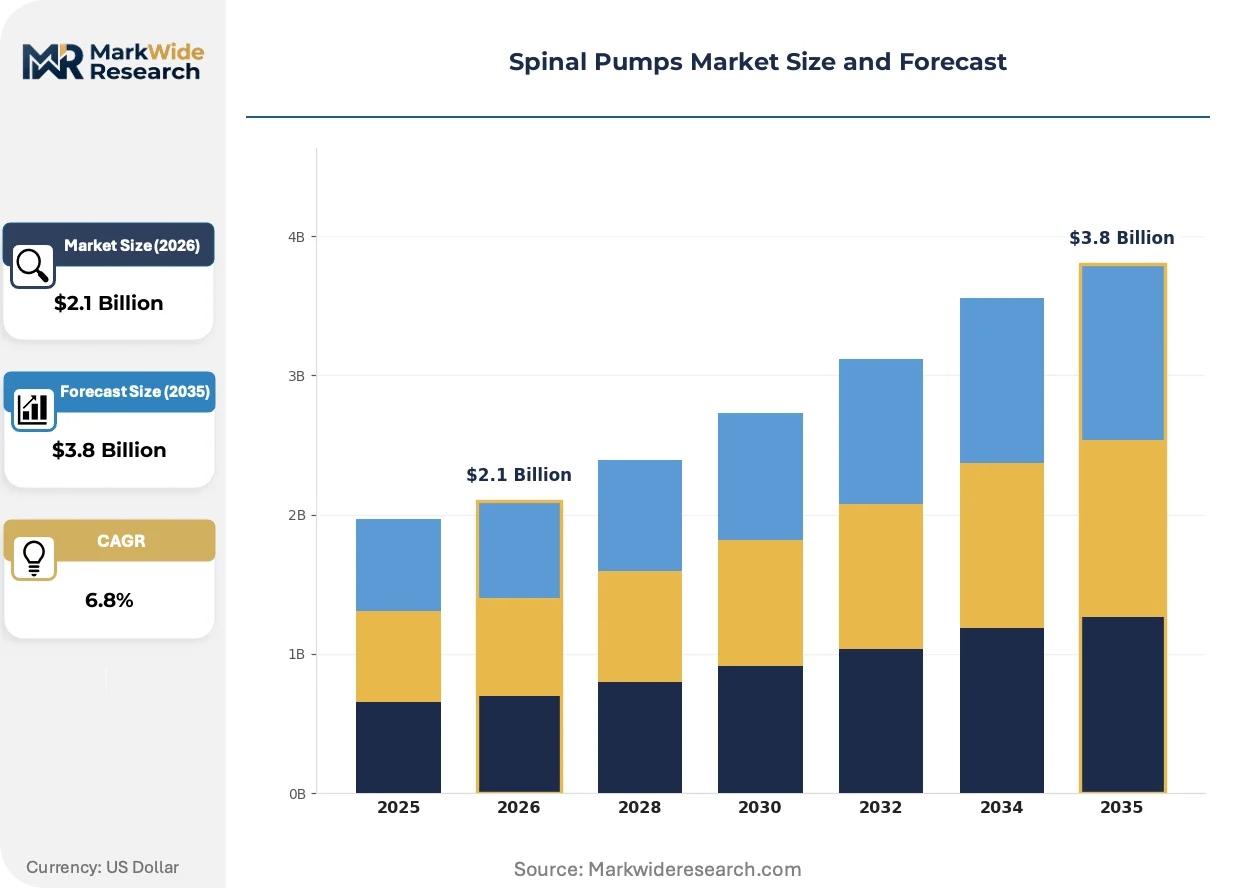
Market Dynamics
Integrated delivery networks are consolidating purchasing decisions for intrathecal delivery systems, hardening procurement standards and squeezing smaller manufacturers that lack vertically integrated supply chains or comprehensive service infrastructures.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated review pathways for next-generation programmable pump platforms compress time-to-market for novel intrathecal delivery technologies targeting refractory chronic pain.
- Home care infusion protocols:Reimbursement recalibration by Medicare and commercial payors expands patient eligibility for long-term ambulatory pump therapy outside acute settings.
- Micro pump miniaturization:Advances in MEMS fabrication and precision fluid dynamics enable catheter-pump systems with substantially reduced form factors, improving patient mobility and device acceptance.
Market Restraints
- Premium device cost structures:Programmable pump platforms carry price points that strain capital budgets at independent surgical centers and emerging-market facilities.
- EU MDR clinical evidence requirements:Enhanced post-market surveillance and PMCF study obligations extend CE marking timelines by 18-36 months for implantable drug delivery systems.
- Catheter complication rates:Granuloma formation and mechanical failures in intrathecal catheters drive revision surgeries, limiting physician willingness to initiate therapy in borderline candidates.
Strategic Opportunities
- Pediatric spasticity applications:Underpenetrated demand for implantable baclofen delivery in cerebral palsy patients creates expansion potential for programmable micro pump platforms with pediatric dosing algorithms.
- Japan's aging demographic:METI healthcare infrastructure investments and PMDA streamlined approval for geriatric neurological devices position the market for catheter-pump adoption in age-related spasticity management.
- Remote monitoring convergence:Integration of Bluetooth-enabled pump telemetry with electronic health record systems enables proactive intervention models and differentiated service contracting.
Industry Challenges
- Neurointerventional specialist scarcity:Limited fellowship-trained physicians capable of intrathecal catheter placement creates bottlenecks for therapy initiation and geographic access disparities.
- ISO 13485 manufacturing compliance:Quality management system audits and CAPA documentation requirements consume substantial operational resources for pump reservoir and flow mechanism production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Pumps Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Pumps, Non-Programmable Pumps, Implantable Pumps, External Pumps Technology: Intrathecal Delivery, Catheter-Pump Systems, Micro Pump Technology, Infusion Technology End User: Hospitals, Outpatient Clinics, Home Care Settings, Rehabilitation Centers Application: Chronic Pain Management, Oncology Treatment, Spasticity Management, Anesthesia |
| Companies Covered | Medtronic, Flowonix Medical, Teleflex Incorporated, Tricumed Medizintechnik GmbH, DePuy Synthes, Johnson & Johnson, Baxter, Smiths Group, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Pumps Market Strategic Shifts
Active pharmaceutical ingredient stability and biocompatibility engineering are reshaping reservoir formulation capabilities, while connectivity architectures and closed-loop control algorithms redefine how therapy delivery interfaces with clinical decision support.
Miniaturized peristaltic pump mechanisms are absorbing advances in precision motor control and biocompatible elastomer materials to enable wearable intrathecal delivery with reservoir volumes below 10 milliliters. Academic medical centers in Germany and the United States are piloting these platforms for ambulatory spasticity management. The technology is absorbing patient preference for discreet, clothing-compatible devices and compressing the historical trade-off between dosing precision and physical footprint.
The EU MDR's enhanced clinical evidence requirements under CE marking protocols are forcing manufacturers to generate PMCF data on long-term catheter-pump biocompatibility and drug stability profiles. This regulatory burden is compressing the competitive set to firms with established European notified body relationships and substantial post-market surveillance infrastructures. Implantable programmable platforms face the steepest compliance cost escalation, particularly for legacy devices without contemporary clinical trial documentation.
Hospital procurement committees are consolidating vendor selection authority and unbundling device acquisition from implantation service contracts. Integrated delivery networks in the United States are replacing individual physician preference purchasing with standardized formularies that specify catheter-pump system configurations by therapeutic indication. This concentration is most visible in the southeastern and midwestern hospital systems, where IDN consolidation has advanced furthest and supply chain rationalization targets implantable device categories specifically.
Spinal Pumps Market Segmentation
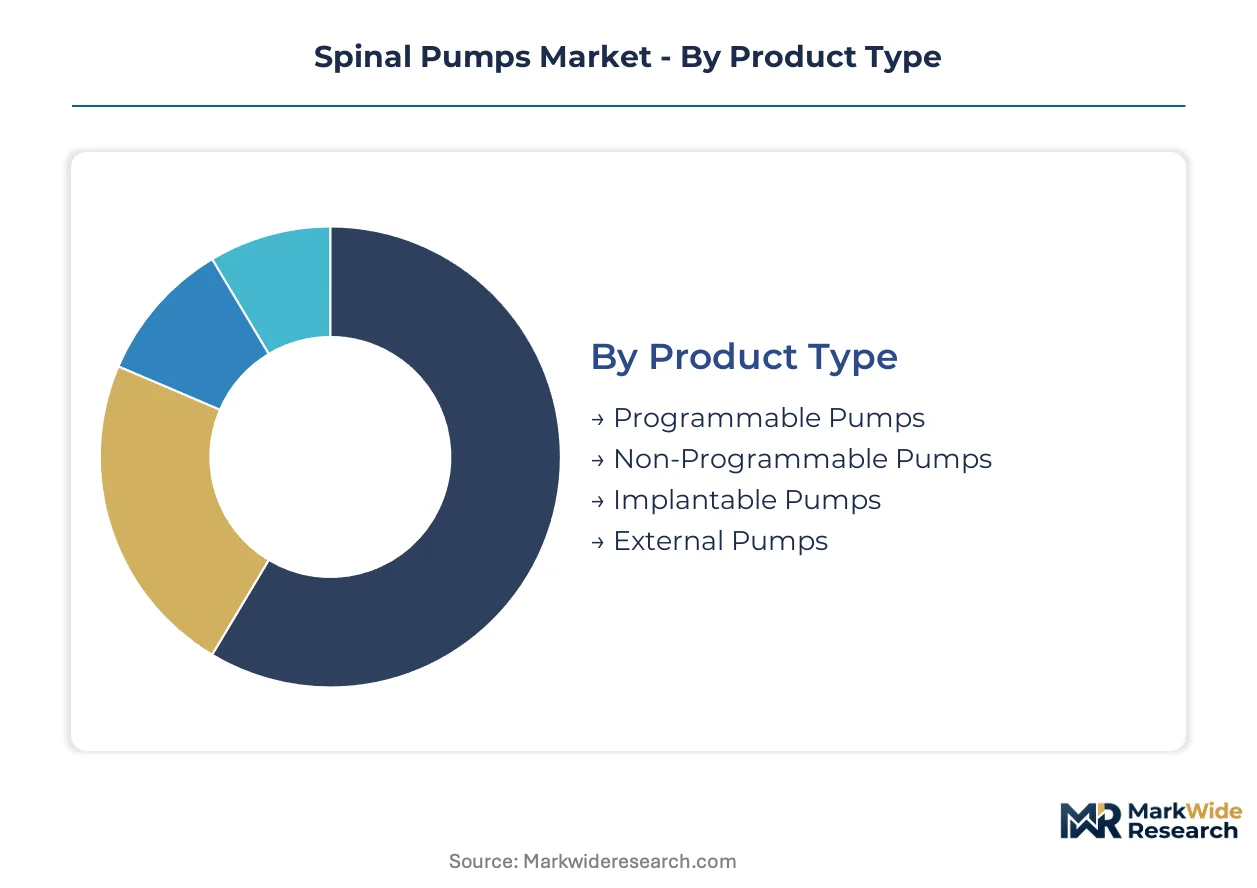
Spinal pump procurement decisions diverge sharply across clinical settings, with reimbursement thresholds and therapy duration dicting hardware specifications. Technology maturity and patient ambulation requirements further fragment vendor positioning across the four core segmentation dimensions.
Product Type:
Hospital capital committees weigh titration flexibility against total cost of ownership when specifying implantable hardware.
- Programmable Pumps:Electronically calibrated reservoirs with wireless telemetry enable dose adjustments without surgical intervention. Demand concentrates in United States academic medical centers managing refractory chronic pain, driven by Medicare reimbursement for home-based titration protocols.
- Non-Programmable Pumps:Fixed-rate mechanical delivery systems with simpler flow mechanisms and lower acquisition costs. Emerging-market hospitals in India and Brazil select these for spasticity management where follow-up access is limited.
- Implantable Pumps:Subcutaneous devices with multi-year battery life designed for chronic intrathecal therapy. These dominate long-term pain management protocols in German and Japanese rehabilitation networks.
- External Pumps:Percutaneous or wearable systems for temporary post-operative analgesia and trial dosing phases. Outpatient surgical centers deploy these for catheter viability assessment before permanent implantation.
Programmable pumps lead on scale; micro pump-enabled external systems lead on momentum.
Technology:
Fluid dynamics precision and biocompatibility engineering determine competitive differentiation in delivery mechanism selection.
- Intrathecal Delivery:Direct cerebrospinal fluid administration bypassing blood-brain barrier constraints. United States pain management protocols favor this for opioid-sparing refractory cases, though granuloma surveillance requirements constrain expansion.
- Catheter-Pump Systems:Integrated reservoir-catheter configurations with programmable flow control. These anchor hospital procurement formularies across southeastern United States integrated delivery networks consolidating vendor selection authority.
- Micro Pump Technology:MEMS-fabricated peristaltic mechanisms with sub-10 milliliter reservoirs enabling wearable ambulatory delivery. Academic centers in Germany pilot these for pediatric cerebral palsy applications where device footprint determines acceptance.
- Infusion Technology:External precision pumping for temporary or bolus-administered intrathecal therapy. Home care infusion providers deploy these for short-cycle oncology pain protocols requiring rapid dose escalation.
Catheter-pump systems command installed base dominance; micro pump platforms are climbing the fastest.
End User:
Site-of-care economics and reimbursement calibration reshape hardware specification across delivery settings.
- Hospitals:Acute care facilities with neurointerventional suites and 24-hour implantation coverage. These drive volume for programmable platforms requiring specialist placement capabilities and intensive care backup.
- Outpatient Clinics:Ambulatory surgical centers performing trial catheter placements and pump refills. Medicare reimbursement shifts for same-day procedures are concentrating refill volume in these settings.
- Home Care Settings:Patient residences with nursing support for long-term infusion and telemetry monitoring. United States payor recalibration of home infusion benefits is expanding eligibility for ambulatory programmable therapy.
- Rehabilitation Centers:Post-acute facilities managing spasticity with baclofen delivery and physical therapy integration. Japan's METI infrastructure investments are positioning these for geriatric neurological device adoption.
Hospitals retain procedure volume leadership; home care settings are gaining share fastest.
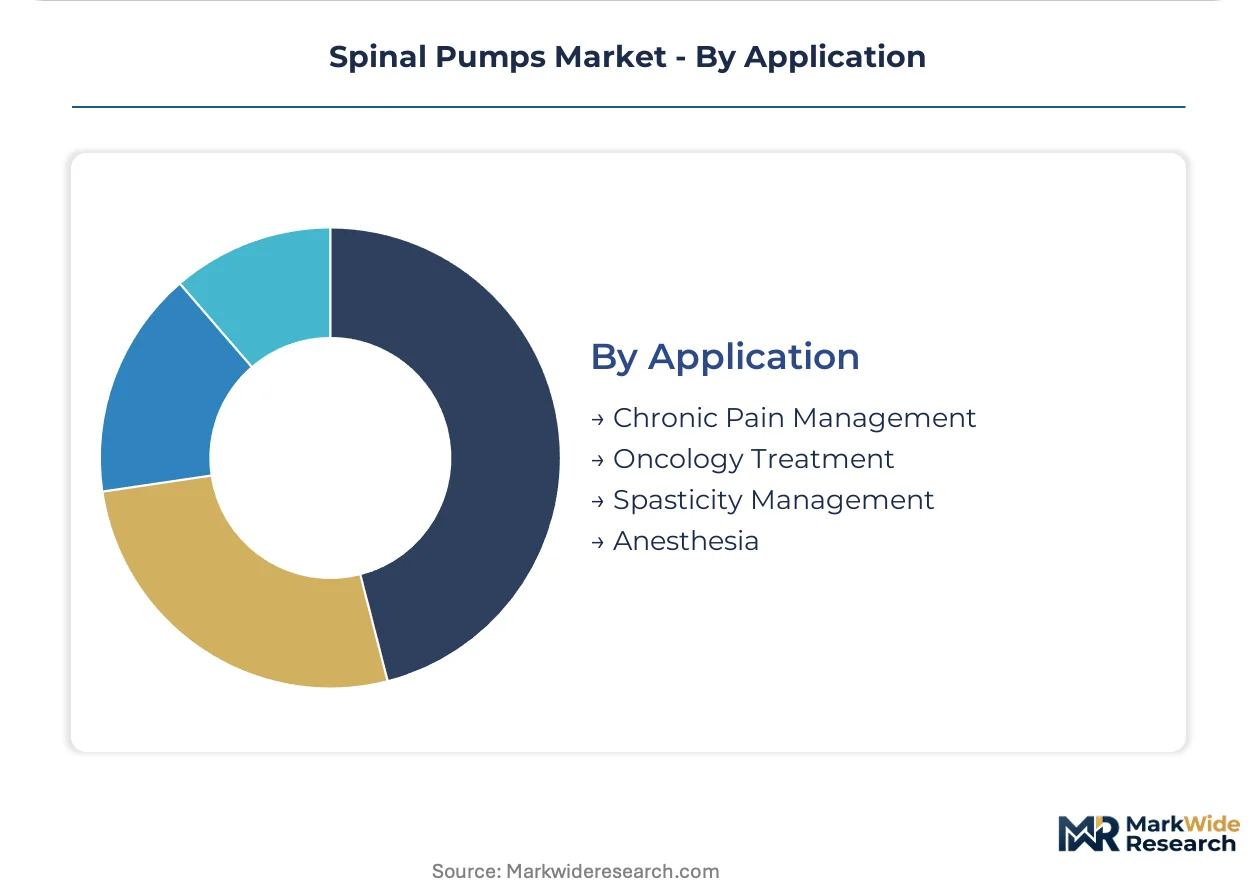
Application:
Therapeutic indication determines drug formulation compatibility, dosing algorithm requirements, and regulatory pathway complexity.
- Chronic Pain Management:Long-term opioid and non-opioid intrathecal delivery for refractory nociceptive and neuropathic conditions. United States prescribing protocols increasingly require documented failure of conventional modalities before pump initiation.
- Oncology Treatment:Intrathecal chemotherapy administration and breakthrough pain control in terminal malignancy. These applications require drug stability engineering for cytotoxic agent compatibility with pump reservoir materials.
- Spasticity Management:Baclofen delivery for cerebral palsy, multiple sclerosis, and spinal cord injury. Pediatric applications remain underpenetrated due to device size constraints and dosing algorithm limitations.
- Anesthesia:Perioperative and post-operative intrathecal analgesia with short-duration delivery requirements. Ambulatory surgical centers specify external micro pumps for these applications to avoid implantation costs.
Chronic pain management anchors revenue concentration; spasticity management shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurointerventional specialists cluster in academic medical centers across the United States, Germany, and Japan, anchoring demand for programmable pump implantation capabilities. These trained physician concentrations determine market penetration rates for intrathecal delivery systems.
United States
Medicare reimbursement for home-based titration protocols drives demand for programmable platforms at academic medical centers. The FDA's Breakthrough Devices Program accelerates review pathways for next-generation intrathecal technologies. Southeastern integrated delivery networks consolidate vendor selection authority, standardizing catheter-pump system configurations across hospital systems.
Germany
Rehabilitation networks prioritize implantable pumps for long-term baclofen delivery in spasticity management. The EU MDR imposes enhanced clinical evidence requirements under CE marking protocols that reshape market access timelines. Academic centers in Bavaria pilot micro pump platforms for pediatric cerebral palsy applications where device footprint determines patient acceptance.
Japan
METI healthcare infrastructure investments target geriatric neurological device adoption in aging populations. The PMDA streamlines approval pathways for devices addressing age-related spasticity management. Rehabilitation centers in the Kanto region around Tokyo position for catheter-pump system expansion as infrastructure investments mature.
India
Emerging-market hospitals select non-programmable pumps for spasticity management where follow-up access remains limited. The CDSCO regulates implantable medical devices under enhanced scrutiny aligned with international standards. Medical device clusters in Maharashtra and Karnataka absorb manufacturing partnerships for cost-sensitive pump platforms.
Brazil
ANVISA oversight of implantable drug delivery systems creates compliance thresholds for market entry. Emerging facilities in São Paulo and Rio de Janeiro states prioritize fixed-rate mechanical delivery systems for capital-constrained procurement environments. Regional distribution networks concentrate refill services in southeastern metropolitan corridors.
Spinal Pumps Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across programmable pump platforms and catheter-pump system configurations. Market structure tilts toward consolidation as integrated delivery networks harden procurement standards and squeeze manufacturers lacking comprehensive service infrastructures. Three archetypes dominate: vertically integrated device-service platforms, micro pump technology specialists, and diversified medtech conglomerates with neurological portfolios. Competitive moves concentrate on strategic partnerships for telemetry integration and geographic expansion into underpenetrated pediatric and geriatric segments.
Within the vertically integrated tier, Medtronic anchors market positioning through captive manufacturing and service infrastructure. Flowonix Medical exemplifies the micro pump specialist archetype with focused technology development. Teleflex Incorporated occupies a diversified conglomerate position, competing through catheter system innovation rather than pump hardware specialization.
| Leading Market Players |
|---|
| Medtronic |
| Flowonix Medical |
| Teleflex Incorporated |
| Tricumed Medizintechnik GmbH |
| DePuy Synthes |
| Johnson & Johnson |
| Baxter |
| Smiths Group |
| Globus Medical |
| Others |
Value Chain & Pricing Dynamics
Neurointerventional specialist concentrations in the United States and Germany create labor-cost differentials that widen spreads between premium programmable platforms and economy-tier non-programmable alternatives. These regional wage disparities in fellowship-trained physician availability cascade through device pricing tiers as manufacturers calibrate service bundling to local implantation economics.
Pricing Analysis
Bundled service contracts historically dominated spinal pump procurement, though integrated delivery networks now unbundle device acquisition from implantation and refill services. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Breakthrough Device designation status, ISO 13485 certification tier, and geographic delivery cost differentials. Pricing pressure stems from IDN formulary standardization that squeezes margins on legacy programmable platforms. Independent surgical centers in emerging markets exhibit highest price sensitivity, while United States academic medical centers with captive reimbursement for home-based titration show lowest sensitivity to acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with precision peristaltic motor suppliers concentrated in Japan and Germany for MEMS-fabricated micro pump mechanisms. Biocompatible elastomer reservoir materials draw from specialized chemical processors in the United States and Switzerland, while battery cell supply for implantable platforms rests on South Korean and Japanese manufacturers. Tariff exposure on precision-machined flow control components creates supply chain risk as trade policy shifts. Distribution runs through regional medical device distributors with neurointerventional specialization, consolidating last-mile delivery to hospital systems and outpatient surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Europe run substantially higher than PMDA streamlined pathways in Japan, creating differential returns on identical device platforms across regulatory jurisdictions.
For Market Incumbents: Extend service infrastructure depth to defend against IDN procurement consolidation that favors vertically integrated device-service platforms. Capture backward integration into biocompatible elastomer reservoir manufacturing to offset raw material cost volatility. Deepen telemetry integration capabilities as Bluetooth-enabled pump monitoring becomes a formulary differentiator. For New Entrants and Emerging Players: Bluetooth-enabled telemetry modules offer a technology-first wedge into the remote monitoring convergence opportunity. Pediatric spasticity applications in cerebral palsy remain the most penetrable segment due to device size constraints limiting incumbent platform adaptation. Pursue academic medical center pilot partnerships in Germany where micro pump miniaturization trials create early reference sites. For Investors and Strategic Acquirers: Valuations sit cheapest among micro pump technology specialists lacking comprehensive service infrastructures but holding MEMS fabrication IP. Long-term viability over the next decade hinges on regulatory pathway execution rather than manufacturing scale. Watch FDA Breakthrough Device designations as the signal indicating which programmable platforms will compress time-to-market and capture IDN formulary slots.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements reshape market access timelines for implantable systems. |
| Hospital System Partnership | IDN procurement consolidation demands captive service infrastructure and standardized formulary compliance. |
| Software Companion Development | Bluetooth-enabled telemetry integration with EHR systems enables proactive intervention models. |
| Reimbursement Strategy | Medicare home-based titration protocol expansion drives programmable pump eligibility in ambulatory settings. |
| FDA Submission | Breakthrough Devices Program accelerates review pathways for next-generation intrathecal delivery technologies. |
Study Parameters
Direct dialogue with neurointerventional specialists, hospital purchasing committee members, biomedical engineers at implantable device manufacturers, and GPO contracts managers grounded qualitative findings in clinical and procurement realities. Secondary validation drew from FDA 510(k) and PMA filings, EMA CE marking documentation under MDR protocols, CMS Medicare reimbursement databases, and hospital procurement records from southeastern United States integrated delivery networks. Bottom-up and top-down triangulation cross-checked unit volume assumptions against aggregate market value estimates.
Bottom-up modeling anchored projections across product type, technology platform, end-user setting, and therapeutic indication dimensions. CAGRs derived from segmented growth rate analysis calibrated to reimbursement trajectory shifts and regulatory pathway timelines. The forecast framework incorporated neurointerventional specialist supply constraints, IDN procurement consolidation velocity, and micro pump miniaturization adoption curves as industry-specific inputs across the projection horizon.
The model holds under stable reimbursement and regulatory pathway assumptions; deviation in FDA enforcement posture or EU MDR audit intensity would shift volume trajectories materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Non-Operative Spine Care Market