
 Asia-Pacific Tattoo Numbing Cream Market | 2026-2036
Asia-Pacific Tattoo Numbing Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tattoo Numbing Cream Market Insights
Cosmetic tattoo clinics is bifurcating from traditional body art studios as the dominant procurement channel across the region. Tattoo Numbing Cream Co. leverages its gel formulation specialization to capture premium studio accounts in Australia. Centaur Pharmaceuticals Pvt. Ltd. anchors its position through manufacturing scale and pharmacy-grade lidocaine sourcing networks. Dr. Numb differentiates via brand recognition among individual consumers purchasing through e-commerce channels.
Asia-Pacific Tattoo Numbing Cream comprises topical anaesthetic formulations typically containing lidocaine, benzocaine, or tetracaine at concentrations between four and five percent, designed to block sodium ion channels in dermal nerve endings prior to needle penetration. The product serves commercial body art practitioners, medical dermatology clinics, and cosmetic tattoo professionals seeking to reduce patient discomfort during invasive surface procedures. Topical cream formulations currently dominate volume shipments due to lower per-unit cost and familiar application protocols among tattoo artists. Gel formats represent the fastest-growing product category as studios prioritize faster onset times and reduced residue during detailed line work. Lidocaine-based ingredient profiles command the widest formulation pipeline, though herbal extract alternatives are gaining traction among salons marketing natural positioning to sensitive-skin clientele.
Australia's Therapeutic Goods Administration and India's CDSCO both classify high-concentration lidocaine creams as restricted-schedule medicines, creating compliance thresholds that filter informal suppliers from licensed distribution channels. Japan's PMDA and South Korea's MFDS enforce additional stability testing for topical anaesthetics marketed through beauty retail, elevating documentation burdens for cross-border entrants. Stakeholders must monitor evolving ingredient concentration ceilings and channel-specific registration requirements as regulatory divergence between national pharmaceutical and cosmetic frameworks intensifies.
Market Dynamics
Regulatory divergence between pharmaceutical and cosmetic frameworks across Southeast Asian jurisdictions is fragmenting distribution pathways and forcing reformulation investments by suppliers seeking multi-country coverage.
Growth Catalysts
- Cosmetic Tattoo Clinic Expansion:Medical-aesthetic facilities in Thailand and Vietnam are absorbing numbing cream volumes previously routed through informal studio channels, creating premium-grade demand clusters.
- TRAI Ingredient Disclosure Mandates:India's tightened labeling requirements for topical anaesthetics are professionalizing supply chains and squeezing unregistered grey-market operators from pharmacy shelves.
- Lidocaine Sourcing Network Densification:Pharmaceutical-grade API procurement corridors linking Indian manufacturers to Australian formulators are shortening lead times for compliant batch production.
Market Restraints
- API Concentration Risk:Bulk lidocaine production concentrates among a handful of Chinese and Indian chemical manufacturers, exposing formulators to input price volatility and supply interruption.
- Schedule Restriction Friction:Australia's TGA and India's CDSCO both classify high-concentration lidocaine creams as restricted medicines, requiring prescription or licensed-practitioner channels that limit retail accessibility.
- Herbal Substitute Encroachment:Natural-extract alternatives marketed by salons to sensitive-skin clientele are capturing price-sensitive segments unwilling to navigate pharmaceutical compliance.
Strategic Opportunities
- Indonesia's Underpenetrated Archipelago:Tattoo studio density in secondary Indonesian cities remains a fraction of Bangkok or Manila levels, offering first-mover positioning for compliant distributors.
- E-Commerce Direct-to-Consumer Channels:South Korea's MFDS-cleared beauty retail platforms are enabling cross-border sales of lower-concentration cosmetic-grade formulations to individual buyers.
- Gel Format Technology Convergence:Faster-onset gel vehicles combining lidocaine with penetration enhancers are opening premium positioning in detailed line-work segments previously served by basic creams.
Industry Challenges
- Multi-Jurisdiction Registration Burden:Each ASEAN member maintains distinct cosmetic-pharmaceutical boundary definitions, forcing suppliers to replicate stability documentation and clinical substantiation across national filings.
- Formulation Talent Scarcity:Cosmetic chemists with dual competency in topical anaesthetic efficacy and tattoo-specific residue performance remain concentrated in Australia and Japan, constraining regional R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tattoo Numbing Cream Market |
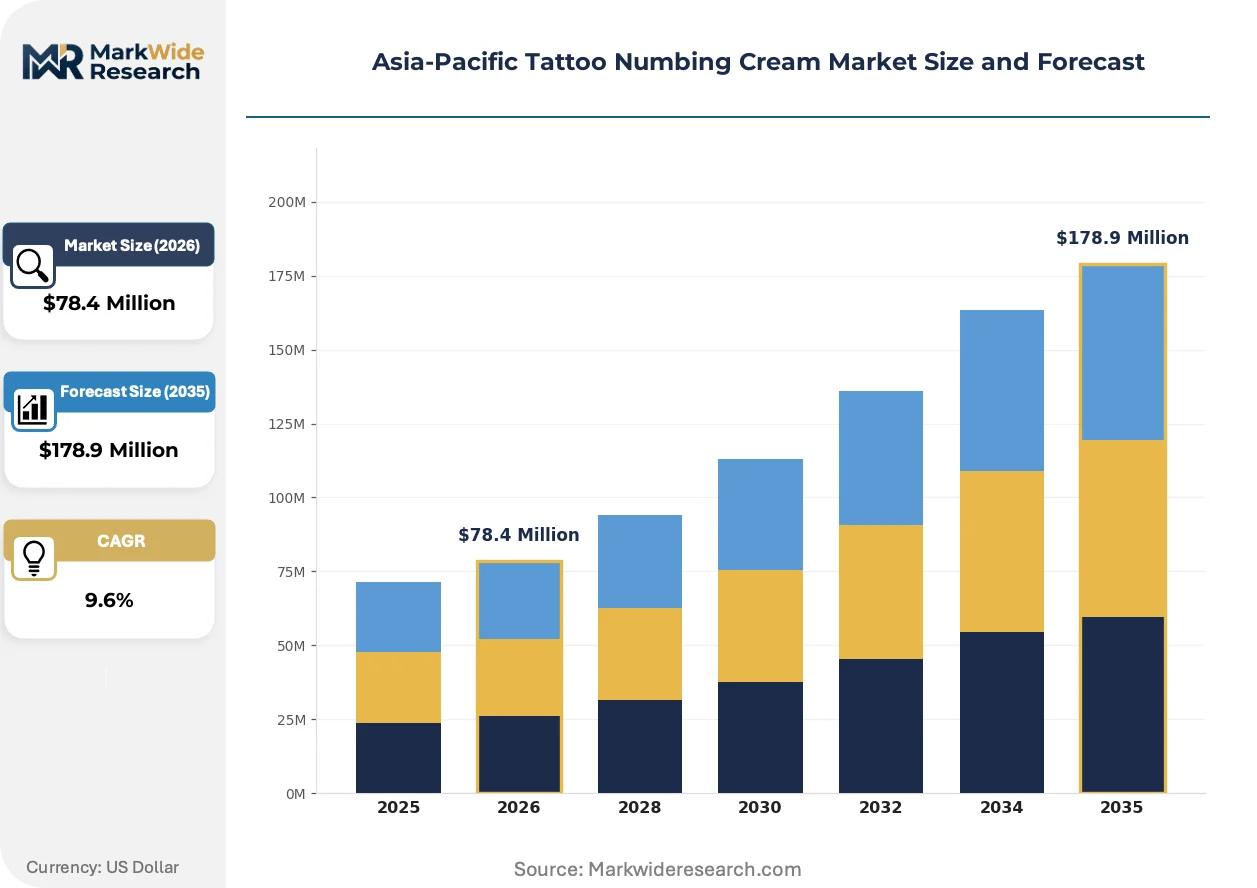
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $178.9 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Cream, Gel, Spray, Wipes Application: Body Art, Medical Procedures, Cosmetic Tattoos, Piercings Customer Type: Tattoo Studios, Clinics, Individual Consumers, Beauty Salons Ingredient: Lidocaine, Benzocaine, Tetracaine, Herbal Extracts |
| Companies Covered | Aspen Pharmacare Australia Pty Ltd, Centaur Pharmaceuticals Pvt. Ltd., Tattoo Numbing Cream Co., Zensa Skin Care, Hera Beauty Ltd., Dr. Numb, TattooNumbX, Toochi Tattoo, Painless Topical Anaesthetic Cream, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tattoo Numbing Cream Market Trends and Innovations
Product format evolution and channel digitization are compressing traditional procurement hierarchies while regulatory technology investments reshape compliance economics for cross-border suppliers.
Gel-based lidocaine vehicles with engineered viscosity profiles are displacing conventional cream formats in premium studio accounts across Australia and South Korea. Tattoo artists executing detailed geometric and portrait work prioritize faster onset kinetics and minimal residue interference during extended sessions. This displacement is compressing margin structures for legacy cream specialists unable to reformulate without API resourcing partnerships.
Japan's PMDA and South Korea's MFDS now mandate accelerated stability testing protocols for topical anaesthetics marketed through beauty retail channels, elevating documentation costs for entrants. Formulators must submit real-time degradation data under temperature-stress conditions previously required only for pharmaceutical registrations. Small-batch importers without captive laboratory infrastructure are retreating from direct retail positioning toward licensed distributor relationships.
Studio procurement officers in India and the Philippines are consolidating vendor relationships around suppliers offering integrated training and after-sales technical support, unbundling these services from traditional distributor markups. Bulk purchasing cooperatives organized through regional tattoo artist associations are compressing traditional wholesale tier margins. This consolidation is most visible in Mumbai and Bangalore, where parlour density has crossed thresholds enabling collective bargaining power.
Asia-Pacific Tattoo Numbing Cream Market Segmentation
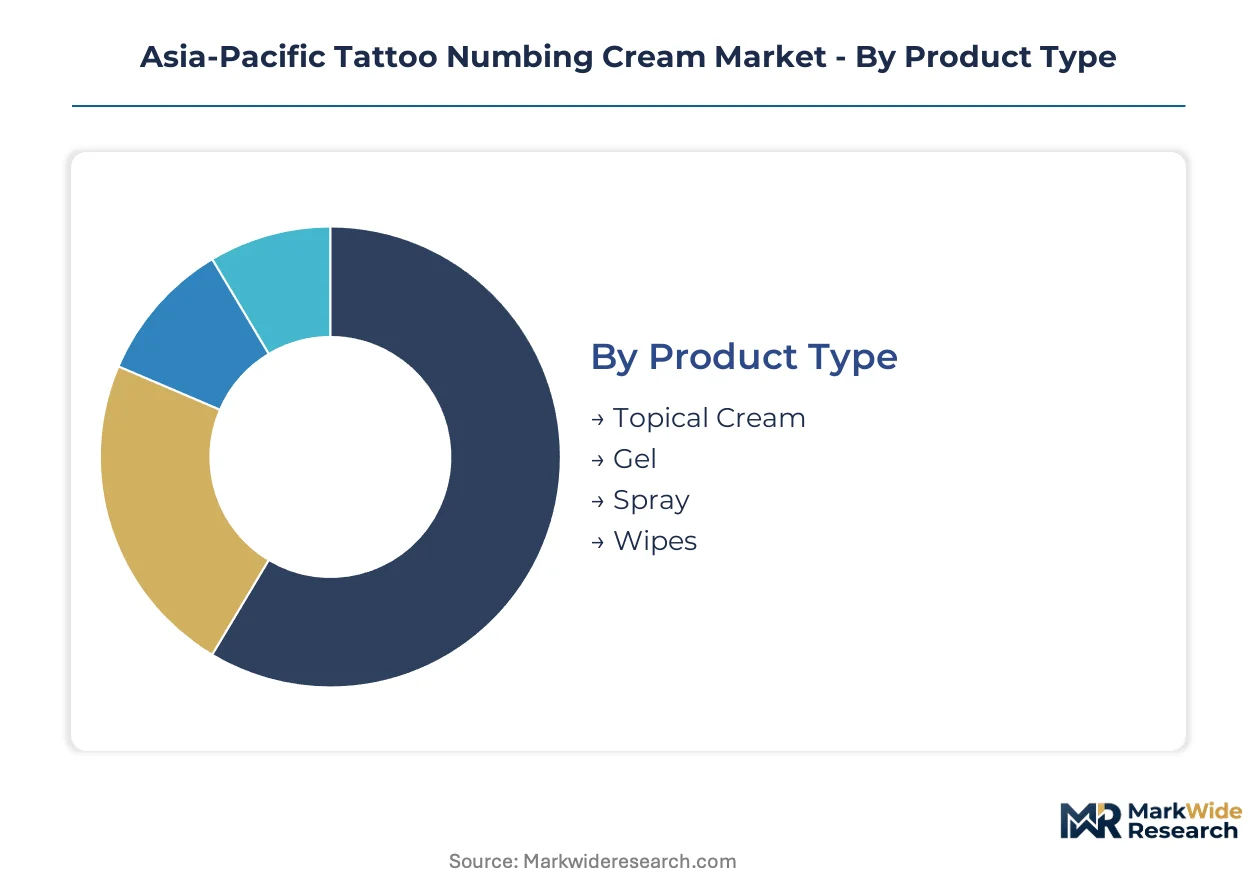
Segmentation in the Asia-Pacific tattoo numbing cream market reveals how formulation choices and procurement channels diverge across regulatory environments. Channel-mix patterns show pharmaceutical-grade products flowing through licensed clinics while cosmetic-grade variants dominate e-commerce and studio direct sales.
Product Type:
Channel-mix dynamics vary sharply across these formats, with cream and gel commanding studio procurement while spray and wipes serve individual consumer convenience channels.
- Topical Cream:Traditional oil-in-water emulsions containing lidocaine at four to five percent concentration. Studios in India and the Philippines purchase bulk containers through distributor networks, though residue complaints during extended sessions constrain premium positioning.
- Gel:Viscous hydro-alcoholic vehicles engineered for rapid dermal penetration and minimal surface residue. Australian and South Korean studios prioritize gel formats for detailed geometric work, with faster onset kinetics justifying per-unit premiums over conventional creams.
- Spray:Aerosolized lidocaine solutions targeting large-area coverage with minimal application time. Individual consumers in Japan favor spray formats for home-use piercing numbing, bypassing professional application requirements.
- Wipes:Pre-saturated towelettes offering single-use convenience and precise dosage control. Beauty salons in Thailand deploy wipes for brow and lip cosmetic tattoo procedures where cross-contamination protocols are stringent.
By volume, Topical Cream leads. By growth pace, Gel is expanding most quickly.
Application:
Cost tier stratification separates medical-grade formulations for clinical use from economy-positioned products serving informal body art channels.
- Body Art:Traditional tattooing across Southeast Asian studios drives baseline demand, with parlour density in Mumbai and Bangalore creating concentrated procurement clusters. TRAI disclosure mandates are professionalizing supply chains previously served by grey-market imports.
- Medical Procedures:Dermatological excisions and minor surgical interventions require CDSCO-registered formulations with documented stability profiles. India's hospital procurement officers prioritize batch-traceable lidocaine creams over unregistered alternatives.
- Cosmetic Tattoos:Permanent makeup applications for eyebrows, eyeliner, and lip coloration. Thailand's medical-aesthetic facilities absorb premium-grade volumes previously routed through informal studio channels, elevating formulation standards.
- Piercings:Ear, nose, and body piercing procedures in mall-based retail settings. South Korea's youth-oriented beauty districts generate concentrated demand for rapid-onset numbing suitable for walk-in service models.
Cosmetic Tattoos command the steepest margin expansion trajectory. Body Art retains the largest absolute volume footprint.
Customer Type:
Volume concentration patterns show tattoo studios consolidating vendor relationships while individual consumers fragment across e-commerce platforms.
- Tattoo Studios:Commercial parlours purchasing institutional-size containers through licensed distributors. Australia's TGA scheduling restrictions filter informal suppliers from legitimate studio procurement, compressing grey-market participation.
- Clinics:Medical-aesthetic facilities requiring pharmaceutical-grade documentation and cold-chain integrity. Vietnam's dermatology chains are absorbing numbing cream volumes with full regulatory compliance that informal channels cannot match.
- Individual Consumers:Direct purchasers through South Korean MFDS-cleared beauty retail platforms and cross-border e-commerce. Lower-concentration cosmetic-grade formulations bypass prescription requirements in this channel.
- Beauty Salons:Brow bars and permanent makeup specialists emphasizing natural-positioning to sensitive-skin clientele. Herbal extract alternatives marketed by Indonesian salons capture price-sensitive segments unwilling to navigate pharmaceutical compliance.
Clinics are gaining share fastest. Tattoo Studios maintain the deepest procurement volume.
Ingredient:
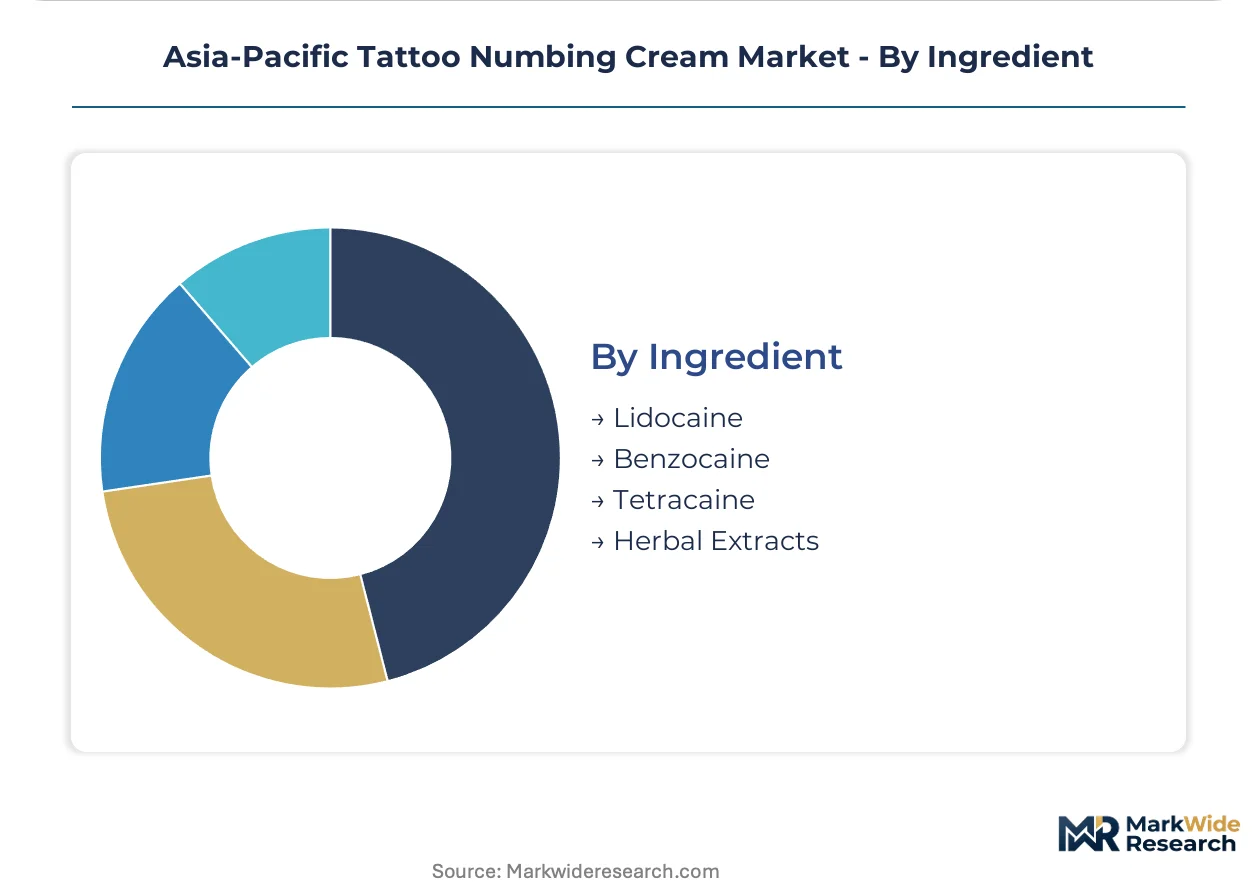
Supply concentration for active pharmaceutical ingredients shapes competitive positioning across synthetic and natural formulation pathways.
- Lidocaine:Amide-type local anaesthetic blocking sodium ion channels at dermal nerve endings. Indian and Chinese API manufacturers dominate bulk production, exposing formulators to input price volatility and supply interruption risks.
- Benzocaine:Ester-type alternative with faster metabolic clearance, favored in Australia's TGA-regulated environments where lidocaine scheduling creates access friction. Pharmacy-grade sourcing networks anchor Centaur Pharmaceuticals' regional position.
- Tetracaine:Potent long-acting ester anaesthetic reserved for extended procedures requiring sustained numbness. Japan's PMDA mandates additional stability testing for tetracaine formulations, elevating documentation burdens for entrants.
- Herbal Extracts:Natural alternatives incorporating clove oil, menthol, or chamomile derivatives. Salons in Indonesia and the Philippines market these to clientele seeking cosmetic-grade positioning without pharmaceutical registration complexity.
Lidocaine dominates absolute formulation volume. Herbal Extracts are climbing the fastest as natural-positioning marketing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical-grade API manufacturers supply lidocaine corridors reaching Australian formulators, compressing lead times for compliant batch production across the region.
India
Urban tattoo parlour density in Mumbai and Bangalore creates concentrated procurement clusters for institutional-size cream containers. TRAI ingredient disclosure mandates professionalize supply chains previously served by grey-market imports. CDSCO registration requirements for high-concentration lidocaine formulations filter informal suppliers from legitimate pharmacy distribution.
Australia
Therapeutic Goods Administration scheduling restrictions classify premium lidocaine creams as restricted medicines, limiting retail accessibility to licensed-practitioner channels. Gel formulation specialists capture premium studio accounts in Sydney and Melbourne through faster onset kinetics. Tattoo artists executing detailed geometric work prioritize residue-minimizing vehicles for extended sessions.
South Korea
MFDS-cleared beauty retail platforms enable cross-border sales of lower-concentration cosmetic-grade formulations to individual consumers. Seoul's youth-oriented beauty districts generate concentrated demand for rapid-onset numbing suitable for walk-in piercing service models. Accelerated stability testing protocols elevate documentation costs for entrants without captive laboratory infrastructure.
Thailand
Medical-aesthetic facilities in Bangkok absorb numbing cream volumes previously routed through informal studio channels, creating premium-grade demand clusters. Cosmetic tattoo clinics for permanent makeup applications elevate formulation standards above traditional body art procurement. Brow bars and lip specialists deploy pre-saturated wipes where cross-contamination protocols are stringent.
Indonesia
Tattoo studio density in secondary cities remains a fraction of Bangkok or Manila levels, offering first-mover positioning for compliant distributors. Herbal extract alternatives marketed by salons capture price-sensitive segments unwilling to navigate pharmaceutical compliance complexity. Jakarta-based procurement officers consolidate vendor relationships around suppliers offering integrated technical support.
Asia-Pacific Tattoo Numbing Cream Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and channel access dimensions. The vendor base clusters around three tiers: pharmaceutical-grade manufacturers with API sourcing networks, gel formulation specialists serving premium studio accounts, and direct-to-consumer brands leveraging e-commerce reach. Strategic archetypes include manufacturing-scale players anchoring supply security, application-technology innovators capturing line-work segments, and brand-recognition specialists penetrating individual buyer channels. Dominant competitive moves encompass backward integration into API procurement and geographic expansion through distributor licensing arrangements.
Among Australia-based pharmaceutical suppliers, Aspen Pharmacare Australia Pty Ltd occupies a position reflecting therapeutic goods manufacturing scale. Centaur Pharmaceuticals Pvt. Ltd. represents the manufacturing-scale archetype with pharmacy-grade sourcing networks. Tattoo Numbing Cream Co. exemplifies gel formulation specialization capturing premium studio accounts. Dr. Numb sits within the brand-recognition tier for individual consumer channels.
| Leading Market Players |
|---|
| Aspen Pharmacare Australia Pty Ltd |
| Centaur Pharmaceuticals Pvt. Ltd. |
| Tattoo Numbing Cream Co. |
| Zensa Skin Care |
| Hera Beauty Ltd. |
| Dr. Numb |
| TattooNumbX |
| Toochi Tattoo |
| Painless Topical Anaesthetic Cream |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory cycles for pharmaceutical-grade lidocaine API concentrate pricing power among Indian and Chinese bulk manufacturers, compressing margin buffers for Australian and Southeast Asian formulators while elevating procurement risk premiums for compliant batch production.
Pricing Analysis
Current-generation gel formulations command per-unit premiums over prior-generation cream vehicles, while next-generation penetration-enhancer combinations remain in pilot pricing. Three-tier pricing structure across premium pharmaceutical-grade, standard cosmetic-grade, and economy herbal-alternative levels separates CDSCO-registered clinic supply from unregistered studio channels. Price differentiation rests on certification tier and after-sales technical support bundling. Cost compression in standard cosmetic-grade segments is intensifying because studio purchasing cooperatives in Mumbai and Bangalore consolidate vendor relationships. Individual consumers through South Korean e-commerce platforms exhibit lowest price sensitivity due to convenience positioning, while Indonesian secondary-city salons remain most price-sensitive.
Supply Chain Analysis
Strategic-stockpile preferences dominate among Australian TGA-registered formulators buffering against API supply interruption, while just-in-time procurement characterizes Indian pharmaceutical manufacturers with direct API sourcing corridors. Bulk lidocaine production concentrates in China and India, with secondary formulation capacity clustering in Australia and South Korea. Raw material dependencies include pharmaceutical-grade API, hydro-alcoholic gel vehicles, and penetration-enhancer compounds. Single-source vulnerability from concentrated Chinese API manufacturers exposes regional formulators to input price volatility. Distribution runs through licensed pharmaceutical distributors for clinic-grade products and direct studio relationships for cosmetic-grade channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tattoo numbing cream adoption across Southeast Asia sits in early-cycle expansion as cosmetic tattoo clinic density in Thailand and Vietnam accelerates premium-grade procurement beyond traditional body art channels.
For Market Incumbents: Compound formulation technology advantages by deepening backward integration into Indian API sourcing networks and accelerating gel-vehicle R&D to defend against herbal-substitute encroachment in price-sensitive Indonesian and Philippine segments. Prioritize CDSCO and TGA certification maintenance as regulatory divergence intensifies compliance thresholds that filter informal competitors. For New Entrants and Emerging Players: Anchor in Indonesia's underpenetrated secondary cities where tattoo studio density remains a fraction of Bangkok or Manila levels, offering first-mover positioning for compliant distributors before incumbent consolidation accelerates. Target cosmetic-grade gel formulations for South Korean MFDS-cleared beauty retail platforms as the most penetrable cross-border channel, leveraging direct-to-consumer e-commerce infrastructure to bypass licensed-distributor barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized pharmaceutical manufacturers with dormant topical anaesthetic portfolios and existing API sourcing relationships but underutilized formulation capacity. Long-term viability hinges on regulatory compliance infrastructure as a durable moat against grey-market competition. Watch studio purchasing cooperative formation rates in Indian urban clusters as inflection indicators for collective bargaining power compression on legacy distributor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Captive lidocaine supply from Indian pharmaceutical-grade manufacturers insulates against Chinese production concentration risk. |
| Gel Format Technology Development | Faster-onset hydro-alcoholic vehicles with engineered viscosity capture premium Australian and South Korean studio accounts. |
| Multi-Jurisdiction Regulatory Registration | Parallel CDSCO, TGA, and MFDS filings enable cross-border sales while squeezing unregistered grey-market operators. |
| Studio Technical Support Integration | Bundled training and after-sales service consolidates vendor relationships against purchasing cooperative pressure. |
| E-Commerce Direct-to-Consumer Channel | MFDS-cleared beauty retail platforms bypass prescription requirements for lower-concentration cosmetic-grade formulations. |
Research Methodology
Cross-validation between primary interviews with tattoo studio procurement officers, cosmetic clinic supply chain managers, and pharmaceutical regulatory consultants anchors the qualitative findings against secondary sources including CDSCO registration databases, TGA therapeutic goods listings, and ASEAN cosmetic directive filings. Bottom-up demand modeling from studio density metrics and top-down market sizing from API production volumes triangulate volume estimates. The analysis combines distributor channel assessments with e-commerce platform transaction pattern analysis across South Korean and Australian retail environments.
Sensitivity analysis around regulatory approval timelines and API price volatility bands tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product format, application type, customer channel, and active ingredient profile alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves against historical penetration rates in comparable topical anaesthetic markets. Forecast inputs incorporate studio formation rates in Indian urban centers and cosmetic tattoo clinic expansion trajectories in Thailand and Vietnam.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in CDSCO or TGA scheduling stringency would warrant model refresh. Forecasts reflect base-case assumptions regarding API supply continuity and clinic-grade demand migration from informal channels. Revision becomes warranted when herbal-substitute market share crosses thresholds that trigger incumbent pricing response.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Global Pain Management Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Heat Therapy Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
OTC Painkiller Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Cluster Headache Market
Pain Management
Pain Management Software Market
Pain Management
Neuropathic Pain Market
Pain Management
Spine Pain Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Central Pain Syndrome Management Market