
 Heat Therapy Market | 2026-2036
Heat Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Therapy Market Analysis
Online direct-to-consumer channels is rewriting how patients access thermal treatment devices, bypassing traditional durable medical equipment distributors. Beurer GmbH leverages its European brand heritage to sustain premium positioning in home-use heating pads. DJO Global anchors hospital and clinic procurement through its rehabilitation equipment portfolio. Medline Industries competes on scale, controlling supply chain logistics that reach acute care facilities across North America.
Heat therapy applies controlled thermal energy, typically ranging from 40°C to 60°C, to superficial or deep tissue through conduction, convection, or infrared radiation to increase blood flow and reduce musculoskeletal stiffness. Heating pads and infrared devices dominate product-level revenue, with infrared segments capturing margin pools due to semiconductor emitter costs and perceived clinical efficacy. Home care end users represent the fastest-growing consumption channel as post-acute patients shift recovery outside institutional settings, while physiotherapy clinics retain stable procedure-linked demand for professional-grade thermal modalities.
FDA 510(k) premarket notification requirements govern electrical heating devices marketed for pain relief in the United States, compelling manufacturers to demonstrate substantial equivalence to predicate devices. EMA medical device regulation and CE marking under the EU MDR framework impose clinical evidence standards that lengthen European market entry timelines. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards apply across all target geographies, creating compliance cost barriers for new entrants. Stakeholders must monitor evolving software-as-a-medical-device classifications as connected heat therapy products integrate temperature sensors and mobile application controls.
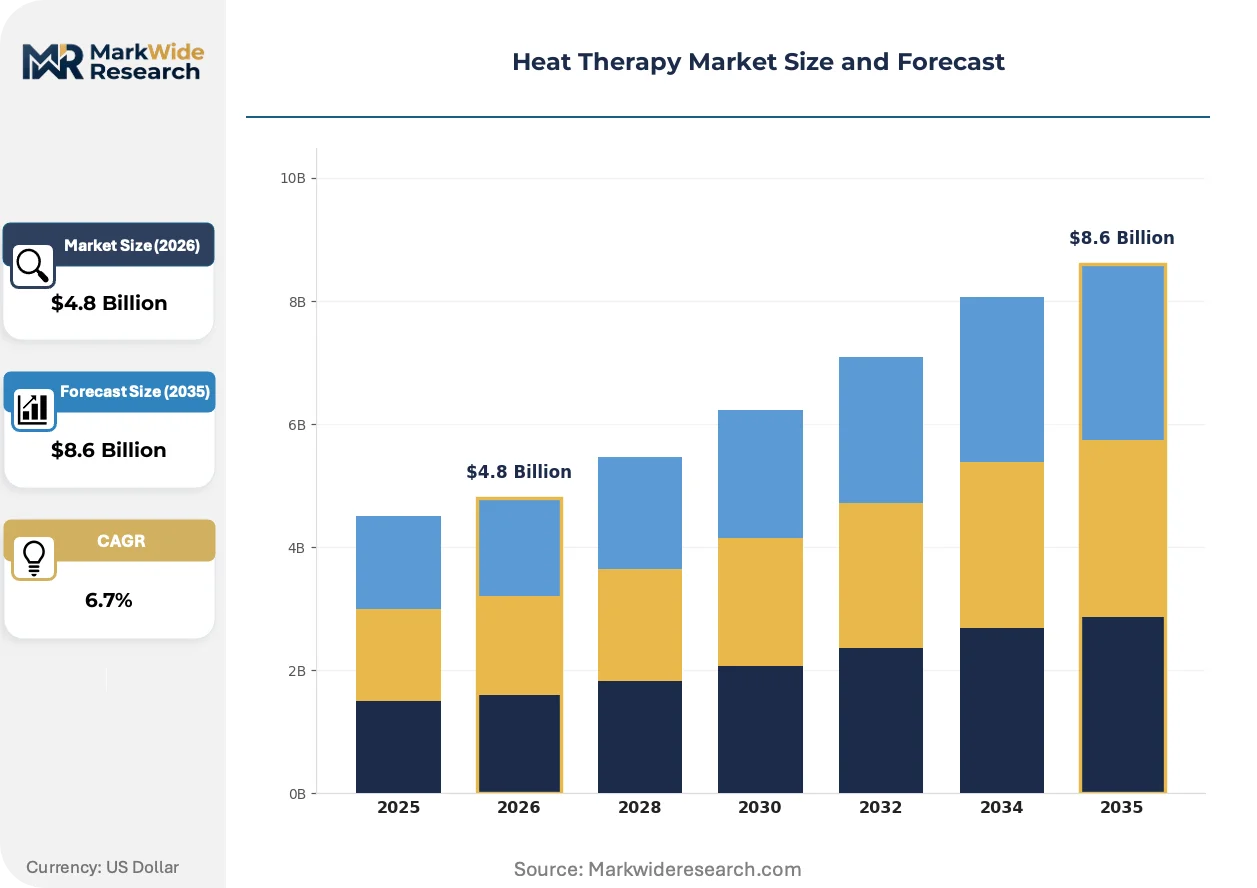
Market Dynamics
Post-acute care decentralization is compressing institutional procurement cycles while amplifying direct-to-consumer demand for portable thermal devices with connected monitoring capabilities.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States exhibit expanding populations over 65 with chronic musculoskeletal conditions requiring home-based pain management solutions.
- FDA 510(k) Pathway Efficiency:Substantial equivalence demonstrations for Class II heating devices accelerate market entry compared to premarket approval requirements for novel therapeutic categories.
- Infrared Emitter Semiconductors:Gallium arsenide and aluminum gallium arsenide diode manufacturing scale economies reduce unit costs for deep-tissue penetration devices.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate infrared emitter chip fabrication, creating single-source vulnerability for device manufacturers.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation mandates post-market surveillance systems that extend certification timelines by 12-18 months.
- Pharmacological Substitution:Topical NSAID formulations and transdermal analgesic patches compete for musculoskeletal pain relief budgets in managed care settings.
Strategic Opportunities
- Software-as-a-Medical-Device Classification:Temperature-sensor-integrated mobile applications create recurring revenue streams through subscription-based treatment protocols.
- Physiotherapy Clinic Chains:Consolidated outpatient rehabilitation networks in Australia and Canada seek standardized thermal modality equipment across multi-site deployments.
- India Home Care Expansion:Urban middle-class households in Mumbai, Delhi, and Bangalore adopt premium heating devices as post-surgical recovery shifts from hospitals to residential settings.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies require specialized laboratory capacity with limited qualified providers in emerging manufacturing regions.
- Legacy System Integration:Connected heat therapy devices must interface with hospital electronic health record systems through HL7 FHIR standards that lack thermal treatment-specific data elements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Therapy Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Pads, Electric Blankets, Heat Wraps, Infrared Devices Application: Pain Relief, Muscle Recovery, Injury Rehabilitation, Stress Relief End User: Hospitals, Physiotherapy Clinics, Home Care, Sports Facilities Technology: Conduction, Convection, Infrared, Magnetic Therapy |
| Companies Covered | Beurer GmbH, BTL International, Zimmer MedizinSysteme GmbH, Medline Industries, Inc., Cardinal Health, Inc., DJO Global, Performance Health Holdings, Inc., Enovis Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Therapy Market Emerging Trajectories
Digital health convergence is redefining thermal treatment from passive commodity hardware to data-generating therapeutic platforms with remote monitoring capabilities.
Far-infrared carbon crystal heating elements are virtualizing traditional resistive wire technology by enabling precise wavelength tuning between 5-15 micrometers for targeted tissue penetration. Physiotherapy clinics in Germany and Japan are retrofitting treatment tables with these emitters to differentiate premium service tiers. The technology is virtualizing capital equipment refresh cycles by extending functional lifespans through software-defined temperature protocols rather than hardware replacement.
REACH substance restrictions on phthalates and heavy metals in electrical device housings are forcing polymer formulation changes across European supply chains. Manufacturers serving EU markets must validate alternative flame-retardant chemistries that maintain IEC 60601-1 electrical safety ratings. Heating pad producers with existing inventory in bonded warehouses face accelerated write-down pressures as MDR technical documentation deadlines approach.
Subscription-based device access models are displacing outright purchase arrangements in North American employer wellness programs. Corporate occupational health departments in Texas, California, and Illinois lease portable infrared units with usage analytics rather than capitalizing durable medical equipment. This shift concentrates procurement authority with benefits administrators who prioritize total cost-per-employee metrics over clinical specification compliance.
Heat Therapy Market Segmentation
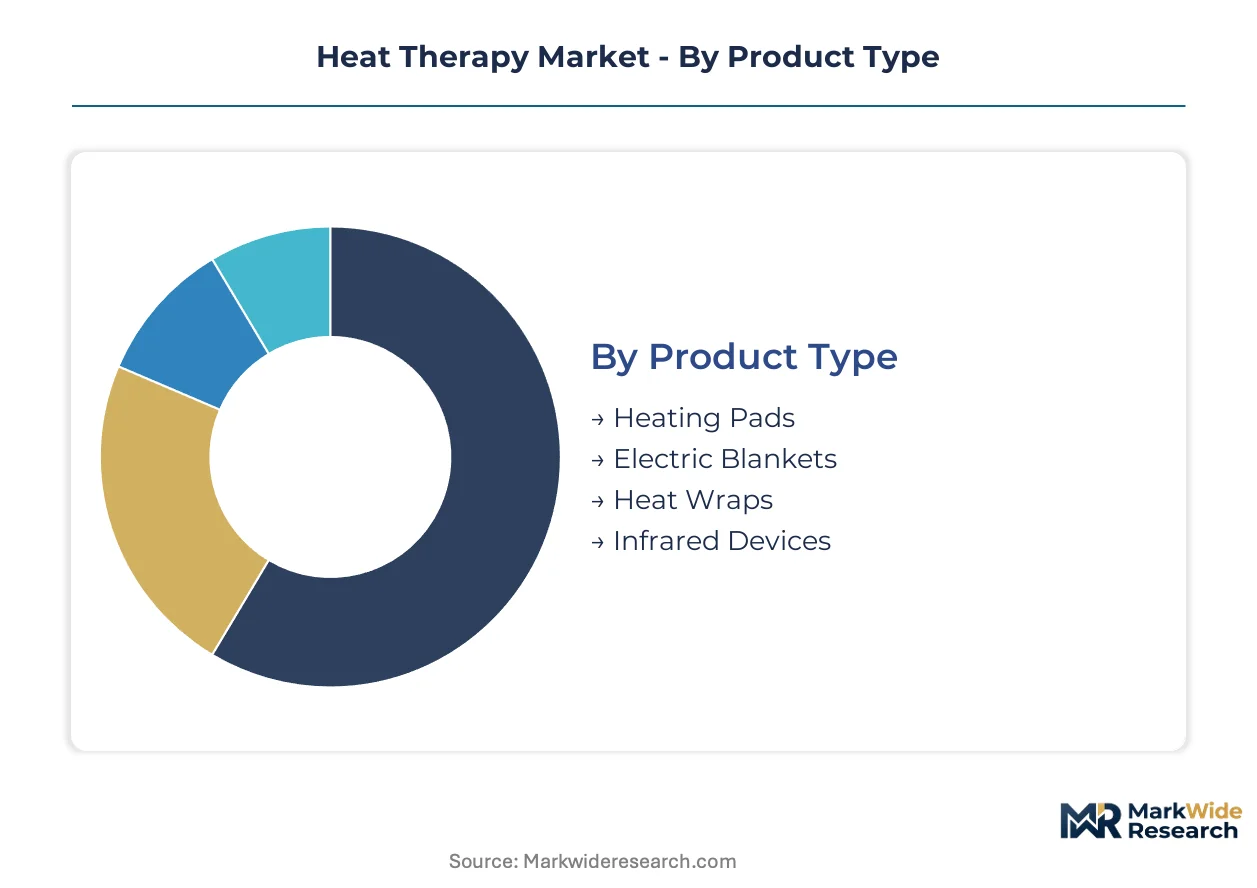
Heat therapy manufacturers segment their portfolios across four distinct dimensions that reflect divergent margin structures and regulatory pathways. Product type and technology choices determine semiconductor content and FDA 510(k) classification complexity, while application and end-user targeting shapes distribution channel economics.
Product Type:
Mature resistive-wire formats coexist with emerging semiconductor-based platforms that command premium positioning through wavelength specificity.
- Heating Pads:Resistive wire or carbon fiber elements embedded in fabric housings deliver surface-level thermal transfer through direct contact. Demand concentrates in United States home care settings where post-acute patients seek Medicare-reimbursable pain management alternatives to pharmacological intervention.
- Infrared Devices:Gallium arsenide and aluminum gallium arsenide diode arrays emit far-infrared wavelengths between 5-15 micrometers for deep tissue penetration. German physiotherapy clinics and Japanese sports medicine facilities prioritize these units for their ability to reach subcutaneous vascular networks without surface burning risk.
- Electric Blankets:Distributed heating elements woven into bedding textiles provide whole-body thermal modulation during sleep cycles. United Kingdom and Scandinavian residential markets sustain demand for energy-efficient models with programmable temperature curves.
- Heat Wraps:Single-use or limited-reuse pouches containing iron powder, salt, and activated carbon generate exothermic reactions upon air exposure. Occupational health programs in Texas and California distribute these as portable alternatives to powered devices for field-based workers.
Heating pads handle the majority of throughput; infrared devices are gaining share fastest on clinical efficacy differentiation.
Application:
Volume concentrates in symptomatic relief categories while rehabilitation protocols drive equipment refresh cycles in institutional procurement.
- Pain Relief:Chronic musculoskeletal conditions in aging populations—particularly lumbar and cervical pathologies—sustain baseline demand across all product formats. Japanese consumers over 65 represent the highest per-capita utilization intensity for home-based thermal intervention.
- Injury Rehabilitation:Post-surgical and post-traumatic recovery protocols specify precise thermal dosing regimens that favor programmable infrared systems. Australian physiotherapy clinic chains standardize on equipment capable of documenting treatment parameters for insurer reimbursement.
- Muscle Recovery:Athletic performance optimization drives adoption of rapid-heating modalities among professional and amateur sports programs. Canadian hockey and ski training facilities integrate heat therapy into pre-competition warm-up routines.
- Stress Relief:Wellness-oriented consumption in urban middle-class households supports premium positioning of aesthetic-focused devices. Mumbai and Bangalore residential markets show expanding uptake of infrared sauna blankets as sleep quality interventions.
Pain relief commands the installed base; injury rehabilitation shows the steepest expansion trajectory on post-acute care decentralization.
End User:
Procurement authority splits between clinical specification committees and individual consumer decision-making with divergent price sensitivity profiles.
- Home Care:Individual purchasers selecting devices through direct-to-consumer channels or durable medical equipment suppliers. United States Medicare Advantage plans increasingly authorize heating pad reimbursement for chronic low back pain, expanding addressable household penetration.
- Physiotherapy Clinics:Outpatient rehabilitation networks requiring multi-modality equipment with documented clinical outcomes. Consolidated chains in Canada and Australia negotiate volume pricing for standardized thermal modality platforms.
- Hospitals:Acute care facilities integrating heat therapy into orthopedic and pain management service lines. Medline Industries and similar distributors control procurement relationships through bundled supply agreements covering multiple therapeutic categories.
- Sports Facilities:Professional team training centers and collegiate athletic departments prioritizing rapid-recovery protocols. German Bundesliga football clubs and Japanese J-League organizations specify infrared devices with sub-60-second heat-up intervals.
Home care channels process the highest unit volumes; physiotherapy clinics drive the fastest technology upgrade cycles.
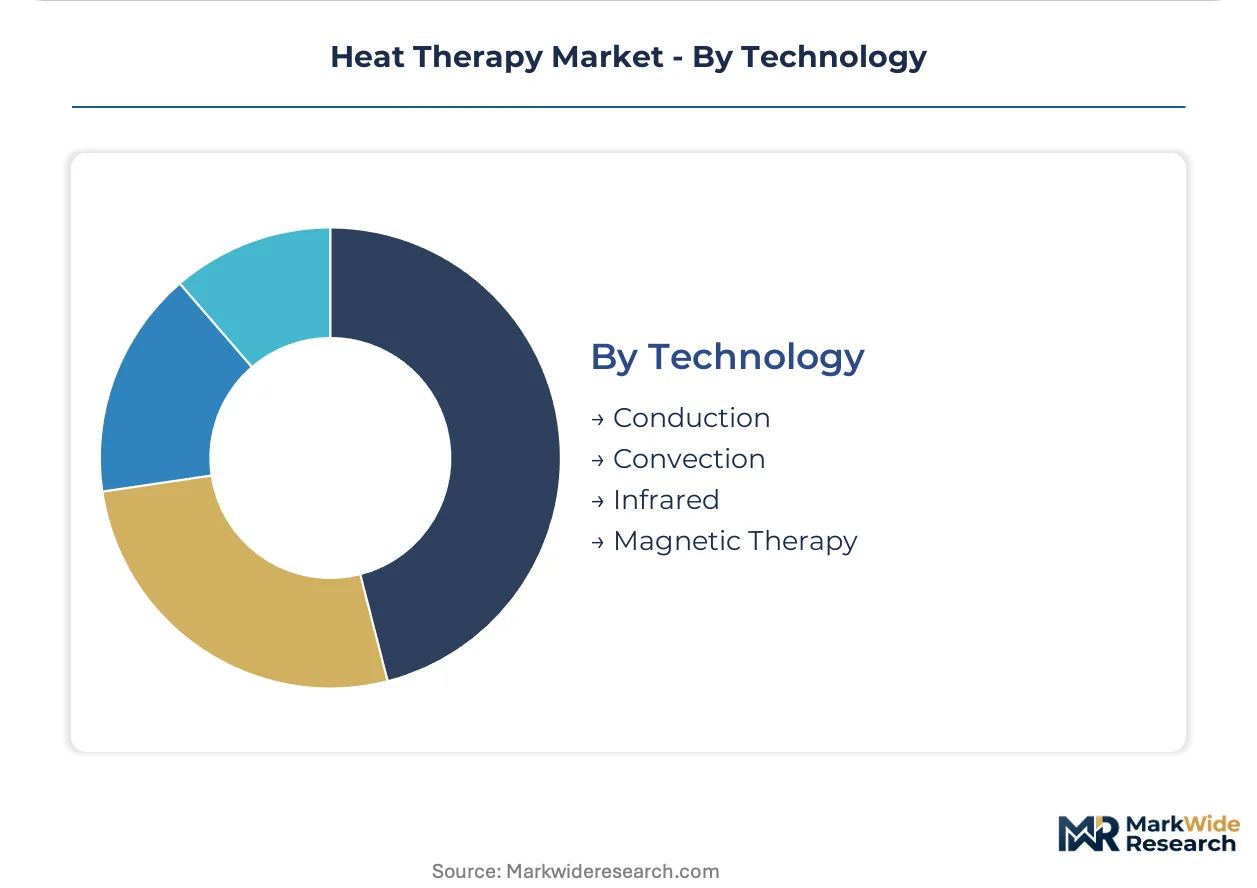
Technology:
Physical heat transfer mechanisms compete with electromagnetic modalities on regulatory classification and reimbursement eligibility.
- Conduction:Direct surface-to-surface thermal transfer through resistive elements in contact with skin. Mature manufacturing ecosystems in China and Mexico support cost-optimized production for price-sensitive retail segments.
- Infrared:Electromagnetic radiation in the 700 nanometer to 1 millimeter wavelength range penetrates tissue without heating intervening air. FDA 510(k) clearance for infrared pain relief devices requires substantial equivalence demonstrations that favor established predicate portfolios.
- Convection:Forced-air or fluid-circulation systems that distribute heat through intermediate media. Paraffin bath units in United States hand therapy clinics represent the primary surviving convection application.
- Magnetic Therapy:Pulsed electromagnetic field generation claimed to enhance circulation and reduce inflammation. Regulatory positioning varies by jurisdiction—EMA recognizes certain applications while FDA classification remains contested.
Conduction platforms retain the largest installed base; infrared technology climbs fastest on semiconductor cost reduction and clinical evidence accumulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution for thermal device components, while Germany's Rhine-Main corridor channels European procurement through Frankfurt's logistics hub. Japan's Kansai International Airport freight terminals handle semiconductor emitter imports for domestic manufacturing.
United States
Medicare Advantage expansion in Florida and Arizona drives home-care device procurement for aging retirees with chronic lumbar conditions. FDA 510(k) premarket notification requirements govern electrical heating devices, compelling manufacturers to demonstrate substantial equivalence to predicate devices. The Dallas-Fort Worth metroplex concentrates durable medical equipment distribution centers serving the Southwest.
Germany
Physiotherapy clinic chains in Bavaria and Baden-Württemberg standardize on infrared equipment for post-surgical rehabilitation protocols. EU MDR clinical evidence standards and CE marking requirements extend certification timelines for new market entrants. The Rhine-Ruhr industrial corridor hosts polymer formulation facilities adapting to REACH substance restrictions on phthalates.
Japan
Consumers over 65 in Tokyo and Osaka exhibit the highest per-capita utilization intensity for home-based thermal intervention. PMDA medical device regulations align with international standards while maintaining additional quality management system requirements. The Chubu region around Nagoya houses precision electronics manufacturers supplying infrared emitter components.
India
Urban middle-class households in Mumbai, Delhi, and Bangalore adopt premium heating devices as post-surgical recovery shifts from hospitals to residential settings. CDSCO medical device rules impose import licensing requirements that filter distributor networks. The Delhi-NCR cluster attracts rehabilitation equipment suppliers targeting northern India's expanding home care market.
Australia
Consolidated outpatient rehabilitation networks in Sydney and Melbourne seek standardized thermal modality equipment across multi-site deployments. TGA medical device regulations require Australian Register of Therapeutic Goods inclusion before commercial distribution. The Victorian manufacturing corridor near Melbourne hosts contract assemblers serving Asia-Pacific markets.
Heat Therapy Market Vendor Landscape
On the supply side, the industry is structured around three distinct tiers: multinational medical device conglomerates with diversified rehabilitation portfolios, specialized thermal therapy manufacturers with concentrated product lines, and regional fabricators serving price-sensitive retail segments. Strategic archetypes include FDA 510(k) clearance specialists leveraging predicate device libraries, semiconductor-integrated platform developers capturing margin through wavelength specificity, and scale-driven distributors controlling hospital procurement channels. Dominant competitive moves encompass backward integration into infrared emitter manufacturing and geographic expansion through physiotherapy clinic chain partnerships.
Among German-origin specialists, Beurer GmbH and Zimmer MedizinSysteme GmbH occupy positions within the premium home-use and clinical equipment tiers respectively. DJO Global anchors the institutional procurement segment through its rehabilitation equipment portfolio. Medline Industries, Inc. exemplifies the scale-driven distributor archetype, leveraging supply chain logistics that reach acute care facilities across North America.
| Leading Market Players |
|---|
| Beurer GmbH |
| BTL International |
| Zimmer MedizinSysteme GmbH |
| Medline Industries, Inc. |
| Cardinal Health, Inc. |
| DJO Global |
| Performance Health Holdings, Inc. |
| Enovis Corporation |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Taiwanese semiconductor foundry concentration for gallium arsenide infrared emitters creates single-source vulnerability that compresses margin pools at the premium tier while forcing mid-market manufacturers toward carbon-fiber conduction alternatives. This chokepoint simultaneously widens pricing spreads between FDA-cleared infrared systems and uncertified heating pads while reshaping procurement strategies across German physiotherapy networks and United States home care channels.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from direct-to-consumer retail pricing. Three-tier pricing stratifies across premium infrared systems with PMDA alignment, standard FDA 510(k) cleared devices, and economy-grade resistive wire pads without biocompatibility certification. Price differentiation hinges on semiconductor content and regulatory tier, with infrared emitters driving 40-60% BOM cost concentration. Pricing pressure stems from gallium arsenide wafer allocation constraints that favor automotive LiDAR demand. Hospital purchasing committees exhibit lowest price sensitivity due to bundled reimbursement protocols; individual Medicare Advantage subscribers in Florida and Arizona show highest elasticity.
Supply Chain Analysis
Supplier-financing facilities from Taiwan Semiconductor Manufacturing Company and South Korean diode fabricators extend 90-120 day payment terms to tier-one device manufacturers, compressing working capital cycles for mid-tier assemblers. Geographic supply concentration centers on Taiwan for gallium arsenide wafers, South Korea for aluminum gallium arsenide epitaxy, and Japan for precision optical packaging. Raw material dependencies include rare-earth phosphors, medical-grade silicone housings, and flame-retardant polymer formulations compliant with REACH restrictions. Single-source vulnerability in emitter chip fabrication dominates supply chain risk profiles. Distribution runs through Medline Industries and Cardinal Health for North American acute care; direct-to-consumer channels bypass traditional durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-acute care decentralization signals a cyclical recovery phase as hospital capacity constraints permanently shift rehabilitation volume toward outpatient and residential settings. This structural demand migration favors manufacturers with home-use certification portfolios and connected monitoring capabilities.
For Market Incumbents: Build predicate device libraries as a regulatory moat by filing FDA 510(k) substantial equivalence claims across wavelength-specific infrared platforms before EU MDR clinical evidence requirements harden. Defensive consolidation should prioritize backward integration into gallium arsenide packaging to escape Taiwan foundry allocation constraints. Capacity addition in Mexico and Poland addresses tariff exposure on Chinese-assembled heating pads while shortening lead times to United States and German procurement channels.
For New Entrants and Emerging Players: Mid-market physiotherapy clinic chains in Australia and Canada represent the most penetrable entry point, as these consolidated networks seek standardized thermal modality equipment without legacy supplier entrenchment. India's urban home care expansion in Mumbai and Bangalore offers secondary white-space as post-surgical recovery shifts from hospitals to residential settings. Go-to-market positioning should emphasize software-as-a-medical-device temperature protocols with subscription-based treatment documentation for insurer reimbursement eligibility.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors semiconductor-integrated platform developers over legacy resistive-wire manufacturers. Long-term viability across a 5-10 year window rests on wavelength-specific clinical evidence accumulation and connected health data monetization. Acquisition target archetypes include infrared emitter packaging specialists with ISO 13485 quality systems and physiotherapy clinic chain equipment lessors with recurring revenue streams. The signal to watch is FDA guidance on software-as-a-medical-device classifications for temperature-sensor-integrated mobile applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Infrared Emitter Manufacturing | Captive gallium arsenide supply secures allocation priority against automotive LiDAR demand from Taiwan foundries. |
| Software-as-a-Medical-Device FDA Submission | Temperature-sensor mobile applications unlock subscription revenue through documented treatment protocols for Medicare Advantage plans. |
| Physiotherapy Clinic Chain Partnership | Standardized equipment deployments across Australian and Canadian consolidated networks reduce customer acquisition costs. |
| EU MDR Technical Documentation Investment | CE marking pathway extension through clinical evidence preparation defends German and Scandinavian market access. |
| Direct-to-Consumer Channel Expansion | Online sales bypass durable medical equipment distributor margins while capturing Medicare Advantage reimbursement authorization. |
Methodological Framework
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and physiotherapy clinic procurement leads anchors the qualitative findings against secondary validation from FDA 510(k) premarket notification databases, EMA medical device registration filings, CMS Medicare reimbursement schedules, and ISO 13485 quality system audit records. Bottom-up triangulation aggregates unit shipment estimates by product type and technology; top-down calibration cross-checks against reported revenue ranges from SEC 10-K disclosures and trade association membership surveys.
Calibration against historical growth patterns and semiconductor cost curves refines the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology mechanism, application indication, end-user channel, and regional regulatory cluster. CAGRs derive from least-squares fitting of normalized growth trajectories, with infrared device adoption curves and home care channel penetration rates serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, gallium arsenide wafer pricing, or EU MDR enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about predicate device availability and semiconductor allocation priorities; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chronic Pain Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Postoperative Pain Market
Pain Management
Pain Relief Oil Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Ketorolac Market
Pain Management
Global Morphine Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Spine Pain Market
Pain Management
Cold Pain Therapy Market
Pain Management
Migraine Management Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Over-The-Counter Pain Medication Market