
 Migraine Management Market | 2026-2036
Migraine Management Market Size, Share, and Industry Trends Forecast 2026-2036
Migraine Management Market Analytics
Acute treatment revenue is fragmenting as payers shift reimbursement toward preventive protocols. Amgen leverages its CGRP receptor antagonist portfolio to anchor recurring prescription volumes. Eli Lilly and Company differentiates through dual-label positioning across both acute and preventive therapy segments.
Migraine management encompasses pharmacological and non-pharmacological interventions targeting the trigeminovascular system, with CGRP pathway modulation representing the dominant mechanistic class in contemporary drug development. The field serves commercial and clinical purposes by reducing attack frequency, severity, and associated disability burden. Prescription medications command the dominant margin pool, while devices represent the fastest-expanding category as neuromodulation technology achieves broader payer acceptance. Preventive therapy is displacing acute-only regimens in neurologist prescribing patterns, though over-the-counter pain relievers sustain volume in primary care gatekeeping roles.
FDA, EMA, and WHO standards govern clinical trial endpoints, bioequivalence requirements, and headache disorder classification frameworks that shape product development priorities and market access pathways. The FDA's Breakthrough Therapy designation for novel migraine mechanisms accelerates development timelines and influences investor allocation toward CGRP-targeted platforms. Stakeholders must monitor evolving prior authorization criteria from large commercial payers and Medicare Advantage plans, as these policies increasingly determine which therapy areas achieve profitable patient access.
Market Dynamics
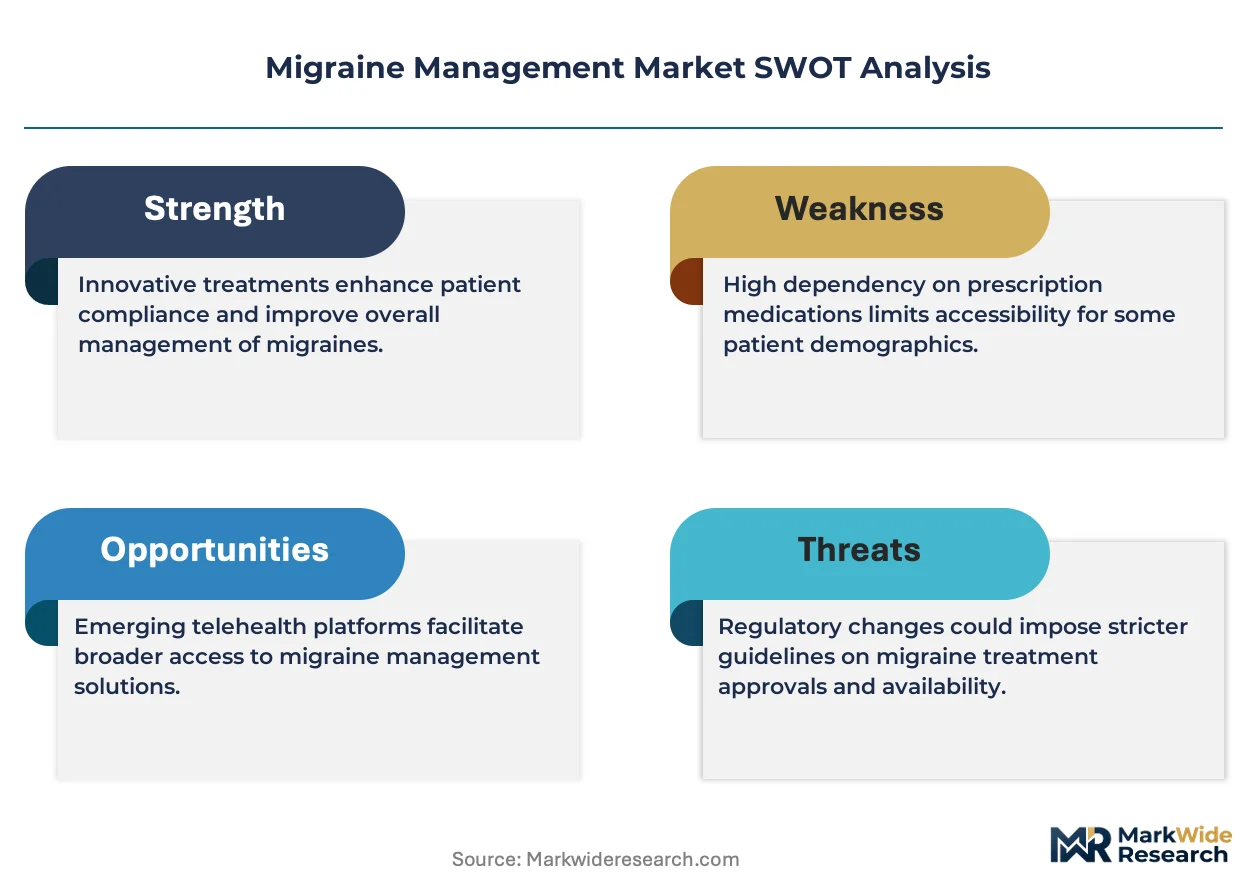
The FDA's Breakthrough Therapy designation for CGRP-targeted mechanisms is compressing development timelines and redirecting R&D investment toward preventive protocols, fundamentally altering how neurologists sequence acute versus prophylactic therapy.
Growth Catalysts
- EMA centralized assessment pathways:The European Medicines Agency's streamlined evaluation for biologics is accelerating cross-border market access for novel migraine therapeutics across EU member states.
- Neuromodulation device reimbursement:Medicare Advantage plans and large commercial payers are establishing dedicated prior authorization tracks for non-invasive vagus nerve stimulation devices.
- Specialty pharmacy networks:United States-based specialty distributors are building cold-chain infrastructure that supports patient adherence programs for injectable CGRP inhibitors.
Market Restraints
- Monoclonal antibody manufacturing concentration:Contract manufacturing organizations in Ireland and Switzerland control critical bioreactor capacity for CGRP inhibitor production, creating single-source vulnerability.
- Prior authorization friction:United States commercial payers require step-therapy documentation that delays preventive therapy initiation by 60-90 days in many plans.
- Acute therapy generic substitution:Sumatriptan and other triptan formulations face aggressive pharmacy-level substitution that erodes branded acute therapy margins.
Strategic Opportunities
- Japan's aging demographic:METI reimbursement reforms for chronic disease management are opening preventive therapy access for migraine patients over 65.
- Digital therapeutics integration:Smartphone-based headache diary applications linked to electronic health records are creating new prescription trigger points for neurologists.
- India's CDSCO fast-track:The Central Drugs Standard Control Organization's accelerated approval pathway for orphan indications is enabling earlier entry for novel mechanisms.
Industry Challenges
- Headache specialist workforce scarcity:United States neurology residency programs produce insufficient fellowship-trained headache medicine physicians to meet rising preventive therapy demand.
- Real-world evidence collection:Payer-mandated patient-reported outcome tracking requires investment in registry infrastructure that strains mid-cap developer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Migraine Management Market |
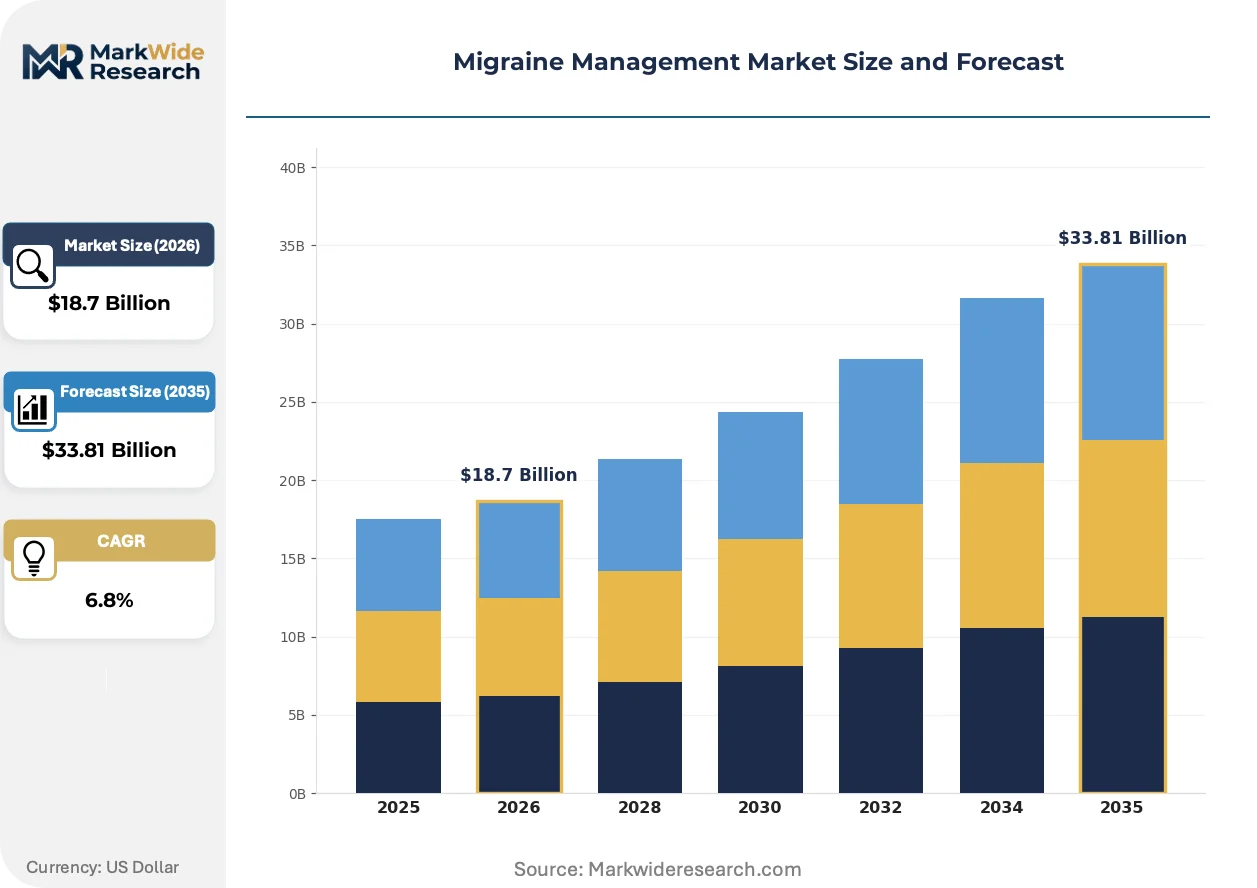
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Pain Relievers, Preventive Medications, Devices Therapy Area: Acute Treatment, Preventive Therapy, Behavioral Therapy, Complementary Therapies Patient Demographics: Adults, Adolescents, Seniors, Pediatric Care Setting: Home Care, Neurology Clinics, Hospitals, Telemedicine Services |
| Companies Covered | Amgen, Eli Lilly and Company, AbbVie, Teva Pharmaceutical, Novartis AG, Pfizer Inc., AstraZeneca, Johnson and Johnson, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Migraine Management Market Evolving Landscape
Digital biomarker platforms and at-home injection devices are collapsing the traditional clinic-visit model for migraine monitoring, while regulatory frameworks race to accommodate patient-generated data in approval dossiers.
Remote electrical neuromodulation wearable devices are rendering obsolete the requirement for in-office transcranial magnetic stimulation sessions. United States-based neurology practices are prescribing these devices for home use within 30 days of initial consultation. The technology is rendering obsolete the historical revenue model tied to procedure-based reimbursement in headache centers.
The FDA's updated guidance on patient-reported outcome instruments now mandates electronic diary compatibility for new drug applications in headache disorders. This policy shift forces developers to integrate validated digital endpoints into phase III trial designs. Small-cap biotech firms without digital infrastructure partnerships face accelerated compliance costs.
Employer-sponsored health plans are unbundling migraine management from general pharmacy benefits and carving out dedicated specialty budgets with outcomes guarantees. Third-party administrators in the United States are contracting directly with CGRP inhibitor manufacturers for risk-based pricing arrangements. This procurement evolution concentrates purchasing power among large self-insured employers and their pharmacy benefit managers.
Migraine Management Market Segmentation
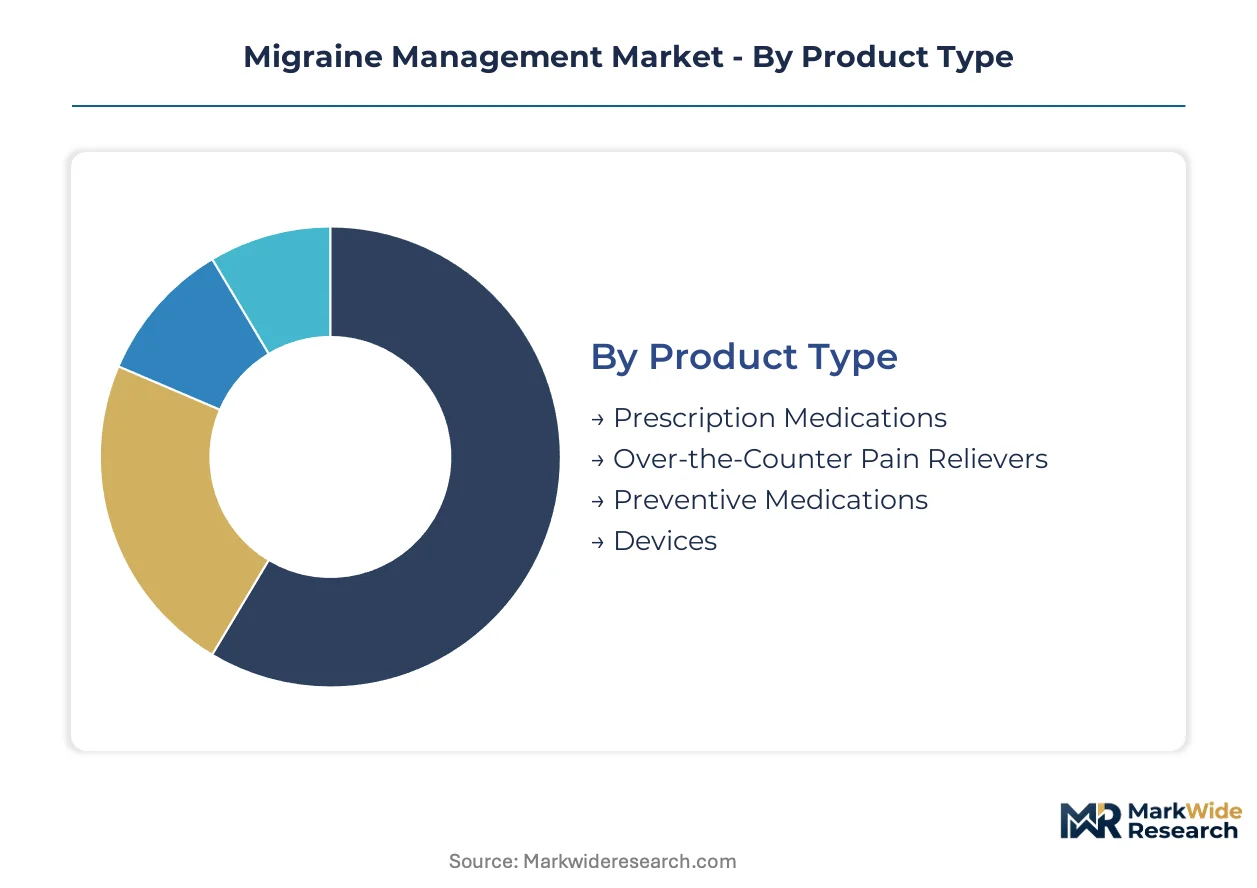
Migraine management segmentation reveals divergent margin profiles across therapeutic modalities. Product type stratification determines reimbursement complexity, while care setting distribution shapes patient adherence outcomes and manufacturer channel strategy.
Product Type:
After-sales service intensity varies sharply across product categories, with device manufacturers bearing ongoing calibration and replacement obligations that pharmaceutical suppliers avoid entirely.
- Prescription Medications:Oral and injectable formulations targeting serotonin receptors or CGRP pathways dominate neurologist prescribing. United States specialty pharmacies manage cold-chain distribution and patient onboarding, with manufacturer investment in nurse educator networks driving adherence rates.
- Devices:Transcranial magnetic stimulation units and vagus nerve stimulators require technical support infrastructure for home deployment. Medicare Advantage carve-out contracts increasingly bundle device procurement with outcomes monitoring, elevating service delivery to core competitive differentiation.
- Preventive Medications:Monthly or quarterly injectable biologics reduce attack frequency in chronic migraine populations. Prior authorization requirements from United States commercial payers create 60-90 day initiation delays that manufacturers address through hub services.
- Over-the-Counter Pain Relievers:Triptan generics and combination analgesics serve primary care gatekeeping roles with minimal clinical oversight. Pharmacy-level substitution erodes branded positioning, constraining manufacturer investment in patient support programs.
By volume, Over-the-Counter Pain Relievers leads. By growth pace, Devices is gaining share fastest.
Therapy Area:
Cost tier stratification separates acute rescue interventions from prophylactic regimens, with preventive protocols commanding premium pricing despite longer payback horizons.
- Preventive Therapy:Scheduled pharmacological or device-based protocols reduce monthly migraine days in chronic sufferers. United States headache centers prioritize these regimens as payers shift reimbursement toward disability reduction metrics.
- Acute Treatment:Rescue medications administered during attack onset include triptans, gepants, and ditans with varying cardiovascular contraindications. Generic sumatriptan penetration constrains branded pricing power in this mature segment.
- Behavioral Therapy:Cognitive behavioral interventions and biofeedback training address medication overuse and stress triggers. Digital therapeutic platforms are achieving Category III CPT codes that enable standalone reimbursement.
- Complementary Therapies:Acupuncture, nutraceuticals, and mindfulness practices occupy regulatory gray zones with limited payer coverage. Out-of-pocket payment dominates, constraining scalable business model development.
Preventive Therapy captures the highest per-patient annual revenue. Behavioral Therapy is expanding most quickly as digital delivery reduces cost per session.
Patient Demographics:
Application requirements diverge across age cohorts, with pediatric indications demanding specialized trial designs and geriatric populations presenting polypharmacy complications.
- Adults:Working-age patients aged 18-64 drive commercial insurance reimbursement and employer-sponsored program design. Disability burden measurement shapes prior authorization evidence requirements for this cohort.
- Seniors:Patients over 65 present cardiovascular comorbidities that contraindicate triptan use and elevate CGRP inhibitor relevance. Medicare Part D coverage gaps and step-therapy requirements create distinct access barriers.
- Adolescents:FDA pediatric exclusivity incentives have accelerated label expansion trials for CGRP-targeted mechanisms in 12-17 year populations. School-based disability assessment differs from occupational metrics used in adults.
- Pediatric:Patients under 12 represent the most underserved segment with limited approved pharmacological options. Off-label prescribing dominates, constraining manufacturer commercial investment.
Adults generates the largest absolute prescription volume. Seniors is climbing the fastest as METI reimbursement reforms in Japan and Medicare Advantage expansion in the United States broaden access.
Care Setting:
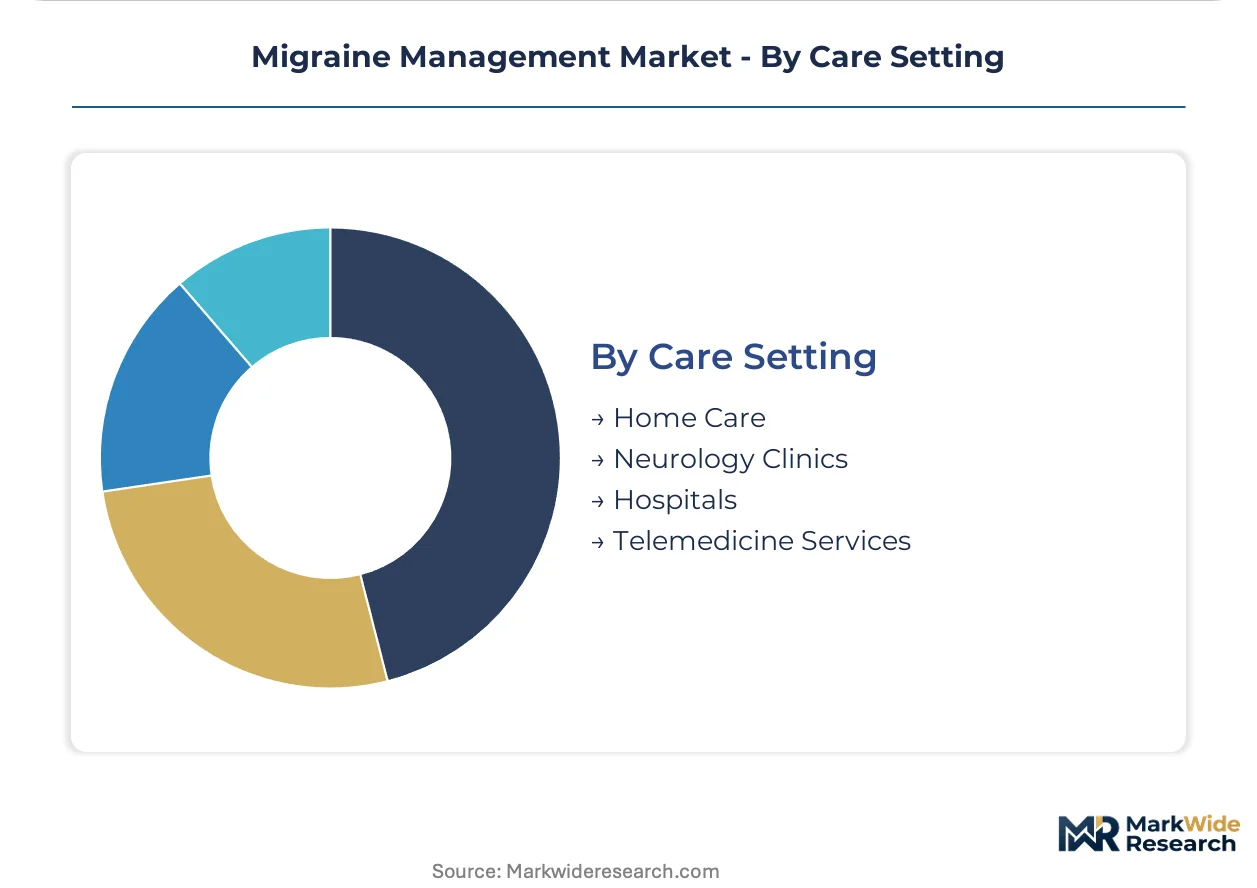
Customer type fragmentation—self-directed patients versus supervised clinical administration—determines product form factor and regulatory pathway selection.
- Neurology Clinics:Fellowship-trained headache specialists coordinate complex polypharmacy and device titration. United States metropolitan markets concentrate these practices, creating geographic access disparities.
- Home Care:Self-administered injectables and wearable neuromodulation devices enable treatment without clinical visits. FDA guidance on patient-reported outcome instruments now mandates electronic diary compatibility for home-use approvals.
- Telemedicine Services:Virtual consultations expand specialist access in neurologist-scarce regions. State-level licensure restrictions and prescribing regulations for controlled substances create operational complexity.
- Hospitals:Emergency department rescue therapy and inpatient detoxification for medication overuse headache occur in this setting. Cost containment pressures favor generic acute therapies over branded alternatives.
Neurology Clinics currently anchors specialist-prescribed volume. Telemedicine Services shows the steepest expansion trajectory as licensure compacts and digital therapeutic integration mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as specialty pharmacy networks and employer carve-outs sustain premium reimbursement, while emerging markets in Asia-Pacific exhibit higher sensitivity where out-of-pocket payment dominates and generic triptans capture volume.
United States
Specialty care networks and Medicare Advantage expansion drive preventive therapy demand among chronic migraine populations. FDA Breakthrough Therapy designations for CGRP-targeted mechanisms compress development timelines and accelerate patient access. The Greater Boston corridor anchors headache medicine fellowship programs that feed specialist workforce into metropolitan neurology clinics.
Germany
EMA centralized assessment pathways enable streamlined biologics approval that accelerates cross-border market access for novel therapeutics. The country's statutory health insurance funds mandate real-world evidence collection for high-cost preventive medications, shaping manufacturer registry investments. North Rhine-Westphalia concentrates contract research organizations supporting phase III headache disorder trials.
Japan
METI reimbursement reforms for chronic disease management expand preventive therapy access for migraine patients over 65, reducing acute rescue dependency. PMDA alignment with FDA endpoints accelerates label expansion for CGRP inhibitors in working-age populations. The Kanto region around Tokyo hosts the highest density of neurology practices prescribing home-use neuromodulation devices.
India
CDSCO fast-track approval pathways for orphan indications enable earlier market entry for novel mechanisms targeting treatment-resistant populations. Out-of-pocket payment constraints sustain generic triptan dominance in primary care gatekeeping roles. Maharashtra's pharmaceutical manufacturing clusters supply active pharmaceutical ingredients for acute therapy formulations across South Asia.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that delay CGRP inhibitor formulary inclusion until post-launch price negotiations conclude. NHS England's migraine pathway redesign prioritizes preventive protocols in specialist referral criteria. London's academic medical centers generate real-world evidence publications that influence EMA regulatory guidance on patient-reported outcome instruments.
Migraine Management Market Competitive Landscape
Capability concentration sits with biologics specialists commanding CGRP pathway expertise; scale advantage sits with diversified pharmaceutical conglomerates with established neurology sales infrastructure. The market structure tiered between monoclonal antibody developers, small-molecule acute therapy manufacturers, and neuromodulation device innovators. Three archetypes dominate: CGRP-targeted platform specialists, dual-label acute-preventive portfolio builders, and wearable technology integrators. Competitive moves center on risk-based pricing arrangements with pharmacy benefit managers and backward integration into patient adherence platform development.
Within the biologics-specialist tier, Amgen exemplifies CGRP receptor antagonist platform concentration, while Eli Lilly and Company occupies a position spanning both acute and preventive label positioning. AbbVie anchors the diversified pharmaceutical archetype with neurology franchise breadth. These three represent the competitive anchors against which mid-cap developers and device innovators define differentiation strategies.
| Leading Market Players |
|---|
| Amgen |
| Eli Lilly and Company |
| AbbVie |
| Teva Pharmaceutical |
| Novartis AG |
| Pfizer Inc. |
| AstraZeneca |
| Johnson and Johnson |
| Merck & Co. |
| Others |
Value Network & Pricing Analysis
Bioreactor capacity concentration in Ireland and Switzerland directly determines margin capture for injectable CGRP inhibitors, with contract manufacturing organizations commanding premium tolling rates that pharmaceutical developers pass through to United States specialty pharmacy networks.
Pricing Analysis
After-sales service contracts for neuromodulation devices generate recurring revenue streams that offset upfront hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates branded biologics from authorized generics and compounded alternatives. Cost compression in acute therapy tiers intensifies because pharmacy-level substitution erodes branded triptan positioning. Employer-sponsored plans exhibit lowest price sensitivity; cash-pay patients in primary care gatekeeping roles face highest out-of-pocket exposure.
Supply Chain Analysis
Extended payment terms from United States specialty pharmacy distributors are compressing working capital cycles for device manufacturers. Active pharmaceutical ingredient production draws from India, China, and Italy; biologic drug substance manufacturing rests on Ireland, Switzerland, and Singapore. Single-source vulnerability in monoclonal antibody fill-finish capacity creates exposure to regulatory inspection delays. Distribution runs through cold-chain specialty pharmacy networks with hub-and-spoke patient adherence infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The migraine management market rewards entities controlling headache medicine specialist networks and CGRP pathway manufacturing expertise, with workforce scarcity in fellowship-trained physicians constraining preventive therapy expansion.
For Market Incumbents: Harden hub services infrastructure against prior authorization friction by embedding nurse educators within United States specialty pharmacy networks. Deepen backward integration into patient adherence platform development to capture outcomes data that satisfies payer evidence requirements. Lock in bioreactor capacity through multi-year manufacturing agreements with Irish and Swiss contract organizations before competitor contracting cycles renew. For New Entrants and Emerging Players: India's CDSCO fast-track pathway for orphan indications offers the most penetrable regulatory entry point for novel mechanisms targeting treatment-resistant populations. Japan's aging demographic and METI reimbursement reforms create white-space access for preventive therapies in patients over 65. Deploy digital therapeutic platforms with electronic health record integration as the primary go-to-market angle to bypass specialist workforce scarcity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed neuromodulation device manufacturers lacking pharmaceutical reimbursement expertise. Long-term viability hinges on portfolio breadth spanning acute and preventive label positioning rather than single-mechanism concentration. Monitor FDA Breakthrough Therapy designation velocity as the inflection indicator for CGRP-targeted platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Prior authorization hub services determine patient access velocity for CGRP inhibitors in Medicare Advantage plans. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Ireland and Switzerland reduces single-source dependency for monoclonal antibody supply. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses development timelines for novel migraine mechanisms. |
| Platform Integration | Electronic health record-linked headache diary applications create prescription trigger points for neurologists. |
| Strategic Partnership | Risk-based pricing arrangements with United States pharmacy benefit managers concentrate purchasing power. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with headache medicine specialists, specialty pharmacy distribution executives, payer formulary directors, and CGRP inhibitor manufacturing leads. Secondary validation drew from FDA approval dossiers, EMA centralized assessment records, ClinicalTrials.gov migraine protocol registrations, and United States Medicare Part D utilization databases. Bottom-up patient population sizing and top-down pharmaceutical revenue triangulation were cross-referenced for segmentation coherence.
Calibration against historical CGRP inhibitor launch trajectories and neuromodulation device adoption curves anchored the analytical framework across the analysis window. Segmentation dimensions modeled included therapy area, product type, patient demographic cohort, and care setting. CAGRs were derived from trend extrapolation moderated by regulatory event probability and payer policy shift scenarios. Forecast inputs incorporated prior authorization delay distributions and specialty pharmacy network expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital therapeutic platforms or employer direct-contracting consortia would shift outcomes beyond modeled ranges. Forecasts reflect assumptions about FDA guidance stability and EMA centralized pathway continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Global Pain Management Market
Pain Management
Bone Pain Treatment Market
Pain Management
Pain Management Devices Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Ketorolac Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Palliative Care Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Cancer Pain Management Market
Pain Management
Arthralgia Management Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market