
 Chinese Fibromyalgia Market | 2026-2036
Chinese Fibromyalgia Market Size, Share, and Industry Trends Forecast 2026-2036
Chinese Fibromyalgia Market Analysis
Hospital procurement departments are redrawing therapeutic formularies for chronic pain management. Pfizer leverages its established neurology franchise to sustain institutional contracts across major Chinese medical centers. Eli Lilly and Company anchors its position through differentiated serotonin-norepinephrine reuptake inhibitor positioning in hospital formularies. Jiangsu Hengrui Medicine competes on domestic manufacturing scale and volume-based procurement compliance.
Fibromyalgia constitutes a chronic central sensitization syndrome characterized by widespread musculoskeletal pain, fatigue, and cognitive disturbance, with diagnosis relying on the Widespread Pain Index and Symptom Severity Scale per modified ACR criteria. Pharmaceuticals dominates current revenue pools due to chronic prescription requirements for pain modulators and antidepressant classes. Injectable delivery modes represent the fastest-expanding segment as biologic and novel peptide therapies advance through China's clinical pipeline. Retail patients account for the largest customer volume, though hospital clinics capture higher per-patient procedural and diagnostic spend.
NMPA's Center for Drug Evaluation maintains stringent pharmacovigilance requirements for chronic pain therapies entering the Chinese market. The National Healthcare Security Administration's volume-based procurement protocols directly compress reimbursement pricing for approved fibromyalgia medications. China's Good Manufacturing Practice standards enforced by the NMPA dictate quality benchmarks for both imported and domestically produced active pharmaceutical ingredients. Stakeholders must monitor NMPA innovation-track approvals and provincial centralized procurement tender calendars to anticipate access and pricing inflections.
Market Dynamics
China's centralized volume-based procurement reforms are compressing pricing power while accelerating hospital formulary access for fibromyalgia therapies, fundamentally restructuring how manufacturers compete on cost and compliance.
Growth Catalysts
- NMPA Innovation Track:Accelerated review pathways for chronic pain indications compress registration timelines by prioritizing novel mechanisms of action.
- Specialist Clinic Clustering:Tier-one cities including Beijing and Shanghai concentrate pain management expertise, creating concentrated demand pools for advanced therapies.
- Biologic Pipeline Maturation:Novel peptide and biologic candidates advancing through Phase III trials expand therapeutic options beyond small-molecule modulators.
Market Restraints
- API Import Dependency:Domestic manufacturers rely on imported active pharmaceutical ingredients for several pain modulator classes, exposing margins to currency and supply volatility.
- Reimbursement Compression:National Healthcare Security Administration volume-based procurement protocols enforce mandatory price cuts upon tender success.
- Diagnostic Underrecognition:Widespread Pain Index application remains inconsistent across provincial hospital systems, delaying treatment initiation.
Strategic Opportunities
- Central China Expansion:Chengdu and Wuhan medical centers are building pain management capacity, offering first-mover advantages ahead of formulary saturation.
- Injectable Delivery Convergence:Combination of sustained-release formulation technology with hospital outpatient administration protocols creates new therapy positioning.
- Dual Carbon Alignment:Domestic manufacturing investments qualifying for green technology incentives under MIIT guidelines secure preferential procurement scoring.
Industry Challenges
- Pain Specialist Shortage:Certified fibromyalgia diagnosticians concentrate in coastal provinces, limiting rural and central region patient access.
- Legacy System Integration:Hospital electronic health record platforms require customized compatibility layers for novel diagnostic scoring tools.
- Pharmacovigilance Scale-Up:Post-market adverse event monitoring infrastructure must expand to match biologic therapy launch volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chinese Fibromyalgia Market |
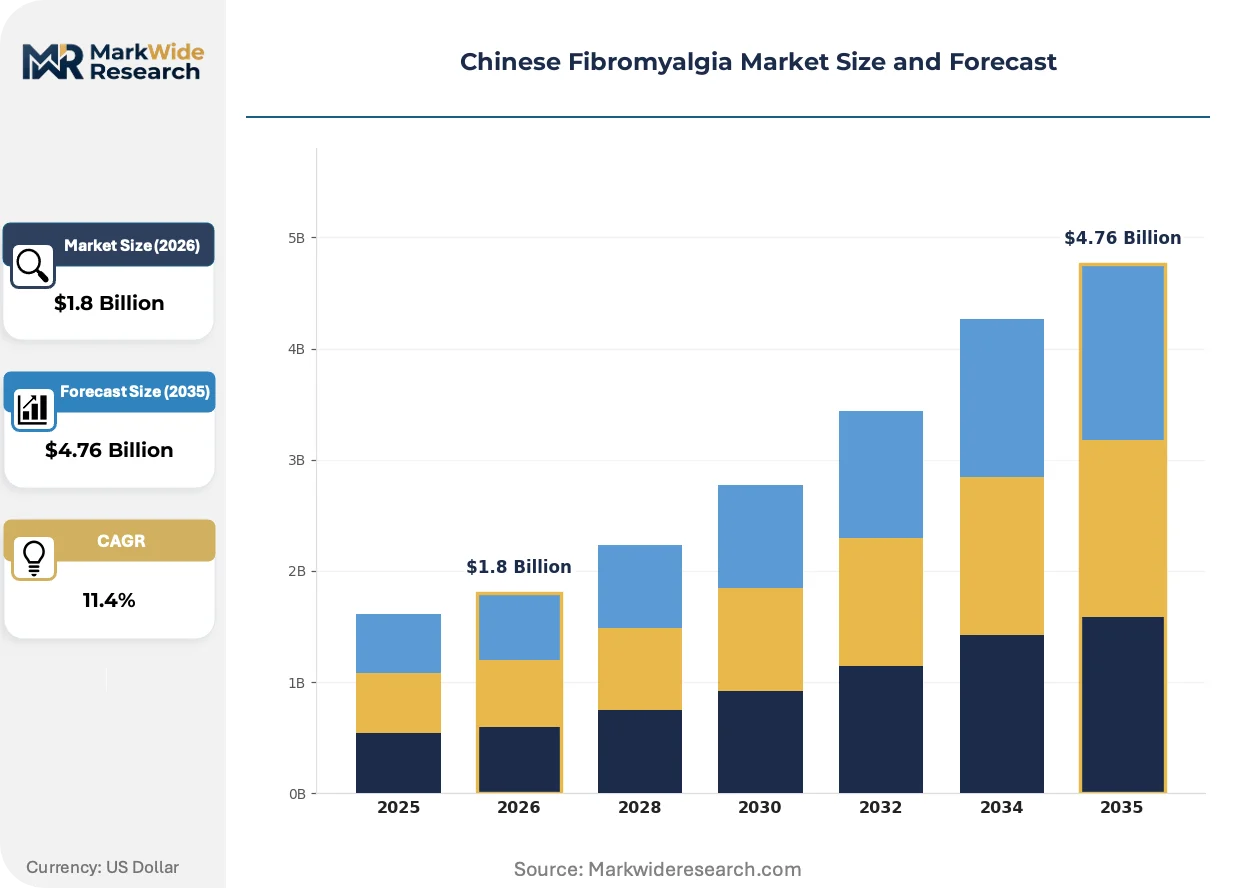
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Supplements, Therapies, Alternative Medicine Delivery Mode: Oral, Injectable, Transdermal, Infusion Customer Type: Retail Patients, Hospitals, Clinics, Home Care Providers Treatment Method: Cognitive Behavioral Therapy, Physical Therapy, Acupuncture, Mindfulness |
| Companies Covered | Pfizer, Eli Lilly and Company, AstraZeneca, Jiangsu Hengrui Medicine, Luye Pharma Group, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, AbbVie, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chinese Fibromyalgia Market Emerging Trajectories
China's fibromyalgia treatment landscape is experiencing therapeutic modality diversification and procurement mechanism digitization, with hospital purchasing behavior and regulatory review processes evolving in parallel.
Biologic pain modulators targeting nerve growth factor pathways are fragmenting the historical dominance of serotonin-norepinephrine reuptake inhibitors in hospital formularies. Tertiary medical centers in Shanghai and Guangzhou are piloting these therapies for treatment-resistant cases. The technology is fragmenting prescriber loyalty toward established antidepressant-class therapies by demonstrating superior pain scores in head-to-head hospital protocols.
NMPA's Center for Drug Evaluation has tightened pharmacovigilance documentation requirements for chronic pain therapies seeking market authorization. Manufacturers must now submit real-world evidence protocols alongside clinical trial data. Imported biologics face extended review timelines as NMPA prioritizes domestic manufacturing capacity under Good Manufacturing Practice standards.
Hospital procurement departments are consolidating vendor relationships through provincial centralized tender platforms, reducing the number of approved suppliers per therapeutic class. Volume-based procurement winners secure multi-year formulary exclusivity in exchange for steep price concessions. This consolidation is most visible in Jiangsu and Zhejiang provinces where tender participation thresholds have risen substantially.
Chinese Fibromyalgia Market Segmentation
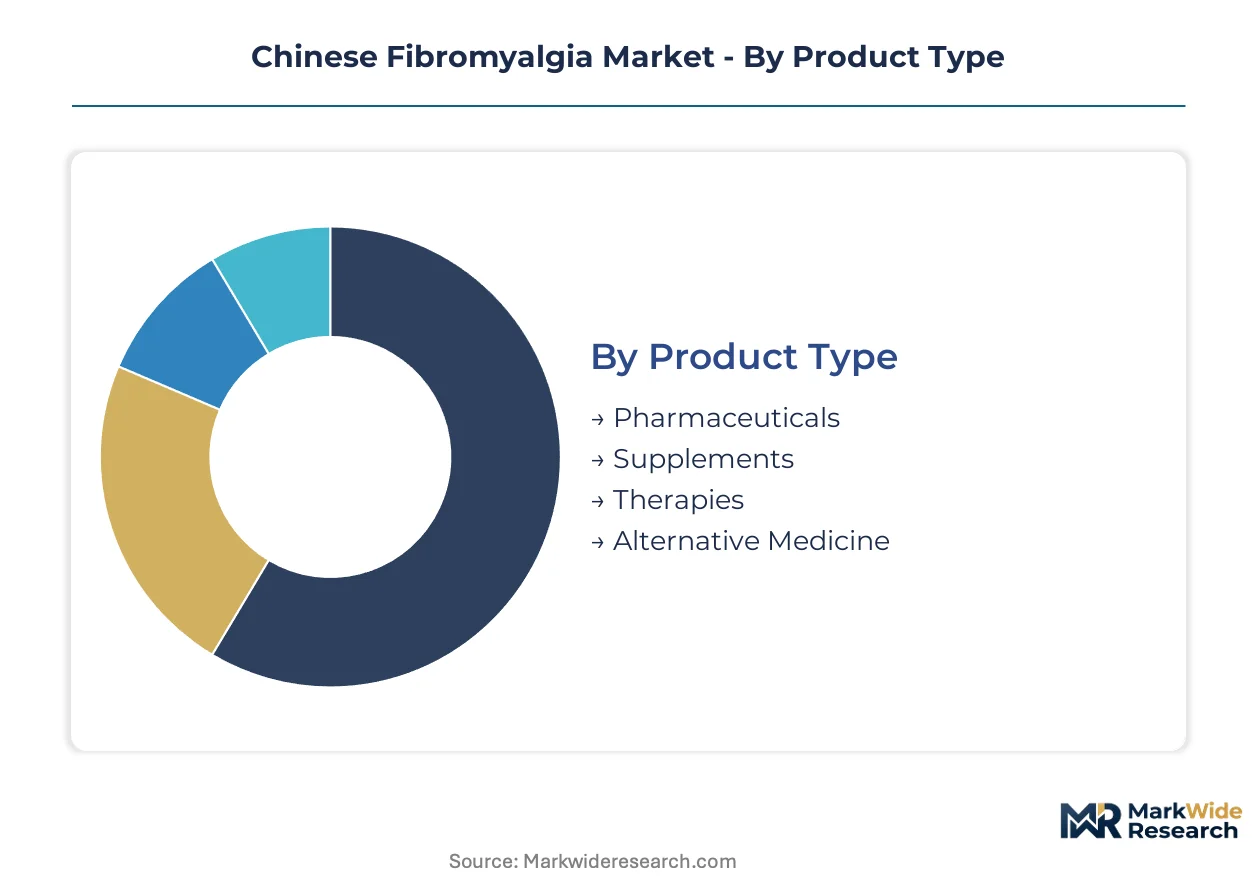
China's fibromyalgia market fragments across therapeutic modalities and care settings, with NMPA regulatory pathways and hospital procurement reforms determining which segments capture institutional volume versus retail out-of-pocket spend. Understanding these divisions reveals where centralized tendering concentrates pricing pressure versus where patient self-selection preserves margin.
Product Type:
Domestic manufacturing capacity concentrates in pharmaceuticals and supplements, while imported biologics and specialized alternative medicine formulations rely on cross-border supply chains subject to NMPA import licensing delays.
- Pharmaceuticals:Small-molecule pain modulators and antidepressant-class therapies dominate hospital formularies under volume-based procurement. Prescription requirements tie demand to tertiary medical centers in Beijing and Shanghai where specialist diagnosis concentrates.
- Supplements:Nutraceutical formulations targeting mitochondrial support and neuroinflammation modulation circulate through retail channels and e-commerce platforms. Domestic brands compete on price while imported products leverage cross-border e-commerce exemptions.
- Therapies:Device-based and procedural interventions including transcranial magnetic stimulation require hospital outpatient department infrastructure.
- Alternative Medicine:Traditional Chinese medicine formulations and herbal compounds operate under dual regulatory tracks—health product registration versus drug approval—creating market access heterogeneity.
Pharmaceuticals commands the established base. The steepest expansion runs through alternative medicine as provincial health authorities integrate TCM into chronic pain management protocols.
Delivery Mode:
Cost tiering separates hospital-administered modalities from self-managed alternatives, with reimbursement status determining which delivery modes sustain volume versus premium positioning.
- Oral:Tablets and capsules dominate prescription volumes due to outpatient dispensing convenience and patient compliance familiarity. Manufacturing scale advantages accrue to domestic producers meeting Good Manufacturing Practice standards.
- Injectable:Sustained-release depot formulations and novel peptide therapies target treatment-resistant cases in specialist clinics. Shanghai and Guangzhou tertiary centers pilot biologic injectables prior to broader formulary inclusion.
- Transdermal:Patch-based delivery bypasses first-pass metabolism for patients with gastrointestinal intolerance.
- Infusion:Hospital-based intravenous administration applies to acute pain flares and combination therapy protocols.
Oral formulations anchor prescription volume. Injectable delivery gains share fastest as biologic pipeline candidates advance through Phase III trials.
Customer Type:
Volume concentration diverges between high-frequency retail transactions and lower-volume hospital encounters with elevated procedural coding.
- Retail Patients:Self-directed purchasers drive supplement and over-the-counter analgesic volume through pharmacy chains and e-commerce. Tier-one city consumers demonstrate higher willingness-to-pay for imported brands.
- Hospitals:Tertiary medical centers capture diagnostic workup revenue and procedural therapy administration. Centralized procurement reforms compress pharmaceutical pricing while preserving service fee structures.
- Clinics:Specialist pain clinics in Beijing and Shanghai concentrate advanced therapy access.
- Home Care Providers:Post-acute and long-term care settings manage maintenance therapy for mobility-limited patients.
Retail patients generate transaction frequency. Hospital clinics concentrate per-episode spend through bundled diagnostic and therapeutic coding.
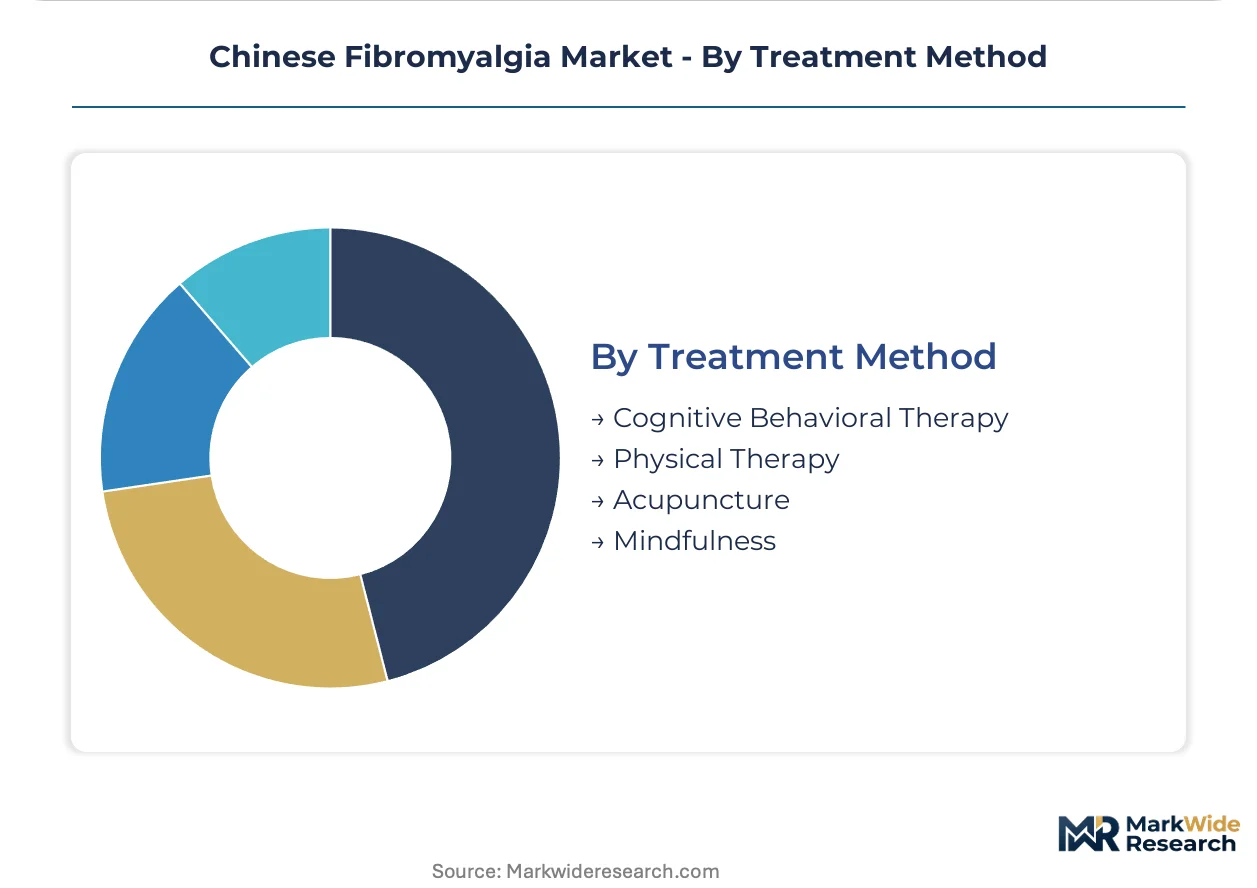
Treatment Method:
Reimbursement eligibility separates insurance-covered modalities from out-of-pocket wellness offerings, with provincial variation in TCM integration policies creating geographic demand skew.
- Cognitive Behavioral Therapy:Structured psychological intervention addresses central sensitization mechanisms and comorbid mood disturbance. Implementation depends on licensed practitioner availability concentrated in coastal provinces.
- Physical Therapy:Exercise-based rehabilitation protocols require specialized equipment and trained physiotherapist supervision.
- Acupuncture:Traditional Chinese medicine modality receives partial reimbursement under provincial medical insurance schemes.
- Mindfulness:Meditation and stress reduction techniques operate outside formal reimbursement frameworks.
Physical therapy commands the established reimbursement base. Mindfulness expands most quickly through digital health platforms and employer wellness programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of active pharmaceutical ingredients for pain modulators concentrate through Shanghai and Tianjin ports, with European and Indian suppliers serving domestic formulation manufacturers under NMPA import licensing frameworks.
Beijing-Tianjin-Hebei
Specialist pain clinics at Peking Union Medical College Hospital and Beijing Tiantan Hospital anchor diagnostic capacity for fibromyalgia under the modified ACR criteria. The National Healthcare Security Administration's centralized procurement protocols enforce price compression on serotonin-norepinephrine reuptake inhibitors entering hospital formularies. Beijing's tertiary medical centers pilot biologic therapies through NMPA innovation-track approvals.
Yangtze River Delta
Shanghai Ruijin Hospital and Huashan Hospital concentrate advanced pain management infrastructure and biologic injection administration protocols. Jiangsu province leads volume-based procurement tender participation, with Zhejiang hospitals consolidating vendor relationships through provincial centralized platforms. Suzhou and Hangzhou medical centers expand specialist clinic capacity ahead of formulary saturation.
Pearl River Delta
Guangzhou's Sun Yat-sen University hospitals and Shenzhen People's Hospital drive demand for sustained-release depot formulations. Guangdong province integrates traditional Chinese medicine pain protocols under provincial medical insurance partial reimbursement schemes. The cluster attracts imported biologic shipments through Shenzhen's pharmaceutical import corridor.
Sichuan-Chongqing
Chengdu's West China Hospital and Chongqing Medical University hospitals build pain management capacity as central China expansion targets. Sichuan province's healthcare procurement platforms raise tender participation thresholds, favoring domestic manufacturers with GMP-certified production. The sub-region offers first-mover positioning ahead of coastal formulary saturation.
Chinese Fibromyalgia Market Vendor Landscape
Player mix skews toward multinational pharmaceutical incumbents with established neurology franchises alongside domestic manufacturers competing on volume-based procurement compliance. Hospital formulary access depends on centralized tender success under NHSA protocols. Two strategic archetypes dominate: patent-protected biologic developers and generic-scale domestic producers. Competitive moves center on NMPA innovation-track registration acceleration and provincial procurement tender participation.
Within the multinational tier, Pfizer and Eli Lilly and Company exemplify established institutional contract holders leveraging differentiated mechanism positioning. Among domestic competitors, Jiangsu Hengrui Medicine occupies a scale-driven position aligned with centralized procurement reforms. These three anchors represent the competitive tension between imported biologic pipelines and domestic manufacturing cost compliance under NMPA quality benchmarks.
| Leading Market Players |
|---|
| Pfizer |
| Eli Lilly and Company |
| AstraZeneca |
| Jiangsu Hengrui Medicine |
| Luye Pharma Group |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| AbbVie |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Multi-year volume-based procurement contracts lock in both API supply access and reimbursement price visibility for fibromyalgia therapies under NHSA protocols, binding domestic formulators to imported active pharmaceutical ingredient commitments while compressing margin buffers.
Pricing Analysis
Small-molecule serotonin-norepinephrine reuptake inhibitor pricing gaps separate established generic entrants from patent-protected biologic candidates entering through NMPA innovation-track approvals. Three-tier pricing structure across premium biologics, standard branded small-molecules, and economy generic tiers reflects certification grade under Good Manufacturing Practice standards and volume scale under provincial tender participation. Cost compression in the economy tier is intensifying because Jiangsu and Zhejiang procurement platforms have raised tender participation thresholds. Hospital procurement departments demonstrate highest price sensitivity, while retail patients in tier-one cities show lowest sensitivity for imported supplement brands.
Supply Chain Analysis
Shanghai and Tianjin port congestion for API containers from European and Indian suppliers elevates inbound logistics costs for domestic pain modulator manufacturers. Active pharmaceutical ingredient supply concentrates in India, China, and selected European manufacturing hubs, with domestic formulators drawing from imported raw materials for nerve growth factor inhibitors and novel peptide candidates. Single-source vulnerability runs through concentrated European suppliers for specialized biologic precursors. Distribution runs through hospital procurement departments consolidating vendor relationships via provincial centralized tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's fibromyalgia market sits at a platform-economics inflection where hospital formulary digitization and provincial procurement platform interoperability are reshaping how manufacturers secure access and price realization.
For Market Incumbents: Secure NMPA innovation-track priority review status for biologic pipeline candidates before volume-based procurement saturation in coastal provinces. Consolidate backward integration into API manufacturing under MIIT green technology incentive guidelines to defend margin position against domestic generic scale competitors. Lock in multi-year hospital system partnerships in Chengdu and Wuhan ahead of central China formulary expansion. For New Entrants and Emerging Players: Differentiate on traditional Chinese medicine integration protocols under provincial partial reimbursement schemes, targeting Sichuan-Chongqing sub-regions where TCM pain management capacity is expanding fastest. Penetrate the mindfulness digital health segment through employer wellness program partnerships, bypassing hospital formulary gatekeeping entirely. Pursue cross-border e-commerce exemptions for imported nutraceutical positioning. For Investors and Strategic Acquirers: GMP-certified domestic manufacturers with volume-based procurement compliance track records represent the most defensible acquisition archetype in this market. Long-term viability hinges on positioning for biologic transition while maintaining generic cash flow stability. Watch NMPA innovation-track approval velocity for nerve growth factor pathway candidates as the inflection signal indicating pipeline maturation timing.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation-Track Registration | Accelerated review compresses timelines for novel mechanism therapies entering Beijing and Shanghai hospitals. |
| Provincial Tender Platform Consolidation | Jiangsu and Zhejiang procurement reforms reduce approved suppliers per therapeutic class under NHSA protocols. |
| API Manufacturing Scale-Up | Domestic GMP-certified production reduces import dependency exposure under MIIT quality benchmarks. |
| TCM Protocol Integration | Guangdong and Sichuan partial reimbursement schemes expand addressable market beyond pharmaceutical formularies. |
| Specialist Clinic Network Expansion | Chengdu and Wuhan pain management capacity builds capture first-mover positioning ahead of coastal saturation. |
Methodological Framework
A standing panel of hospital procurement managers, formulary directors, regulatory affairs leads at NMPA-registered manufacturers, and pain clinic specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against NMPA Center for Drug Evaluation filings, NHSA procurement tender databases, ClinicalTrials.gov China entries, and MIIT Good Manufacturing Practice certification records. Bottom-up prescription volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled segmentation dimensions including therapeutic modality, delivery mode, customer type, and regional regulatory cluster. CAGRs derived from patient population growth assumptions, pricing trajectory modeling under volume-based procurement, and therapy penetration rate evolution. Forecast inputs incorporated NMPA approval pipeline velocity and provincial tender calendar density.
The analysis sits within stated boundaries; outcomes outside NMPA regulatory pathway continuity, NHSA procurement reform implementation, or API import flow stability would require recalibration. Forecasts reflect documented assumptions regarding specialist diagnostician training expansion and biologic manufacturing scale-up feasibility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cold Pain Therapy Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Cancer Pain Management Market
Pain Management
Visceral Pain Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Dyspareunia Market
Pain Management
Chronic Pain Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Spine Pain Market
Pain Management
Pain Patches Market
Pain Management
Neuralgia Treatment Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Provoked Vestibulodynia Treatment Market