
 Bone Pain Treatment Market | 2026-2036
Bone Pain Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Pain Treatment Market Analysis
Oncology pain management is decoupling from general palliative care as a distinct specialty channel. Pfizer leverages its biologics manufacturing scale to supply denosumab formulations for skeletal-related events. Amgen anchors the monoclonal antibody segment with its established R&D infrastructure for bone-modifying agents. Novartis competes through radiopharmaceutical pipelines targeting metastatic bone lesions.
Bone pain treatment encompasses pharmacological and interventional modalities that modulate nociceptive signaling from osseous tissue, including bisphosphonates that inhibit osteoclast-mediated bone resorption and targeted alpha-emitters for localized radiation delivery. Analgesics and nonsteroidal anti-inflammatory drugs occupy the largest volume share as first-line agents, while osteoporosis medications generate premium margins due to chronic administration profiles. Injectable delivery modes are expanding fastest in hospital settings where bioavailability requirements override patient convenience preferences.
The FDA, EMA, and WHO pharmacovigilance frameworks govern bone-modifying agent approvals, with post-market surveillance requirements extending trial obligations and shaping manufacturer liability structures. The FDA's opioid REMS program and EMA's extended pharmacovigilance mandates for bisphosphonate-related osteonecrosis of the jaw are redirecting development investment toward non-opioid mechanisms. Stakeholders must monitor radiopharmaceutical manufacturing capacity constraints and reimbursement negotiations for novel targeted therapies as competitive differentiators.
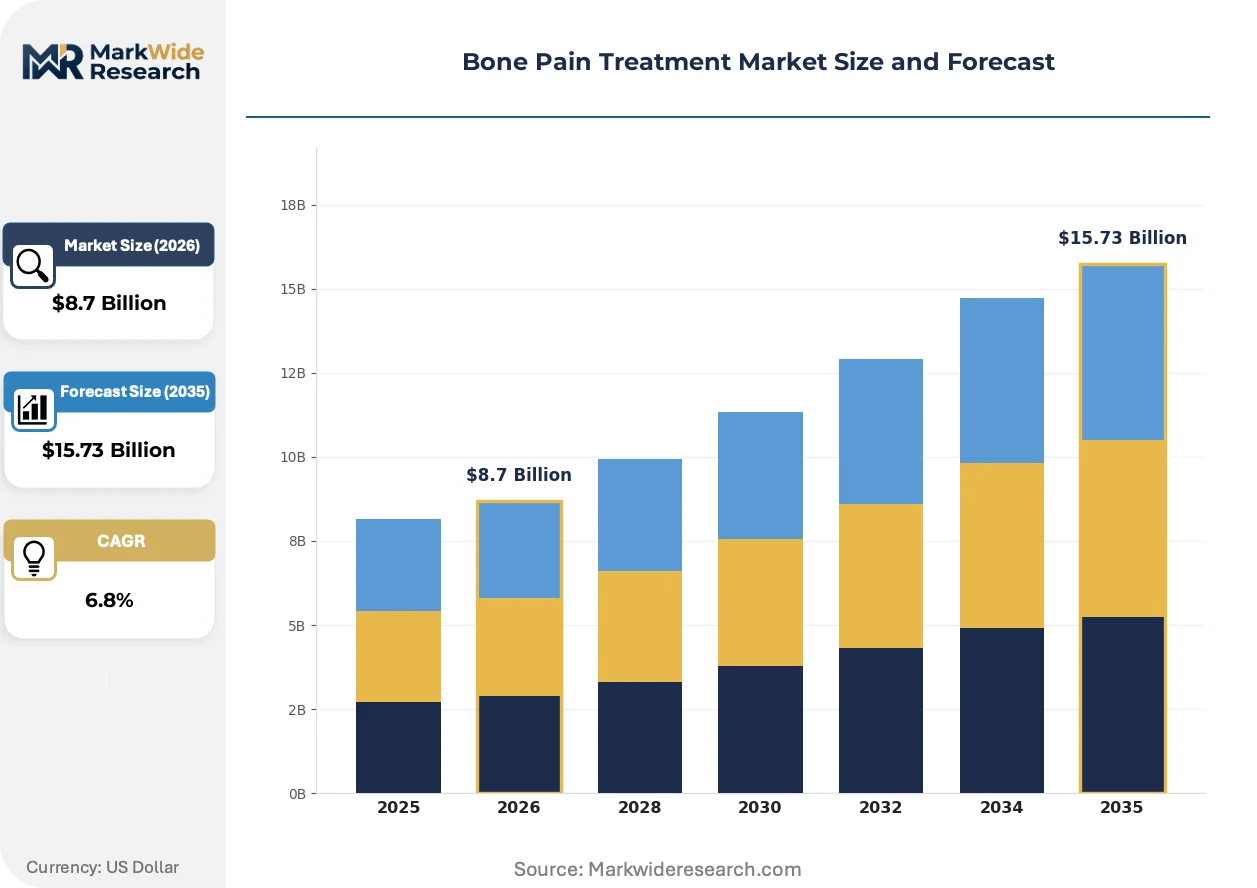
Market Dynamics
The FDA's opioid REMS program is forcing oncology centers to rebuild pain management protocols around non-narcotic mechanisms, redirecting procurement budgets toward bisphosphonates, monoclonal antibodies, and radiopharmaceuticals while eroding traditional analgesic volume.
Growth Catalysts
- EMA Extended Pharmacovigilance:Post-market surveillance mandates for bisphosphonate-related osteonecrosis of the jaw are accelerating manufacturer investment in safer bone-modifying agents and novel delivery mechanisms.
- Oncology Center Expansion:Specialized skeletal-related event units within cancer hospitals are creating dedicated procurement channels for denosumab and targeted alpha-emitter formulations.
- Integrated Delivery Networks:US-based IDN consolidation of musculoskeletal care pathways is standardizing formularies and concentrating purchasing power for premium osteoporosis medications.
Market Restraints
- Radiopharmaceutical Manufacturing Bottlenecks:Limited production capacity for alpha-emitting isotopes constrains supply expansion for metastatic bone lesion therapies.
- Reimbursement Negotiation Friction:Payer resistance to novel targeted therapies in Germany and France delays market access for premium radiopharmaceutical pipelines.
- Substitution Pressure from Biosimilars:Denosumab biosimilar entry is compressing margins for originator monoclonal antibodies in European hospital tenders.
Strategic Opportunities
- Underpenetrated Ambulatory Infusion:Outpatient oncology clinics in Spain and Italy represent expansion targets for injectable bisphosphonate administration outside hospital settings.
- Dual-Action Formulation Convergence:Combination therapies integrating anti-resorptive agents with analgesic payloads are opening chronic administration profiles in palliative care.
- WHO Essential Medicines Listing:Inclusion of specific bone-modifying agents in national formularies across Southeast Asia is unlocking government procurement channels.
Industry Challenges
- Radiopharmaceutical Handling Certification:Nuclear medicine technicians require specialized training for alpha-emitter administration, creating workforce bottlenecks in community oncology settings.
- Legacy EHR Integration:Pain management protocols for skeletal-related events require reconfiguration of electronic health record workflows, delaying protocol standardization across health system networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Pain Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Nonsteroidal Anti-inflammatory Drugs, Corticosteroids, Osteoporosis Medications Therapy Area: Osteoarthritis, Osteoporosis, Rheumatoid Arthritis, Post-surgical Pain Delivery Mode: Oral, Injectable, Transdermal, Topical End User: Hospitals, Outpatient Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | Pfizer, Novartis, Johnson & Johnson, Eli Lilly, Amgen, GSK, Merck & Co., Abbott, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Pain Treatment Market Emerging Trajectories
Biologics manufacturing platforms are reshaping competitive economics in bone-modifying agents. Three distinct vectors are compressing development timelines and altering procurement patterns across oncology and musculoskeletal specialties.
Targeted alpha-emitter conjugates for metastatic bone lesions are modularizing radiopharmaceutical supply chains. Isotope production partnerships with nuclear reactors are replacing captive cyclotron facilities. Hospital buyers are consolidating vendor relationships around integrated dose-calibration and logistics services. This modularization is lowering capital barriers for regional cancer centers entering radioligand therapy.
EMA's extended pharmacovigilance mandates for osteonecrosis of the jaw are extending clinical trial obligations into post-market phases. Manufacturers must maintain active surveillance registries for bisphosphonate and denosumab patients. The monoclonal antibody segment is absorbing these compliance costs through risk-sharing agreements with European reference pricing authorities.
Integrated delivery networks are unbundling pain management from general oncology procurement. IDN pharmacy and therapeutics committees are creating separate formularies for skeletal-related event protocols. This reorganization is most advanced in Texas and California health systems, where specialized bone health service lines are capturing pharmacy budgets previously controlled by medical oncology divisions.
Bone Pain Treatment Market Segmentation
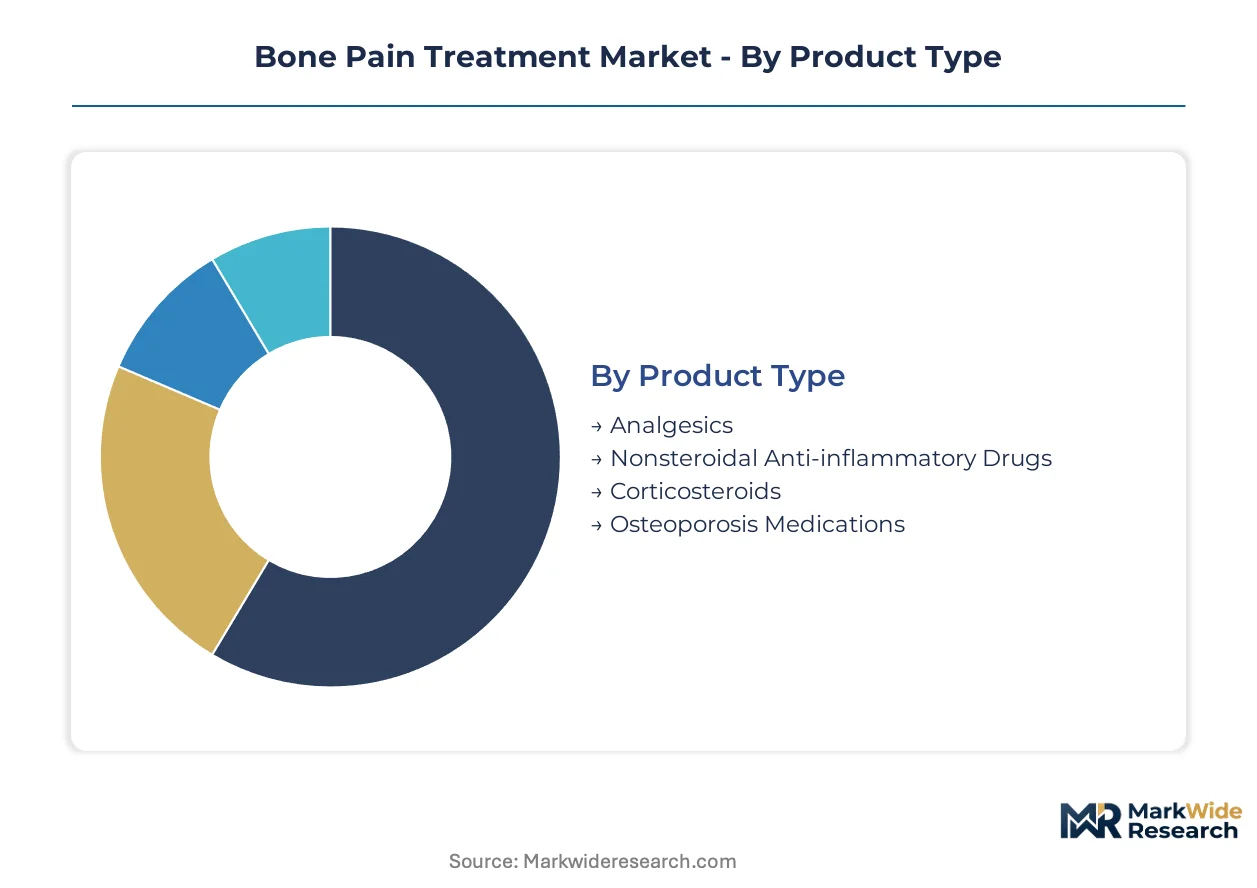
Bone pain treatment modalities span pharmacological and interventional categories with distinct procurement pathways. Segmentation reveals where integrated delivery networks concentrate purchasing power and which delivery modes are displacing traditional administration routes.
Product Type:
Standalone analgesics operate independently of disease-modifying protocols, while osteoporosis medications embed within chronic skeletal management systems.
- Analgesics:First-line agents targeting nociceptive signaling through opioid and non-opioid mechanisms. Hospital formularies in the United States are restricting opioid analgesic placement under FDA REMS compliance mandates.
- Nonsteroidal Anti-inflammatory Drugs:Oral and topical formulations modulating prostaglandin synthesis for inflammatory bone pain. Outpatient clinics in Germany and France favor NSAID prescriptions to avoid opioid escalation pathways.
- Corticosteroids:Potent anti-inflammatory agents for acute bone pain flares and intra-articular injection protocols.
- Osteoporosis Medications:Bisphosphonates and monoclonal antibodies inhibiting osteoclast-mediated resorption with chronic administration profiles.
Volume placements concentrate in analgesics; the faster expansion belongs to osteoporosis medications.
Therapy Area:
Cost tier stratification separates acute intervention segments from chronic management categories with recurring revenue profiles.
- Osteoarthritis:Degenerative joint disease driving demand for intra-articular corticosteroid and hyaluronic acid injections. Medicare reimbursement policies in the United States shape procedural volume for viscosupplementation.
- Osteoporosis:Systemic bone density loss requiring long-term anti-resorptive therapy. Japan's aging demographic concentration sustains premium pricing for denosumab and bisphosphonate formulations.
- Rheumatoid Arthritis:Autoimmune-mediated bone erosion combining disease-modifying antirheumatic drugs with pain management protocols.
- Post-surgical Pain:Acute intervention window favoring multimodal analgesia and regional anesthesia techniques over standalone opioid therapy.
Revenue concentration sits with osteoporosis; post-surgical pain is climbing the fastest as enhanced recovery after surgery protocols expand.
Delivery Mode:
Application context determines whether patient convenience or bioavailability requirements dominate formulation selection.
- Oral:Convenience-driven administration for chronic outpatient management with established generic substitution patterns.
- Injectable:Hospital and oncology center preference where rapid onset and complete bioavailability override administration burden. Injectable bisphosphonates and denosumab dominate skeletal-related event protocols in cancer hospitals.
- Transdermal:Steady-state plasma concentration maintenance for chronic pain with reduced gastrointestinal exposure.
- Topical:Localized delivery for superficial bone pain with minimal systemic absorption and favorable safety profiles.
Oral formulations retain volume dominance; injectable modes are gaining share fastest as hospital-based oncology pain management protocols expand.
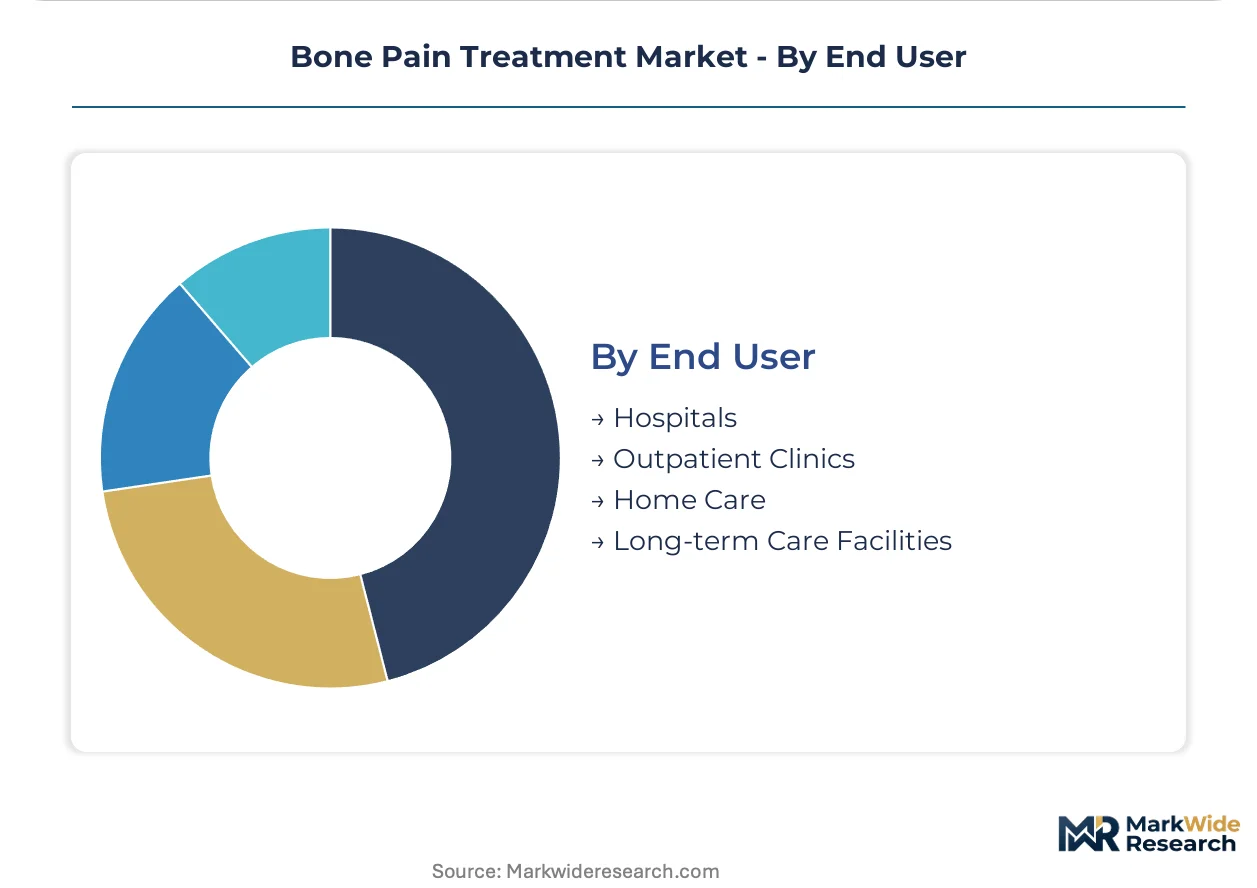
End User:
Customer type segmentation tracks where procurement authority concentrates and how reimbursement pathways shape site-of-care decisions.
- Hospitals:Centralized pharmacy and therapeutics committees controlling formulary placement for inpatient and emergency department protocols. United States health systems are consolidating bone pain management under specialized skeletal-related event service lines.
- Outpatient Clinics:Ambulatory oncology and rheumatology settings where infusion center economics drive injectable therapy selection.
- Home Care:Oral and transdermal administration with nursing support for mobility-limited patients.
- Long-term Care Facilities:Regulatory scrutiny of antipsychotic and sedative use is redirecting pain management toward non-pharmacological and topical interventions.
Procurement authority concentrates in hospitals; outpatient clinics represent the steepest expansion trajectory as oncology centers unbundle pain management from inpatient services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of bone-modifying agents clusters in the United States, Germany, and Switzerland, while consumption concentrates in aging economies with high oncology burden. The FDA's opioid REMS program and EMA's extended pharmacovigilance mandates are reshaping procurement patterns across major markets.
United States
Integrated delivery networks in Texas and California are consolidating musculoskeletal care pathways under specialized skeletal-related event service lines. The FDA's opioid risk evaluation and mitigation strategy redirects hospital formularies toward bisphosphonates and monoclonal antibodies. Boston's oncology research corridor anchors denosumab manufacturing scale for domestic supply.
Germany
Reference pricing authorities negotiate risk-sharing agreements for premium osteoporosis medications amid biosimilar entry pressure. EMA extended pharmacovigilance mandates for bisphosphonate-related osteonecrosis accelerate post-market surveillance investments. The Rhine-Main biopharma cluster hosts radiopharmaceutical development partnerships with university medical centers.
Japan
Aging demographics sustain premium pricing for chronic anti-resorptive therapies in the world's oldest population. The Pharmaceuticals and Medical Devices Agency maintains stringent safety monitoring for bone-modifying agents in long-term administration. Tokyo's hospital networks pioneer ambulatory infusion protocols for outpatient oncology clinics.
United Kingdom
NICE technology appraisals determine reimbursement access for novel targeted alpha-emitter therapies in metastatic bone lesions. The NHS long-term plan prioritizes non-opioid pain management pathways in cancer care. London's academic medical centers coordinate multicenter trials for radioligand therapy dose optimization.
France
Payer resistance to premium radiopharmaceuticals delays market access despite clinical efficacy demonstrations. ANSM pharmacovigilance frameworks require specialized handling certification for nuclear medicine technicians. The Paris-Saclay research cluster advances isotope production partnerships for regional cancer center supply.
Bone Pain Treatment Market Vendor Landscape
Top-tier vendors anchor the monoclonal antibody and radiopharmaceutical segments, while mid-scale specialists populate the generic analgesic and bisphosphonate tiers. The market exhibits consolidated R&D infrastructure alongside fragmented manufacturing of commodity formulations. Three archetypes dominate: biologics platform operators, radiopharmaceutical modularizers, and integrated pain management portfolio builders. Competitive maneuvering centers on isotope production partnerships and IDN formulary consolidation contracts.
Among established biopharmaceutical conglomerates, Pfizer leverages manufacturing scale for denosumab supply chain security, while Amgen anchors monoclonal antibody development infrastructure for bone-modifying agents. Novartis occupies a distinct position through radiopharmaceutical pipeline investments targeting metastatic bone lesions. These three exemplify divergent strategic vectors—biologics manufacturing depth, established antibody R&D, and radioligand therapy modularization—shaping procurement relationships with oncology centers and integrated delivery networks.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Johnson & Johnson |
| Eli Lilly |
| Amgen |
| GSK |
| Merck & Co. |
| Abbott |
| Teva Pharmaceutical Industries |
| Others |
Supply Flow & Price Mechanics
Captive biologics manufacturing by Pfizer and Amgen anchors supply security for denosumab and monoclonal antibody formulations, concentrating pricing power with originators while biosimilar entrants compress margins in European tenders. This vertical integration into active pharmaceutical ingredient production insulates premium osteoporosis medications from spot-market volatility but exposes hospital buyers to concentrated supplier leverage.
Pricing Analysis
Short lead-time premiums for alpha-emitting radiopharmaceuticals command substantial markups over standard bisphosphonate procurement, while spot inventory of generic analgesics trades at depressed levels. Three-tier pricing structure across originator biologics, authorized biosimilars, and commodity generics separates oncology hospital formularies from outpatient clinic budgets. Pricing pressure stems from denosumab biosimilar entry in Germany and France, where reference pricing authorities negotiate risk-sharing agreements. Outpatient clinics exhibit highest price sensitivity due to infusion center margin constraints; specialized skeletal-related event units within cancer hospitals demonstrate lowest sensitivity due to protocol-locked formularies.
Supply Chain Analysis
FDA current good manufacturing practice certification and EMA extended pharmacovigilance mandates gate entry for bisphosphonate and monoclonal antibody suppliers, filtering subscale manufacturers from hospital procurement channels. Active pharmaceutical ingredient production concentrates in the United States, Switzerland, and Ireland, while fill-finish operations draw from Puerto Rican and German contract manufacturing networks. Supply chain risk centers on single-source vulnerability for alpha-emitting isotopes produced at limited nuclear reactor facilities. Distribution runs through integrated delivery network centralized pharmacy committees controlling formulary placement across multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA opioid REMS compliance costs and EMA post-market surveillance obligations force subscale analgesic manufacturers toward exit.
For Market Incumbents: Cement formulary control through risk-sharing agreements with IDN pharmacy and therapeutics committees, locking out biosimilar substitution for denosumab protocols. Deepen backward integration into isotope production partnerships to secure alpha-emitter supply against nuclear reactor capacity constraints. Defensive patent estate management around bisphosphonate delivery mechanisms delays generic erosion. For New Entrants and Emerging Players: The mid-tier pricing gap between premium monoclonal antibodies and economy generic bisphosphosphonates offers white-space positioning for novel dual-action formulations combining anti-resorptive and analgesic payloads. Target ambulatory infusion centers in Spain and Italy where hospital-unbundled oncology pain management creates procurement autonomy. Pursue WHO Essential Medicines listing pathways to unlock government procurement channels in Southeast Asia. For Investors and Strategic Acquirers: Exit pathways concentrate in radiopharmaceutical modularizers with isotope production partnerships and captive dose-calibration logistics. Long-term viability favors platform operators with biologics manufacturing depth over single-product osteoporosis specialists. Watch FDA radiopharmaceutical manufacturing guidance revisions as inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Isotope Production Partnership | Alpha-emitter supply security anchors radioligand therapy expansion for regional cancer centers. |
| IDN Formulary Consolidation Contract | Multi-hospital system agreements lock in skeletal-related event protocol standardization. |
| WHO Essential Medicines Listing Application | National formulary inclusion unlocks government procurement channels across Southeast Asia. |
| Biosimilar Manufacturing Scale-Up | European tender participation compresses originator margins while capturing volume share. |
| Radiopharmaceutical Handling Certification Program | Nuclear medicine technician training expands addressable market for community oncology settings. |
Methodological Framework
Multi-period observation of FDA REMS compliance filings, EMA pharmacovigilance registry expansions, and IDN formulary consolidation announcements anchored the trend analysis, supplemented by interviews with oncology pharmacy directors, hospital procurement managers, regulatory affairs leads at biologics manufacturers, and payer access specialists. Secondary validation drew from FDA Orange Book listings, EMA EPAR assessments, ClinicalTrials.gov bone-modifying agent protocols, and CMS Medicare Part B reimbursement data. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue disclosures.
Segment-weighting across product type, therapy area, delivery mode, and end user channels shaped the analytical framework, with regional regulatory clusters treated as distinct modeling dimensions. CAGRs were derived from log-linear trend fitting across the projection horizon, calibrated to historical patent expiry impacts and biosimilar penetration curves. Forecast inputs incorporated oncology center expansion rates, radiopharmaceutical manufacturing capacity buildout timelines, and IDN consolidation velocity in Texas and California health systems.
Underlying measurement precision varies by segment; injectable bisphosphonate and denosumab volumes carry tighter precision than emerging radioligand therapy categories where manufacturing capacity constraints introduce uncertainty. Forecasts reflect assumptions around FDA REMS program continuity, EMA pharmacovigilance mandate stability, and isotope production partnership formation rates. A model refresh is warranted upon material change in alpha-emitter manufacturing capacity or IDN formulary consolidation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Heat Therapy Market
Pain Management
Topical Pain Relief Market
Pain Management
Cold Pain Therapy Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Cancer Pain Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Cluster Headache Market
Pain Management
Ketorolac Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Postoperative Pain Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Global Pain Management Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Arthralgia Management Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Asia-Pacific Chronic Disease Management Market