
 Global Analgesic Infusion Pumps Market | 2026-2036
Global Analgesic Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Analgesic Infusion Pumps Market Foresight
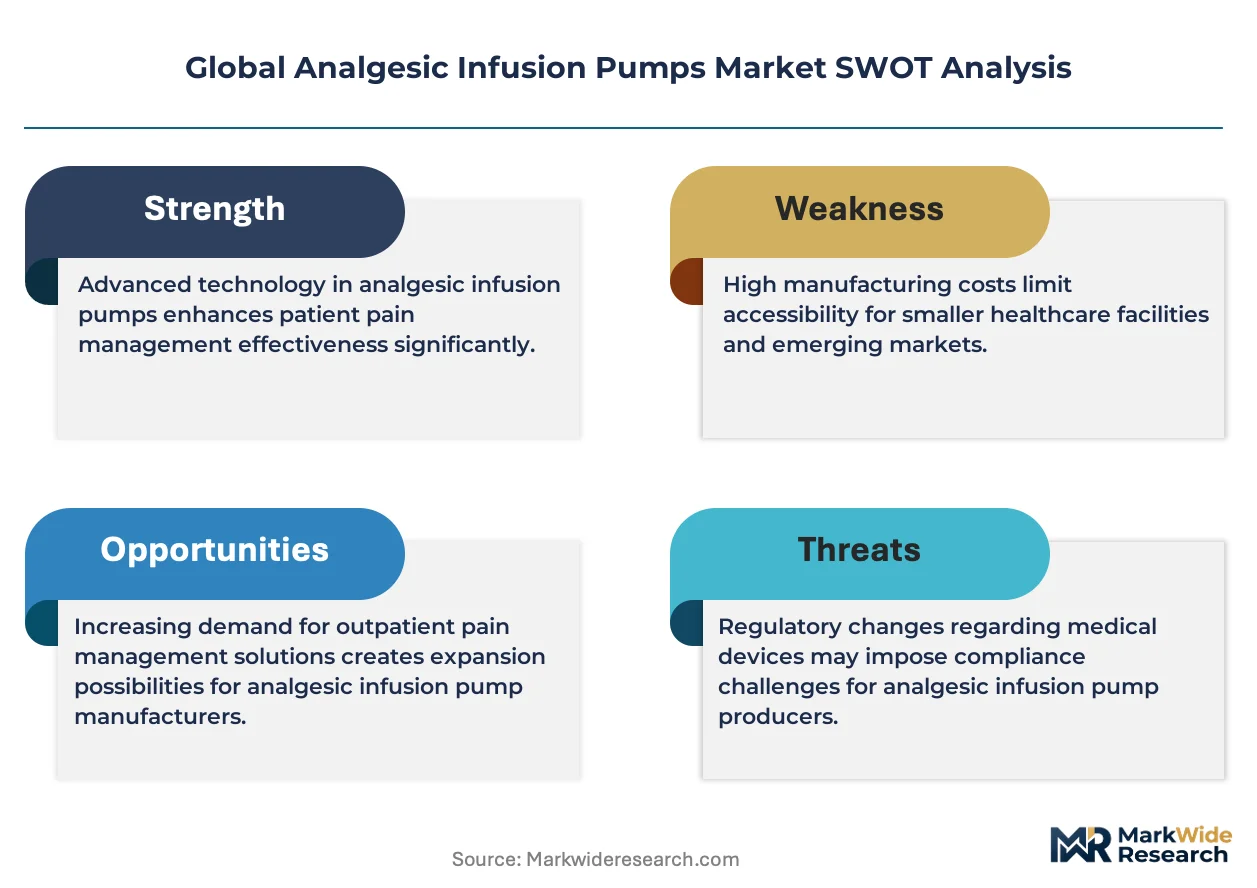
The analgesic infusion pump industry is pivoting around a widening split between premium connected devices with closed-loop safety architectures and commodity mechanical pumps serving cost-constrained procurement environments. B. Braun Melsungen AG leverages its vertically integrated manufacturing footprint in Europe to sustain margin advantages in elastomeric pump production. Baxter International Inc. anchors its competitive stance through deep hospital formulary relationships and specialized fluid-delivery expertise. Fresenius Kabi AG competes aggressively in ambulatory care channels where portability and disposable economics dominate purchasing criteria.
Analgesic infusion pumps are precision drug-delivery instruments engineered to administer controlled doses of pain medication through intravenous, epidural, or subcutaneous routes, typically operating within flow-rate tolerances of plus or minus five percent to prevent underdosing or respiratory depression. Patient-controlled technology leads installed base value due to higher unit economics and software-enabled safety interlocks, while elastomeric pumps represent the fastest-expanding segment in home healthcare where disposable simplicity reduces infection risk and eliminates capital equipment requirements. Electronic technology platforms concentrate margin pools through recurring software validation and cybersecurity maintenance revenues, whereas mechanical systems occupy stable but declining positions in emergency care settings with limited infrastructure.
The FDA enforces rigorous premarket notification requirements under 21 CFR 880.5725 for infusion pump safety interlocks and software validation, while the EU Medical Device Regulation mandates enhanced clinical evidence and post-market surveillance through EUDAMED registration. Japan's PMDA applies supplemental Japanese Industrial Standards for electromagnetic compatibility and alarm fatigue mitigation that extend development timelines for foreign manufacturers. Stakeholders must monitor evolving software-as-a-medical-device classifications and harmonized international standards for interoperability to anticipate compliance investments and competitive repositioning requirements.
Market Dynamics
The FDA's 510(k) software update pathway is compressing development cycles while expanding compliance overhead, forcing manufacturers to restructure R&D budgets around recurring validation costs rather than discrete hardware launches.
Growth Catalysts
- Ambulatory surgical center expansion:United States facility networks are installing patient-controlled analgesia systems to capture outpatient orthopedic and gynecological procedures migrating from inpatient settings.
- EUDAMED post-market surveillance mandates:EU Medical Device Regulation requirements for enhanced clinical evidence are accelerating replacement cycles as hospitals upgrade to compliant connected pump architectures.
- Elastomeric disposable economics:Home healthcare agencies in Germany are adopting single-use mechanical pumps to eliminate capital equipment maintenance and reduce catheter-related bloodstream infection liability.
Market Restraints
- Semiconductor component volatility:Precision flow sensors and microcontrollers face supply concentration in East Asian foundries, creating production scheduling uncertainty for electronic pump assembly.
- Biocompatibility testing costs:ISO 10993 cytotoxicity and sensitization studies for new catheter materials add eighteen to twenty-four months to product commercialization timelines.
- Mechanical pump substitution ceiling:Emergency departments in cost-constrained health systems retain gravity-fed alternatives for short-duration analgesia, limiting electronic system penetration in acute care.
Strategic Opportunities
- Japanese home healthcare underpenetration:METI reimbursement reforms for post-operative pain management are creating first-mover advantages for portable elastomeric pump distributors building local service infrastructure.
- Closed-loop safety convergence:Integration of respiratory monitoring with infusion rate modulation is opening premium positioning for anesthesia-critical care crossover applications.
- Direct-to-hospital digital procurement:Specialized distributors in France are bypassing group purchasing organizations through e-commerce platforms with real-time inventory visibility and same-day fulfillment.
Industry Challenges
- Cybersecurity validation backlog:FDA premarket submissions for software-enabled safety interlocks face extended review queues, compressing revenue recognition timelines for connected device portfolios.
- Legacy system integration friction:Hospital IT departments struggle to harmonize proprietary pump communication protocols with existing electronic health record architectures, delaying multi-device fleet deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Analgesic Infusion Pumps Market |
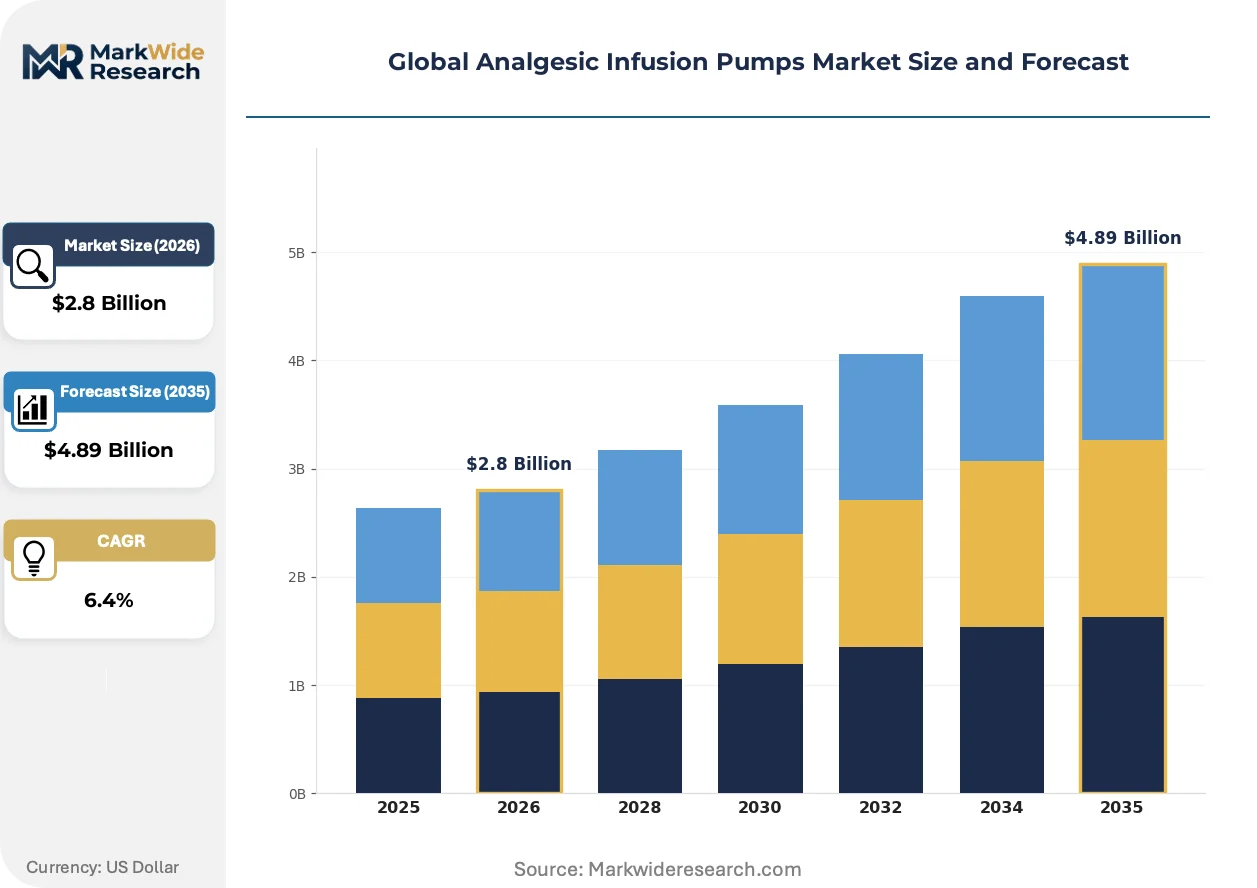
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient-Controlled, Elastomeric, Ambulatory, Volumetric Technology: Microprocessor Controlled, Disposable, Mechanical, Electronic Application Area: Postoperative Pain Relief, Cancer Pain, Chronic Pain Management, Emergency Care End User: Hospitals, Ambulatory Surgical Centers, Pain Clinics, Home Healthcare |
| Companies Covered | B. Braun Melsungen AG, Baxter International Inc., Fresenius Kabi AG, Medtronic plc, Terumo Corporation, Becton, Dickinson and Company, ICU Medical, Inc., Smiths Medical, CareFusion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Analgesic Infusion Pumps Market Shifts & Advancements
Connected device architectures are displacing standalone mechanical systems as the default specification in procurement tenders, with software-enabled safety features becoming the primary competitive differentiator rather than hardware reliability alone.
Closed-loop analgesia systems incorporating real-time respiratory rate monitoring are rewriting competitive requirements for high-acuity installations. Academic medical centers in the United States are piloting these platforms for post-surgical opioid administration. The technology is compressing liability exposure while commanding forty to sixty percent unit price premiums over conventional patient-controlled modules.
Japan's PMDA has implemented supplemental electromagnetic compatibility standards under revised Japanese Industrial Standards for medical electrical equipment. Foreign manufacturers face extended type approval timelines as domestic testing laboratory capacity constrains throughput. European and North American suppliers are responding by establishing captive regulatory affairs subsidiaries in Tokyo to accelerate documentation preparation.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, negotiating separate multi-year software maintenance agreements with cybersecurity patch guarantees. This shift is most pronounced in German university hospital networks, where chief information officers now hold veto authority over device selection based on interoperability certification status rather than clinical preference alone.
Global Analgesic Infusion Pumps Market Segmentation
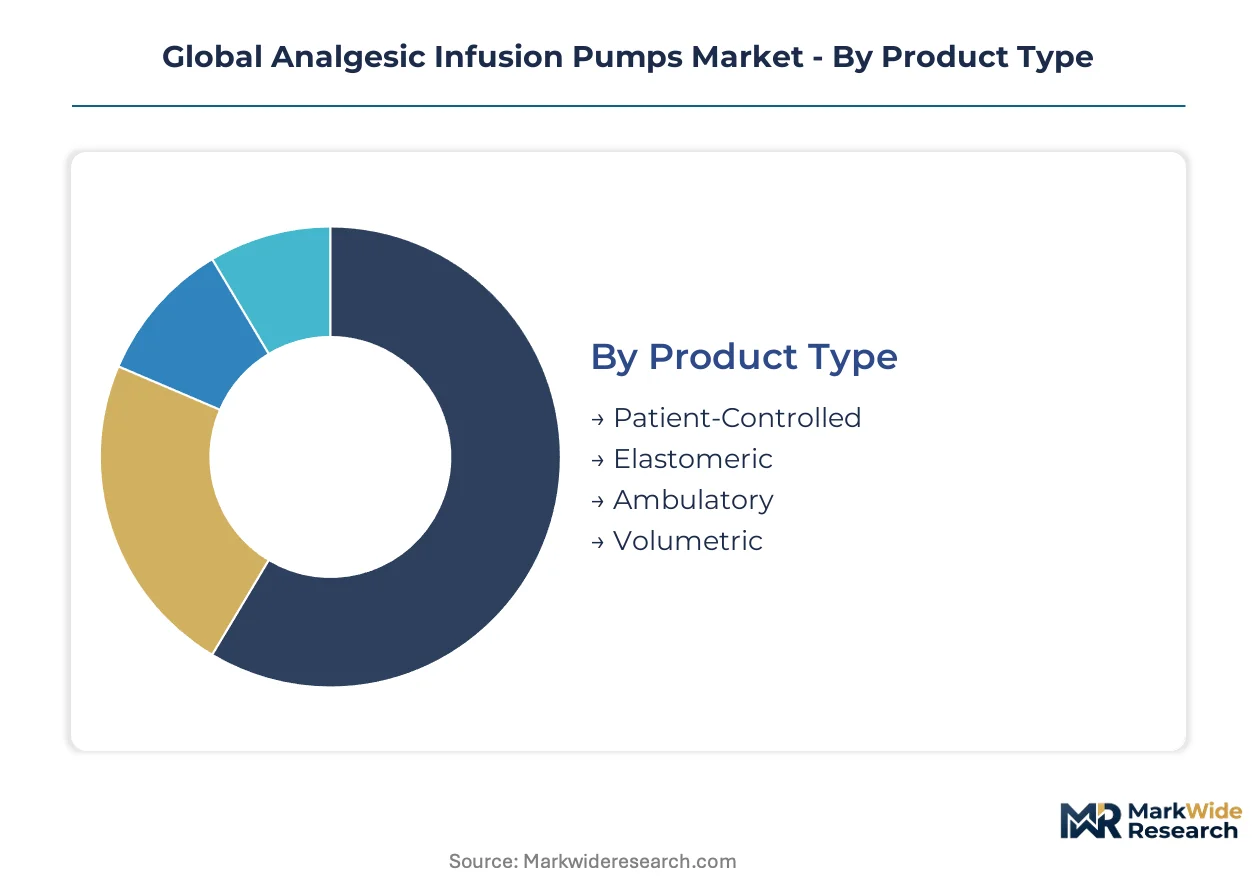
Segmentation in analgesic infusion pumps reveals how technology choices cascade through procurement hierarchies, with embedded connectivity requirements reshaping which configurations win in hospital formulary reviews versus home healthcare disposables.
Product Type:
Standalone devices dominate acute care installations where precision dosing and alarm integration justify capital expenditure, while embedded disposable systems penetrate cost-sensitive ambulatory channels.
- Patient-Controlled:Electronically programmable pumps with software interlocks enabling on-demand bolus delivery within clinician-set boundaries. Demand concentrates in United States academic medical centers where closed-loop respiratory monitoring integration commands premium positioning.
- Elastomeric:Balloon-powered disposable reservoirs delivering medication through calibrated flow restrictors without external power. German home healthcare agencies favor these for post-operative discharge protocols where capital equipment elimination reduces infection liability and logistics overhead.
- Ambulatory:Wearable electronic pumps designed for mobility during outpatient recovery. Japanese rehabilitation facilities specify these for cancer pain patients requiring continuous infusion during daily activities.
- Volumetric:Large-capacity pumps for extended-duration therapy in inpatient settings. United States oncology wards deploy these for multi-day chemotherapy adjuvant regimens requiring steady analgesic co-administration.
Volume placements concentrate in Patient-Controlled systems; the faster expansion belongs to Elastomeric disposables.
Technology:
Cost tier stratification separates recurring-revenue electronic platforms from single-use mechanical alternatives, with microprocessor architectures capturing margin pools through software validation services.
- Microprocessor Controlled:Software-driven flow regulation with programmable dose limits and event logging. Ambulatory surgical centers in France specify these for outpatient orthopedic procedures where documentation requirements meet reimbursement audit standards.
- Disposable:Single-use mechanical or elastomeric systems eliminating sterilization cycles. United Kingdom community nursing services adopt these for terminal cancer patients managed in residential settings.
- Mechanical:Spring or gravity-powered systems with fixed flow rates. Emergency departments in Spain retain these for short-duration analgesia where electronic infrastructure is unavailable.
- Electronic:Reusable electronic platforms with replaceable administration sets. German university hospitals negotiate multi-year software maintenance contracts separate from hardware procurement, shifting vendor relationships toward cybersecurity service models.
Procurement volume clusters in Electronic platforms; Disposable systems are climbing the fastest as home healthcare agencies eliminate capital maintenance burdens.
Application Area:
Clinical acuity determines device specification, with high-stakes postoperative applications demanding redundant safety architectures while chronic management prioritizes portability and patient adherence.
- Postoperative Pain Relief:Immediate recovery protocols following major surgery requiring titratable opioid delivery. United States hospitals install patient-controlled systems in surgical wards where respiratory depression monitoring integrates with central nursing stations.
- Cancer Pain:Long-term opioid and adjuvant therapy for malignant disease. Palliative care networks in Italy deploy ambulatory elastomeric pumps for home-based end-of-life pain management.
- Chronic Pain Management:Non-malignant persistent pain conditions requiring sustained infusion. Pain clinics in Australia combine electronic pumps with spinal cord stimulation trials for complex regional pain syndrome.
- Emergency Care:Rapid analgesia initiation in trauma and acute presentations. French emergency medical services carry mechanical syringe pumps for prehospital analgesia where device simplicity ensures reliability under field conditions.
Installed base value aggregates in Postoperative Pain Relief; Cancer Pain applications are gaining share fastest as population aging expands palliative care infrastructure.
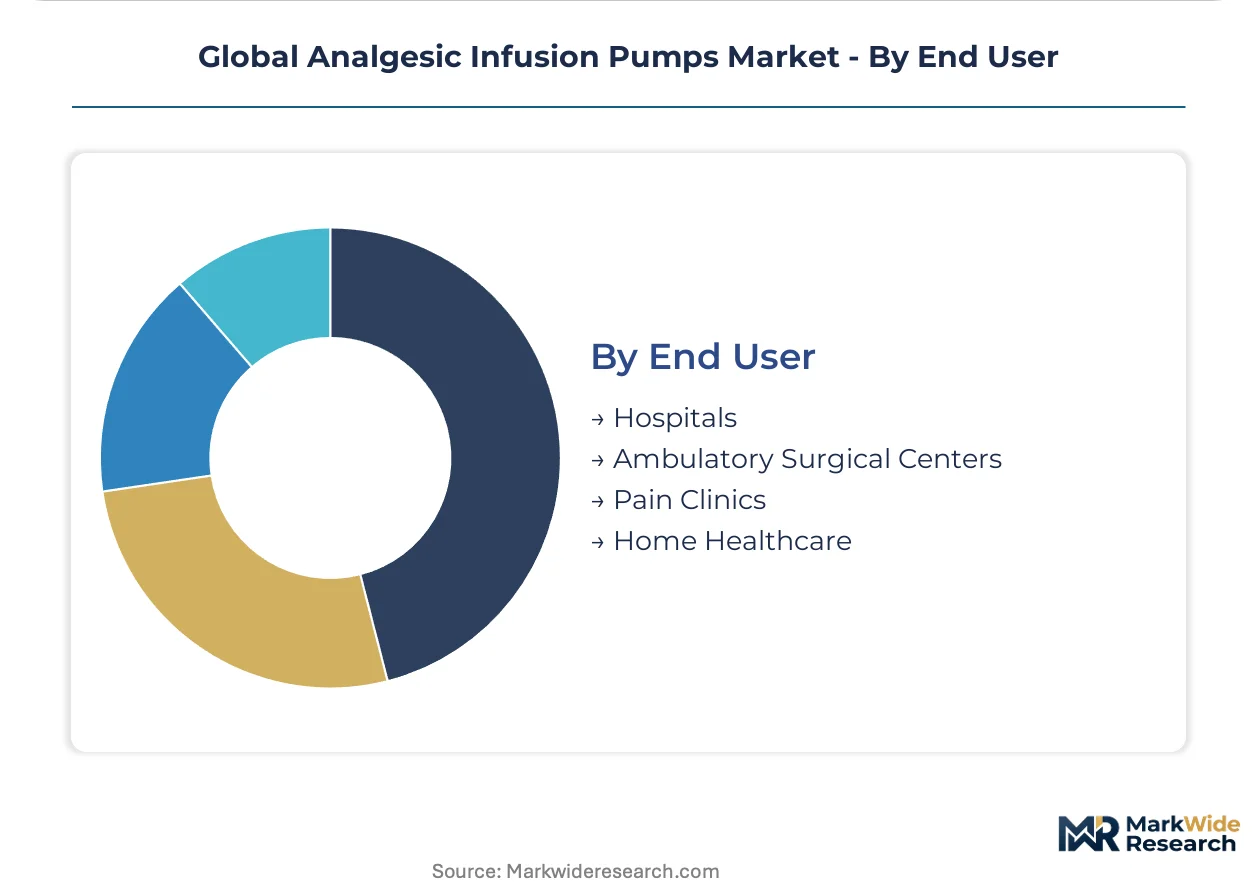
End User:
Customer type segmentation maps directly to procurement authority structures, with hospital pharmacy committees wielding formulary control distinct from home healthcare agency disposable purchasing.
- Hospitals:Integrated delivery networks with capital equipment committees and biomedical engineering departments. United States health systems standardize on single vendor platforms to simplify training and maintenance credentialing.
- Ambulatory Surgical Centers:Freestanding facilities performing same-day procedures with compressed recovery protocols. German outpatient surgery networks specify compact patient-controlled systems for orthopedic and gynecological cases.
- Pain Clinics:Specialized interventional practices managing complex chronic conditions. Japanese pain societies certify specific pump models for intrathecal drug delivery, creating de facto procurement standards.
- Home Healthcare:Community nursing services and hospice organizations managing patients outside institutional settings. United Kingdom district nursing contracts specify disposable elastomeric pumps to eliminate equipment retrieval logistics.
Capital expenditure concentrates in Hospitals; the steepest expansion trajectory belongs to Home Healthcare as reimbursement shifts favor early discharge and community-based pain management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-Saint Paul medical device corridor anchors North American infusion pump engineering, with regulatory affairs clusters concentrated near FDA headquarters in suburban Maryland and the Research Triangle Park compliance ecosystem.
United States
Ambulatory surgical center networks in Texas and Florida are installing patient-controlled analgesia systems to capture outpatient orthopedic volume migrating from inpatient settings. The FDA's evolving 510(k) pathway for software updates is extending premarket review timelines for connected device submissions. The Minneapolis-Saint Paul corridor houses concentrated biomedical engineering talent pools serving major device manufacturers with regulatory strategy and clinical validation services.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are standardizing on electronic platforms with multi-year software maintenance contracts negotiated separately from hardware procurement. The EU Medical Device Regulation mandates enhanced clinical evidence and EUDAMED post-market surveillance registration. The Baden-Württemberg precision manufacturing belt supplies flow sensor components and molded administration sets to domestic pump assemblers.
Japan
Rehabilitation facilities in the Kansai region specify portable ambulatory pumps for cancer pain patients requiring continuous infusion during daily activities. The PMDA applies supplemental Japanese Industrial Standards for electromagnetic compatibility and alarm fatigue mitigation that extend foreign manufacturer approval timelines. Tokyo-based regulatory affairs subsidiaries are expanding documentation preparation capacity to accelerate type approval throughput.
United Kingdom
Community nursing services in Greater London and the West Midlands are adopting disposable elastomeric pumps to eliminate equipment retrieval logistics for terminal cancer patients managed in residential settings. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit with transitional arrangements for EU-CE marked devices. The Cambridge-Oxford healthcare technology corridor incubates early-stage infusion monitoring startups.
France
Ambulatory surgical centers in the Île-de-France region specify microprocessor-controlled systems for outpatient orthopedic procedures where documentation requirements meet reimbursement audit standards. ANSM oversees national vigilance reporting and post-market surveillance with harmonized EU MDR implementation timelines. The Lyon biomedical cluster concentrates catheter material suppliers and sterilization service providers serving southern European pump distributors.
Global Analgesic Infusion Pumps Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered technology platforms, with integrated manufacturers maintaining captive component supply against specialized assemblers sourcing precision flow sensors from merchant foundries. The vendor base stratifies across three archetypes: diversified medical technology conglomerates with hospital formulary leverage, mid-scale regional specialists with elastomeric manufacturing depth, and emerging connectivity-focused developers targeting software-as-a-medical-device revenue streams. Dominant competitive moves include backward integration into precision molding and sensor calibration capabilities, alongside geographic expansion through regulatory affairs subsidiary establishment in Tokyo and Seoul.
Among diversified conglomerates, B. Braun Melsungen AG and Baxter International Inc. occupy positions defined by manufacturing scale and hospital supply chain integration. Fresenius Kabi AG exemplifies the mid-scale specialist archetype with concentrated presence in ambulatory and home healthcare channels. These three entities represent distinct strategic postures: vertically integrated European manufacturing, North American hospital formulary anchoring, and disposable-economics specialization for cost-constrained procurement environments.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Baxter International Inc. |
| Fresenius Kabi AG |
| Medtronic plc |
| Terumo Corporation |
| Becton, Dickinson and Company |
| ICU Medical, Inc. |
| Smiths Medical |
| CareFusion Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into precision molding and sensor calibration capabilities anchors competitive positioning for diversified manufacturers while compressing margin pools for assemblers sourcing from merchant suppliers. This structural divide concentrates pricing power among European and North American producers with captive component supply, forcing price-sensitive procurement tiers toward Asian contract manufacturers.
Pricing Analysis
Value-based pricing anchored to clinical outcomes and safety interlock reliability separates premium electronic platforms from commodity mechanical alternatives. Pricing stratifies across closed-loop respiratory monitoring systems, standard patient-controlled modules, and disposable elastomeric reservoirs based on software validation depth and cybersecurity certification tier. Cost compression in mechanical pump segments intensifies as German home healthcare agencies consolidate disposable purchasing through tender mechanisms. Hospital formulary committees exhibit lowest price sensitivity for anesthesia-critical care crossover applications, while emergency departments retain gravity-fed alternatives where capital budgets constrain electronic system penetration.
Supply Chain Analysis
Direct-to-hospital digital procurement channels handle demand from integrated delivery networks seeking real-time inventory visibility and same-day fulfillment capabilities. Component sourcing concentrates in Germany for precision flow sensors, China for microcontroller assembly, and Japan for electromagnetic compatibility testing infrastructure. Raw material dependencies span medical-grade elastomers for disposable reservoirs, biocompatible catheter polymers, and semiconductor-grade pressure transducers. Single-source vulnerability in East Asian foundry capacity for precision flow sensors creates production scheduling uncertainty. Distribution runs through specialized medical device distributors in France bypassing group purchasing organizations, alongside direct manufacturer relationships with United States health system capital equipment committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around software-enabled safety architectures as FDA cybersecurity validation backlogs and recurring compliance overhead force weaker hardware-only competitors toward exit or acquisition.
For Market Incumbents: Anchor formulary position through multi-year software maintenance contracts with cybersecurity patch guarantees, mirroring German university hospital procurement patterns. Deepen backward integration into precision molding capabilities to defend margin position against Asian contract manufacturers. Prioritize regulatory affairs subsidiary establishment in Tokyo to compress PMDA approval timelines and preempt domestic competitors in Japanese rehabilitation facility channels. For New Entrants and Emerging Players: Capture white-space opportunity in Japanese home healthcare where METI reimbursement reforms for post-operative pain management create first-mover advantages for portable elastomeric pump distributors. Target United Kingdom community nursing services adopting disposable systems to eliminate equipment retrieval logistics for terminal cancer patients. Build local service infrastructure as the primary go-to-market angle rather than competing on device specification alone. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale regional specialists with elastomeric manufacturing depth and established ambulatory care channel relationships, as diversified conglomerates seek disposable-economics capabilities. Long-term viability favors targets with regulatory clearance in multiple jurisdictions and recurring software validation revenue streams. Monitor FDA premarket submission queue lengths as the inflection indicator for connected device portfolio revenue recognition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Update Pathway Mastery | Compresses revenue recognition timelines for connected pump portfolios facing extended review queues. |
| CE Marking Pathway Optimization | Accelerates EUDAMED registration and EU MDR compliance for hospital formulary access. |
| Hospital System Partnership | Secures multi-year software maintenance contracts with German university network CIOs. |
| Software Companion Development | Enables closed-loop respiratory monitoring integration commanding premium positioning in academic medical centers. |
| Reimbursement Strategy | Aligns device specification with METI post-operative pain management reforms in Japanese home healthcare. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and PMDA approval databases, complemented by interviews with hospital biomedical engineers, ambulatory surgical center procurement managers, home healthcare agency directors, and medical device regulatory affairs specialists. Secondary validation drew from hospital procurement databases, group purchasing organization contract repositories, and CMS Medicare reimbursement schedules. Bottom-up triangulation across installed base estimates and replacement cycle analysis intersected with top-down market sizing from manufacturer revenue disclosures and distributor shipment data.
Segment-level projections across product type, technology platform, application area, and end user configuration were generated through the analytical framework spanning the projection horizon. CAGRs were derived from surgical volume recovery trajectories, ambulatory surgical center expansion rates, and home healthcare reimbursement policy shifts. Industry-specific forecast inputs incorporated FDA software update pathway evolution, EU MDR post-market surveillance implementation timelines, and Japanese electromagnetic compatibility standard revisions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor component supply volatility, cybersecurity validation backlog duration, and harmonized international software-as-a-medical-device classification developments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Pain Management Software Market
Pain Management
Cold Pain Therapy Market
Pain Management
Spine Pain Market
Pain Management
Cancer Pain Market
Pain Management
Pain Relief Oil Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Neuralgia Treatment Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Pain Management Therapeutics Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Topical Pain Relief Market
Pain Management
Provoked Vestibulodynia Treatment Market