
 Lumbosacral Radicular Pain Management Market | 2026-2036
Lumbosacral Radicular Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Lumbosacral Radicular Pain Management Market Foresight
Project finance for neuromodulation device trials is narrowing the field of companies capable of bringing spinal cord stimulation platforms through late-stage development. Medtronic plc leverages its integrated manufacturing footprint to sustain cost advantages across implantable pulse generator production. Boston Scientific Corporation competes through specialized radiofrequency ablation catheters that target lumbosacral nerve roots with enhanced precision. Abbott Laboratories anchors its position with rechargeable neurostimulation systems that reduce replacement surgery frequency for chronic radicular pain patients.
Lumbosacral radicular pain management encompasses pharmacologic, interventional, and surgical modalities directed at compressed or inflamed nerve roots emanating from the L1-S1 spinal segments, typically presenting with dermatomal pain distribution and measurable neurologic deficit. The primary commercial purpose centers on restoring functional mobility and delaying or avoiding operative decompression in degenerative spine conditions. Medications and interventional pain management command the largest current revenue pools, though spinal cord stimulation within the technology dimension represents the fastest-growing segment as device longevity improves and outpatient implantation protocols mature. Oral delivery mode retains dominant prescription volume for initial conservative management, while infusion systems capture premium pricing in refractory cases requiring intrathecal drug delivery.
FDA neuromodulation premarket review and ISO 14155 clinical investigation standards govern device commercialization timelines and data requirements for US market access, directly influencing R&D allocation across the competitive set. The Centers for Medicare & Medicaid Services national coverage determinations for spinal cord stimulation shape reimbursement-enabled demand volumes and site-of-service economics for implanting physicians. Stakeholders must monitor evolving FDA breakthrough device designations for closed-loop stimulation algorithms and corresponding CMS parallel review pathways that could compress time-to-payment for next-generation platforms.
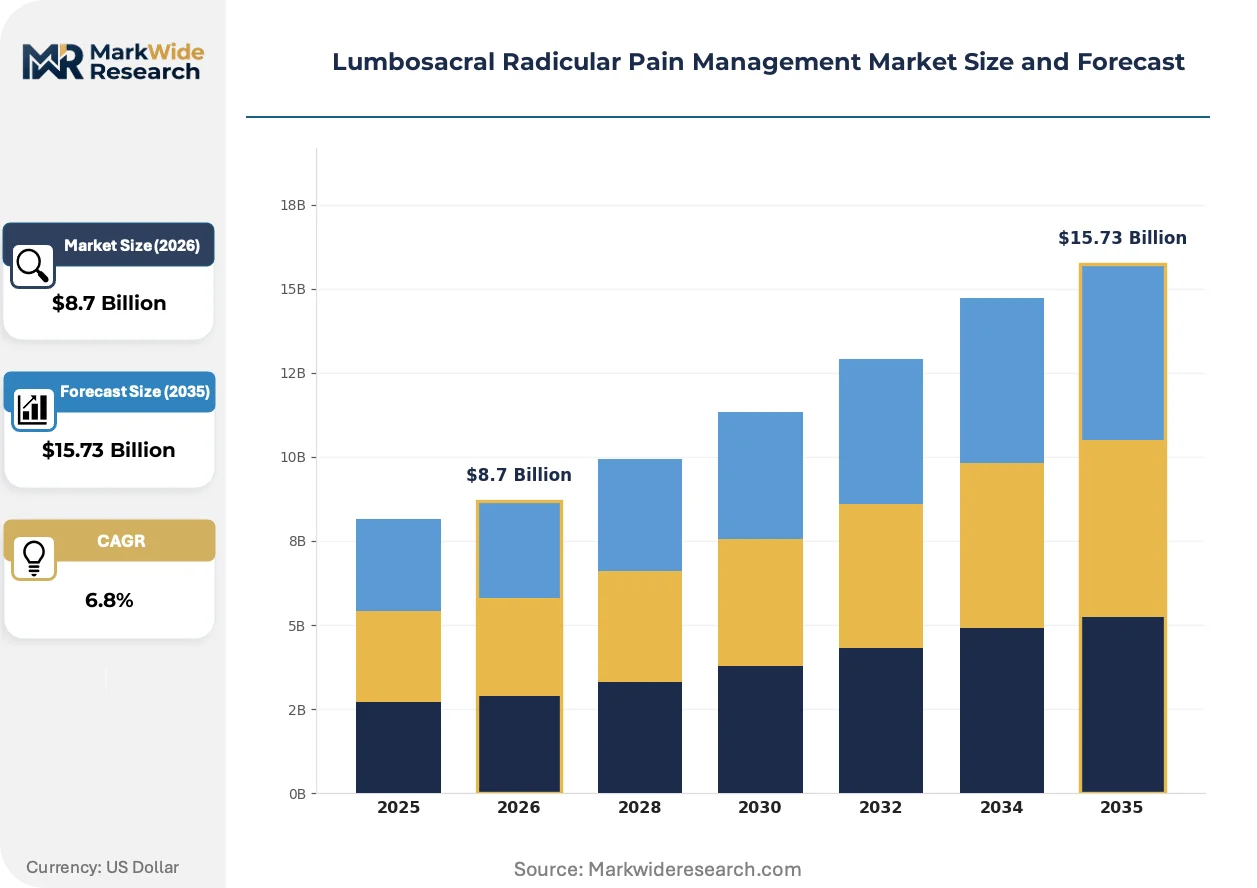
Market Dynamics
Medicare reimbursement compression is forcing site-of-service migration toward ambulatory surgical centers, while closed-loop spinal cord stimulation algorithms are collapsing the trial-to-implant conversion timeline from months to weeks.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement policies increasingly favor minimally invasive outpatient interventions over inpatient spinal fusion, accelerating procedure volume shifts toward pain clinics.
- Closed-loop neurostimulation:Adaptive stimulation algorithms that automatically adjust therapy delivery based on patient movement are expanding addressable populations beyond traditional spinal cord stimulation candidates.
- Pain clinic consolidation:United States-based interventional pain management practices are scaling procedure volumes as first-line surgical referrals decline across degenerative spine conditions.
Market Restraints
- Implantable pulse generator supply concentration:Manufacturing of rechargeable neurostimulation systems depends on a limited supplier base for specialized battery cells, creating vulnerability to input cost volatility.
- FDA premarket review timelines:Neuromodulation device clearance pathways impose extended clinical investigation requirements under ISO 14155 standards, compressing competitive windows for emerging manufacturers.
- Oral analgesic substitution:Extended-release opioid formulations and novel non-opioid pharmacologics retain strong formulary positioning for initial conservative management of radicular symptoms.
Strategic Opportunities
- Breakthrough device designation pathway:FDA parallel review mechanisms for next-generation closed-loop platforms could compress time-to-payment and accelerate commercial access.
- Radiofrequency ablation catheter advancement:Precision-targeted lumbosacral nerve root interventions represent underpenetrated expansion potential within ambulatory settings.
- Intrathecal drug delivery systems:Premium-priced infusion platforms for refractory cases offer white space as oral medication tolerance limits become more widely recognized.
Industry Challenges
- Implanting physician training pipelines:Fellowship programs in interventional pain medicine produce insufficient procedural specialists to match expanding device implantation demand.
- Reimbursement code fragmentation:Site-of-service economics vary dramatically across hospital outpatient departments, ambulatory surgical centers, and office-based labs, complicating financial modeling for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lumbosacral Radicular Pain Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physical Therapy, Surgical Procedures, Interventional Pain Management Delivery Mode: Oral, Injectable, Topical, Infusion End User: Hospitals, Pain Clinics, Rehabilitation Centers, Home Care Technology: Radiofrequency Ablation, Spinal Cord Stimulation, Transcutaneous Electrical Nerve Stimulation, Others |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Novartis AG, Sanofi, Eli Lilly and Company, GlaxoSmithKline plc, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lumbosacral Radicular Pain Management Market Shifts & Advancements
Neurostimulation hardware longevity and algorithm sophistication are converging to enable permanent implantation protocols that eliminate the traditional external trial phase entirely.
Rechargeable implantable pulse generators with multi-decade battery lifespans are collapsing the replacement surgery burden that previously limited spinal cord stimulation candidacy among younger chronic pain patients. Pain clinics in the United States are accelerating adoption of these platforms as outpatient implantation protocols mature and physician comfort with device programming expands. The structural consequence is a compression of total cost-of-ownership calculations that now favor neurostimulation over repeated surgical decompression in actuarial models.
EMA Medical Device Regulation requirements are tightening clinical evidence standards for spinal cord stimulation systems seeking European market access, mandating extended follow-up data that smaller manufacturers struggle to generate. This regulatory friction is consolidating competitive positioning around established players with integrated clinical affairs capabilities. The directive most acutely affects novel electrode array designs and wireless power transfer systems undergoing conformity assessment.
Episode-based payment bundles for lumbar spine procedures are reshaping how hospitals and ambulatory surgical centers evaluate interventional versus surgical radicular pain pathways. United States-based health systems are increasingly steering appropriate candidates toward spinal cord stimulation trials before authorizing decompression surgery, driven by total cost accountability. This behavioral shift concentrates demand volume within integrated delivery networks that can manage the full care continuum.
Lumbosacral Radicular Pain Management Market Segmentation
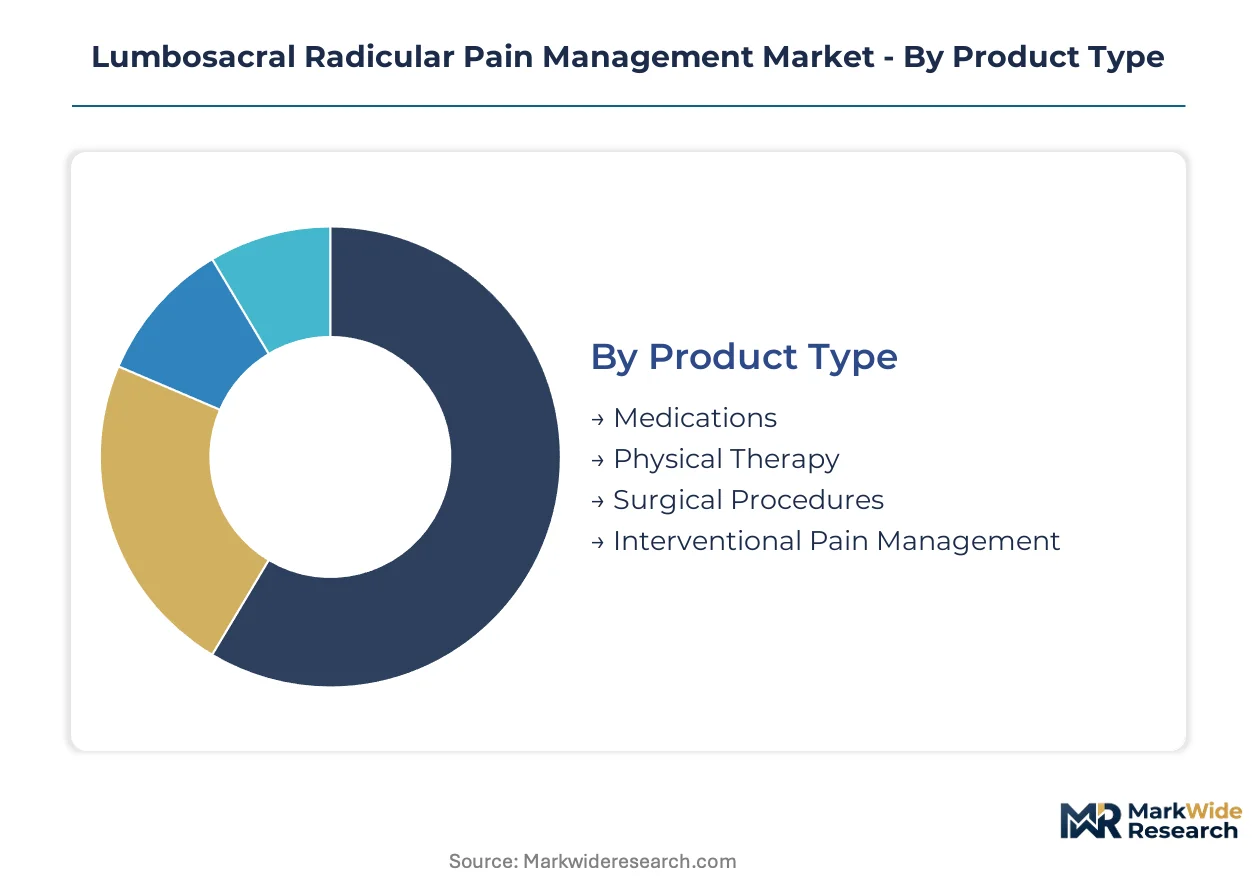
Segmentation in lumbosacral radicular pain management reflects divergent clinical workflows across conservative, interventional, and surgical pathways. Product type and technology dimensions capture the largest revenue pools, while delivery mode and end-user splits reveal shifting site-of-service economics.
Product Type:
Use-case spectrum spans acute symptom control through definitive operative correction, with reimbursement intensity rising across the progression.
- Medications:Oral analgesics, neuropathic agents, and anti-inflammatory compounds constitute first-line conservative management. Demand concentrates in United States primary care settings where CMS reimbursement policies favor pharmaceutical trials before procedural escalation.
- Interventional Pain Management:Epidural steroid injections, nerve blocks, and minimally invasive techniques target radicular symptoms without open surgery. Pain clinics in the United States are scaling these volumes as first-line surgical referrals decline across degenerative spine conditions.
- Physical Therapy:Structured rehabilitation protocols address mechanical dysfunction and neuromuscular stabilization.
- Surgical Procedures:Lumbar discectomy, laminectomy, and spinal fusion represent definitive decompression for refractory cases.
Established volume favors Medications; emerging adoption favors Interventional Pain Management.
Delivery Mode:
Cost tier stratification separates high-volume oral prescriptions from premium-priced infusion systems requiring specialized infrastructure.
- Oral:Tablets and capsules dominate initial prescription volume for radicular pain, with extended-release formulations capturing maintenance therapy. United States retail pharmacy channels retain dominant fulfillment share for conservative management protocols.
- Infusion:Intrathecal drug delivery systems enable direct cerebrospinal administration for refractory cases. Pain clinics with ambulatory surgical center attachments are expanding pump implantation as oral tolerance limits become more widely recognized.
- Injectable:Parenteral corticosteroids and local anesthetics support interventional procedures.
- Topical:Transdermal patches and localized preparations address superficial symptom clusters.
Oral retains volume leadership; infusion gains share fastest in refractory case management.
End User:
Site-of-service migration is compressing hospital outpatient revenue as procedures shift toward specialized ambulatory environments.
- Pain Clinics:Dedicated interventional pain practices combine diagnostic expertise with procedural capability for radicular conditions. United States-based clinics are consolidating through private equity investment to capture episode-based payment bundles.
- Hospitals:Academic medical centers and community hospitals retain complex surgical caseloads requiring inpatient infrastructure. CMS reimbursement compression is forcing site-of-service migration toward ambulatory surgical centers for appropriate candidates.
- Rehabilitation Centers:Post-acute facilities manage functional recovery following intervention or surgery.
- Home Care:Remote monitoring and self-administered therapies support chronic maintenance populations.
Pain Clinics capture procedure volume expansion; Hospitals retain surgical complexity premiums.
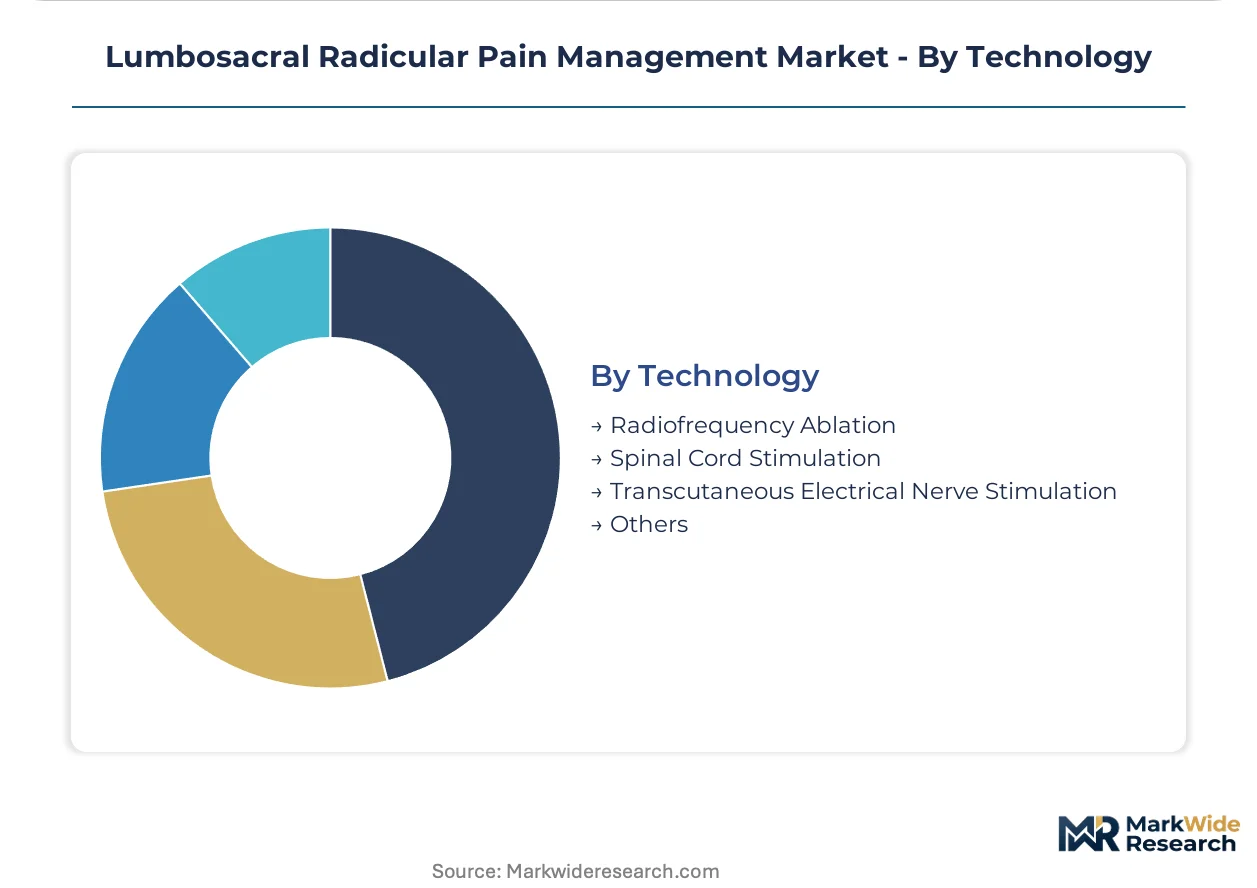
Technology:
Technology maturity separates established neuromodulation platforms from emerging closed-loop architectures with algorithmic differentiation.
- Spinal Cord Stimulation:Implantable pulse generators with epidural electrode arrays deliver electrical impulses to modulate pain signaling. Rechargeable systems with multi-decade battery lifespans are collapsing replacement surgery burden in United States pain clinics.
- Radiofrequency Ablation:Thermal lesioning of lumbosacral nerve roots provides durable analgesia for facet-mediated and radicular pain. Precision-targeted catheter designs from Boston Scientific and others are expanding ambulatory procedure penetration.
- Transcutaneous Electrical Nerve Stimulation:Non-invasive surface stimulation offers conservative neuromodulation without implantation risk.
- Others:Emerging modalities include dorsal root ganglion stimulation and peripheral nerve field stimulation.
Spinal Cord Stimulation commands premium pricing; Radiofrequency Ablation shows steepest expansion trajectory in ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement compression and ambulatory surgical center migration policies in the United States are accelerating procedure volume shifts toward minimally invasive interventions. European regulatory tightening under EMA Medical Device Regulation is consolidating competitive positioning around established clinical affairs capabilities. Asian markets are expanding interventional pain infrastructure as chronic disease burdens rise.
United States
Pain clinic consolidation and private equity investment are scaling interventional procedure volumes as first-line surgical referrals decline. CMS national coverage determinations increasingly favor outpatient spinal cord stimulation over inpatient fusion, reshaping site-of-service economics. The Greater Boston and Pacific Northwest clusters concentrate rechargeable neurostimulation system development and physician training programs.
Germany
Episode-based payment bundles for lumbar spine procedures are steering appropriate candidates toward neurostimulation trials before surgical authorization. EMA Medical Device Regulation mandates extended follow-up data for conformity assessment, favoring manufacturers with integrated clinical affairs. The Baden-Württemberg industrial corridor anchors precision catheter manufacturing for radiofrequency ablation systems.
Japan
Aging demographics and degenerative spine prevalence are expanding addressable populations for implantable pain management devices. PMDA review timelines and reimbursement negotiations shape commercial access for closed-loop stimulation platforms. The Kanto region around Tokyo concentrates academic medical center adoption of next-generation neuromodulation protocols.
United Kingdom
NICE technology appraisals and NHS procurement frameworks are standardizing interventional pain pathways across integrated care systems. The country's national pharmaceutical regulator maintains stringent evidence requirements for novel drug-device combinations. London and the Southeast cluster specialist pain services and private ambulatory surgical center investment.
Australia
TGA approval pathways and private health insurance reimbursement structures determine commercial viability for imported spinal cord stimulation systems. Remote monitoring capabilities are addressing geographic dispersion of chronic pain patients across vast territories. New South Wales and Victoria concentrate interventional pain fellowship training and device implantation volume.
Lumbosacral Radicular Pain Management Market Competitive Landscape
On the supply side, the industry is consolidating around diversified medtech conglomerates with integrated manufacturing footprints and specialized pain management divisions. Strategic archetypes span rechargeable neurostimulation platform developers, precision interventional catheter specialists, and pharmaceutical-neuromodulation hybrid portfolios. Dominant competitive moves include vertical integration into specialized battery cell supply and strategic partnerships with ambulatory surgical center networks.
Within the diversified medtech tier, Medtronic plc, Abbott Laboratories, and Boston Scientific Corporation exemplify scale-driven competitive positioning. Medtronic plc anchors integrated manufacturing capabilities across implantable pulse generator production. Abbott Laboratories occupies a position within rechargeable neurostimulation system development. Boston Scientific Corporation represents precision-targeted interventional catheter specialization for nerve root procedures.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| Sanofi |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
The Greater Boston medical device cluster concentrates rechargeable neurostimulation system manufacturing, where capacity constraints at specialized battery cell foundries translate directly into pricing power for implantable pulse generator OEMs serving United States pain clinics.
Pricing Analysis
Certification level creates the primary spread between FDA-cleared and CE-marked-only devices, with three-tier pricing structure across premium, standard, and economy levels anchoring procurement decisions. Price differentiation rests on battery longevity specifications and algorithm sophistication, with United States hospital purchasing committees showing highest sensitivity to total cost-of-ownership calculations. Cost compression in standard-tier radiofrequency ablation catheters is intensifying because of Asian contract manufacturing expansion.
Supply Chain Analysis
Specialized lithium-ion battery cells for implantable devices draw from manufacturing concentrated in Japan, South Korea, and China, with electrode array fabrication tethered to precision machining capabilities in Germany and Switzerland. Raw material dependencies span medical-grade titanium, platinum-iridium alloys, and biocompatible polymers. Single-source vulnerability persists for closed-loop stimulation ASICs. Distribution runs through GPO-negotiated contracts with integrated delivery networks and ambulatory surgical center chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lumbosacral radicular pain management market rewards players who control scarce capabilities in closed-loop algorithm development and specialized battery chemistry, as fellowship-trained interventional pain physicians remain insufficient to match expanding device implantation demand.
For Market Incumbents: Pre-empt competitive erosion by securing captive supply of next-generation solid-state battery cells through backward integration into Japanese and South Korean materials suppliers. Accelerate FDA breakthrough device designation applications for adaptive stimulation algorithms before CMS parallel review pathways mature. Threat substitution from extended-release oral analgesics with novel mechanisms demands sustained clinical evidence generation to defend procedural volumes.
For New Entrants and Emerging Players: Australian and Canadian pain clinic networks present underpenetrated expansion corridors where reimbursement frameworks for spinal cord stimulation remain less consolidated than United States markets. Target ambulatory surgical center partnerships in secondary United States metro areas where physician-owned facilities lack GPO negotiating leverage. Go-to-market execution should emphasize remote monitoring capabilities that address geographic dispersion of chronic pain populations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among neuromodulation platform developers with rechargeable implantable pulse generator portfolios that collapse replacement surgery frequency. Long-term viability across the analysis window favors acquisition targets with integrated clinical affairs capabilities spanning FDA and EMA regulatory pathways. Signal to monitor: CMS national coverage determination expansions for closed-loop stimulation that would accelerate time-to-payment for next-generation platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses premarket review timelines for closed-loop algorithms under FDA-CMS parallel review. |
| Rechargeable IPG Platform Development | Multi-decade battery lifespans reduce replacement burden and expand candidacy in younger chronic pain patients. |
| Ambulatory Surgical Center Partnership | Captures site-of-service migration driven by Medicare reimbursement compression on hospital outpatient departments. |
| Specialized Battery Cell Supply Agreement | Secures input cost stability for implantable pulse generators against lithium-ion materials volatility. |
| Interventional Pain Fellowship Sponsorship | Addresses implanting physician pipeline constraints that limit procedure volume expansion. |
Research Methodology
Cross-validation between primary interviews with interventional pain physicians, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) filings, CMS Medicare claims data, and hospital procurement databases anchors the qualitative findings. Bottom-up modeling of implantable device shipments and top-down reconciliation against manufacturer revenue disclosures ensures dimensional consistency.
Calibration against historical adoption curves for spinal cord stimulation and radiofrequency ablation procedures informs the projection framework across product type, technology, delivery mode, and end-user segments. CAGRs derive from segmented growth rate analysis incorporating reimbursement policy trajectories, regulatory approval timelines, and physician training pipeline constraints specific to neuromodulation device markets.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, FDA premarket review staffing levels, or lithium-ion battery materials costs would shift the trajectory. Cross-checking against CMS national health expenditure projections for outpatient spinal procedures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Arthralgia Management Market
Pain Management
Palliative Care Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Bone Pain Treatment Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Migraine Management Market
Pain Management
Global Chiropractic Care Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Global Morphine Market
Pain Management
Ketorolac Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market