
 China Tea Market | 2026-2036
China Tea Market Size, Share, and Industry Trends Forecast 2026-2036
China Tea Market Intelligence
A capital-intensity divergence between plantation-owning incumbents and asset-light new retail brands is unwinding traditional margin structures in the China tea sector. Unilever PLC leverages its global procurement networks to sustain bulk commodity positions across multiple provinces. Heytea competes through direct-store ownership in tier-one cities, while Chagee anchors its expansion in lower-tier markets with standardized milk-tea formats. Mixue Ice Cream & Tea controls extreme price points through captive supply chains that few rivals can replicate.
China tea comprises processed leaves from Camellia sinensis, graded by oxidation level, polyphenol content, and geographic origin indicators that determine brewing parameters and sensory profiles. Green tea dominates volume through everyday household consumption, while oolong tea commands premium positioning in gift channels and ceremonial settings. Specialty stores capture the highest margin pools per transaction, though online retailers are displacing traditional wholesale layers in tier-two and tier-three cities.
SAMR enforces GB standards for pesticide maximum residue limits and labeling transparency, while the Ministry of Agriculture and Rural Affairs administers geographical indication protections for heritage production zones. These frameworks elevate compliance costs for smallholders but create market access barriers that favor scaled processors with in-house testing laboratories. Stakeholders must monitor how dual carbon goals reshape energy-intensive withering and drying operations across traditional manufacturing clusters.
Market Dynamics
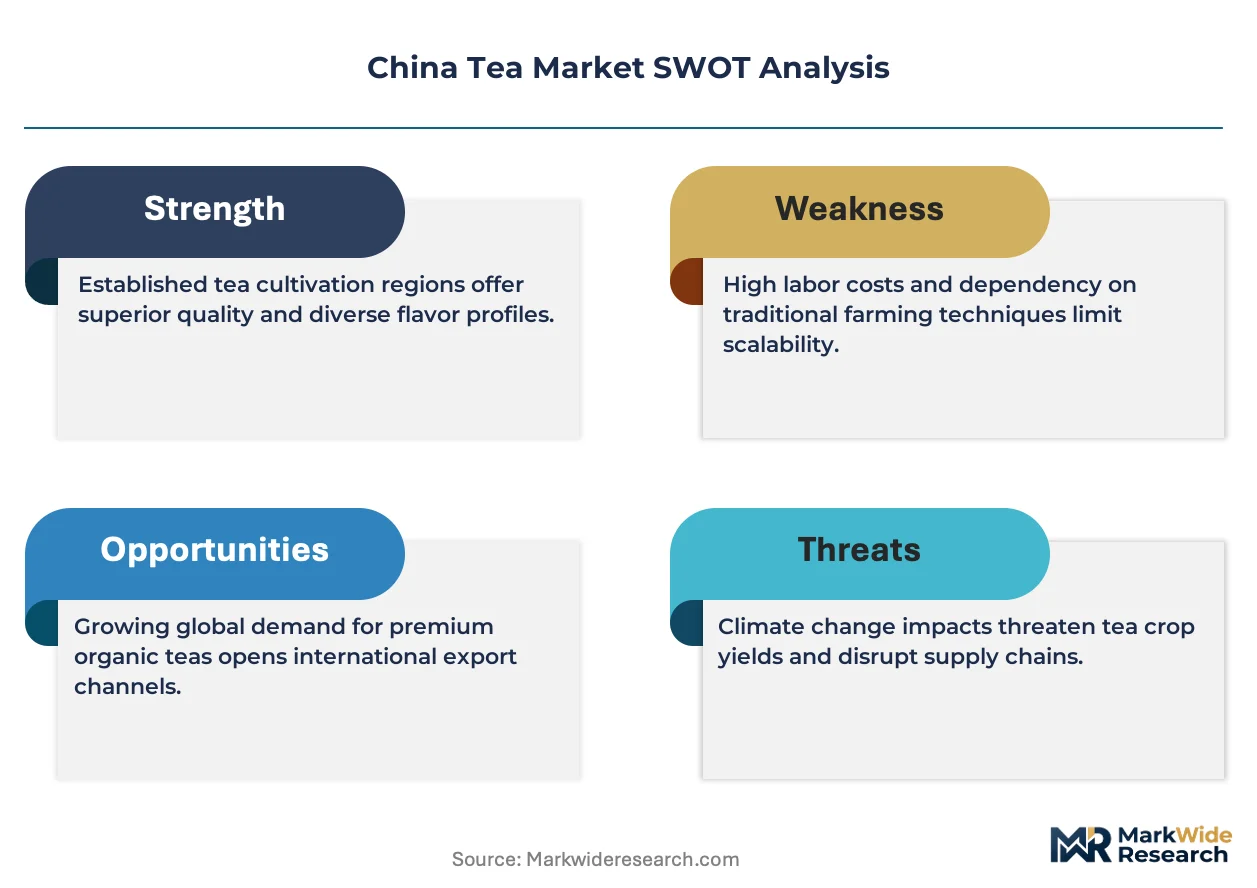
Dual carbon goals from China's MEE are forcing energy-intensive withering and drying operations across Fujian and Zhejiang manufacturing clusters to retool or relocate, compressing margins for traditional processors while creating compliance moats for scaled operators with captive renewable energy.
Growth Catalysts
- Geographic Indication Protections:The Ministry of Agriculture and Rural Affairs administers heritage zone designations that anchor premium positioning for terroir-specific oolong and green tea varieties, elevating price realization for certified producers.
- Younger Consumer Formats:Milk-tea and ready-to-drink innovations are pulling eighteen-to-thirty-five-year-old demographics into daily consumption habits previously concentrated among older generations.
- GB Standard Harmonization:SAMR's tightening maximum residue limits for agricultural inputs are consolidating processing capacity toward laboratory-equipped facilities capable of batch-level testing.
Market Restraints
- Input Cost Volatility:Fertilizer and labor expenses in Anhui and Yunnan growing regions fluctuate with seasonal migration patterns and input material pricing tied to energy markets.
- Supply Concentration Risk:Premium raw leaf procurement depends on smallholder networks in specific mountain microclimates where aging farmer populations constrain volume scalability.
- Substitution Threat:Coffee consumption in Shanghai and Beijing urban centers captures morning ritual occasions previously dominated by tea, particularly among white-collar employment segments.
Strategic Opportunities
- Lower-Tier City Expansion:Chagee's standardized format penetration into tier-three and tier-four municipalities demonstrates scalable unit economics for beverage-first retail concepts beyond saturated coastal markets.
- Direct-to-Consumer Channels:Live-streaming commerce on Douyin and Xiaohongshu is displacing traditional wholesale layers, enabling heritage brands to capture margin pools previously allocated to distributor networks.
- Carbon-Neutral Certification:Provincial dual carbon implementation timelines create first-mover advantages for processors investing in solar-drying infrastructure and regenerative cultivation partnerships.
Industry Challenges
- Skill Transfer Gap:Traditional hand-rolling and roasting techniques concentrated in generational master craftspeople lack structured apprenticeship pipelines, threatening quality consistency for heritage-grade production.
- Capex Intensity:In-house testing laboratories and renewable energy retrofits demand capital deployment that fragments competitive position between plantation-owning incumbents and asset-light new retail brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Tea Market |
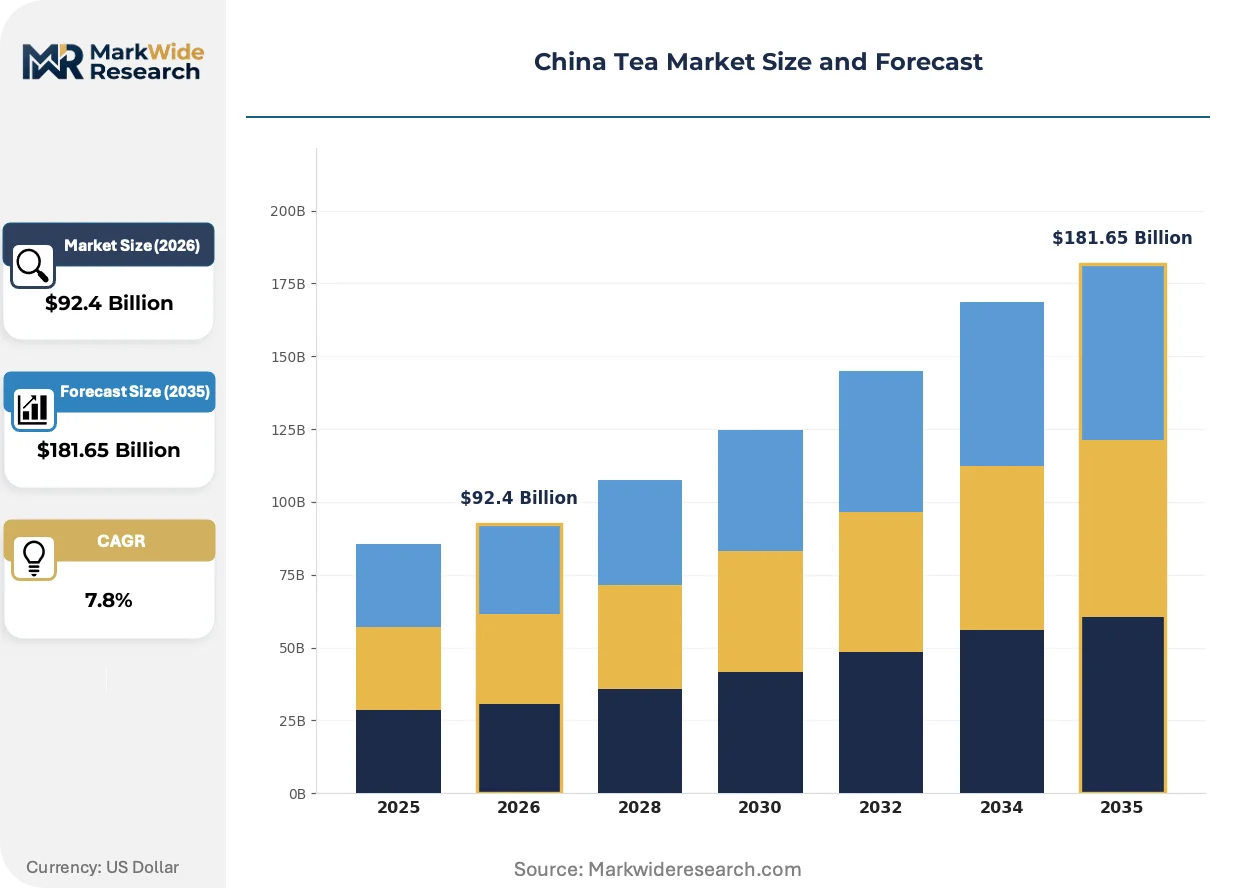
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $181.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Oolong Tea, White Tea Packaging Type: Bulk, Tea Bags, Loose Leaf, Instant Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Direct Sales End User: Households, Restaurants, Cafés, Hotels |
| Companies Covered | Twinings, Bigelow Tea, Unilever PLC, Mixue Ice Cream & Tea, Heytea, PepsiCo Inc, Dilmah, Chagee, Starbucks Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Tea Market Strategic Shifts & Innovations
Digital traceability systems and automated sorting technologies are compressing traditional quality-assurance layers while regulatory pressure on carbon intensity reshapes manufacturing geography across eastern and southwestern production belts.
Near-infrared spectroscopy coupled with AI-driven leaf grading is displacing manual sensory evaluation in large-scale processing facilities. Major exporters to European markets are adopting these systems to preempt EFSA scrutiny on consistency claims. The technology is displacing quality-control employment structures that previously absorbed seasonal labor surges.
GB standards for pesticide maximum residue limits are tightening on an accelerated review cycle under SAMR coordination with agricultural authorities. Smallholders in Zhejiang face compliance cost escalation that favors cooperative aggregation models. Premium gift-channel processors are responding by vertically integrating into controlled cultivation zones with documented input histories.
Concentration of beverage retail in tier-one cities is fragmenting as operator economics push format innovation toward smaller-footprint, take-away-dominant models. Heytea's direct-store ownership in Shanghai and Shenzhen is being displaced by franchised kiosk concepts in Chengdu and Xi'an that reduce rent exposure. This rotation is most visible in provincial capitals where commercial real estate costs remain sub-metropolitan but youth density supports throughput.
China Tea Market Segmentation
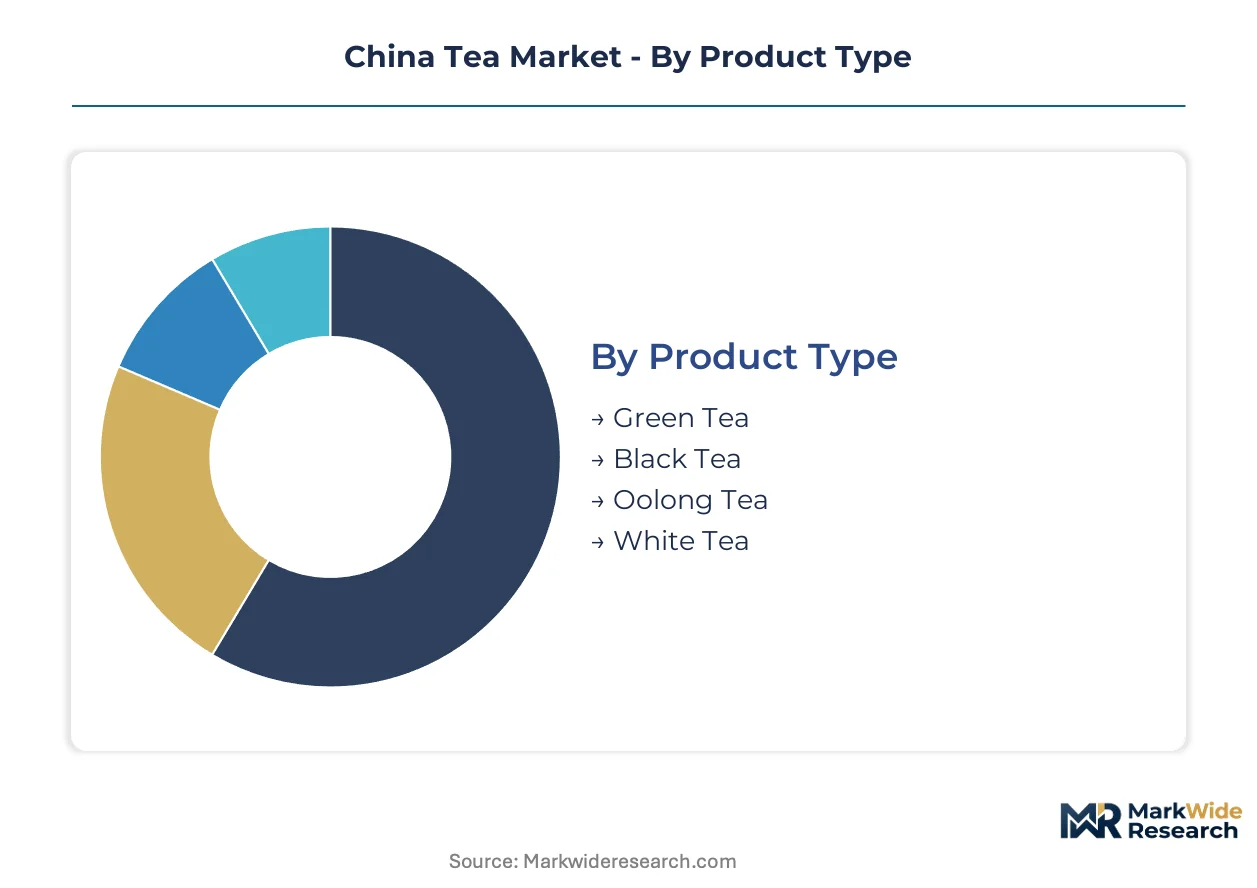
Segmentation in the China tea market reveals distinct channel economics and margin architectures. Product type determines procurement patterns, while packaging format and distribution channel dictate final price realization and consumer access.
Product Type:
Channel-mix varies sharply across oxidation levels, with green tea flowing through mass retail and oolong commanding specialty store premiums.
- Green Tea:Unoxidized leaves retain high polyphenol content and dominate household consumption volumes through supermarket and e-commerce channels. Zhejiang province anchors supply, where heritage terroirs support both commodity bulk sales and premium Longjing positioning in gift channels.
- Oolong Tea:Semi-oxidized varieties require controlled withering and roasting protocols that concentrate production in Fujian's Wuyi and Anxi microclimates. Partial oxidation creates aromatic complexity that commands ceremonial and corporate gifting price points through specialty stores and direct sales networks.
- Black Tea:Fully oxidized leaves from Yunnan and Anhui provinces serve export markets and domestic breakfast consumption. Standardized processing enables scale economies that black tea leverages in foodservice bulk supply.
- White Tea:Minimal processing preserves delicate flavor profiles that attract health-positioned consumers in tier-one cities. Fuding county in Fujian controls geographic indication supply, constraining volume scalability.
By volume, green tea leads. By growth pace, oolong is ahead in premium channel expansion.
Packaging Type:
Cost tier stratification separates convenience-oriented formats from heritage presentation layers that capture ceremonial occasions.
- Loose Leaf:Traditional presentation retains highest margins in specialty retail and direct-to-consumer channels. Tea masters and heritage brands in Hangzhou and Xiamen control this tier through provenance storytelling and sensory evaluation services.
- Tea Bags:Standardized portioning dominates office and hospitality procurement, with Unilever's procurement networks supplying bulk positions. Convenience positioning limits price elasticity but secures institutional volume contracts.
- Bulk:Unpackaged leaves flow through wholesale layers to restaurants and processors, where price transparency compresses margins. Anhui and Yunnan sourcing regions concentrate this lowest-cost tier.
- Instant:Soluble and ready-to-drink formats target younger demographics through convenience retail and e-commerce. Heytea and Chagee format innovations are accelerating this segment's channel penetration.
By volume, bulk leads. By margin capture, loose leaf is expanding most quickly.
Distribution Channel:
Customer type concentration shapes channel investment, with households fragmenting across digital touchpoints while foodservice demands reliable supply contracts.
- Online Retailers:Douyin live-streaming and Tmall flagship stores displace traditional wholesale layers, enabling heritage brands to capture margin pools previously allocated to distributor networks. Xiaohongshu community commerce accelerates trial among twenty-five-to-thirty-five-year-old urban consumers.
- Specialty Stores:Tea houses and boutique retailers in Shanghai and Beijing provide sensory evaluation and brewing education that justifies premium pricing. This channel captures highest per-transaction values but faces rent pressure in core districts.
- Supermarkets:Mass retail chains in tier-two and tier-three cities standardize green tea and black tea accessibility. Private label expansion by RT-Mart and Yonghui is compressing branded processor margins.
- Direct Sales:Corporate gifting accounts and plantation tourism create bypass routes for certified heritage producers. Fujian and Zhejiang producers with geographic indication status leverage this channel for price realization.
By volume, supermarkets lead. By channel shift velocity, online retailers are gaining share fastest.
End User:
Application maturity separates daily consumption rituals from ceremonial and commercial service occasions.
- Households:Daily brewing in Zhejiang, Fujian, and Anhui provinces sustains baseline demand for green and oolong varieties. Aging demographics in traditional tea-drinking regions constrain per-capita growth, while younger consumers shift toward milk-tea formats.
- Cafés:Beverage-first retail concepts in Chengdu, Xi'an, and Changsha demonstrate scalable unit economics for standardized milk-tea and fruit-tea innovations. Chagee's tier-three and tier-four penetration anchors this segment's expansion trajectory.
- Restaurants:Foodservice procurement demands consistent supply and price stability, favoring bulk black tea and standardized green tea contracts. Cost pressure limits premium positioning in this channel.
- Hotels:Hospitality gifting and in-room service create seasonal demand spikes for presentation-grade packaging. Five-star properties in Shanghai and Beijing source certified heritage varieties for guest experience differentiation.
By volume, households lead. By growth pace, cafés show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Chinese provinces diverge sharply between heritage ceremonial markets in coastal provinces and milk-tea adoption corridors in interior cities. Zhejiang households maintain daily loose-leaf brewing rituals, while Sichuan and Hunan younger demographics drive beverage-retail throughput. This geographic split shapes procurement priorities and channel investment strategies for processors and retailers alike.
Zhejiang Province
Hangzhou and Shaoxing anchor domestic premium green tea consumption through Longjing heritage terroirs. SAMR enforces GB standards for pesticide residue limits that elevate testing costs for smallholders in West Lake production zones. Cooperative aggregation models in Lin'an and Anji are consolidating processing capacity to meet laboratory-equipped compliance thresholds.
Fujian Province
Wuyi Mountain and Anxi microclimates command ceremonial oolong price premiums through geographic indication protections administered by the Ministry of Agriculture and Rural Affairs. Xiamen specialty retailers provide sensory evaluation services that justify loose-leaf margins. Dual carbon goals from MEE are forcing energy-intensive roasting operations toward solar-drying retrofits or relocation.
Guangdong Province
Guangzhou and Shenzhen beverage retail density supports the highest concentration of milk-tea outlets nationally. Younger consumer formats pull eighteen-to-thirty-five-year-old demographics into daily consumption previously concentrated among older generations. Chagee and Heytea format innovations are accelerating penetration through franchised kiosk concepts that reduce rent exposure in core districts.
Sichuan Province
Chengdu's lower commercial real estate costs relative to coastal metros enable scalable unit economics for beverage-first retail concepts. Provincial tea culture merges with standardized milk-tea formats to create hybrid consumption occasions. Chongqing's parallel growth corridor demonstrates replicable expansion templates for tier-three and tier-four municipal penetration.
Yunnan Province
Pu'er and Xishuangbanna aging farmer populations constrain volume scalability for premium raw leaf procurement. The province's black tea and pu'er production serves export markets and domestic breakfast consumption through standardized processing scale economies. Input cost volatility in fertilizer and labor expenses fluctuates with seasonal migration patterns tied to energy markets.
China Tea Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with plantation-owning incumbents competing against asset-light new retail brands for margin capture. Unilever PLC leverages global procurement networks to sustain bulk commodity positions across multiple provinces. Three strategic archetypes dominate: heritage processors with geographic indication control, beverage-retail format innovators, and multinational FMCG operators with institutional supply contracts. Competitive moves concentrate on direct-store ownership versus franchised expansion, and on backward integration into controlled cultivation zones versus outsourced procurement.
Among multinational operators, Unilever PLC and PepsiCo Inc exemplify scale-driven commodity positioning through institutional and retail channel dominance. Within the new retail tier, Heytea and Chagee occupy contrasting geographic vectors—direct-store ownership in tier-one cities versus standardized franchise penetration in lower-tier markets. Mixue Ice Cream & Tea represents extreme price-point control through captive supply chains that few rivals can replicate. These named entities anchor archetype discussions without prescribing specific strategic actions or financial positions.
| Leading Market Players |
|---|
| Twinings |
| Bigelow Tea |
| Unilever PLC |
| Mixue Ice Cream & Tea |
| Heytea |
| PepsiCo Inc |
| Dilmah |
| Chagee |
| Starbucks Corp |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Fujian oolong processors and heritage zone cooperatives lock in both raw leaf access and price visibility across multi-year harvest cycles. These arrangements insulate certified producers from spot market volatility in Anhui and Yunnan while embedding GB standard compliance costs into baseline pricing structures.
Pricing Analysis
After-sales service revenue from brewing education and sensory evaluation drives lifetime value for Hangzhou heritage brands. Three-tier pricing structure across premium Longjing, standard green tea, and economy bulk separates gift-channel ceremonial positioning from household consumption tiers. Cost compression in economy bulk stems from supermarket private label expansion by RT-Mart and Yonghui. Household consumers in tier-two cities show highest price sensitivity, while corporate gifting accounts in Beijing demonstrate lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from Yunnan mountain microclimates to Guangdong processing hubs fluctuate with seasonal migration patterns and fuel pricing tied to energy markets. Raw leaf procurement draws from smallholder networks in Zhejiang, Fujian, and Anhui provinces. Single-source vulnerability concentrates in Fuding county white tea production where geographic indication constraints limit alternative sourcing. Distribution runs through cooperative aggregation models that consolidate laboratory-equipped testing capacity for SAMR compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward beverage-retail chains as Chagee and Heytea consolidate procurement volumes across tier-one through tier-four expansion, fragmenting traditional processor pricing leverage.
For Market Incumbents: Fortify heritage zone control through backward integration into controlled cultivation with documented input histories. Invest in solar-drying infrastructure to preempt MEE dual carbon enforcement in Fujian manufacturing clusters. Certification moats around geographic indication status defend against asset-light new retail brands capturing margin pools through franchised kiosk expansion. For New Entrants and Emerging Players: White-space in tier-three and tier-four municipal beverage retail offers scalable unit economics below coastal rent thresholds. Live-streaming commerce infrastructure on Douyin and Xiaohongshu remains under-deployed by traditional processors, creating direct-to-consumer bypass routes. Anchor go-to-market through standardized milk-tea formats that merge provincial tea culture with convenience positioning. For Investors and Strategic Acquirers: Capital is best deployed toward plantation-owning processors with captive renewable energy and in-house testing laboratories across the analysis window. Acquisition targets combine geographic indication certifications with cooperative aggregation models that absorb smallholder compliance costs. Watch for MEE provincial implementation timelines as inflection signals for carbon-neutral certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Cultivation | Heritage zone processors secure GB-compliant input documentation for SAMR batch testing requirements. |
| Solar-Drying Infrastructure Deployment | Fujian roasting operations preempt MEE dual carbon enforcement while creating compliance moats. |
| Direct-to-Consumer Channel Launch | Douyin live-streaming commerce displaces wholesale layers for margin recapture by heritage brands. |
| Geographic Indication Certification Investment | Ministry of Agriculture protections anchor premium positioning in corporate gifting channels. |
| Franchised Kiosk Format Expansion | Reduced rent exposure enables tier-three and tier-four penetration for beverage-first retail concepts. |
Research Approach
Operator-level perspectives from plantation managers, cooperative processing heads, beverage-retail franchise operators, and SAMR compliance officers anchored the qualitative base. Secondary validation drew from customs export records, Ministry of Agriculture geographic indication registries, MEE provincial carbon implementation disclosures, and retail audit data from Nielsen and Circana. Bottom-up volume modeling across oxidation levels and packaging formats triangulated with top-down value estimates from channel margin analysis.
Sensitivity analysis tested input cost volatility scenarios for fertilizer and labor expenses across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user application, with provincial regulatory cluster as an additional industry-specific layer. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for format innovation adoption curves and dual carbon policy implementation pacing.
Underlying assumptions cover continued GB standard enforcement intensity, cooperative aggregation model scalability, and beverage-retail format penetration rates, with deviation risk concentrated in aging farmer population constraints and coffee substitution acceleration in urban morning ritual occasions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Smart Tea Maker Market
Tea
White Tea Market
Tea
Pyramid Tea Bags Market
Tea
Butterfly Pea Flower Tea Market
Tea
Edible Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Tea Pitchers Market
Tea
Instant Tea Premix Consumption Market
Tea
Green Tea Extract Market
Tea
Europe Green Tea Market
Tea
Black Tea Market
Tea
Tea Essence Market
Tea
Bottled Milk Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
US Ready to Drink Tea Market
Tea
Slimming Tea Market