
 Black Tea Market | 2026-2036
Black Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Black Tea Market Analysis
Specialty tea houses and premium food service operators are rotating share away from traditional supermarket retail channels. Tata Consumer Products anchors its position through backward integration into Assam and Nilgiri estates. Unilever competes via mass-market brand architecture and multi-channel distribution density. ITO EN Ltd. differentiates through cold-brew extraction technology and ready-to-drink format specialization in East Asian markets.
Black tea comprises fully oxidized Camellia sinensis leaves processed through withering, rolling, fermenting, and firing stages, yielding liquor with higher theaflavin and thearubigin content than green or oolong varieties. The oxidation process creates shelf-stable products suited for bulk commodity trade and premium single-origin retail alike. Black loose leaf formats command margin concentration in specialty retail and direct-to-consumer channels, while black bagged tea dominates volume throughput in supermarkets and convenience stores. Organic black tea represents the fastest-growing certification tier, though flavored black tea generates higher per-unit revenue in North American and European markets.
The U.S. FDA and USDA enforce pesticide residue limits and organic certification standards for imported tea, while the EU's EFSA and REACH frameworks govern maximum residue levels and packaging chemical compliance. India's FSSAI and Tea Board regulations shape export quality grading and geographical indication protections for Darjeeling and Assam origins. Stakeholders must monitor evolving climate-risk protocols and carbon-border adjustment mechanisms that will reshape sourcing economics and origin premiums across major producing regions.
Market Dynamics
The EU's F-Gas Regulation and REACH frameworks are tightening packaging material compliance requirements for imports into European markets. Specialty tea houses and premium café chains are expanding procurement of single-origin orthodox grades from India's Assam and Darjeeling growing regions as well as Sri Lanka's Central Province highland estates.
Growth Catalysts
- Organic certification demand:Consumers in North American and European markets prioritize pesticide-free products. The USDA organic standard and EU organic logo drive premium pricing for certified estates.
- Cold-brew extraction technology:Ready-to-drink format specialization accelerates in East Asian markets. ITO EN Ltd. and similar operators capture convenience-oriented consumption occasions.
- Geographical indication protections:India's Tea Board regulations enforce Darjeeling and Assam origin authenticity. Export quality grading reinforces price premiums for designated terroirs.
Market Restraints
- Climate volatility in highland estates:Erratic rainfall patterns in Sri Lanka's Central Province disrupt flush timing. Yields compress during drought cycles that lengthen between monsoons.
- Input cost inflation:Natural gas prices elevate firing-stage energy costs for orthodox processing. Smallholder processors face margin compression against integrated estate competitors.
- Regulatory friction:The EU's REACH framework imposes chemical compliance documentation burdens on packaging suppliers. Non-EU exporters absorb testing costs or lose shelf access.
Strategic Opportunities
- Direct-to-consumer channel expansion:Specialty retailers bypass supermarket intermediaries. Subscription models capture recurring revenue from enthusiast segments in Germany and Japan.
- Carbon-border adjustment readiness:Early adoption of emissions tracking satisfies impending EU import levies. Estates with renewable energy integration secure preferential procurement contracts.
- Functional ingredient extraction:Theaflavin and thearubigin isolates target nutraceutical applications. Pharmaceutical and cosmetic formulators source standardized polyphenol concentrates.
Industry Challenges
- Skill gaps in orthodox processing:Traditional rolling and fermentation expertise concentrates among aging workforce cohorts. Knowledge transfer mechanisms fail to attract younger operators.
- Compliance timeline compression:Multiple certification schemes (organic, Fairtrade, Rainforest Alliance) demand overlapping audit schedules. Small estates struggle with administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Tea Market |
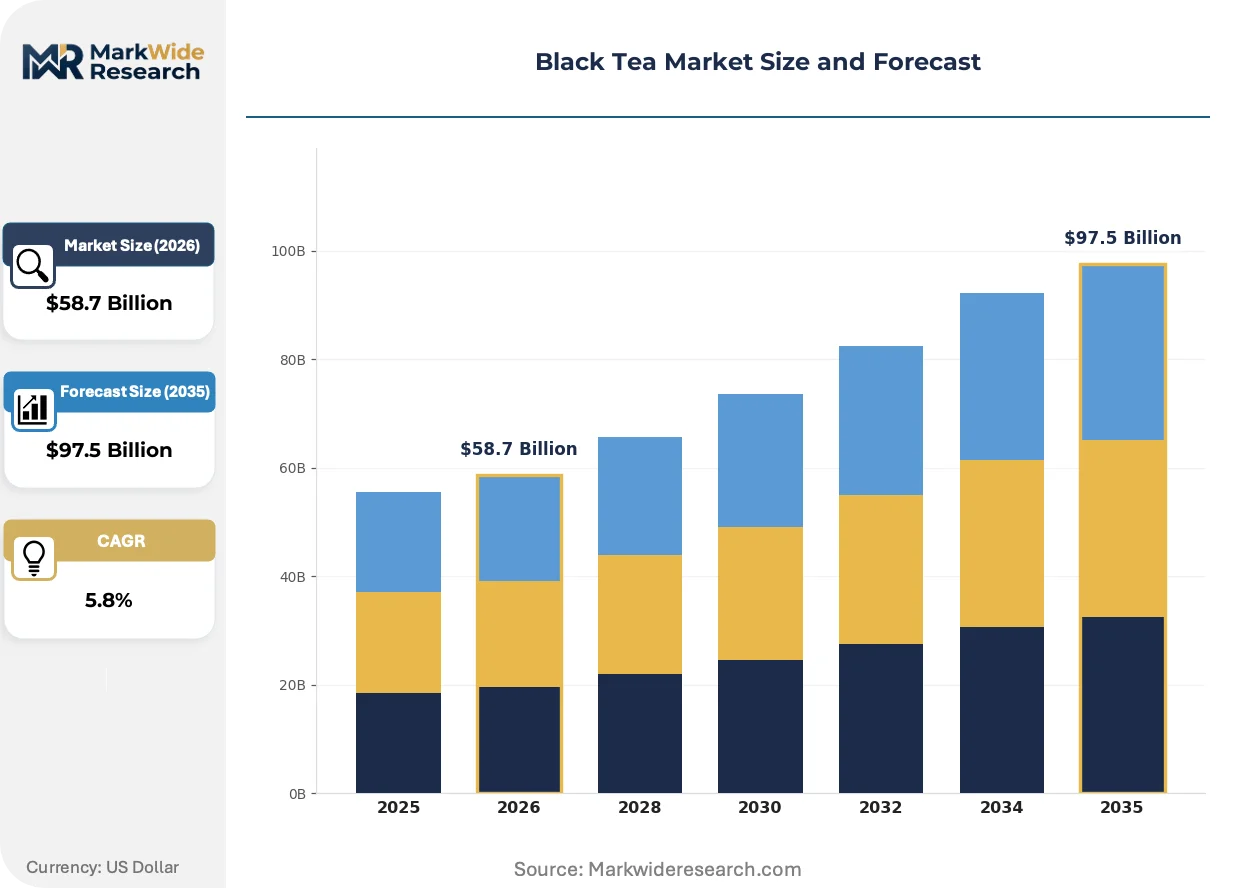
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Loose Leaf, Black Bagged Tea, Flavored Black Tea, Organic Black Tea End User: Retail Consumers, Food Service, Tea Houses, Online Retailers Packaging Type: Pouches, Tins, Boxes, Bulk Packaging Distribution Channel: Supermarkets, Specialty Stores, E-commerce, Convenience Stores |
| Companies Covered | Dilmah Ceylon Tea Company, Nestlé, Tata Consumer Products, Ahmad Tea, Bigelow Tea, Unilever, Zhejiang Chunli Tea Co., Ltd., ITO EN Ltd., R. Twining and Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Tea Market Emerging Trajectories
Processing technology and consumption formats are diverging between commodity bulk trade and premium specialty channels. Climate adaptation protocols and digital traceability systems reshape estate operations.
Cold-brew extraction systems is displacing hot-infusion methods in ready-to-drink manufacturing. Japanese and South Korean beverage manufacturers deploy low-temperature steeping to reduce tannin bitterness and extend shelf stability. This technology compresses the advantage of traditional hot-brew concentrate suppliers.
The EU's F-Gas Regulation phases down hydrofluorocarbon use in cold-chain logistics. Tea exporters to European markets must retrofit refrigerated transport and storage infrastructure. Organic and specialty grade shipments face disproportionate compliance costs relative to commodity volumes.
Specialty tea houses rotate procurement toward single-origin transparency. Direct relationships with Assam and Darjeeling estates displace auction-based purchasing. This pattern concentrates in German and Japanese metropolitan markets where provenance storytelling commands price premiums.
Black Tea Market Segmentation
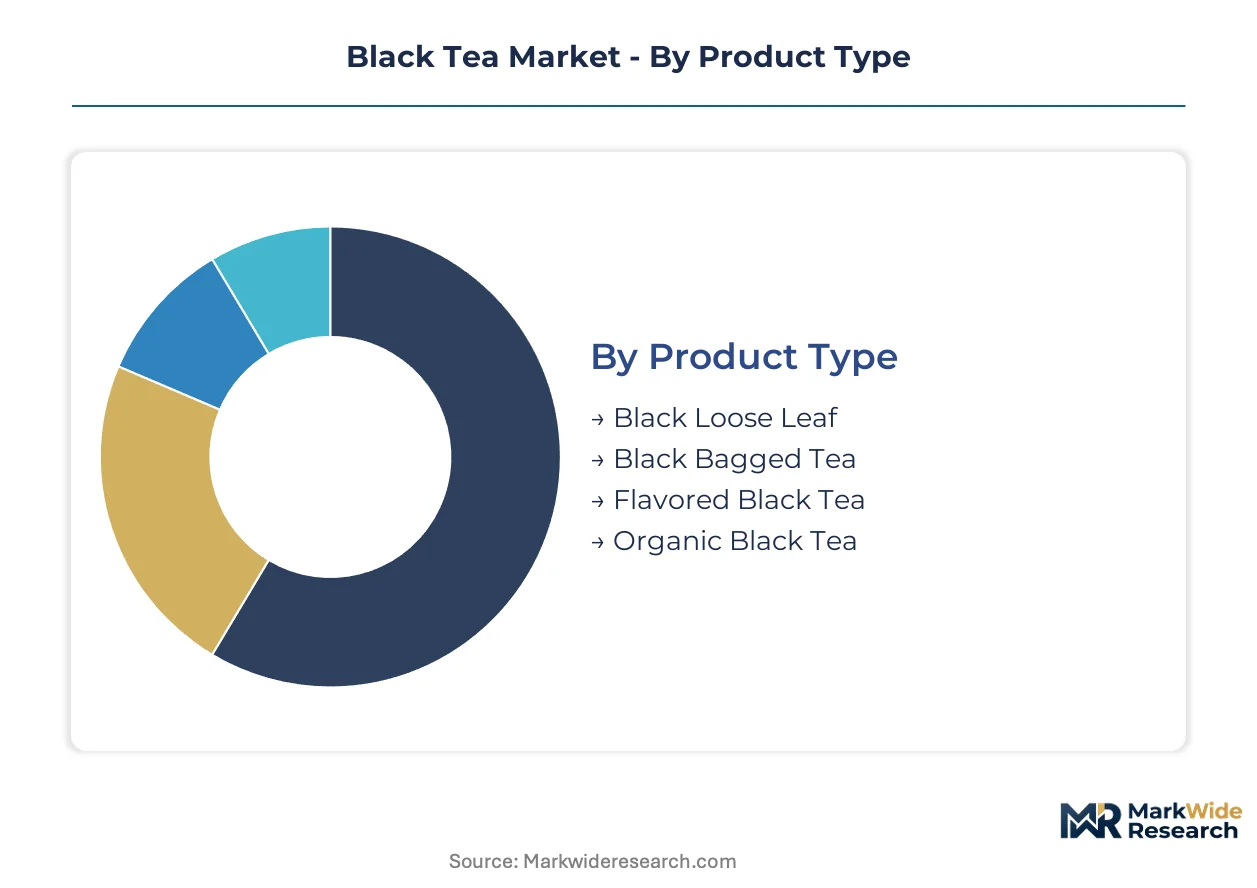
Black tea segmentation reveals divergent profit pools across commodity and specialty channels. Product format, end-user concentration, and distribution access determine margin capture and regulatory exposure for estate operators and brand owners.
Product Type:
Substitution pressure from ready-to-drink beverages and functional drinks weighs heaviest on bagged formats, while loose leaf and organic grades defend position through ritual consumption and certification premiums.
- Black Loose Leaf:Fully oxidized leaves retain terroir-specific aromatic compounds. Specialty tea houses in Germany and Japan concentrate procurement here, drawn by provenance storytelling and direct estate relationships that command price premiums over auction grades.
- Black Bagged Tea:CTC-processed dust and fanning grades dominate supermarket volume throughput. Convenience-oriented retail consumers in the US and UK absorb this format despite erosion from loose leaf alternatives in premium channels.
- Flavored Black Tea:Bergamot, vanilla, and spice infusions target North American palate preferences. Per-unit revenue exceeds unflavored equivalents through value-added processing.
- Organic Black Tea:USDA and EU organic certification eliminates synthetic pesticide residues. Supply concentrates in Assam and Darjeeling estates with conversion timelines stretching three to five years.
Black bagged tea anchors the volume base while organic black tea gains share at the steepest rate.
End User:
Cost tier stratification separates mass-market absorption from enthusiast-driven premium extraction, with food service and tea houses capturing margin through experience-based pricing.
- Retail Consumers:Supermarket and e-commerce purchasers drive standardized packaging demand. Price sensitivity concentrates in bagged tea selection while loose leaf buyers accept per-gram premiums for origin transparency.
- Food Service:Hotels and restaurants procure bulk grades for breakfast service. Steeped-to-order protocols in premium establishments rotate toward orthodox single-origin offerings.
- Tea Houses:Specialty operators in Tokyo, Berlin, and New York City curate direct estate relationships. Gongfu and Western service formats dictate leaf grade and brewing equipment specifications.
- Online Retailers:Subscription models and direct-to-consumer platforms bypass traditional wholesale markups. Digital-native brands exploit lower customer acquisition costs in enthusiast segments.
Retail consumers provide the demand foundation as tea houses expand at the fastest clip.
Packaging Type:
Volume scale and margin structure diverge sharply between commodity bulk shipments and unitized retail formats, with regulatory compliance costs disproportionately burdening smaller pack sizes.
- Pouches:Flexible laminated structures dominate single-serve and small-format retail. REACH-compliant barrier films elevate unit costs for EU-bound exports.
- Tins:Metal canisters signal premium positioning in gift and specialty channels. Japanese and German consumers associate tin packaging with freshness preservation and reusability.
- Boxes:Paperboard cartons with inner foil wrapping balance shelf presence and cost efficiency. Supermarket private label programs standardize on this format.
- Bulk Packaging:Multi-kilogram foil-lined sacks serve food service and industrial extraction. Minimal processing and handling costs support lowest per-kilogram landed prices.
Bulk packaging moves the greatest tonnage while tins achieve the most rapid share expansion in premium channels.
Distribution Channel:
Customer type and purchase occasion fragmentation force parallel channel strategies, with e-commerce penetration rewriting geographic access rules for origin-specific grades.
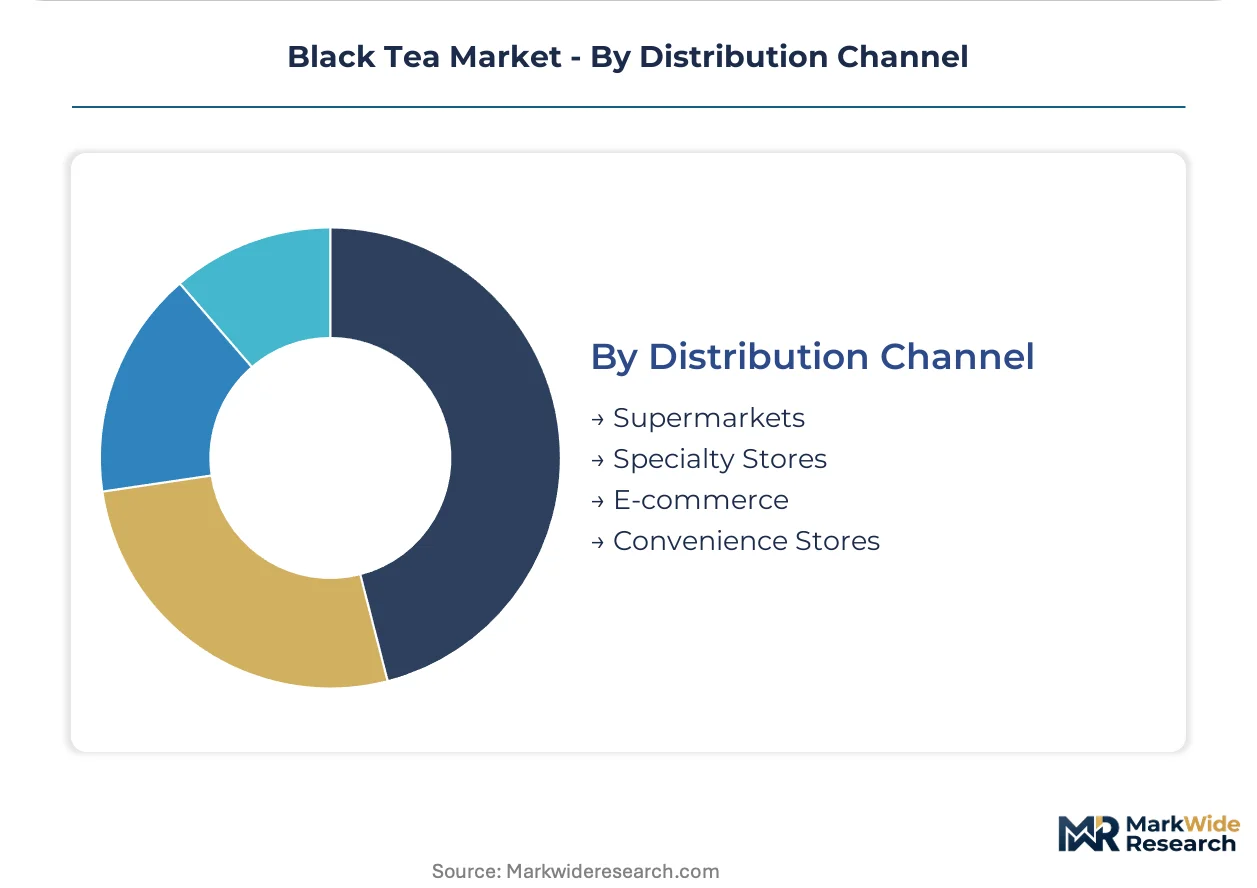
- Supermarkets:Mass-market retail chains consolidate volume through centralized procurement. Private label programs and multinational brand slots compress margins for estate-direct suppliers.
- Specialty Stores:Curated assortments in tea-focused retailers and gourmet food halls emphasize single-origin storytelling. Staff training and sampling protocols justify price multiples over supermarket equivalents.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators collapse geographic distance between Assam estates and Berlin consumers. Subscription retention metrics now rival traditional brand loyalty.
- Convenience Stores:Immediate consumption occasions drive single-serve hot and cold tea sales. Ready-to-drink format dominance in Japan and South Korea originates here.
Supermarkets retain the volume core even as e-commerce climbs fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Assam and Darjeeling estates supply premium orthodox grades to German and Japanese specialty buyers, while Sri Lankan highland producers serve European retail chains under tightening REACH packaging mandates.
Germany
Specialty tea houses in Berlin and Hamburg drive demand for single-origin Darjeeling and Assam lots with full provenance documentation. The EU's F-Gas Regulation phases down hydrofluorocarbon use in cold-chain logistics for refrigerated tea storage. Importers in Hamburg port cluster retrofit transport infrastructure to maintain organic certification integrity.
Japan
Convenience-oriented consumers in Tokyo and Osaka absorb ready-to-drink cold-brew black tea formats. METI efficiency standards shape processing equipment imports for domestic blending operations. ITO EN Ltd. anchors cold-brew extraction technology development in Kansai metropolitan markets.
United States
Supermarket chains and direct-to-consumer platforms in New York and California concentrate volume throughput for bagged and loose leaf grades. FDA pesticide residue limits and USDA organic certification standards govern import quality thresholds. Specialty retailers in Brooklyn and San Francisco bypass traditional wholesale channels through subscription-based estate relationships.
India
Domestic consumption and export grading operations concentrate in Assam and West Bengal growing regions. FSSAI regulations and Tea Board geographical indication protections enforce Darjeeling and Assam origin authenticity. Tata Consumer Products maintains backward integration into Nilgiri and Assam estates for supply security.
Sri Lanka
Central Province highland estates supply orthodox grades to European and Middle Eastern buyers. Erratic rainfall patterns disrupt flush timing and compress yields during extended drought cycles. Colombo-based exporters navigate EU REACH chemical compliance documentation for flexible packaging materials.
Black Tea Market Vendor Landscape
Player mix skews toward integrated estate operators and multinational brand architects with divergent channel strategies. Consolidation pressures concentrate among mass-market bagged tea segments while specialty loose leaf channels fragment across direct-to-consumer entrants. Three archetypes dominate: backward-integrated estate owners, multi-brand portfolio conglomerates, and format-specialized beverage technology firms. Competitive moves center on direct estate relationship cultivation and cold-brew processing capacity expansion.
Among integrated estate operators, Tata Consumer Products and Dilmah Ceylon Tea Company exemplify backward integration models with captive supply control over South Asian growing regions. Unilever occupies a position as multi-brand architect with mass-market distribution density across retail channels. ITO EN Ltd. anchors the format-specialized tier through cold-brew extraction technology representation in East Asian ready-to-drink markets. These three patterns illustrate how scale, origin control, and processing innovation segment competitive positioning.
| Leading Market Players |
|---|
| Dilmah Ceylon Tea Company |
| Nestlé |
| Tata Consumer Products |
| Ahmad Tea |
| Bigelow Tea |
| Unilever |
| Zhejiang Chunli Tea Co., Ltd. |
| ITO EN Ltd. |
| R. Twining and Company Limited |
| Others |
Supply Flow & Price Mechanics
Capacity utilization disparities between integrated Assam estates and fragmented Sri Lankan smallholders concentrate pricing power upstream. Scale economies in orthodox processing anchor price floors for specialty grades, while CTC commodity volumes face margin compression from energy cost inflation and REACH compliance burdens.
Pricing Analysis
Cold-brew extraction technology commands premium positioning over hot-infusion concentrates in ready-to-drink formats. Three-tier pricing structure across single-origin orthodox, blended premium, and mass-market CTC grades reflects certification intensity and origin traceability. Price differentiation hinges on organic certification tier and direct estate relationship depth. Pricing pressure stems from natural gas cost inflation in firing-stage processing. Mass-market bagged buyers exhibit highest price sensitivity; Japanese specialty tea houses show lowest.
Supply Chain Analysis
Colombo port clearance and Hamburg cold-chain transit underwrite European access for Sri Lankan and Indian exporters. Supply concentrates in India's Assam and Darjeeling districts alongside Sri Lanka's Central Province highlands. Raw material flows draw from Camellia sinensis leaf harvests, natural gas for firing operations, and REACH-compliant laminated films. Single-source vulnerability concentrates in monsoon-dependent flush timing. Distribution runs through direct estate relationships for specialty grades and auction houses for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against ready-to-drink functional beverages and specialty coffee chains that capture convenience-oriented consumption occasions. Substitution threats from cold-brew coffee and adaptogenic drinks compress traditional black tea's share of beverage occasions.
For Market Incumbents: Fortify backward integration into Assam and Nilgiri estates to secure orthodox grade supply amid climate volatility. Deepen direct-to-consumer channel control through subscription platforms that lock in German and Japanese enthusiast segments. Cold-brew processing capacity expansion counters ready-to-drink coffee substitution.
For New Entrants and Emerging Players: Lead with carbon-border adjustment readiness as procurement differentiator for EU-bound specialty grades. Target underpenetrated online retail in North American organic segments where certification premiums exceed compliance costs. Subscription-based provenance storytelling offers lowest customer acquisition friction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer specialty operators with estate-level integration. Long-term viability favors assets with renewable energy firing infrastructure and organic certification runway. Acquisition target archetype: mid-scale Darjeeling or Assam estates with EU organic approval and cold-chain retrofit completion. Signal to watch: EU carbon-border adjustment mechanism implementation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Brew Processing Capacity Expansion | ITO EN Ltd. and East Asian competitors anchor technology leadership in ready-to-drink formats. |
| Direct Estate Relationship Cultivation | Berlin and Tokyo specialty tea houses bypass auction intermediaries for provenance transparency. |
| Organic Certification Investment | USDA and EU organic tiers command price premiums across North American and European retail. |
| Carbon-Border Adjustment Readiness | Early emissions tracking adoption secures preferential procurement from EU import-dependent buyers. |
| Functional Ingredient Extraction Development | Theaflavin isolates target pharmaceutical and cosmetic formulators seeking standardized polyphenol concentrates. |
Methodological Framework
Desk research of customs trade databases, Tea Board export statistics, and EU regulatory filings preceded structured interviews with estate operations managers, specialty tea house buyers, cold-brew processing technologists, and REACH compliance consultants. Primary fieldwork validated secondary estimates through bottom-up estate capacity surveys and top-down import value reconciliation. Triangulation across these sources anchored segmentation splits and growth rate derivation.
Variance decomposition across product format, end-user concentration, and distribution channel shaped the analytical framework over the projection horizon. Modeled dimensions included orthodox versus CTC processing grade, retail versus food service versus tea house end use, and direct estate versus auction versus supermarket channel pathways. CAGRs were synthesized from volume trajectory analysis and price realization trends. Climate risk protocols and carbon-border adjustment mechanisms served as scenario-dependent forecast modifiers.
Forecasts assume regulatory continuity in EU REACH, F-Gas Regulation, and organic certification regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EU import levy implementation and monsoon pattern volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Organic Tea Market
Tea
North America Tea Market
Tea
Moringa Tea Market
Tea
Tea Concentrate Market
Tea
Bottled Milk Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Tea Infuser Market
Tea
RTD Tea Market
Tea
Nitro Tea Market
Tea
Matcha Tea Market
Tea
Global Fruit Tea Market
Tea
High Protein Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Edible Tea Market
Tea
Herbal Tea Market