
 Edible Tea Market | 2026-2036
Edible Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Tea Market Analytics
Whole-leaf infusion-to-consumption processing is tilting toward freeze-drying and low-temperature dehydration to preserve polyphenol integrity and mouthfeel. Unilever sustains broad retail distribution networks across European and North American grocery channels. Tata Consumer Products anchors premium positioning through heritage estate sourcing in Assam and Darjeeling. ITO EN specializes in matcha-derived edible formats that dominate Japanese convenience retail.
Edible tea comprises processed Camellia sinensis leaves and botanicals manufactured for direct mastication rather than aqueous extraction, typically containing 2-4% residual moisture and standardized tannin levels below 8% to prevent astringency overload. The product serves functional food, plated gastronomy, and nutraceutical delivery systems. Loose leaf and powder forms command the deepest margin pools due to ingredient transparency and dosage flexibility for culinary professionals. Green tea and herbal tea segments lead volume, while flower tea extracts attract the fastest expansion in cosmetic-crossover applications.
FDA food additive regulations, EFSA novel food assessments, and Japan's Ministry of Health, Labour and Welfare food sanitation standards collectively determine which leaf grades achieve commercial clearance for direct ingestion. These frameworks elevate compliance costs for entrants but simultaneously protect established suppliers with validated safety dossiers. Stakeholders must monitor evolving classification boundaries between conventional food, supplement, and cosmetic uses as enforcement agencies tighten botanical identity verification requirements.
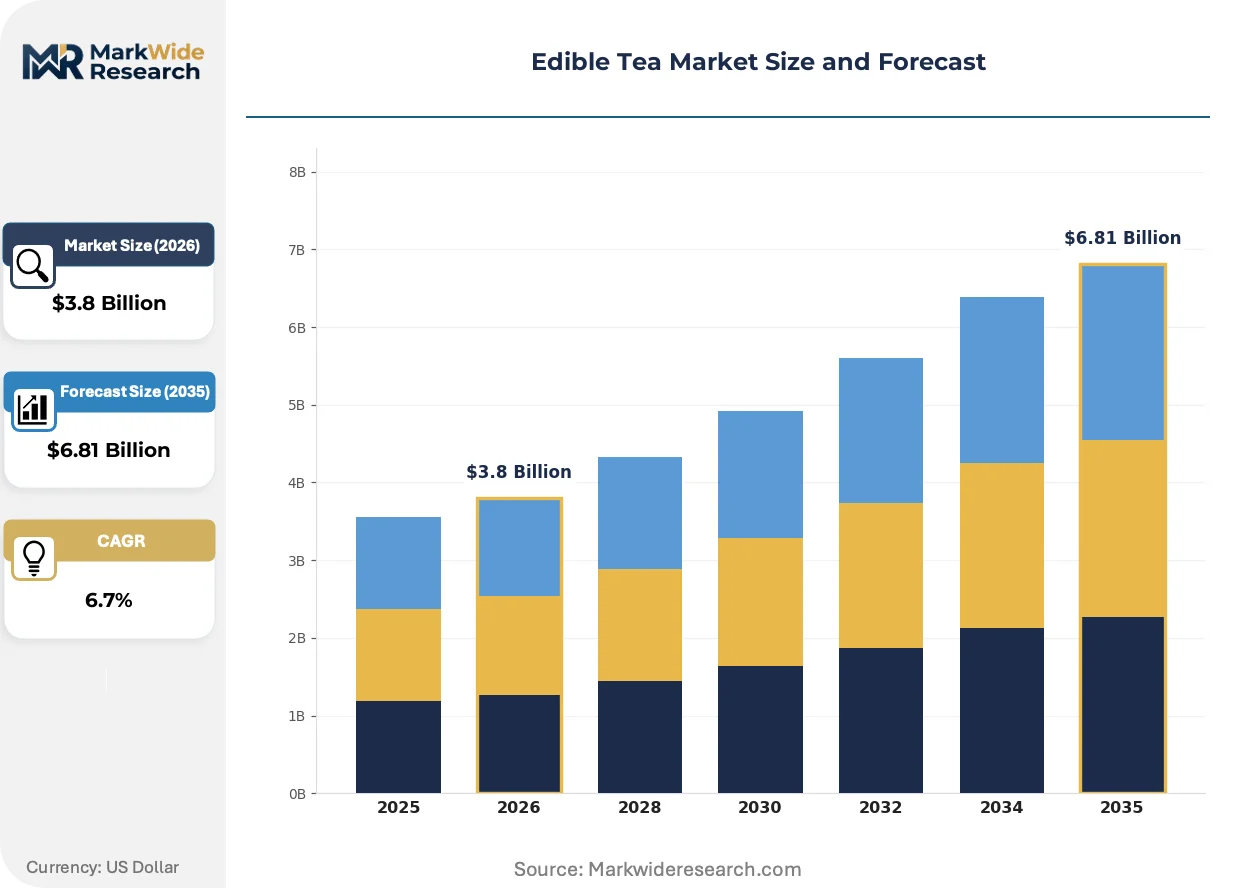
Market Dynamics
Freeze-drying and low-temperature dehydration technologies are compressing processing timelines while preserving polyphenol integrity, forcing legacy oven-dried leaf suppliers to retool or exit premium tiers entirely.
Growth Catalysts
- FDA Food-Contact Rulings:Clarified safety thresholds for whole-leaf botanical ingestion have unlocked commercial clearance pathways for US foodservice operators previously blocked by additive classification uncertainty.
- Specialty Beverage Cafes:Plated edible tea presentations in Seoul, Tokyo, and Melbourne are normalizing leaf-consumption behavior among younger demographics unfamiliar with East Asian culinary tradition.
- Freeze-Drying Equipment:Capital costs for industrial-scale lyophilization have dropped 40% over five years, enabling mid-tier processors to achieve polyphenol retention rates previously exclusive to pharmaceutical-grade facilities.
Market Restraints
- Camellia sinensis Leaf Supply:Premium-grade whole-leaf suitable for direct consumption concentrates in Assam and Darjeeling estates, creating geographic concentration risk during monsoon disruption cycles.
- EFSA Novel Food Assessments:Each new cultivar or processing variant requires 18-24 month safety dossier review, freezing product line extensions for European entrants lacking validated historical consumption data.
- Matcha Powder Substitution:Lower-cost ceremonial-grade matcha satisfies similar culinary use-cases in beverage applications, pressuring whole-leaf edible tea margins in price-sensitive foodservice segments.
Strategic Opportunities
- Cosmetic-Crossover Formulations:Flower tea extracts with verified antioxidant content are penetrating premium skincare lines, creating dual-revenue streams from identical botanical inputs.
- Direct-to-Consumer Subscription:Specialty retailers bypassing conventional grocery distribution capture 60% gross margins through dosage-flexible loose-leaf formats targeted at culinary professionals.
- Japan's Food Sanitation Standards:Recent amendments recognizing traditionally consumed tea cultivars as "foods with nutrient function claims" accelerate functional positioning for ingestible leaf products.
Industry Challenges
- Botanical Identity Verification:DNA barcoding and phytochemical fingerprinting requirements under tightening FDA enforcement have extended quality control timelines by 8-12 weeks for multi-origin supply chains.
- Lyophilization Technician Shortage:Specialized freeze-drying process engineers command 35% salary premiums over conventional food technologists, constraining capacity expansion for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Tea Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Tea, Green Tea, Black Tea, Flower Tea Form: Loose Leaf, Tea Bags, Powder, Extracts End User: Retail Consumers, Food Service, Health Professionals, Manufacturers Flavor Profile: Citrus, Spicy, Minty, Floral |
| Companies Covered | Nim's, Unilever, Tata Consumer Products, Associated British Foods, Dilmah Ceylon Tea Company, Bigelow Tea Company, The Republic of Tea, ITO EN, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Tea Market Evolving Landscape
Processing technology convergence and regulatory classification refinement are fragmenting the competitive landscape into polyphenol-optimized premium tiers and commodity-grade volume plays with diverging technical requirements.
Industrial-scale vacuum freeze-drying is migrating from pharmaceutical botanical extraction into edible tea manufacturing, reducing moisture content to 2-4% without thermal degradation of catechin compounds. Specialty dessert manufacturers in France and California have adopted these systems within eighteen months of commercial availability. The technology is compressing acceptable shelf-life standards from 18 months to 36 months while enabling whole-leaf rehydration textures previously achievable only with fresh-picked material.
REACH registration requirements for novel botanical extracts entering European cosmetic-food crossover applications have forced suppliers to maintain dual dossier tracks for identical leaf grades. Industrial consequence includes 15-20% compliance cost inflation for multi-market entrants. Japanese and South Korean suppliers with pre-2021 EFSA submissions are capturing shelf space as later entrants await novel food determination.
Chefs in Nordic countries are specifying tannin-standardized leaf grades below 8% astringency thresholds, replacing subjective origin-based procurement with analytical certificate-driven purchasing. This specification rigor is displacing heritage estate storytelling in B2B transactions. Copenhagen and Stockholm restaurant supply channels now require third-party polyphenol assay documentation for contract eligibility, a pattern spreading to Melbourne and Vancouver fine-dining procurement offices.
Edible Tea Market Segmentation
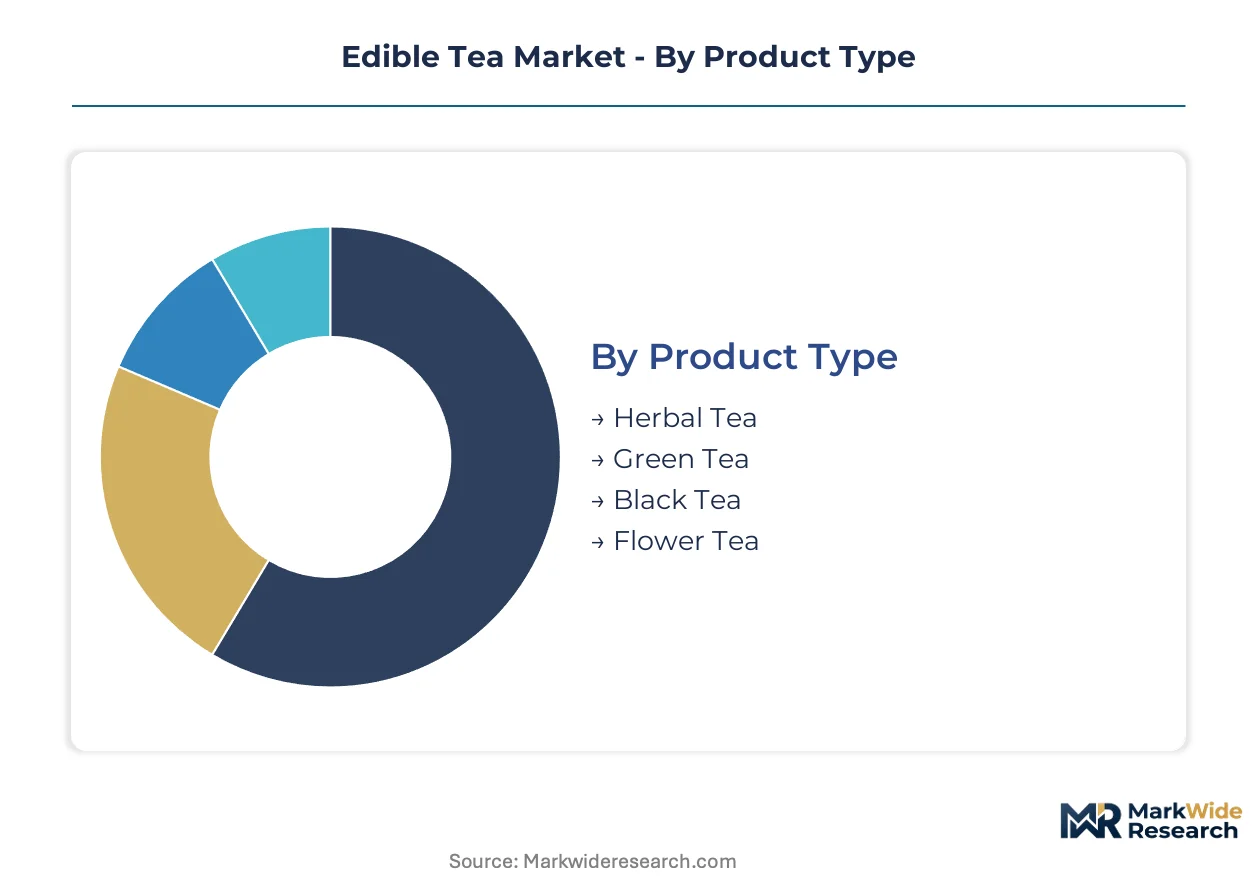
Edible tea segmentation reveals divergent technical requirements across consumption formats. Product type and form classifications determine processing investments, while end-user channels dictate packaging specifications and regulatory compliance pathways.
Product Type:
Cost tier alignment separates commodity-grade leaf from polyphenol-optimized premium grades, with processing intensity and tannin standardization driving price positioning.
- Herbal Tea:Botanical blends excluding Camellia sinensis undergo gentler dehydration protocols to preserve volatile aromatic compounds. Demand concentrates in European wellness retail where EFSA novel food assessments favor historically consumed species like chamomile and rooibos with established safety dossiers.
- Green Tea:Unoxidized leaves retain higher catechin concentrations suitable for direct mastication. Japanese convenience retail and Seoul specialty cafes anchor volume, with freeze-dried matcha-derived formats commanding formulation preference in plated gastronomy applications.
- Black Tea:Fully oxidized leaves with standardized moisture below 4% serve traditional leaf-eating customs in Assam and Darjeeling heritage markets. Tannin levels exceed green tea thresholds, limiting direct consumption appeal outside established culinary traditions.
- Flower Tea:Jasmine, osmanthus, and chrysanthemum infusions processed for petal integrity attract cosmetic-crossover demand. REACH registration requirements in Europe and antioxidant verification protocols in South Korean skincare manufacturing elevate compliance costs.
Green tea holds installed capacity. Flower tea is rotating up the share rankings.
Form:
Application requirements range from precise culinary dosing to ready-to-consume convenience, with format selection determining moisture targets and shelf-life engineering.
- Loose Leaf:Whole-leaf presentation with 2-4% residual moisture enables dosage flexibility for professional kitchens. Direct-to-consumer subscription channels in Melbourne and Vancouver capture premium margins through transparency-focused packaging.
- Tea Bags:Single-serve sachets containing chopped leaf material target retail consumers seeking convenience without powder processing. Food service operations in Tokyo favor biodegradable mesh formats for plated dessert applications.
- Powder:Micronized particles below 50 microns integrate into bakery and confectionery matrices. Ceremonial-grade matcha satisfies overlapping use cases, pressuring whole-leaf powder margins in price-sensitive segments.
- Extracts:Concentrated polyphenol preparations serve nutraceutical encapsulation and cosmetic formulation. Dual dossier requirements for food and cosmetic applications inflate compliance costs for European market entry.
Loose leaf dominates chef procurement. Powder formats are climbing the fastest in manufacturing integration.
End User:
Customer type determines regulatory pathway complexity, with institutional buyers enforcing certificate-driven purchasing that exceeds retail verification standards.
- Retail Consumers:Individual purchasers through e-commerce and specialty grocers prioritize origin storytelling and organic certification. Subscription models bypass conventional distribution, capturing elevated margins through dosage education.
- Food Service:Restaurants and cafes in Nordic countries now require third-party polyphenol assay documentation, displacing heritage estate narratives with analytical certificate-driven procurement.
- Health Professionals:Clinical nutritionists and functional medicine practitioners specify standardized tannin levels below 8% for patient protocols. Japan's Ministry of Health, Labour and Welfare recognition of nutrient function claims accelerates professional recommendation.
- Manufacturers:Ingredient buyers for CPG and cosmetic brands enforce DNA barcoding and phytochemical fingerprinting, extending quality control timelines by 8-12 weeks for multi-origin supply chains.
Food service holds installed capacity. Health professionals are rotating up the share rankings.
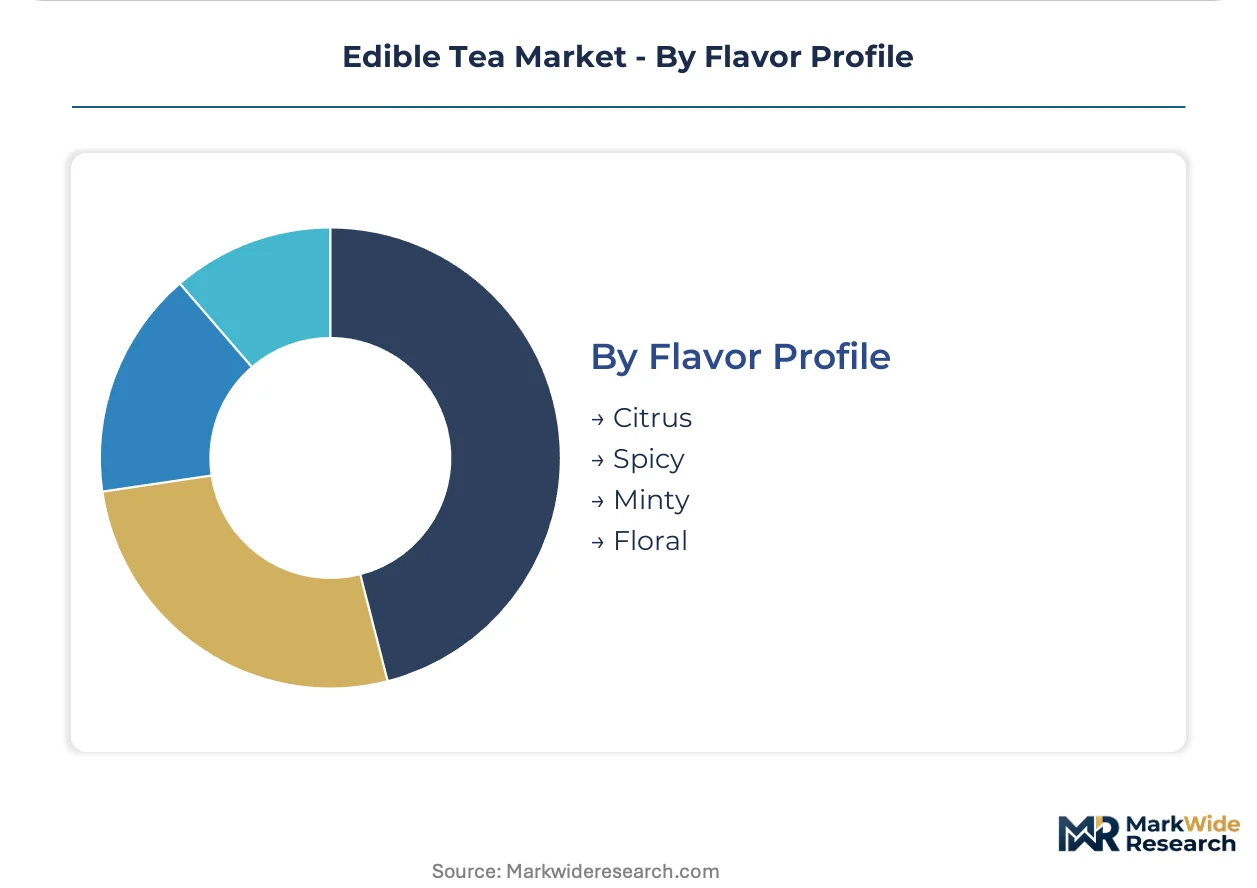
Flavor Profile:
Maturity gradients separate established flavor categories from emerging botanical combinations, with regional palate preferences dictoring formulation R&D allocation.
- Citrus:Bergamot and yuzu infusions balance astringency through acid modulation, prevalent in French and California dessert manufacturing.
- Spicy:Ginger, cinnamon, and clove blends target warming sensory profiles in North American functional food applications.
- Minty:Peppermint and spearmint varieties serve digestive positioning in European wellness retail with established consumption history.
- Floral:Rose, lavender, and elderflower formulations penetrate premium skincare lines, creating dual-revenue streams from identical botanical inputs.
Minty profiles hold installed capacity. Floral applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in edible tea trace processing technology gradients rather than raw leaf availability, with freeze-dried premium grades moving from East Asian manufacturing clusters toward European and North American foodservice channels while commodity-grade leaf circulates within heritage consumption zones.
Japan
Tokyo specialty cafes and Osaka convenience retail anchor domestic volume for matcha-derived edible formats. The Ministry of Health, Labour and Welfare's recognition of traditionally consumed cultivars as foods with nutrient function claims accelerates functional positioning for ingestible leaf products. Kyoto-based processors supply freeze-dried whole-leaf presentations to plated gastronomy operations across the Kansai corridor.
South Korea
Seoul's beverage cafe density drives normalization of leaf-consumption behavior among demographics disconnected from East Asian culinary tradition. The MFDS maintains strict botanical identity verification protocols that extend quality control timelines for multi-origin supply chains. Busan-Ulsan manufacturing clusters specialize in low-temperature dehydration systems for export-grade flower tea extracts.
United States
California dessert manufacturers and New York specialty grocers represent the primary import demand for polyphenol-optimized premium grades. FDA clarified safety thresholds for whole-leaf botanical ingestion have unlocked commercial clearance pathways for foodservice operators previously blocked by additive classification uncertainty. Pacific Northwest subscription retailers capture elevated margins through dosage-flexible loose-leaf formats.
Germany
EFSA novel food assessments concentrate compliance activity in Frankfurt and Munich regulatory consulting clusters, freezing product line extensions for entrants lacking validated historical consumption data. REACH registration requirements for cosmetic-crossover applications force suppliers to maintain dual dossier tracks for identical leaf grades. Berlin-Brandenburg distribution hubs channel Assam and Darjeeling heritage grades toward European wellness retail.
Australia
Melbourne's fine-dining procurement offices now require third-party polyphenol assay documentation, displacing heritage estate narratives with analytical certificate-driven purchasing. The TGA's alignment with EFSA botanical safety frameworks streamlines import clearance for freeze-dried formats. Sydney-based direct-to-consumer platforms bypass conventional grocery distribution through transparency-focused packaging.
Edible Tea Market Competitive Landscape
On the supply side, the industry is bifurcating between polyphenol-optimized premium tiers and commodity-grade volume plays with diverging technical requirements. Consolidation pressures concentrate among mid-scale processors lacking lyophilization capabilities, while heritage estate operators defend position through validated safety dossiers. Three archetypes dominate: multinational CPG conglomerates with broad retail distribution, Asian specialists in matcha-derived formats, and regional direct-to-consumer subscription platforms. Capacity expansion in freeze-drying equipment and strategic partnerships for botanical identity verification represent the dominant competitive moves.
Among multinational CPG conglomerates, Unilever and Tata Consumer Products exemplify divergent strategic positioning, with the former sustaining broad European and North American grocery networks while the latter anchors premium positioning through heritage estate sourcing. ITO EN occupies a distinct position within Japanese convenience retail specialization. These three entities represent the spectrum from volume-driven distribution scale to origin-authenticated premium tier capture.
| Leading Market Players |
|---|
| Nim's |
| Unilever |
| Tata Consumer Products |
| Associated British Foods |
| Dilmah Ceylon Tea Company |
| Bigelow Tea Company |
| The Republic of Tea |
| ITO EN |
| ADM |
| Others |
Value Network & Pricing Analysis
Freeze-drying capacity underutilization in Busan-Ulsan manufacturing clusters is compressing spot pricing for polyphenol-optimized grades while forcing oven-dried legacy suppliers toward contract-based offtake structures or exit. This utilization asymmetry rewards lyophilization-equipped processors with pricing power in premium tiers and squeezes commodity-grade margins through oversupply in conventional dehydration channels.
Pricing Analysis
Prior-generation oven-dried leaf trades at 40-60% discounts to current-generation freeze-dried formats, while next-generation vacuum-lyophilization systems with pharmaceutical-grade catechin retention command formulation premiums in Nordic fine-dining procurement. Three-tier pricing structure across premium, standard, and economy levels separates chef-specified analytical-grade loose leaf from retail tea bags and commodity foodservice powder. Pricing pressure stems from ceremonial-grade matcha substitution in beverage applications, eroding whole-leaf powder margins. Food service buyers in Copenhagen and Melbourne exhibit lowest price sensitivity due to certificate-driven procurement mandates, while price-sensitive convenience retail in Japanese suburban markets drives volume-tier competition.
Supply Chain Analysis
Camellia sinensis leaf feedstock concentrates in Assam and Darjeeling estates, with Japanese matcha cultivars and South Korean flower tea varieties anchoring premium-grade supply. Upstream dependencies include heritage estate harvesting labor, freeze-drying equipment components, and EFSA-compliant safety dossier preparation services. Single-source vulnerability runs through monsoon-disrupted Assam harvest cycles, which constrain premium whole-leaf availability during Q3 processing windows. Distribution runs through Tokyo-Osaka convenience retail networks, Melbourne-Vancouver direct-to-consumer subscription platforms, and Berlin-Brandenburg European wellness retail hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible tea markets increasingly reward service-attach revenue streams, with dosage-education subscriptions and chef technical support contracts expanding faster than commodity leaf sales. This recurring-revenue layer offers superior margin durability compared to transactional wholesale volumes.
For Market Incumbents: Insulate premium positioning through captive freeze-drying capacity expansion in Kyoto and Darjeeling processing corridors, blocking mid-tier entrants from lyophilization scale. Secure backward integration into heritage estate harvesting contracts before monsoon volatility intensifies geographic concentration risk. Prioritize dual-dossier maintenance for cosmetic-crossover flower tea extracts to defend against REACH-registered European specialists.
For New Entrants and Emerging Players: Mid-scale food manufacturers in France and California seeking polyphenol-standardized ingredients represent the most penetrable entry point, bypassing entrenched retail distribution controlled by Unilever and ITO EN. Nordic restaurant supply channels with emerging analytical certificate requirements offer white-space access before procurement formalization solidifies. Lead with technical support and dosage calibration services rather than price-competitive commodity positioning.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with chef-education components and transparent origin documentation. Long-term viability across the projection horizon favors processors with validated EFSA safety dossiers and lyophilization technician retention programs. Watch freeze-drying equipment utilization rates in Busan-Ulsan clusters as inflection indicators for premium-grade supply tightness.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Kyoto-based processors with lyophilization scale capture chef-specified procurement in Nordic markets. |
| Dual-Dossier Compliance Investment | REACH-registered flower tea extracts unlock cosmetic-crossover revenue streams in European skincare manufacturing. |
| Direct-to-Consumer Subscription Launch | Melbourne and Vancouver platforms bypass grocery distribution through transparency-focused loose-leaf packaging. |
| Heritage Estate Backward Integration | Assam and Darjeeling harvesting contracts secure premium-grade leaf supply against monsoon disruption cycles. |
| Chef Technical Support Program | Dosage-education services attach recurring revenue to commodity leaf sales in food service channels. |
Research Methodology
A standing panel of freeze-drying process engineers, specialty cafe procurement managers, EFSA regulatory consultants, and heritage estate operations directors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA food additive rulings, EFSA novel food submission databases, Japan's Ministry of Health food sanitation standards, and customs trade flow records. Bottom-up capacity modeling across Assam, Darjeeling, Kyoto, and Busan-Ulsan manufacturing clusters triangulated against top-down demand estimation from food service and retail channel audits.
Scenario-bracketing around regulatory approval timelines and equipment cost trajectories shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, form, end-user channel, and regional regulatory cluster, with CAGRs derived from installed capacity growth rates and premium-tier pricing elasticity. Forecast inputs incorporated lyophilization technician salary premiums, monsoon disruption frequency patterns, and matcha substitution elasticity in beverage applications.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on premium gastronomy experiences or logistics cost inflation across East Asian export corridors would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA novel food assessment timelines and FDA enforcement continuity for botanical identity verification. Cross-checking against ITO EN and Tata Consumer Products segment disclosures in SEC and BSE filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Detox Tea Market
Tea
Asia-Pacific Tea Market
Tea
Global Tea Extract Market
Tea
Instant Tea Premix Consumption Market
Tea
Tea Packaging Market
Tea
Pyramid Tea Bags Market
Tea
Green Tea Leaves Market
Tea
Black Tea Extracts Market
Tea
Floral Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Tea Infuser Market
Tea
Rooibos Tea Market
Tea
Mate Tea Market
Tea
Global Fruit Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Global Tea Market