
 Tea Essence Market | 2026-2036
Tea Essence Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Essence Market Analytics
Buyer concentration in the beverage industry is rebalancing as ready-to-drink brands consolidate supplier relationships while specialty coffee chains fragment procurement across smaller botanical extractors. Finlays leverages its integrated tea estates in Kenya and Sri Lanka to secure raw material traceability for multinational beverage clients. Givaudan differentiates through flavor house expertise, blending tea essences with complementary botanicals for premium positioning. Tata Tea anchors South Asian supply through its domestic plantation network and regional distribution infrastructure.
Tea essence comprises concentrated aromatic and soluble compounds extracted from Camellia sinensis leaves, typically standardized to polyphenol content between 20% and 60% for industrial formulation. Manufacturers deploy solvent extraction or steam distillation to isolate catechins and volatile terpenes for use in beverages, nutraceuticals, and personal care products. Liquid extracts command the deepest margin pools due to customization requirements from beverage formulators seeking specific flavor profiles. Solvent extraction dominates volume output for instant tea applications where cost efficiency outweighs organic certification premiums.
FDA GRAS self-affirmation governs tea essence deployment in US functional beverages, while EFSA Novel Food assessments delay European market entry for innovative extraction formats. China's NMPA and GB standards enforce pesticide residue thresholds that shape cultivation practices across Yunnan and Zhejiang growing regions. India's FSSAI labeling mandates for caffeine content influence how brands position concentrated extracts for household versus food service channels. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized extraction or regional formulation assets offer superior compliance economics.
Market Dynamics
Ready-to-drink beverage manufacturers are consolidating supplier relationships around traceable, concentrated tea extracts while EU solvent recovery mandates force extraction facilities to retool processing infrastructure.
Growth Catalysts
- REACH Framework Compliance:European extraction facilities investing in closed-loop solvent systems are securing preferential supply contracts with multinational beverage brands seeking regulatory certainty.
- Cosmetics Formulation Demand:Personal care manufacturers in South Korea are integrating catechin-rich tea essences into anti-aging product lines, expanding addressable market beyond traditional beverage applications.
- Steam Distillation Advancement:Supercritical CO2 extraction technology is reducing thermal degradation of volatile terpenes, improving flavor fidelity for premium positioning.
Market Restraints
- Camellia sinensis Concentration Risk:Raw material sourcing concentrates in Kenya, Sri Lanka, and Yunnan provinces, exposing processors to climate-induced harvest volatility and quality inconsistency.
- Organic Certification Cost Structure:Pesticide-free cultivation requirements and third-party audit expenses add 15-25% to input costs, compressing margins for mid-tier extractors.
- Decaffeinated Substitute Threat:Botanical alternatives including rooibos and yerba mate extracts are capturing shelf space in functional beverage channels seeking stimulant-free positioning.
Strategic Opportunities
- India Domestic Market Expansion:FSSAI's streamlined caffeine labeling protocols are enabling concentrated extract penetration into household retail channels previously restricted to food service.
- Nutraceutical Convergence:Polyphenol standardization between 40-60% is opening pharmaceutical-grade applications for metabolic health supplements targeting aging populations in Japan.
- Direct-to-Brand Distribution:Ready-to-drink manufacturers are bypassing traditional flavor houses to contract directly with estate-integrated extractors for proprietary blend development.
Industry Challenges
- Extraction Chemistry Expertise Gap:Facilities struggle to recruit process engineers capable of optimizing solvent recovery rates under tightening EU F-Gas Regulation thresholds.
- GRAS Self-Affirmation Timeline:FDA documentation requirements for novel extraction formats delay US market entry by 18-24 months, constraining revenue recognition for innovative suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Essence Market |
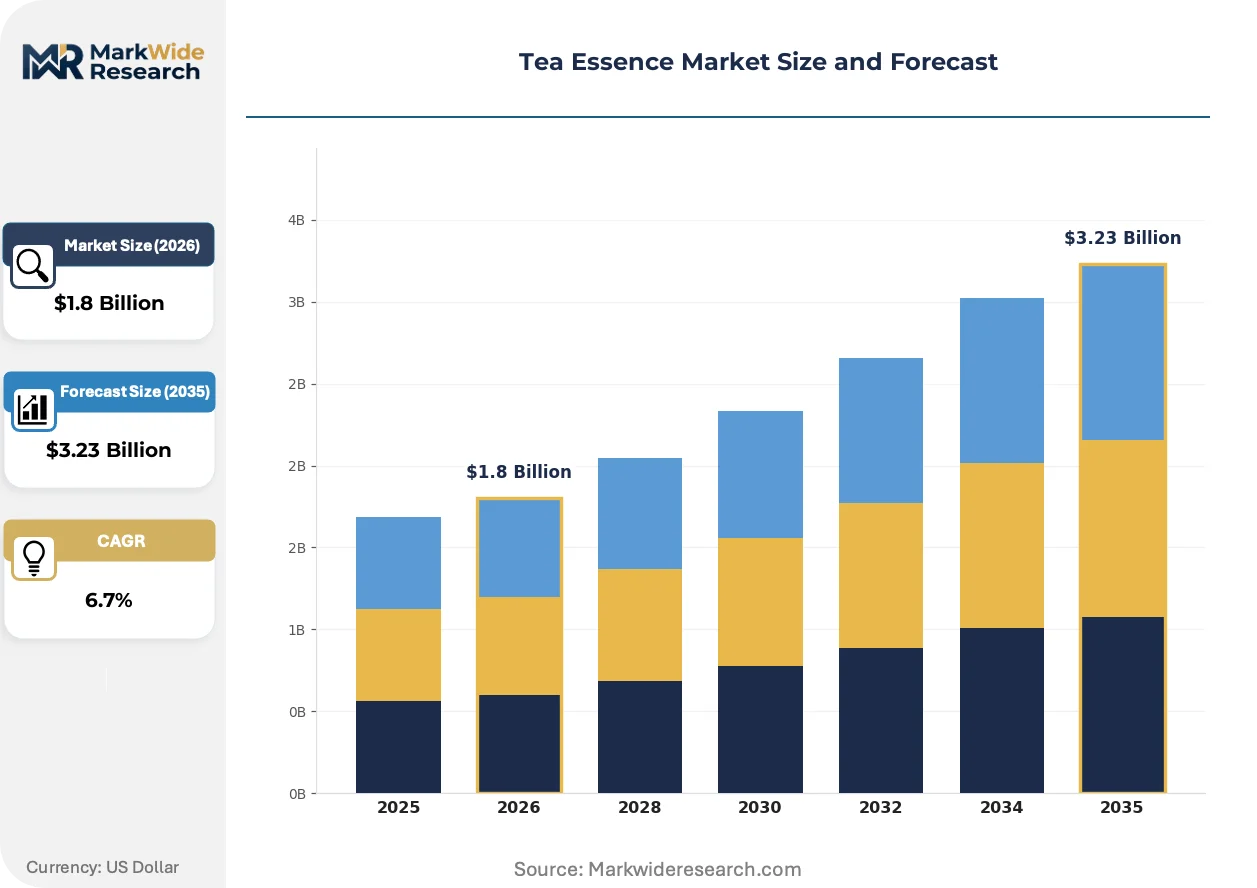
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Instant Tea, Liquid Extracts End User: Household, Food Service, Beverage Industry, Retail Extraction Method: Solvent Extraction, Steam Distillation, Cold Pressing, Infusion Packaging Type: Pouches, Boxes, Tins, Bulk Container |
| Companies Covered | Martin Bauer Group, Finlays, Archer Daniels Midland Company, Kemin Industries, Inc., Synthite Industries Ltd., Givaudan, Tata Tea, Unilever, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Essence Market Evolving Landscape
Processing technology and procurement models are restructuring competitive advantage around traceability, regulatory compliance, and application-specific standardization rather than commodity volume.
Supercritical CO2 extraction is consolidating technical leadership among premium extractors by preserving heat-sensitive catechins and volatile aromatic compounds that steam distillation degrades. Ready-to-drink brands seeking clean-label positioning are accelerating adoption of CO2-processed essences for their flavor fidelity. This technology is consolidating market position for facilities with capital to deploy high-pressure systems, compressing margins for conventional solvent-based operators.
EFSA's evolving Novel Food assessment protocols are extending approval timelines for innovative tea extraction formats entering European markets. The regulatory friction is redirecting R&D investment toward GRAS-affirmed US market entry or domestic Chinese certification under NMPA guidelines. Instant tea and functional beverage categories face the steepest compliance burdens, with some formulators retreating to established extraction methods rather than navigating extended safety evaluations.
Beverage manufacturers are fragmenting procurement across smaller botanical extractors with direct estate relationships rather than consolidating through integrated flavor houses. Specialty coffee chains and regional ready-to-drink brands are driving this disintermediation, seeking proprietary flavor profiles and supply transparency. China and South Korea exhibit the most pronounced supplier diversification, where domestic brands build captive extraction capacity to secure both beverage and cosmetics-grade output.
Tea Essence Market Segmentation
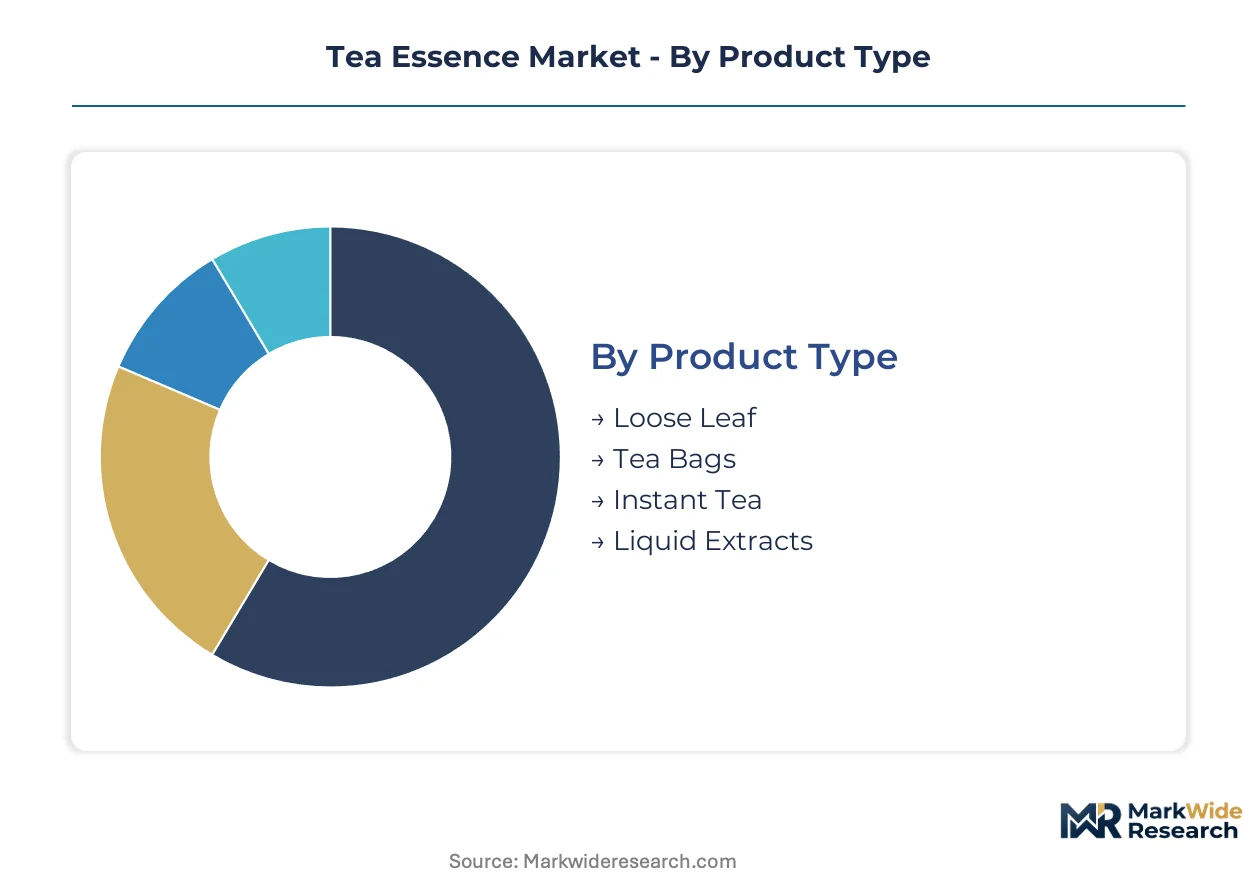
Tea essence manufacturers configure production lines around extraction chemistry and end-use specifications rather than commodity volume. Segmentation reveals where margin pools concentrate and which technical capabilities determine supplier selection.
Product Type:
Customization intensity varies from standardized commodity formats to precision-engineered liquid concentrates requiring co-development with beverage formulators.
- Liquid Extracts:Concentrated aromatic compounds standardized to 20-60% polyphenol content for industrial formulation. Beverage manufacturers in China and South Korea are contracting directly with estate-integrated extractors to secure proprietary flavor profiles and supply transparency.
- Instant Tea:Spray-dried or freeze-dried powders optimized for solubility and shelf stability. Solvent extraction dominates volume output here where cost efficiency outweighs organic certification premiums for multinational ready-to-drink brands.
- Loose Leaf:Minimally processed dried leaves retaining whole-leaf structure for premium brewing applications.
- Tea Bags:Finely cut leaf material in filter paper sachets for convenience-oriented household channels.
Most installed capacity flows through Instant Tea. Expansion is steepest in Liquid Extracts.
End User:
Channel requirements diverge sharply between regulated food service protocols and mass retail shelf stability demands.
- Beverage Industry:Concentrated extracts for ready-to-drink formulation requiring GRAS self-affirmation or EFSA Novel Food compliance. Procurement is consolidating around traceable supply chains as EU F-Gas Regulation tightens solvent recovery mandates for extraction facilities.
- Food Service:Bulk formats for hospitality and institutional brewing with standardized brewing protocols.
- Household:Retail-packaged products for direct consumer purchase, with India's FSSAI caffeine labeling mandates reshaping how brands position concentrated extracts.
- Retail:Branded packaged goods distributed through supermarket and specialty store channels.
Volume concentrates in Beverage Industry. Value expansion is fastest in Food Service as specialty coffee chains fragment procurement across smaller botanical extractors.
Extraction Method:
Capital intensity and regulatory compliance burdens separate commodity processors from premium positioning specialists.
- Solvent Extraction:Ethanol or hexane-based processing for high-yield polyphenol recovery. REACH framework compliance investments in closed-loop solvent systems are securing preferential supply contracts with multinational brands seeking regulatory certainty.
- Steam Distillation:Thermal separation of volatile terpenes for aromatic applications. Conventional operators face margin compression as supercritical CO2 technology consolidates technical leadership among premium extractors.
- Cold Pressing:Mechanical extraction preserving heat-sensitive compounds for organic certification markets.
- Infusion:Traditional hot water steeping for specialty and artisanal product positioning.
Most extraction capacity deploys Solvent Extraction. Steepest investment growth targets Steam Distillation advancement through supercritical CO2 systems.
Packaging Type:
Format selection tracks distribution economics and shelf-life requirements across channel tiers.
- Bulk Container:Industrial drums and totes for beverage manufacturing and food service procurement. Direct-to-brand distribution models are bypassing traditional flavor houses as ready-to-drink manufacturers seek estate-integrated supply relationships.
- Pouches:Flexible film packaging for single-serve and sample formats.
- Boxes:Paperboard secondary packaging for retail shelf presentation.
- Tins:Metal canisters for premium loose-leaf and gift positioning.
Volume flows through Bulk Container formats. Premium positioning drives fastest growth in Tins for specialty retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China extracts more tea essence volume than any other nation, yet India's regulatory streamlining is accelerating faster market penetration into household retail channels.
China
Domestic beverage brands and cosmetics manufacturers are building captive extraction facilities across Yunnan and Zhejiang provinces. NMPA enforces pesticide residue thresholds under GB standards that shape cultivation practices throughout growing regions. Hangzhou and Kunming host concentrated clusters where estate-integrated processors supply both ready-to-drink formulators and personal care companies.
India
FSSAI's streamlined caffeine labeling protocols are unlocking concentrated extract distribution into household retail previously restricted to food service. The regulator's 2023 notification reduced compliance burdens for packaged tea essence products. Assam and Darjeeling plantation networks anchor supply, with Mumbai and Delhi processing hubs expanding cold-chain distribution infrastructure.
United States
Functional beverage manufacturers are driving procurement of GRAS-affirmed concentrated extracts for metabolic health positioning. FDA self-affirmation timelines delay novel extraction format entry by 18-24 months, constraining supplier revenue recognition. New Jersey and California formulation clusters house multinational brand R&D centers that co-develop proprietary blends with estate-integrated extractors.
Germany
REACH framework compliance investments in closed-loop solvent systems are securing preferential supply contracts with multinational beverage brands. ECHA enforcement of F-Gas Regulation thresholds is forcing facility retooling across extraction operations. Hamburg and Bavaria host technical centers where process engineers optimize solvent recovery rates for EU market access.
South Korea
Personal care manufacturers are integrating catechin-rich tea essences into anti-aging product lines, expanding addressable market beyond traditional beverage channels. MFDS cosmetic ingredient regulations govern polyphenol standardization claims for topical applications. Seoul and Gyeonggi-do formulation clusters blend tea extracts with complementary botanicals for premium skincare positioning.
Tea Essence Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base fragments between estate-integrated extractors securing raw material traceability and flavor houses blending tea essences with complementary botanicals. Three archetypes dominate: plantation-backed processors, integrated flavor houses, and commodity-scale traders. Competitive moves concentrate on direct-to-brand distribution bypassing traditional intermediaries, alongside supercritical CO2 technology licensing for premium positioning.
Within the estate-integrated tier, Finlays and Tata Tea exemplify backward integration strategies. Finlays leverages Kenyan and Sri Lankan plantation networks to secure traceability for multinational beverage clients. Tata Tea anchors South Asian supply through its domestic plantation infrastructure and regional distribution reach. Givaudan occupies a distinct position as a flavor house specialist, representing the blending-and-formulation archetype rather than raw extraction.
| Leading Market Players |
|---|
| Martin Bauer Group |
| Finlays |
| Archer Daniels Midland Company |
| Kemin Industries, Inc. |
| Synthite Industries Ltd. |
| Givaudan |
| Tata Tea |
| Unilever |
| Nestle |
| Others |
Value Network & Pricing Analysis
Camellia sinensis leaf auction indices in Mombasa and Colombo set baseline input costs that cascade through extraction tiers, with polyphenol-standardized liquid extracts commanding premium multiples over solvent-extracted instant powders while REACH compliance investments reshape processor economics across European facilities.
Pricing Analysis
Capacity additions in Yunnan province are reshaping price floors for commodity-grade extracts, compressing margins for mid-tier processors unable to secure organic certification premiums. Three-tier pricing structure across premium CO2-extracted, standard solvent-extracted, and economy-grade instant tea separates facilities by extraction chemistry sophistication. Price differentiation hinges on polyphenol standardization precision and EU organic certification status. Cost compression in standard-grade segments is intensifying because Chinese domestic brands are building captive extraction capacity, while beverage multinationals exhibit lowest price sensitivity for traceable, regulatory-certain supply.
Supply Chain Analysis
Organic certification and REACH framework compliance function as qualification gates that filter supplier access to multinational beverage procurement channels. Raw material sourcing draws from Kenya, Sri Lanka, and Yunnan province, with Assam and Darjeeling anchoring specialty-grade supply. Processing inputs center on ethanol and hexane solvents, supercritical CO2 systems, and spray-drying infrastructure. Single-source vulnerability concentrates in Kenyan estate networks exposed to climate-induced harvest volatility. Distribution runs through bulk container formats to beverage manufacturing clusters, with direct-to-brand contracting displacing traditional flavor house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through supercritical CO2 technology licensing and captive cosmetics-grade supply, as premium extraction premiums widen against commodity solvent-extracted alternatives.
For Market Incumbents: Lock in estate-integrated supply relationships across Kenyan and Sri Lankan plantation networks before regional competitors consolidate traceable raw material access. Invest in closed-loop solvent recovery systems to secure preferential supply contracts under tightening EU F-Gas Regulation thresholds. Prioritize supercritical CO2 capacity additions to defend technical leadership against emerging Chinese domestic processors. For New Entrants and Emerging Players: Enter via South Korean cosmetics formulation channels where catechin-rich tea essence demand outpaces established supplier capacity. Target Indian household retail segments unlocked by FSSAI's streamlined caffeine labeling protocols. Pursue direct-to-brand distribution partnerships with regional ready-to-drink manufacturers seeking proprietary flavor profiles. For Investors and Strategic Acquirers: Asymmetric upside sits with estate-integrated processors possessing both plantation control and supercritical CO2 extraction capabilities. Long-term viability centers on facilities capable of serving dual beverage and cosmetics applications with regulatory-certain supply chains. Watch for inflection signals in EU EFSA Novel Food assessment timelines that could redirect R&D investment flows toward GRAS-affirmed US market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Technology Licensing | Preserves heat-sensitive catechins for premium beverage positioning against conventional solvent extraction. |
| Captive Extraction Facility Buildout | Chinese domestic brands secure supply transparency for both beverage and cosmetics-grade output requirements. |
| Closed-Loop Solvent System Investment | REACH compliance secures preferential contracts with multinational brands facing F-Gas Regulation enforcement. |
| Direct-to-Brand Distribution Model | Bypasses flavor house intermediaries to capture proprietary blend development margins with ready-to-drink manufacturers. |
| Dual-Certification Capacity Expansion | Organic plus pharmaceutical-grade polyphenol standardization opens nutraceutical applications in aging Japanese markets. |
Research Methodology
Coverage spans China, India, Kenya, Sri Lanka, and Germany, with primary inputs from each major production and regulatory jurisdiction. The research combined structured interviews with extraction facility process engineers, beverage formulation R&D directors, cosmetics product development leads, and plantation network procurement managers. Secondary validation drew from NMPA GB standard filings, EFSA Novel Food assessment registers, FSSAI notification databases, and Kenya Tea Development Agency auction records. Bottom-up capacity and utilization estimates were triangulated against top-down consumption projections across end-use segments.
Granularity was maintained at the extraction-method-by-application level, modeling solvent extraction, steam distillation, and supercritical CO2 outputs separately for beverage, cosmetics, and nutraceutical channels. CAGRs were derived from trend extrapolation of procurement volumes against capacity expansion pipelines and regulatory approval timelines. Forecast inputs incorporated EU F-Gas Regulation implementation schedules, NMPA pesticide residue enforcement patterns, and GRAS self-affirmation documentation trajectories.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time Chinese domestic captive capacity buildout rates introduce uncertainty bands around medium-term supply projections. Forecasts reflect documented assumptions regarding REACH compliance investment pacing and EFSA assessment timeline stability. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement thresholds or NMPA GB standard revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Packaging Market
Tea
APAC RTD Tea Market
Tea
White Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Tea Subscription Market
Tea
Light-Fermented Tea Market
Tea
Natural Tea Extract Market
Tea
Moringa Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Out of Home Tea Market
Tea
Slimming Tea Market
Tea
China Tea Market
Tea
Oolong Tea Market
Tea
Fermented Tea Market
Tea
Black Tea Extracts Market
Tea
Green Tea Market