
 Tea Pitchers Market | 2026-2036
Tea Pitchers Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Pitchers Market Analytics
The gap between hand-blown borosilicate pitchers and mass-market molded vessels is consolidating around thermal shock resistance, pour precision, and artisanal provenance. Takeya leverages Japanese design heritage to anchor its position in cold-brew specialization. Hiware competes through direct-to-consumer channel control and aggressive pricing on extra-large capacity formats. Pyrex sustains brand recognition by extending laboratory-grade thermal durability into consumer kitchen applications.
Tea pitchers are lidded serving vessels engineered from glass, ceramic, stainless steel, or plastic, typically incorporating infusion cores or filters and rated for temperature differentials exceeding 120 degrees Celsius to enable direct hot-water brewing. Their primary commercial purpose spans controlled extraction timing in foodservice environments and aesthetic beverage presentation in hospitality settings. Glass dominates household preference where visual monitoring of steeping color matters, while stainless steel leads cafe procurement for impact resistance during high-volume service. The design style dimension shows modern minimalist forms commanding margin premiums in urban markets, whereas traditional ceramic shapes retain loyalty in heritage tea-shop segments.
FDA food-contact substance regulations govern plastic and ceramic glazing compliance for US-bound products, while EU REACH restrictions on heavy metals in decorative coatings constrain ceramic export formulations. China's GB standards for food-contact glass and SAMR product safety labeling create additional certification layers for cross-border manufacturers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and material disclosure requirements that will reshape supplier qualification criteria and inventory risk profiles.
Market Dynamics
Specialty cafes and tea shops are consolidating procurement around vessels that withstand thermal shock while satisfying aesthetic presentation requirements, compressing supplier margins on undifferentiated molded glass.
Growth Catalysts
- Cold-brew format expansion:Cafes are expanding dedicated cold-brew menu lines, driving replacement cycles for purpose-built pitchers with extended infusion cores and precision pour spouts.
- Bisphenol A restrictions:EU REACH and US FDA tightening on food-contact plastics is accelerating migration toward borosilicate glass and ceramic alternatives in export-bound production.
- China domestic premiumization:Urban tea culture in Shanghai and Hangzhou is displacing low-cost plastic vessels with artisanal ceramic and hand-blown glass formats.
Market Restraints
- Borosilicate raw material concentration:High-grade thermal glass feedstock concentrates among German and Chinese chemical suppliers, exposing molders to input volatility.
- Artisanal production bottlenecks:Hand-blown vessel output remains capped by skilled glassbower availability, constraining premium segment scale.
- Stainless steel substitution in foodservice:Impact-resistant metal pitchers are displacing glass in high-volume cafe environments where breakage costs dominate lifetime value calculations.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging state-level mandates in California and New York will reward modular, repairable designs with preferential retail placement.
- Smart vessel integration:Temperature-sensing ceramics and Bluetooth-enabled steeping timers are converging with wellness app ecosystems to create subscription-linked hardware.
- Southeast Asia cafe buildout:Vietnam and Indonesia specialty coffee chains are importing premium vessel specifications previously concentrated in East Asian markets.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EU REACH, and China GB compliance testing extends product launch cycles by eight to fourteen months.
- Decorative coating heavy metal testing:Ceramic glaze formulations require iterative lab validation to meet evolving ECHA restrictions on cadmium and lead migration limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Pitchers Market |
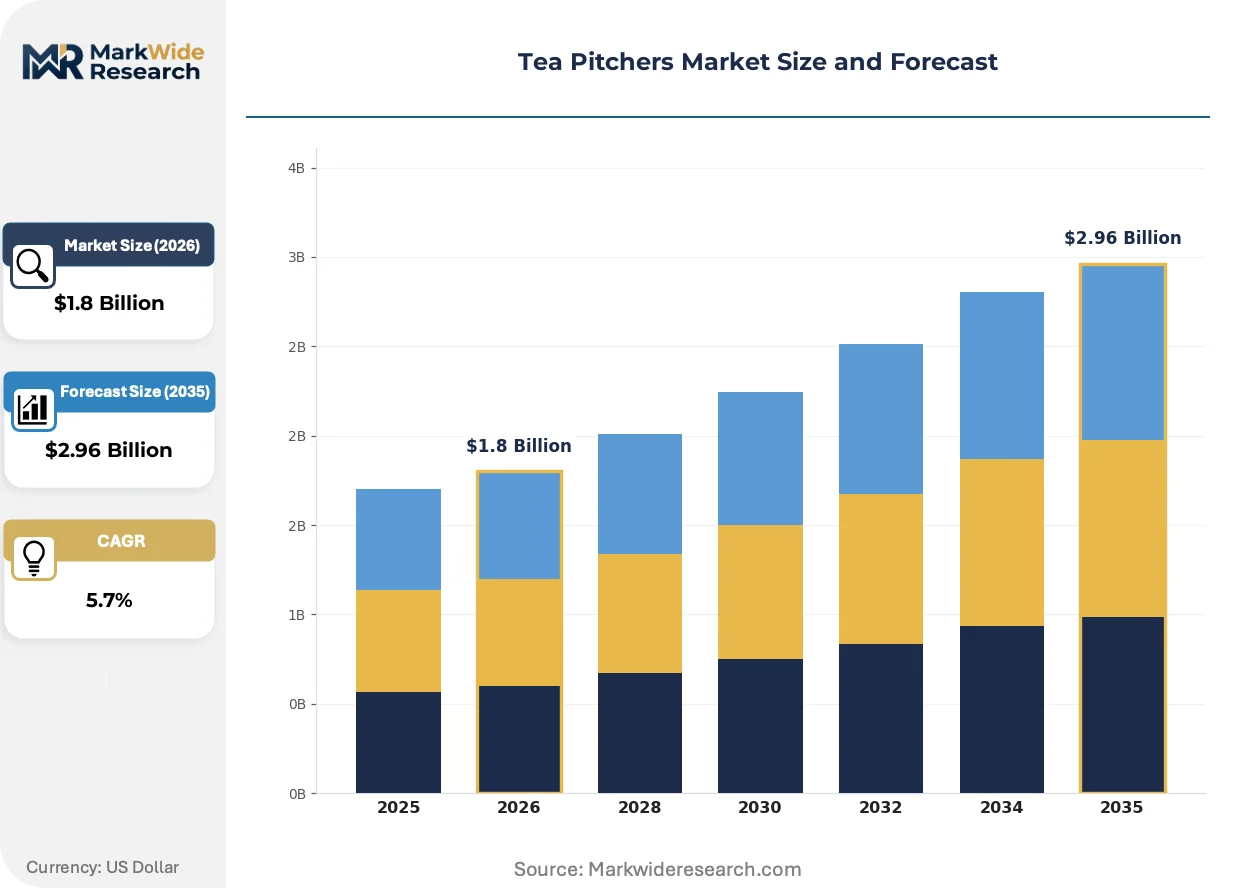
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Ceramic, Stainless Steel, Plastic Design Style: Modern, Traditional, Minimalist, Vintage Capacity: Small, Medium, Large, Extra Large End User: Households, Cafes, Restaurants, Tea Shops |
| Companies Covered | Takeya, Komax, IKEA, Hiware, Artcome, Pratico, Libbey, Pyrex, Anchor Hocking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Pitchers Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are jointly reshaping vessel composition, while channel consolidation among specialty beverage retailers is altering how specifications reach end-users.
Borosilicate glass with laser-etched volume markers is absorbing functionality previously delivered by separate measuring tools. High-end home barista segments are adopting these integrated formats fastest, with direct-to-consumer brands reporting strongest uptake among urban apartment dwellers. The technology is absorbing accessory spend into core vessel purchases, compressing the addressable market for standalone tea timers and thermometers.
EU REACH Annex XVII restrictions on heavy metals in decorative coatings are forcing ceramic producers to reformulate traditional glaze chemistries. Industrial consequence includes elevated R&D overhead and extended product qualification periods. Heritage tea-shop segments in France and Italy are responding by emphasizing unglazed stoneware and raw clay aesthetics that bypass coating compliance entirely.
Direct sourcing between specialty roasters and vessel manufacturers is collapsing traditional kitchenware distributor tiers. Roasters in Melbourne, Portland, and Copenhagen are specifying custom co-branded pitchers as loyalty program anchors. This pattern is most visible in single-origin tea subscription services where unboxing experience drives retention metrics and vessel design becomes a marketing asset rather than commodity procurement.
Tea Pitchers Market Segmentation
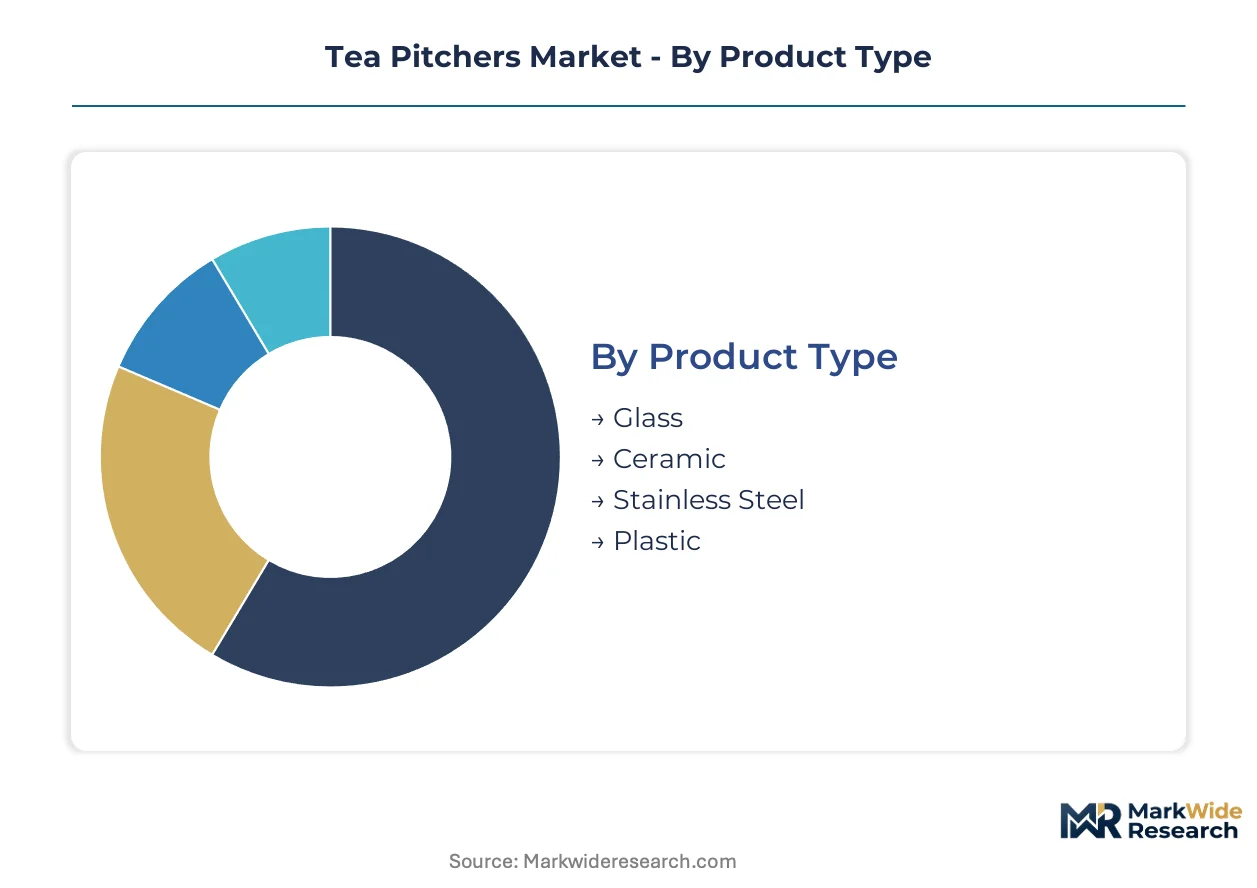
Tea pitcher segmentation reveals how capital deployment, thermal performance requirements, and aesthetic positioning fragment manufacturing strategies. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier specialization.
Product Type:
Glass and ceramic segments demand the heaviest upfront capital for kiln infrastructure and precision molding equipment, while metal and plastic alternatives run on lower tooling thresholds but higher per-unit material costs.
- Glass:Borosilicate formulations rated for thermal shock exceeding 120 degrees Celsius dominate household procurement where steeping visibility matters. Demand concentrates in China as urban consumers replace plastic vessels with hand-blown artisanal formats; EU REACH compliance on heavy metals in decorative coatings adds certification overhead for export-bound production.
- Ceramic:Unglazed stoneware and traditional glazed formats serve heritage tea-shop segments in France and Italy. Raw clay aesthetics are gaining traction as producers bypass ECHA coating restrictions entirely; Hangzhou and Jingdezhen workshops anchor artisanal supply.
- Stainless Steel:Impact-resistant vessels displace glass in high-volume Melbourne and Portland cafe environments where breakage costs dominate lifetime value calculations.
- Plastic:Bisphenol A restrictions under FDA and EU REACH are accelerating migration toward glass and ceramic alternatives; residual demand concentrates in entry-level household segments.
Glass absorbs the bulk of installed capacity; ceramic is expanding most quickly as heritage aesthetics bypass coating compliance costs.
Design Style:
Style differentiation maps directly to customer acquisition cost tiers, with modern and minimalist formats commanding premium shelf placement in direct-to-consumer channels while traditional shapes retain loyalty through lower marketing spend.
- Modern:Clean geometric lines with integrated laser-etched volume markers absorb functionality from separate measuring tools. Copenhagen and Portland roasters specify these as subscription program anchors where unboxing experience drives retention.
- Minimalist:Stripped-down forms with hidden infusion cores dominate Japanese-influenced cold-brew specialization. Urban apartment dwellers in Shanghai and Tokyo represent the steepest expansion trajectory for this segment.
- Traditional:Ornate handles and heritage glaze patterns retain procurement loyalty among French and Italian tea-shop segments; lower digital marketing intensity sustains margin.
- Vintage:Reproduction early-20th-century forms serve hospitality staging and gift-market occasions; seasonal demand concentration requires flexible production scheduling.
Modern and minimalist formats together capture the highest customer lifetime value; vintage styling shows the most pronounced demand seasonality.
Capacity:
Volume specifications align with brewing ritual frequency and serving context, creating distinct procurement patterns between single-serve household formats and batch-production foodservice scales.
- Small:Single-serve 300-500ml vessels dominate Japanese and Korean personal tea ceremonies. Compact footprints suit urban apartment storage constraints in Tokyo and Seoul.
- Medium:Standard 800-1200ml formats balance household flexibility with moderate entertaining needs; replacement cycles align with moving patterns in rental-heavy markets.
- Large:1500-2000ml vessels serve family households and small cafe tables; thermal retention engineering becomes critical at this scale.
- Extra Large:Batch-format 2500ml+ pitchers anchor cold-brew menu lines in Vietnamese and Indonesian specialty chains importing East Asian specifications.
Medium capacity moves the highest unit volumes; extra large formats are climbing the fastest as Southeast Asian cafe buildout accelerates.
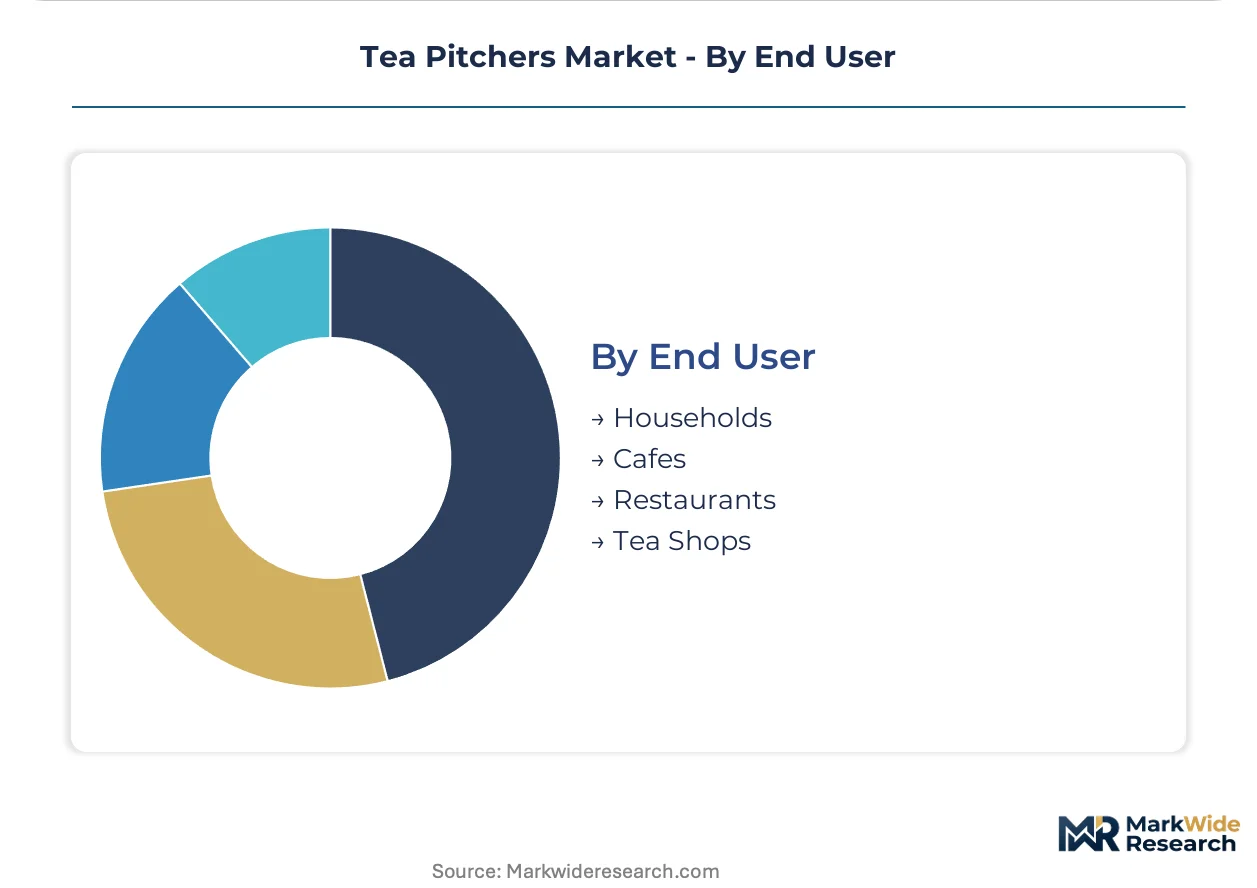
End User:
Buyer type determines specification rigor, with foodservice procurement emphasizing durability certification and household segments prioritizing aesthetic differentiation and steeping visibility.
- Households:Visual monitoring of tea color and integrated measurement features drive glass preference. Direct-to-consumer brands report strongest uptake among urban apartment dwellers seeking space-efficient multifunction vessels.
- Cafes:Thermal shock resistance and precision pour engineering dominate Melbourne, Portland, and Copenhagen specialty roaster specifications. Co-branded custom vessels function as loyalty program anchors.
- Restaurants:Front-of-house presentation requirements favor ceramic and glass; back-of-house brewing stations increasingly specify stainless steel for impact resistance.
- Tea Shops:Heritage segments in Hangzhou and Paris emphasize artisanal provenance and traditional ceramic shapes; modern formats in Shanghai prioritize minimalist glass with precision pour control.
Households generate the broadest SKU diversification; cafes are driving the most concentrated specification consolidation around thermal performance and co-branding compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hangzhou anchors artisanal tea pitcher manufacturing through Jingdezhen ceramic workshops and precision glassblowing clusters serving domestic premiumization and export markets simultaneously.
China
Urban tea culture in Shanghai and Hangzhou drives replacement of plastic vessels with hand-blown borosilicate and artisanal ceramic formats. SAMR product safety labeling and GB standards for food-contact glass create certification layers for cross-border manufacturers. Jingdezhen workshops concentrate heritage ceramic output while Yangtze River Delta molders scale thermal glass production.
United States
Specialty roasters in Portland and Melbourne-source specifications consolidate procurement around thermal shock-resistant vessels with precision pour engineering. FDA food-contact substance regulations govern plastic and ceramic glazing compliance for domestic-bound production. Pacific Northwest direct-to-consumer brands absorb standalone accessory spend into integrated vessel purchases.
Germany
High-grade borosilicate raw material supply concentrates among German chemical suppliers, exposing molders to input volatility and price negotiation pressure. EU REACH Annex XVII restrictions on heavy metals in decorative coatings constrain ceramic export formulations. Bavarian laboratory glass heritage extends into consumer kitchen applications through thermal durability engineering.
Japan
Minimalist cold-brew specialization dominates Tokyo and Osaka urban apartment segments where compact footprints suit storage-constrained dwellings. METI standards alignment with international thermal shock testing protocols facilitates export qualification. Kanto region design houses leverage heritage craft positioning for premium-margin capture.
Vietnam
Southeast Asian cafe buildout imports premium vessel specifications previously concentrated in East Asian markets, with 2500ml+ batch formats climbing fastest. General food-contact material regulations govern import compliance as specialty coffee chains expand. Ho Chi Minh City roasters specify co-branded vessels as loyalty program anchors mirroring Copenhagen and Portland patterns.
Tea Pitchers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal performance certification and artisanal provenance dimensions, compressing mid-tier positioning. The vendor base separates into three strategic archetypes: heritage laboratory glass extenders, direct-to-consumer channel controllers, and Japanese-influenced design specialists. Dominant competitive moves include co-branding partnerships with specialty roasters and modular repairable design investment anticipating extended producer responsibility mandates.
Among heritage-anchored fabricators, Pyrex exemplifies laboratory-grade thermal durability extension into consumer applications. Takeya occupies a position within Japanese-influenced cold-brew specialization. Hiware represents direct-to-consumer channel control with aggressive capacity format positioning.
| Leading Market Players |
|---|
| Takeya |
| Komax |
| IKEA |
| Hiware |
| Artcome |
| Pratico |
| Libbey |
| Pyrex |
| Anchor Hocking |
| Others |
Value Network & Pricing Analysis
Cafe procurement consolidation around thermal shock certification and precision pour engineering is compressing margins on undifferentiated molded glass while elevating price premiums for artisanal provenance. Suppliers must absorb multi-jurisdiction compliance testing overhead or cede positioning to certified competitors.
Pricing Analysis
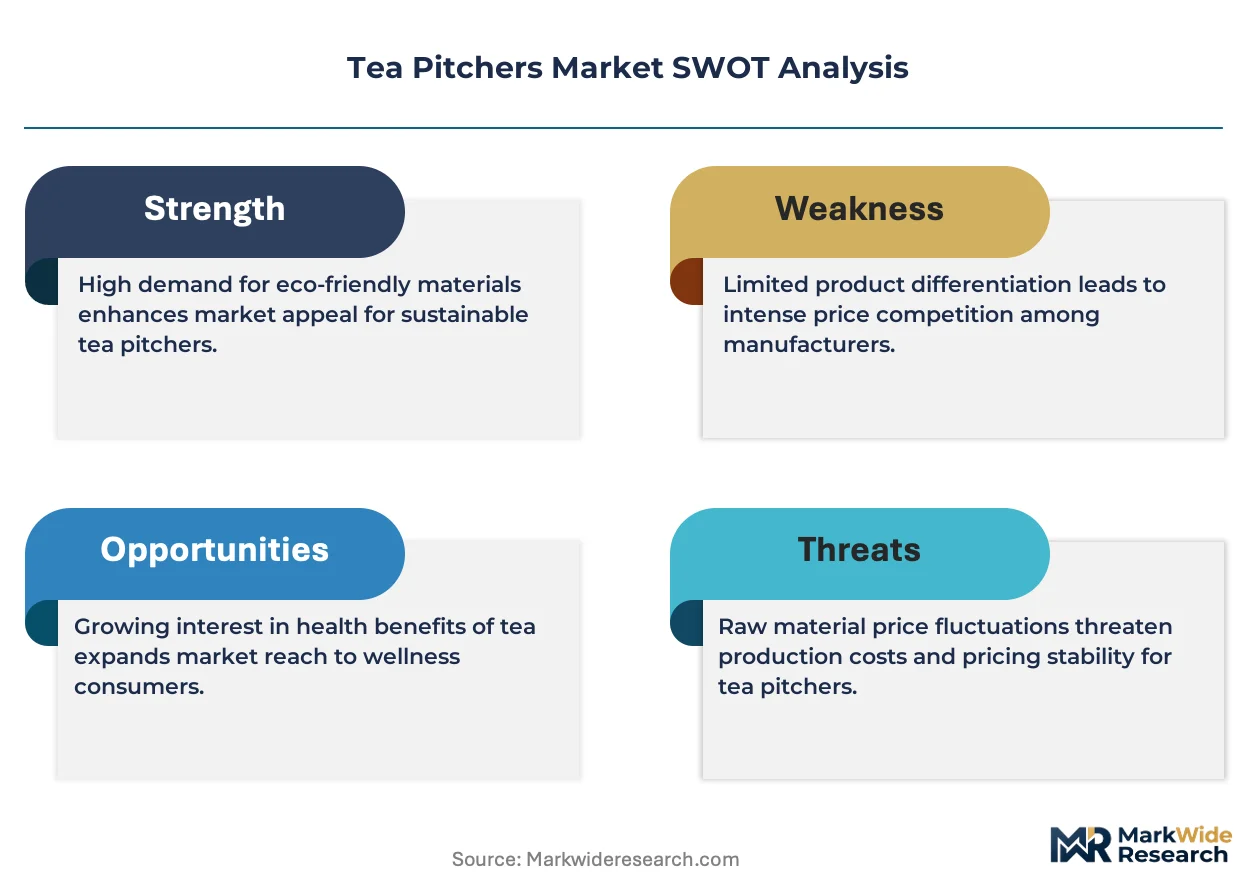
Value-based pricing anchored to thermal performance certification and steeping precision separates premium hand-blown borosilicate from commodity alternatives. Three-tier pricing structure across certified artisanal, standard thermal-grade, and entry-level plastic tiers reflects differentiation by GB/FDA compliance tier and volume scale. Pricing pressure stems from stainless steel substitution in high-volume foodservice where breakage cost calculations favor metal lifetime value. Household segments show highest price sensitivity for undifferentiated formats; specialty roasters exhibit lowest sensitivity for co-branded custom specifications.
Supply Chain Analysis
High-grade borosilicate feedstock rests on German chemical suppliers and Yangtze River Delta glassworks, exposing molders to input volatility. Raw material dependencies center on thermal glass precursors, ceramic clay from Jingdezhen deposits, and stainless steel sheet from South Korean mills. Single-source vulnerability concentrates in artisanal glassbower availability constraining premium segment scale. Distribution runs through direct sourcing partnerships between specialty roasters and vessel manufacturers, collapsing traditional kitchenware distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled glassbower scarcity caps hand-blown output, propping pricing premiums for certified thermal performance vessels as demand outstrips artisanal production capacity.
For Market Incumbents: Anchor positioning through backward integration into Jingdezhen ceramic workshops or Yangtze River Delta thermal glass facilities to secure capacity. Invest in modular repairable designs anticipating California and New York extended producer responsibility mandates. Defend against stainless steel substitution by emphasizing steeping visibility and co-branding compatibility with specialty roaster loyalty programs. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling offers the most penetrable route, targeting urban apartment dwellers in Shanghai and Tokyo with space-efficient multifunction vessels. White-space exists in Southeast Asian cafe buildout importing East Asian premium specifications. Pursue Vietnamese and Indonesian specialty chains with 2500ml+ batch formats and co-branded unboxing experience design. For Investors and Strategic Acquirers: The window for entry favors direct-to-consumer channel controllers with GB/FDA dual certification and artisanal provenance narratives. Long-term viability hinges on regulatory compliance infrastructure and roaster relationship depth. Watch for ECHA heavy metal restriction tightening as inflection indicator accelerating ceramic glaze reformulation costs and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Branded Custom Vessel Development | Specialty roasters in Portland and Copenhagen deploy vessels as subscription retention anchors. |
| Modular Repairable Design Investment | California EPR frameworks reward repairable formats with preferential retail placement. |
| Dual Certification Infrastructure Buildout | Simultaneous FDA and GB compliance accelerates product launch cycles versus single-market competitors. |
| Artisanal Provenance Narrative Marketing | Hangzhou and Jingdezhen heritage positioning commands margin premiums in urban Chinese markets. |
| Southeast Asian Distribution Partnership | Vietnamese and Indonesian cafe chains import premium specifications previously concentrated in East Asia. |
Research Methodology
Independent corroboration across specialty roaster procurement directors, ceramic workshop owners in Jingdezhen, and thermal glass plant managers underwrites the qualitative findings. Primary interviews with cafe operators, kitchenware category buyers, and regulatory compliance officers combined with secondary validation from SAMR product safety filings, EU REACH Annex XVII updates, and customs trade data. Bottom-up vessel shipment analysis triangulates against top-down market sizing across material type, design style, capacity tier, and end-user segment.
Comparable-period anchoring to replacement cycle patterns and premiumization trajectories structures the projection framework. Segmentation modeling spans material composition, thermal performance certification tier, design archetype, capacity specification, and geographic demand cluster. CAGRs derive from installed base turnover rates and format migration elasticity. Forecast inputs incorporate Bisphenol A regulatory phase-out timelines and Southeast Asian cafe buildout pipeline data.
The model holds under steady regulatory enforcement and artisanal production capacity constraints; deviation in ECHA heavy metal restriction severity or Yangtze River Delta glassworks expansion would shift premium segment availability. Forecasts reflect assumptions on compliance cost pass-through and roaster co-branding adoption curves. A small set of named triggers—skilled glassbower wage inflation, state-level EPR mandate acceleration, and stainless steel cold-brew format innovation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Fermented Tea Market
Tea
Organic Tea Market
Tea
Green Tea Bag Market
Tea
Smart Tea Maker Market
Tea
Black Tea Extracts Market
Tea
Asia-Pacific Green Tea Market
Tea
Global Tea Extract Market
Tea
Tea Polyphenols Market
Tea
Tea Subscription Market
Tea
Butterfly Pea Flower Tea Market
Tea
Out of Home Tea Market
Tea
Tea Concentrate Market
Tea
Spray-Dried Tea Products Market
Tea
Slimming Tea Market
Tea
Detox Tea Market
Tea
Europe Green Tea Market