
 Butterfly Pea Flower Tea Market | 2026-2036
Butterfly Pea Flower Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Butterfly Pea Flower Tea Market Outlook
Synthetic food dyes is recalibrating cost structures across natural colorant supply chains. EverforEver Biotech leverages its biotech extraction capabilities to secure pharmaceutical-grade supply contracts. Tea Trunk anchors its brand identity around single-origin butterfly pea sourcing from Southeast Asian cooperatives. Blue Tea dominates direct-to-consumer channels through specialized wellness positioning.
Butterfly pea flower tea comprises dried Clitoria ternatea florets, valued for anthocyanin concentrations exceeding 13% dry weight that produce pH-dependent color shifts from deep blue to violet. The primary commercial purpose centers on natural colorant applications across beverages, cosmetics, and functional food formulations. Loose leaf formats command premium shelf positioning in specialty retail, while extract segments capture the fastest expansion through nutraceutical and cosmetic ingredient demand. Powder variants occupy economy-tier positioning for bulk foodservice procurement.
Thailand's FDA-equivalent food safety authority governs raw material export certification, while the EU EFSA Novel Food framework determines European market access timelines for new ingredient applications. The US FDA color additive regulations classify butterfly pea extract under petition-reviewed status, creating compliance differentiation between approved and pending suppliers. Stakeholders must monitor regulatory approval cascades across target jurisdictions before committing to capacity expansion or formulation investments.
Market Dynamics
The butterfly pea flower tea market pivots on regulatory approval cascades across major import jurisdictions, where EFSA Novel Food timelines and FDA color additive petitions create supply bottlenecks that concentrate procurement power among pre-certified Thai exporters.
Growth Catalysts
- EU Novel Food pathway maturation:EFSA's evolving guidance on Clitoria ternatea extracts accelerates market access for compliant suppliers, expanding foodservice formulation opportunities across member states.
- Mixology sector expansion:Premium cocktail bars in North American and European urban centers drive bulk extract procurement for pH-reactive beverage presentations.
- Anthocyanin standardization:Advances in spectrophotometric assay protocols enable consistent 13%+ dry weight certification, unlocking pharmaceutical-grade supply contracts.
Market Restraints
- Raw material geographic lock-in:Thailand's dominance of Clitoria ternatea cultivation creates monopsony risk for international buyers dependent on single-origin supply.
- FDA petition backlog:Pending color additive regulation status restricts US food and beverage applications to dietary supplement categories, compressing addressable market width.
- Synthetic dye cost competition:FD&C Blue No. 1 maintains 60-80% lower unit economics for mass-market food manufacturers, limiting natural colorant penetration in economy-tier segments.
Strategic Opportunities
- Cosmeceutical ingredient pivot:Anthocyanin-rich extracts command 4-7x pricing multiples in topical skincare formulations versus beverage applications, attracting R&D investment from Korean and Japanese beauty manufacturers.
- Direct-to-consumer subscription models:Specialty tea brands bypass wholesale margin compression through curated wellness boxes targeting North American and European urban consumers.
- Carbon credit stacking:Thai cooperative farming operations integrate Clitoria ternatea into agroforestry systems eligible for voluntary carbon market certification, offsetting input costs.
Industry Challenges
- Phytochemical assay standardization:Inconsistent delphinidin-3,5-glucoside quantification methods across ISO-accredited laboratories create batch rejection risk at import clearance.
- Cold chain infrastructure gaps:Extract stability requirements for anthocyanin preservation demand refrigerated logistics investment that exceeds working capital capacity of mid-tier distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butterfly Pea Flower Tea Market |
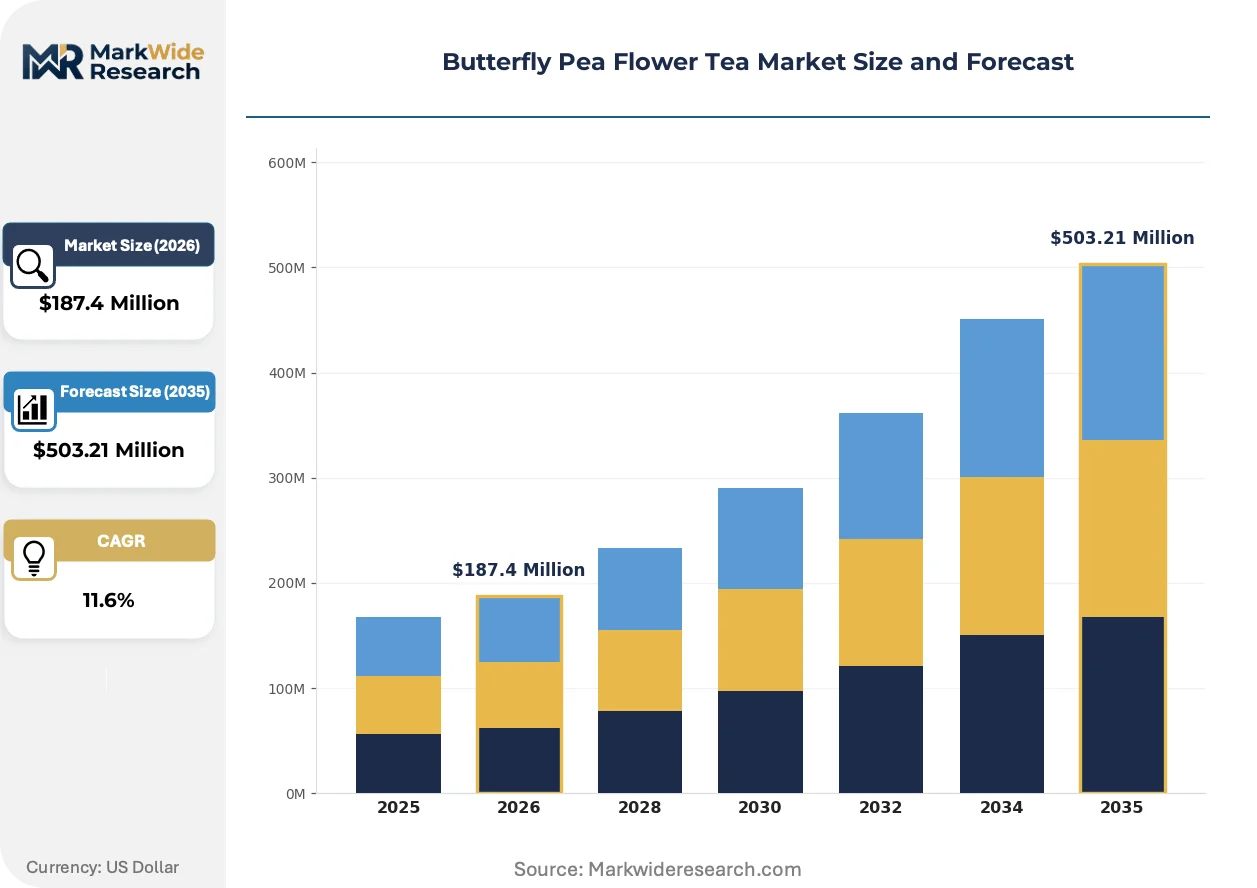
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Powder, Extract Flavor Profile: Floral, Earthy, Sweet, Herbal Application: Beverages, Cosmetics, Culinary, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | EverforEver Biotech, Tea Trunk, Blue Tea, Wild Hibiscus Flower Co., Specialty Natural Products Public Company Limited, Revival Tea Company, Paraman Food Works, Woodland Foods, Bigelow Tea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butterfly Pea Flower Tea Market Strategic Shifts
Technology and regulatory frameworks are compressing traditional supply hierarchies in butterfly pea flower tea, with extraction methods and compliance protocols now determining competitive access rather than raw volume or commodity trading relationships.
Supercritical CO2 extraction systems are modularizing downstream processing capabilities for mid-scale Thai processors. Equipment manufacturers from Germany and Italy now offer 50-200 liter skid-mounted units that reduce capital barriers for GMP-certified extract production. This technology diffusion is fragmenting what had been a concentrated pharmaceutical-grade supply tier.
EFSA's 2023-2024 Novel Food guidance updates clarified safety data requirements for Clitoria ternatea flower preparations, compressing approval timelines for applicants with existing toxicology dossiers. European food manufacturers are accelerating formulation trials ahead of anticipated 2025-2026 positive opinions, stockpiling raw material through Thai direct contracts.
Specialty coffee roasters and third-wave tea houses are displacing traditional wholesale distributors as primary volume aggregators. Bangkok-based exporters now maintain dedicated account teams for Melbourne, Portland, and Copenhagen hospitality clusters, bypassing conventional import brokerage relationships that had captured 15-25% margin layers.
Butterfly Pea Flower Tea Market Segmentation
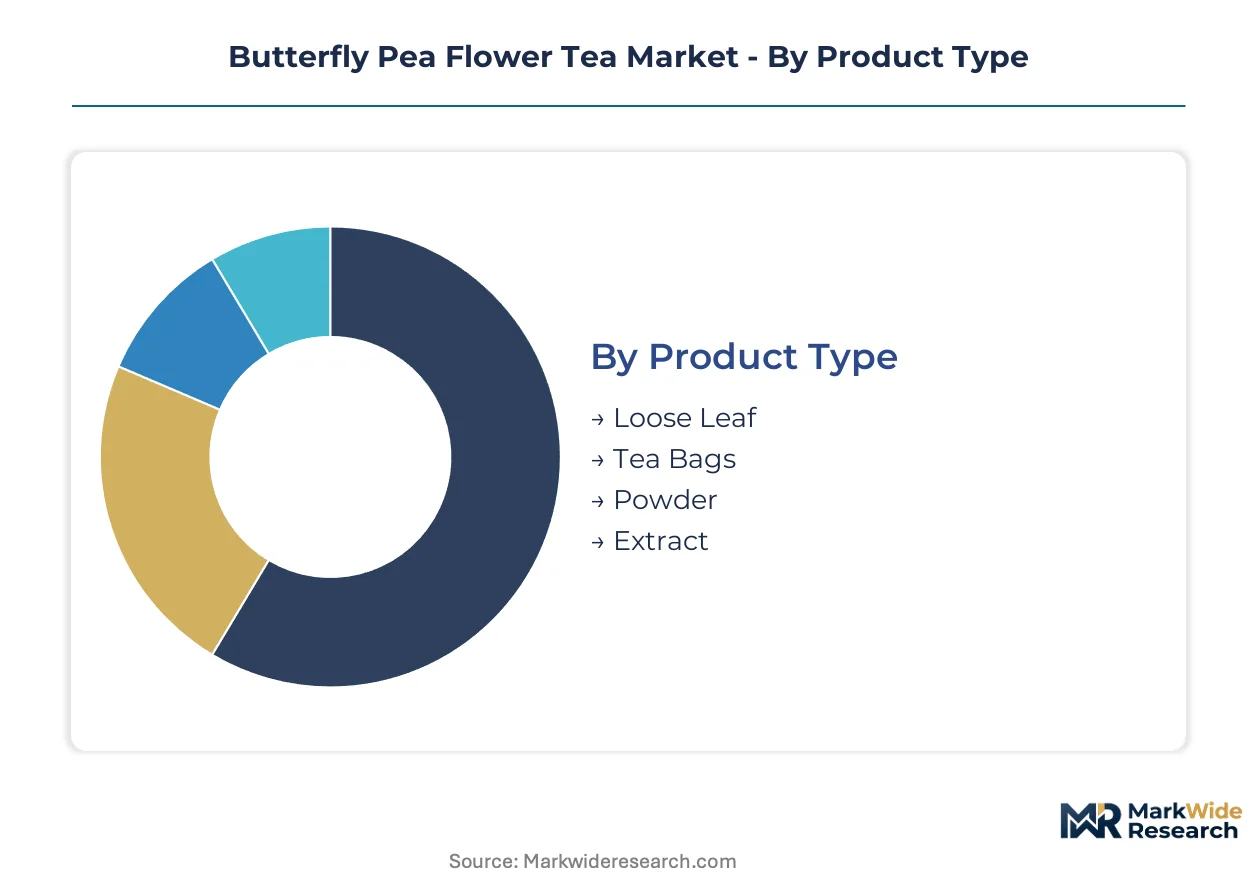
Segmentation in butterfly pea flower tea reveals how anthocyanin concentration and format stability determine margin capture across end-use applications. Product form and distribution channel selection directly shape regulatory compliance burdens and customer acquisition economics.
Product Type:
Volume concentrates in bulk formats for foodservice and manufacturing procurement, while premium positioning clusters around single-origin loose leaf for direct-to-consumer channels.
- Loose Leaf:Whole dried Clitoria ternatea florets retain maximum anthocyanin integrity above 13% dry weight. Specialty tea houses in Copenhagen, Melbourne, and Portland drive procurement through direct Thai cooperative contracts, bypassing traditional import brokers.
- Extract:Standardized liquid and powder concentrates enable precise dosing for pH-reactive cocktail formulations and cosmetic actives. Korean and Japanese beauty manufacturers command 4-7x pricing multiples versus beverage applications, making this the fastest-expanding segment through nutraceutical and cosmeceutical demand.
- Tea Bags:Convenience positioning targets urban wellness consumers through subscription models. Heat-sealed sachet formats sacrifice some anthocyanin potency for portion control consistency.
- Powder:Economy-tier bulk positioning serves foodservice and commercial baking applications. Lower unit economics reflect reduced extraction purity and shorter shelf stability.
Today's leader: Loose Leaf. Tomorrow's challenger: Extract.
Flavor Profile:
Flavor positioning tracks closely with end-use application requirements and regional palate preferences in key import markets.
- Floral:Delicate aroma notes dominate North American and European specialty retail positioning. Thai cultivars with higher terpene content command premium shelf placement.
- Earthy:Deeper, vegetal profiles align with traditional Ayurvedic and Southeast Asian consumption patterns. Indian and Thai domestic markets sustain consistent demand.
- Sweet:Mild, honeyed undertones suit blended beverage formulations where butterfly pea serves as colorant rather than dominant flavor. Mixology applications in premium cocktail bars favor this profile.
- Herbal:Neutral, grassy bases function as canvas ingredients for functional food fortification. Nutraceutical manufacturers prefer this profile for masking with other actives.
Current volume anchor: Floral. Emerging preference shift: Sweet.
Application:
Application segmentation reflects divergent regulatory pathways and technical specification requirements across end-use categories.
- Beverages:pH-reactive color-changing properties drive mixology sector adoption. EFSA Novel Food approval timelines and FDA color additive petition status determine market access breadth for ready-to-drink formulations.
- Cosmetics:Anthocyanin antioxidant properties command premium ingredient pricing in topical skincare. Stability requirements demand refrigerated logistics investment that filters mid-tier distributor participation.
- Culinary:Natural food coloring applications in artisan baking and plating compete directly with synthetic FD&C Blue No. 1 on cost, limiting penetration to premium positioning.
- Nutraceuticals:Standardized extract specifications for supplement capsules require GMP-certified production that concentrates supply among Thai processors with modular supercritical CO2 extraction capabilities.
Revenue concentration: Beverages. Margin expansion: Cosmetics.
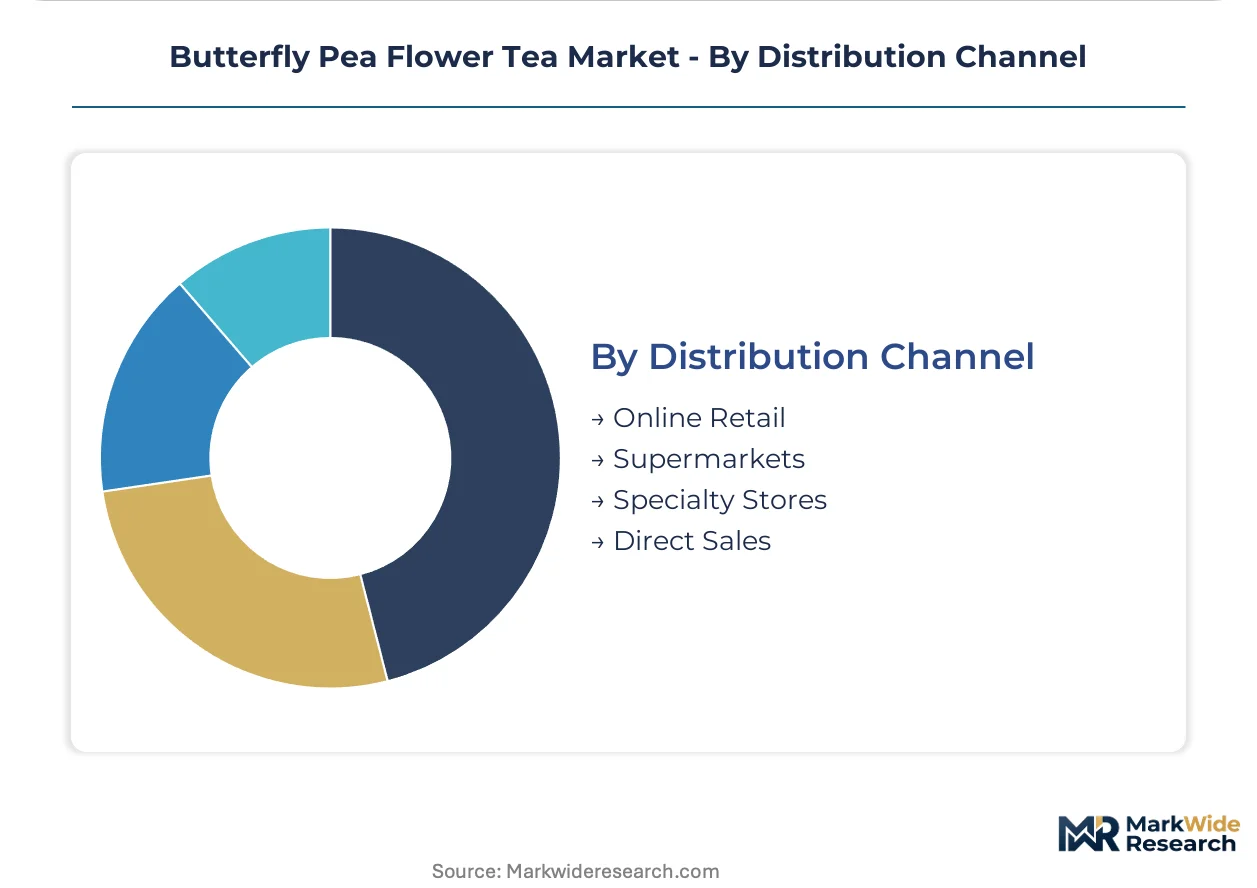
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct models displacing traditional wholesale hierarchies.
- Online Retail:Subscription wellness boxes and direct-to-consumer platforms enable specialty brands to bypass 15-25% wholesale margin compression. North American and European urban consumers drive volume through curated discovery formats.
- Specialty Stores:Third-wave tea houses and premium grocers provide education-intensive purchase environments. Bangkok-based exporters now maintain dedicated account teams for key accounts in Melbourne, Portland, and Copenhagen.
- Supermarkets:Mass retail placement requires economy-tier pricing and conventional food additive regulatory status. FDA petition backlog restricts US supermarket penetration to supplement aisle positioning.
- Direct Sales:Foodservice and manufacturing procurement through Thai cooperative direct contracts. Carbon credit stacking in agroforestry systems offsets input costs for certified sustainable operations.
Margin leader: Online Retail. Volume scale: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Chanthaburi and Chiang Rai provinces anchor the global butterfly pea flower tea supply chain, with smallholder cooperatives supplying over 70% of international raw material demand. Regulatory divergence across import markets is fragmenting procurement patterns and concentrating certification advantages among pre-approved exporters.
Thailand
Domestic consumption and export processing dominate the commercial landscape. The Thai Food and Drug Administration governs export certification under GMP-equivalent standards for Clitoria ternatea raw material. Bangkok-based processors in the Lat Krabang industrial zone now operate modular supercritical CO2 extraction units for pharmaceutical-grade extract production.
United States
Premium cocktail bars in New York, Portland, and Los Angeles drive bulk extract procurement for pH-reactive beverage presentations. The FDA color additive petition backlog restricts food and beverage applications to dietary supplement categories, compressing addressable market width. Direct-to-consumer subscription brands headquartered in Austin and Brooklyn bypass traditional import brokerage relationships.
Germany
Specialty tea houses in Berlin and Hamburg anchor European demand for single-origin loose leaf formats. EFSA Novel Food guidance updates clarified safety data requirements for Clitoria ternatea preparations, accelerating formulation trials among compliant applicants. Munich-based natural cosmetics manufacturers command 4-7x pricing multiples for anthocyanin-rich extracts versus beverage applications.
Japan
Functional food and cosmeceutical sectors absorb high-purity extract volumes for antioxidant skincare formulations. The Ministry of Health, Labour and Welfare (MHLW) and PMDA govern import specifications for botanical ingredients used in quasi-drug applications. Osaka and Tokyo beauty manufacturers integrate butterfly pea extract into premium topical products targeting domestic and Southeast Asian export markets.
South Korea
K-beauty manufacturers represent the fastest-expanding demand segment for standardized anthocyanin concentrates. The Ministry of Food and Drug Safety (MFDS) regulates cosmetic ingredient safety assessments for Clitoria ternatea-derived actives. Seoul-based R&D labs and Incheon-area production facilities are displacing traditional wholesale distributors as primary volume aggregators for Thai exporters.
Butterfly Pea Flower Tea Market Competitive Environment
Regulatory pre-certification dominates the current landscape, with procurement power concentrating among Thai exporters holding validated EFSA Novel Food dossiers and FDA-acknowledged GRAS submissions. The vendor base fragments across three operational tiers: integrated biotech extractors with pharmaceutical-grade capabilities, single-origin specialty brands leveraging cooperative sourcing narratives, and direct-to-consumer wellness platforms optimizing subscription economics. Strategic archetypes include certification-first exporters, agroforestry-integrated cooperatives, and cosmeceutical ingredient specialists. Competitive moves center on backward integration into Thai cultivation networks and technology licensing for modular extraction systems.
Within the biotech extraction tier, EverforEver Biotech represents pharmaceutical-grade supply contract capabilities. Among single-origin specialists, Tea Trunk exemplifies cooperative-sourced brand positioning. At the direct-to-consumer end, Blue Tea anchors wellness-subscription channel economics. These three entities collectively illustrate how regulatory compliance, sourcing narrative, and channel control determine margin capture in a market where raw material geographic lock-in creates structural supply advantages.
| Leading Market Players |
|---|
| EverforEver Biotech |
| Tea Trunk |
| Blue Tea |
| Wild Hibiscus Flower Co. |
| Specialty Natural Products Public Company Limited |
| Revival Tea Company |
| Paraman Food Works |
| Woodland Foods |
| Bigelow Tea |
| Others |
Value Chain & Pricing Dynamics
Thai cooperative farming clusters in Chanthaburi and Chiang Rai provinces anchor labor-cost differentials that widen pricing-tier spreads between pharmaceutical-grade extracts and economy-tier powders. Input-cost pass-through from anthocyanin standardization assays and cold-chain logistics feeds directly into premium-mid-economy pricing differentiation across export markets.
Pricing Analysis
Input-cost pass-through dominates pricing dynamics, with supercritical CO2 extraction equipment and refrigerated logistics feeding into three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—EFSA Novel Food dossiers versus FDA-acknowledged GRAS submissions—and volume scale for bulk foodservice procurement. Cost compression in economy-tier segments is intensifying because synthetic FD&C Blue No. 1 maintains substantially lower unit economics. Mass-market food manufacturers exhibit highest price sensitivity, while Korean and Japanese cosmeceutical buyers accept 4-7x multiples for standardized anthocyanin concentrates.
Supply Chain Analysis
Single-source vulnerability sits with Thailand's concentration of Clitoria ternatea cultivation, where smallholder cooperatives supply over 70% of international raw material demand. The supply chain draws from Thai raw material, German and Italian extraction equipment, and Korean-Japanese beauty manufacturing demand. Regulatory restriction risk concentrates in FDA color additive petition backlogs and EFSA Novel Food approval timelines. Distribution runs through Bangkok-based processors with direct account teams for Melbourne, Portland, and Copenhagen hospitality clusters, bypassing traditional import brokerage relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Butterfly pea flower tea functions as a stable compounder, with regulatory approval cascades across major import jurisdictions creating durable barriers that protect certified incumbents and sustain pricing power.
For Market Incumbents: Cement backward integration into Thai cooperative farming networks to secure captive supply of GMP-certified raw material. Lock in long-term offtake agreements with EFSA-pre-approved extract processors before European formulation trials accelerate. Priority lever: carbon credit stacking in agroforestry systems to offset input costs and defend margin position against emerging biotech extractors.
For New Entrants and Emerging Players: The gap between premium cosmeceutical pricing and economy-tier foodservice rates creates white-space opportunity for mid-tier standardization. Target US direct-to-consumer subscription channels where FDA petition backlog restricts incumbent food-and-beverage positioning. Go-to-market angle: single-origin cooperative sourcing narratives paired with wellness-box curation for North American urban consumers.
For Investors and Strategic Acquirers: Korean and Japanese beauty manufacturers represent the most active acquirer in this space, driven by anthocyanin antioxidant demand for topical skincare formulations. Five-to-ten-year viability hinges on EFSA Novel Food pathway maturation expanding addressable market width. Signal to watch: positive opinions on Clitoria ternatea extract safety dossiers triggering European food manufacturer stockpiling behavior.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thai Cultivation | Captive supply of GMP-certified raw material secures EFSA and FDA regulatory pre-approval advantages. |
| Modular Supercritical CO2 Extraction Deployment | German and Italian equipment manufacturers reduce capital barriers for pharmaceutical-grade extract production. |
| Direct-to-Consumer Subscription Launch | Specialty brands bypass 15-25% wholesale margin compression through curated wellness box economics. |
| Cosmeceutical Ingredient Pivot | Korean and Japanese beauty manufacturers command 4-7x pricing multiples versus beverage applications. |
| Carbon Credit Stacking in Agroforestry | Thai cooperative operations offset input costs through voluntary carbon market certification eligibility. |
Study Parameters
Direct dialogue with Bangkok-based export processors, EFSA regulatory consultants, specialty tea house procurement managers in Melbourne and Portland, and Korean beauty manufacturer R&D directors grounded qualitative findings. Secondary validation drew from Thai FDA export certification records, EFSA Novel Food guidance updates, FDA color additive petition dockets, and customs trade data for Clitoria ternatea raw material. Bottom-up volume estimates from cooperative farming surveys triangulated against top-down addressable market sizing by application segment.
Bottom-up modeling of loose leaf, extract, tea bag, and powder volumes across beverage, cosmetic, culinary, and nutraceutical applications anchored the analytical lens. Top-down constraints from regulatory approval timelines and import certification capacity shaped the projection horizon. CAGRs derived from segment-level demand elasticity and supply-side capacity buildout assumptions. Forecast inputs included EFSA Novel Food opinion trajectories, supercritical CO2 extraction equipment deployment rates, and mixology sector expansion in North American urban centers.
The model assumes a particular technology adoption path; alternative pathways for anthocyanin stabilization and cold-chain logistics would alter the outlook. Forecasts reflect assumptions around EFSA approval cascades, Thai cooperative farming output stability, and synthetic dye substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Tea Packaging Market
Tea
Asia-Pacific Tea Market
Tea
Global Fruit Tea Market
Tea
Bottled Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
Pu-Erh Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Global Tea Extract Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Light-Fermented Tea Market
Tea
Green Tea Leaves Market
Tea
Tea Pitchers Market
Tea
Floral Tea Market
Tea
APAC RTD Tea Market
Tea
Instant Tea Premix Consumption Market