
 Green Tea Extract Market | 2026-2036
Green Tea Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Extract Market Outlook
Modular dosage formats are restructuring buyer choice across the green tea extract landscape, as single-serve sachets and stackable capsule systems displace bulk powder purchasing among wellness-focused consumers. Taiyo International leverages its Japanese extraction heritage to dominate high-EGCG specification supply. Synthite Industries Ltd. anchors South Asian raw material sourcing through backward integration into Kerala tea estates. Finlays competes on flavor-standardized liquid extracts for beverage formulation.
Green tea extract comprises concentrated bioactive polyphenols—principally epigallocatechin gallate (EGCG) at 40-98% standardization—derived from Camellia sinensis leaves via solvent or supercritical CO2 extraction, serving antioxidant, metabolic, and preservative functions across nutrition and cosmetic industries. Powder formulations lead volume due to blending flexibility in functional foods, while liquid extracts capture premium positioning in ready-to-drink applications where solubility and taste masking command higher margins. The dietary supplements channel sustains the fastest expansion as clinical validation of catechin benefits deepens practitioner recommendations.
EFSA novel food regulations and FDA GRAS notification requirements shape product standards for catechin concentration and contaminant thresholds, directly determining market access for new extraction entrants. China's NMPA and SAMR enforce dual carbon goals that are tightening energy-intensive extraction facility permits, redirecting capacity toward cleaner supercritical technologies. Stakeholders must monitor evolving pharmacovigilance signals on hepatotoxicity risk at high EGCG doses, as regulatory repositioning on safety limits would reshape formulation ceilings and label claims across all major supply corridors.
Market Dynamics
Supercritical CO2 extraction technology is displacing solvent-based methods as China's SAMR tightens energy permits under dual carbon goals, forcing capacity retooling and reshaping supplier cost structures across the green tea extract value chain.
Growth Catalysts
- EFSA novel food pathways:The European Union's tightening purity benchmarks for catechin content are accelerating quality differentiation among extraction specialists seeking premium positioning.
- Dietary supplements channel:Preventive health regimens are pulling EGCG-standardized powders into practitioner-recommended protocols, deepening clinical validation loops.
- Supercritical CO2 adoption:Cleaner extraction technologies are unlocking carbon-compliant capacity expansion in jurisdictions with strict MEE oversight.
Market Restraints
- Raw material concentration:Kerala and Fujian tea estates control premium leaf supply, creating geographic chokepoints for quality-tier inputs.
- Hepatotoxicity signal monitoring:Pharmacovigilance reviews of high-dose EGCG safety profiles are compressing formulation ceilings and label claim flexibility.
- Energy cost volatility:Carbon-intensive solvent extraction faces margin pressure as China's dual carbon goals redirect permit approvals toward cleaner technologies.
Strategic Opportunities
- Modular dosage formats:Single-serve sachets and stackable capsule systems are capturing wellness-focused consumers migrating from bulk powder purchasing.
- Cosmetic applications:Antioxidant positioning in topical formulations represents underpenetrated white space beyond nutrition channels.
- PLI scheme alignment:India's production-linked incentives for botanical extraction are attracting backward-integrated investment into domestic tea processing.
Industry Challenges
- GRAS notification timelines:FDA review cycles for new catechin specifications are extending market entry lead times for novel extraction entrants.
- Cross-border standard harmonization:Divergent EFSA, FDA, and NMPA purity thresholds are fragmenting batch certification requirements and complicating inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Extract Market |
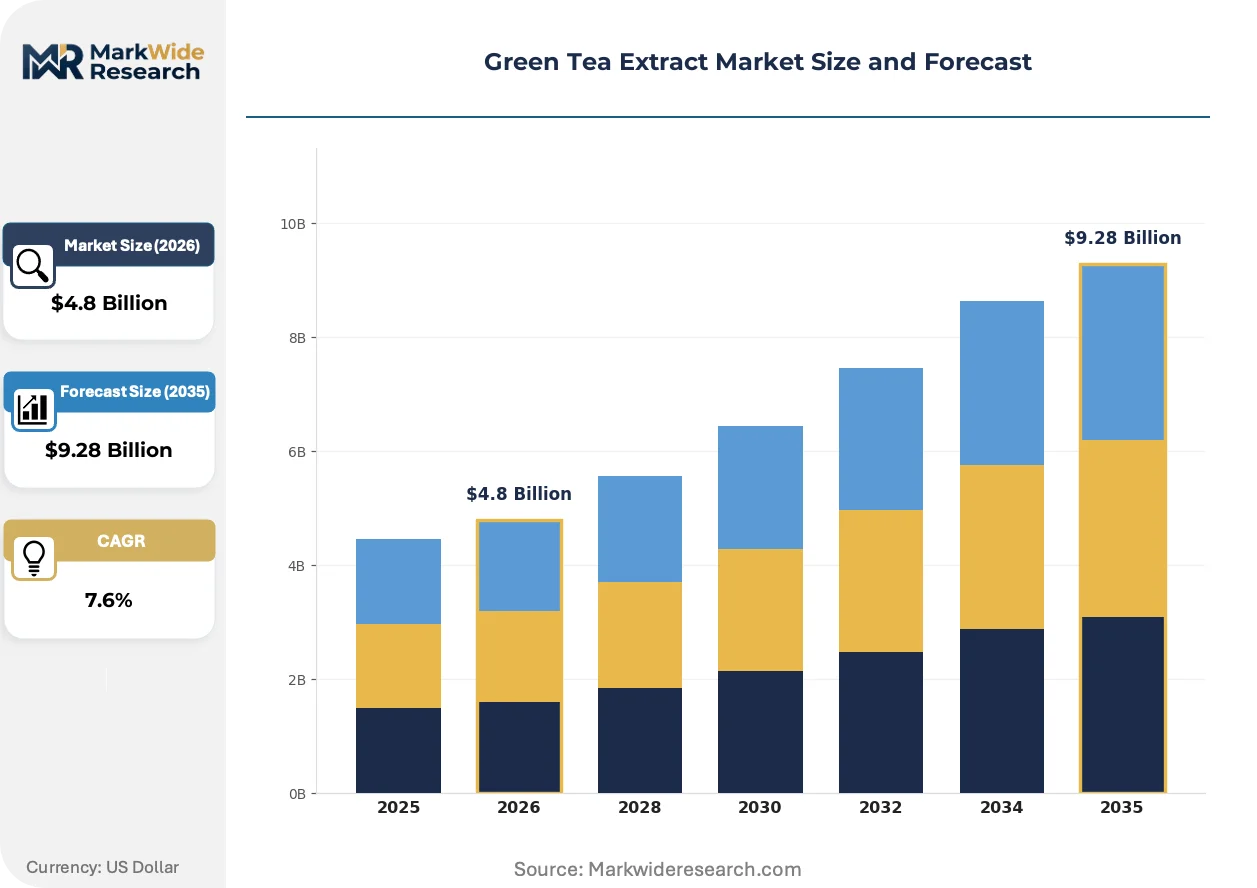
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tablet Application: Food & Beverage, Dietary Supplements, Personal Care, Pharmaceuticals End User: Retail, Hospitals, Wellness Centers, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Synthite Industries Ltd., Finlays, Archer Daniels Midland Company, Givaudan, Amax NutraSource, Kemin Industries, Taiyo International, International Flavors & Fragrances Inc., Martin Bauer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Extract Market Strategic Shifts
Extraction technology and dosage format innovation are compressing traditional supply hierarchies as regulatory carbon constraints and consumer convenience preferences simultaneously reshape production and purchasing patterns.
Supercritical CO2 extraction systems are modularizing production footprints, enabling smaller-scale facilities to achieve pharmaceutical-grade catechin purity previously requiring centralized solvent infrastructure. Mid-tier supplement manufacturers are adopting these systems to bypass raw material aggregation bottlenecks. This technology diffusion is modularizing regional supply structures and compressing economies-of-scale advantages historically held by large integrated extractors.
China's SAMR enforcement of dual carbon goals is redirecting energy-intensive extraction permits toward cleaner technology adopters, creating regulatory preference for supercritical CO2 operators. Facilities in Zhejiang and Anhui provinces are retooling to maintain operating licenses under tightening MEE oversight. This policy pivot is advantaging extraction specialists with capital reserves for technology transition over legacy solvent-dependent competitors.
Wellness consumers are migrating from bulk powder purchasing toward single-serve sachets and stackable capsule systems that enable precise dosing and portability. E-commerce direct-to-consumer channels are capturing this format preference shift, displacing traditional bulk ingredient distributors in the premium segment. This behavioral rotation is most visible in North American and European urban markets where subscription-based supplement purchasing has normalized.
Green Tea Extract Market Segmentation
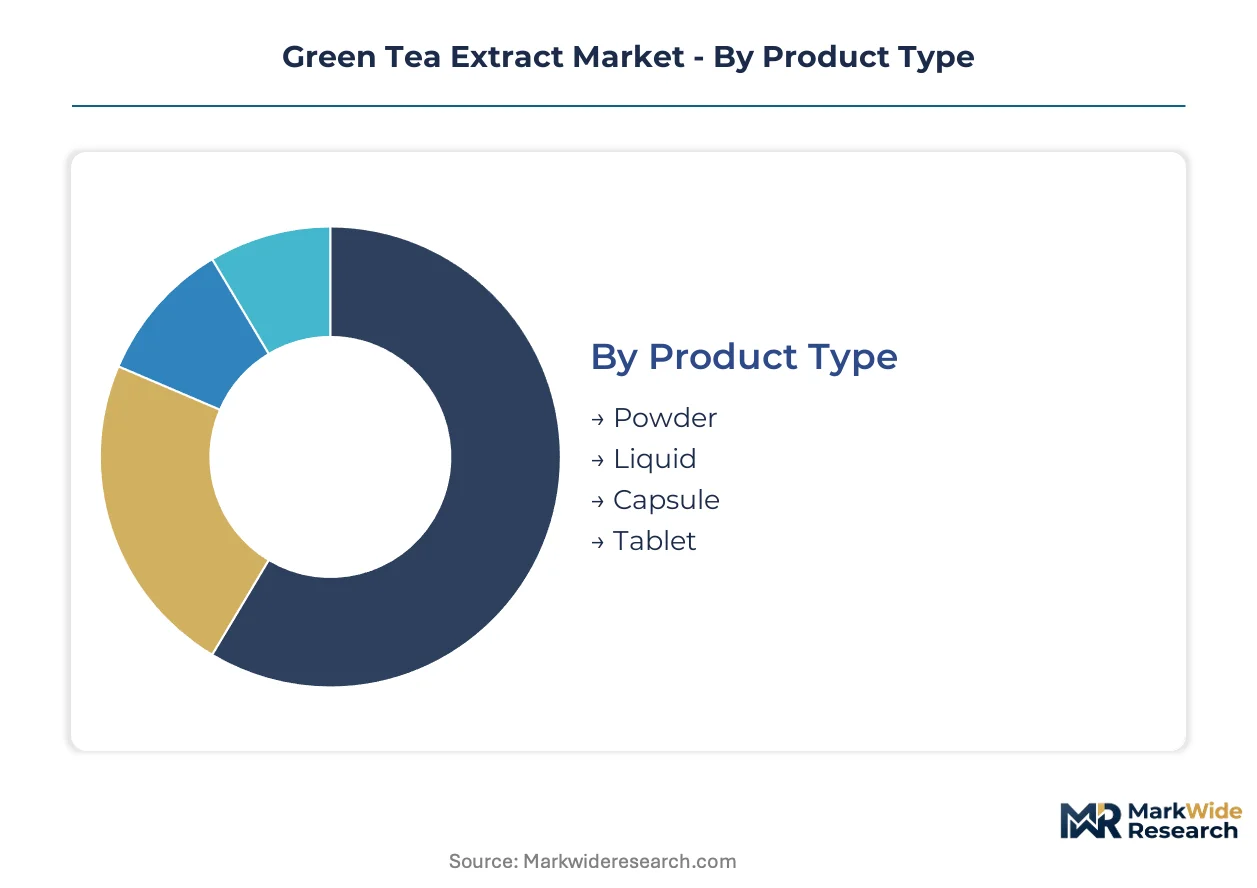
Green tea extract segmentation reveals how regulatory certification burdens, formulation complexity, and channel access requirements fragment commercial opportunities across distinct buyer ecosystems. Understanding these divides enables suppliers to align extraction capabilities with the specific purity benchmarks and documentation demands of each segment.
Product Type:
Powder formulations carry the heaviest EFSA novel food documentation loads for catechin standardization claims, while liquid extracts face FDA GRAS notification requirements for beverage incorporation. Capsule and tablet formats trigger varying pharmacovigilance thresholds across jurisdictions.
- Powder:Granular concentrates standardized to 40-98% EGCG content dominate blending flexibility for functional food manufacturers. Demand concentrates among North American contract manufacturers seeking bulk input for private-label supplement lines, constrained by EFSA tightening purity benchmarks for novel food approvals.
- Liquid:Solubility-optimized extracts with taste-masking profiles command premium positioning in ready-to-drink applications. Japanese beverage formulators drive specification innovation, requiring sub-ppm solvent residue documentation under PMDA import protocols.
- Capsule:Pre-metered gelatin and vegetable-shell formats reduce dosing variability for practitioner-recommended protocols. Hospital procurement in Germany favors these units for outpatient metabolic support programs.
- Tablet:Compressed formulations with excipient matrices suit mass-market retail channels with extended shelf-life requirements. Indian PLI scheme beneficiaries are scaling tablet production for domestic Ayurveda-integrated wellness chains.
Powder sits at the top of the volume ranking, with liquid climbing the fastest.
Application:
Application segments diverge sharply on margin structure, with pharmaceutical channels demanding batch-level CoA documentation that cosmetic and food applications rarely require.
- Food & Beverage:Natural preservative and antioxidant functions in packaged goods require flavor-standardized extracts with minimal astringency. European clean-label formulators in Switzerland and France specify low-caffeine variants for mainstream beverage launches.
- Dietary Supplements:EGCG-standardized powders for preventive health regimens carry the steepest expansion trajectory. US practitioner channels are deepening clinical validation loops through functional medicine protocols.
- Personal Care:Topical antioxidant positioning in serums and creams represents underpenetrated white space beyond nutrition channels. South Korean cosmetic manufacturers are pioneering liposomal delivery systems for enhanced dermal absorption.
- Pharmaceuticals:Investigational drug applications require GMP-certified extraction with full supply chain traceability. Clinical trial sponsors in Australia face TGA scrutiny on hepatotoxicity risk documentation at high-dose EGCG thresholds.
Dietary supplements command the highest value per kilogram, with personal care gaining share fastest.
End User:
End user categories separate on procurement sophistication, with institutional buyers enforcing supplier audit protocols that retail channels rarely replicate.
- Retail:Direct-to-consumer supplement brands and mass-market chains prioritize SKU breadth and packaging differentiation. Amazon marketplace sellers in the US are capturing modular dosage format preferences through subscription models.
- Hospitals:Clinical nutrition departments require evidence-backed dosing protocols with pharmacovigilance monitoring systems. NHS trust procurement in England is standardizing on specific EGCG milligram strengths for metabolic syndrome protocols.
- Wellness Centers:Integrated medicine clinics and spa facilities source practitioner-exclusive lines with higher catechin concentrations. Dubai wellness tourism operators are importing Japanese extraction heritage brands for premium positioning.
- Food Manufacturers:Industrial buyers negotiate long-term supply agreements with backward-integrated Kerala and Fujian estate operators. Carbon-compliant supercritical CO2 extraction is becoming a mandatory supplier qualification under Nestlé and Unilever sustainability scorecards.
Food manufacturers anchor procurement volume, with wellness centers expanding most quickly.
Distribution Channel:
Channel selection determines margin capture and customer data access, with direct and digital routes offering formulation feedback loops that traditional retail obscures.
- Online Retail:E-commerce direct-to-consumer platforms enable precise demographic targeting for stackable capsule systems. German subscription services are displacing traditional bulk distributors in the premium segment.
- Supermarkets:Mass-market shelf placement requires trade marketing investment and standardized unit pricing. Carrefour and Tesco private-label programs in France and England are consolidating supplier bases to reduce audit complexity.
- Specialty Stores:Health food retailers and pharmacy chains offer educated staff recommendations that drive premium conversion. Holland & Barrett's UK footprint provides dedicated shelf space for high-EGCG specification lines.
- Direct Sales:Network marketing and practitioner-only channels maintain price integrity through exclusive distribution rights. Amway's Nutrilite division leverages this structure for metabolic health positioning in China.
Supermarkets dominate unit volume throughput, with online retail capturing margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Green tea extract production traces its industrial roots to Japanese and Chinese tea cultivation traditions, with commercial extraction scaling first in East Asia before diffusing to South Asian and European processing hubs.
China
Domestic consumption of catechin-standardized extracts drives volume, with Zhejiang and Anhui provinces hosting retooling facilities under SAMR dual carbon enforcement. NMPA and SAMR permits now favor supercritical CO2 operators over solvent-dependent plants. Hangzhou extraction clusters are consolidating capacity as MEE oversight tightens energy compliance thresholds.
Japan
PMDA import protocols for sub-ppm solvent residue documentation shape specification requirements for beverage formulators in Tokyo and Osaka. METI standards on extraction purity anchor premium positioning for heritage brands. Kansai industrial corridors concentrate pharmaceutical-grade catechin facilities serving domestic and export markets.
India
Kerala tea estates provide backward-integrated raw material supply for extraction specialists serving domestic Ayurveda-integrated wellness chains. FSSAI standards on botanical purity intersect with PLI scheme incentives for extraction capacity investment. Kochi processing hubs are scaling tablet and capsule production for hospital procurement networks.
United States
Practitioner-recommended EGCG protocols drive dietary supplement channel expansion, with FDA GRAS notification requirements extending market entry timelines for novel extraction entrants. Functional medicine networks in California and New York deepen clinical validation loops. Amazon marketplace sellers capture modular dosage format preferences through subscription models.
Germany
Hospital procurement standardization on specific EGCG milligram strengths for metabolic syndrome protocols anchors institutional demand. EFSA novel food pathways tighten purity benchmarks for catechin content claims. Hamburg and Frankfurt extraction facilities serve as distribution nodes for EU-wide supplement and cosmetic formulation supply.
Green Tea Extract Market Competitive Environment
Premium-margin players sit above commodity-margin players across standardization tiers, with EGCG concentration levels and certification documentation separating pricing bands. The vendor base clusters around three strategic archetypes: heritage Japanese extraction specialists, South Asian estate-integrated processors, and European flavor-standardized liquid extract formulators. Capacity expansion and backward integration into tea estate control represent the dominant competitive moves reshaping supply structures.
Within the heritage specialist tier, Taiyo International occupies a position exemplifying Japanese extraction lineage, while Synthite Industries Ltd. anchors South Asian estate-integrated supply. Finlays sits within the European liquid extract segment serving beverage formulation channels. These three represent distinct archetype positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Synthite Industries Ltd. |
| Finlays |
| Archer Daniels Midland Company |
| Givaudan |
| Amax NutraSource |
| Kemin Industries |
| Taiyo International |
| International Flavors & Fragrances Inc. |
| Martin Bauer Group |
| Others |
Value Chain & Pricing Dynamics
Energy costs at Chinese extraction facilities cascade through three distinct pricing tiers as SAMR dual carbon enforcement redirects permit approvals toward supercritical CO2 operators, compressing margins for solvent-dependent competitors while premiumizing carbon-compliant supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade EGCG specifications from beverage-grade and bulk commodity tiers, with EFSA novel food certification and PMDA sub-ppm residue documentation commanding substantial premiums. Price differentiation hinges on catechin standardization precision and carbon compliance credentials. Pricing pressure stems from raw material concentration in Kerala and Fujian estates, where estate-integrated processors capture upstream margin. Food manufacturers exhibit highest price sensitivity, while pharmaceutical sponsors tolerate premium positioning for GMP-certified traceability.
Supply Chain Analysis
Workforce availability in Zhejiang and Anhui provinces constrains capacity expansion as MEE oversight tightens energy compliance thresholds, forcing retooling investments that advantage capital-reserved operators. Geographic supply concentrates in China, India, and Japan, with Kerala tea estates and Fujian leaf markets anchoring raw material flows. The chain draws from Camellia sinensis cultivation, solvent and supercritical CO2 extraction infrastructure, and pharmaceutical-grade certification capacity. Single-source vulnerability runs through premium leaf supply controlled by backward-integrated estate operators. Distribution runs through direct-to-consumer e-commerce platforms and hospital procurement networks for practitioner-recommended protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green tea extract market functions as a stable compounder, with preventive health regimen adoption providing durable demand visibility across economic cycles.
For Market Incumbents: Deploy supercritical CO2 capacity expansion in carbon-compliant jurisdictions to capture SAMR permit preferences and outcompete solvent-dependent rivals. Deepen backward integration into Kerala and Fujian estate control to secure quality-tier raw material chokepoints. Fortify EFSA and FDA certification documentation to extend formulation ceilings before hepatotoxicity signals trigger regulatory repositioning. For New Entrants and Emerging Players: Enter via cosmetic applications and South Korean liposomal delivery partnerships, where topical antioxidant positioning remains underpenetrated relative to saturated nutrition channels. Target India's PLI scheme beneficiaries for Ayurveda-integrated wellness chain supply, leveraging FSSAI botanical purity alignment. Pursue modular dosage format innovation through German subscription service partnerships to bypass entrenched bulk distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where carbon compliance capital requirements exceed legacy operator balance sheet capacity, creating acquisition opportunities for technology-transitioned assets. Long-term viability favors extraction specialists with estate-integrated supply and multi-jurisdiction certification portfolios. Monitor EFSA pharmacovigilance reviews on high-dose EGCG hepatotoxicity as the critical inflection signal for formulation ceiling compression and label claim restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | SAMR dual carbon enforcement advantages carbon-compliant operators with preferential permit access in Zhejiang and Anhui. |
| Backward Integration into Estate Control | Kerala and Fujian tea estate ownership secures premium leaf supply chokepoints against raw material concentration risk. |
| EFSA Novel Food Certification Investment | Tightening catechin purity benchmarks differentiate premium positioning for EU market access and practitioner channel credibility. |
| Modular Dosage Format Development | Single-serve sachets and stackable capsules capture wellness consumer migration from bulk powder purchasing in North American and European urban markets. |
| Cosmetic Application Partnership | South Korean liposomal delivery systems unlock topical antioxidant white space beyond saturated nutrition channels. |
Study Parameters
Multiple input streams — extraction facility operators, dietary supplement brand managers, cosmetic formulators, and hospital procurement officers — were reconciled against customs records, FSSAI botanical purity filings, and EFSA novel food submission databases. Primary interviews with Kerala estate agronomists, Zhejiang plant engineers, and German hospital nutrition directors supplied operational validation. Secondary sources encompassed SAMR dual carbon policy documents, PMDA import protocol specifications, and PLI scheme beneficiary disclosures. Bottom-up capacity modeling and top-down demand estimation were triangulated to constrain variance bands.
Data-stream reconciliation across product type, application, and end-user segmentation dimensions anchored volume and value projections over the analysis window. CAGRs were derived from trend extrapolation of catechin standardization adoption curves and regulatory pathway completion timelines. Modeled inputs included supercritical CO2 technology diffusion rates, EFSA hepatotoxicity review trajectories, and modular dosage format penetration in e-commerce channels.
Inputs from SAMR enforcement bulletins and PMDA import inspection records were available through the study window; gaps in real-time estate-level leaf pricing introduce uncertainty bands around raw material cost assumptions. Forecasts reflect documented assumptions on carbon compliance permit allocation and practitioner protocol adoption velocity. Material deviation in EFSA safety limit repositioning or SAMR enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Infuser Market
Tea
Out of Home Tea Market
Tea
Green Tea Leaves Market
Tea
Global Tea Market
Tea
Tea Concentrate Market
Tea
APAC RTD Tea Market
Tea
Detox Tea Market
Tea
Organic Tea Market
Tea
Africa Tea Market
Tea
RTD Tea Market
Tea
Oolong Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
Tea Pitchers Market
Tea
Pu-Erh Tea Market
Tea
Green Tea Bag Market
Tea
South America Tea Market