
 Bottled Milk Tea Market | 2026-2036
Bottled Milk Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Milk Tea Market Insights
Aseptic cold-fill processing is reshaping how bottled milk tea achieves extended shelf life without preservatives. Uni-President Enterprises Corporation leverages its integrated beverage manufacturing base across Taiwan and mainland China to control production costs. Nestlé S.A. competes through specialized dairy sourcing networks that anchor its supply of authentic milk-based formulations. Suntory Holdings Limited differentiates via precision blending technology that sustains consistent flavor profiles across large production runs.
Bottled milk tea consists of brewed tea extract combined with dairy or non-dairy creamers, sweeteners, and stabilizers, then pasteurized and packaged in shelf-stable formats for ambient distribution. The product type segment shows green tea variants leading volume while oolong commands premium positioning in East Asian markets. Packaging type insights reveal plastic bottles dominating mass-market distribution, though tetra pak formats are gaining traction in convenience channels where portability drives purchase decisions. Distribution channel dynamics center on supermarket and convenience store networks, with online retail emerging as a high-growth vector for subscription-based replenishment models.
FDA oversight of dairy ingredient labeling and China's SAMR enforcement of GB standards for pre-packaged beverages both shape product formulation requirements and market access conditions. Japan's METI energy-drink classification rules and Taiwan's food additive regulations further constrain cross-border formulation flexibility. Stakeholders must monitor evolving sugar-tax proposals across multiple Asian jurisdictions and assess whether reformulation investments or regional SKU customization delivers superior returns.
Market Dynamics
Aseptic cold-fill processing is compressing production timelines while China's SAMR labeling mandates are forcing simultaneous packaging redesigns across East Asian supply chains. These dual pressures are restructuring competitive advantage around technical compliance rather than brand equity alone.
Growth Catalysts
- Urban Convenience Infrastructure:Convenience store networks in Shanghai, Tokyo, and Taipei are dedicating expanded cooler space to grab-and-go beverage formats. This channel prioritizes products with 9-12 month ambient shelf stability.
- GB Standards Harmonization:China's SAMR enforcement of unified pre-packaged beverage labeling is reducing regional SKU fragmentation. Manufacturers can now deploy single packaging designs across multiple provincial markets.
- Millennial Consumption Patterns:Working-age consumers in dense Chinese and Japanese metropolitan areas are substituting home-brewed tea with ready-to-drink alternatives during commute windows. This behavioral shift anchors volume concentration in urban corridors.
Market Restraints
- Dairy Input Volatility:Global milk powder and non-dairy creamer supply chains face price instability linked to feed grain markets. Formulators absorb margin pressure or risk losing shelf positioning.
- Regulatory Friction:Japan's METI energy-drink classification rules create formulation barriers for caffeinated milk tea variants. Cross-border product standardization remains technically constrained.
- Sugar Tax Exposure:Proposed excise frameworks across Thailand, Malaysia, and Singapore threaten profit pools in sweetened beverage categories. Reformulation investments compete for capital against capacity expansion.
Strategic Opportunities
- Tetra Pak Channel Penetration:Convenience operators in South Korea and Vietnam are testing ambient carton formats for transit-friendly consumption. This packaging shift opens distribution beyond traditional cold-chain limits.
- Subscription Replenishment Models:Direct-to-consumer platforms in urban China are capturing recurring purchase patterns for pantry-stocking households. Digital-native brands bypass conventional retail slotting fees.
- Oolong Premium Positioning:High-elevation Taiwanese oolong variants command price multiples over mass-market green tea formulations. Terroir-linked sourcing narratives support margin expansion in gift and premium channels.
Industry Challenges
- Aseptic Technician Scarcity:Cold-fill line operation and maintenance require specialized training unavailable in many secondary Chinese manufacturing hubs. Talent gaps constrain geographic diversification of production assets.
- Dual Certification Timelines:Simultaneous FDA dairy facility registration and SAMR GB compliance for export-oriented Chinese plants extend product launch windows. Parallel regulatory tracks consume management bandwidth.
- Flavor Stability Validation:Extended shelf-life claims require accelerated aging studies that add 4-6 months to new product development cycles. R&D pipelines face compression against seasonal launch windows.
Report Scope
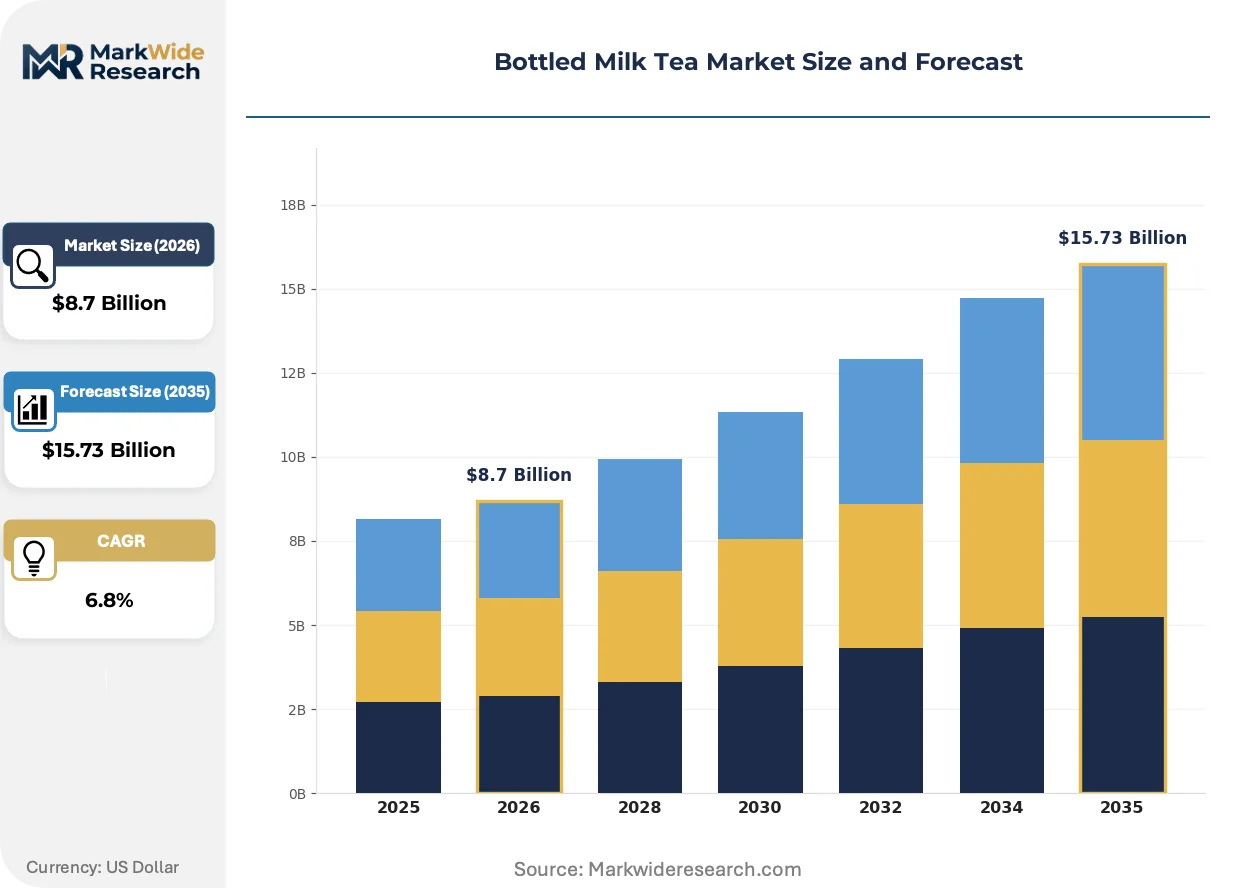
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Milk Tea Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chai, Green Tea, Oolong, Fruit Infusion Packaging Type: Plastic Bottle, Glass Bottle, Tetra Pak, Carton Distribution Channel: Supermarket, Online Retail, Convenience Store, Direct Sales Flavor Profile: Original, Vanilla, Chocolate, Honey |
| Companies Covered | Uni-President Enterprises Corporation, Nestlé S.A., The Coca-Cola Company, Suntory Holdings Limited, Ito En, Ltd., Kirin Holdings Company, Limited, Asahi Group Holdings, Ltd., Nongfu Spring, Otsuka Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Milk Tea Market Trends and Innovations
Digital traceability systems and precision blending hardware are converging to reshape how bottled milk tea manufacturers demonstrate quality consistency and origin authenticity to increasingly skeptical urban consumers.
Blockchain-enabled ingredient provenance tracking is virtualizing supply chain transparency for premium-tier products. Japanese and Taiwanese exporters deploy distributed ledger verification to satisfy mainland Chinese buyer scrutiny regarding Taiwanese oolong sourcing claims. This technology is virtualizing the traditional audit-based trust model, compressing third-party certification timelines while raising barriers for uncredentialed competitors.
China's SAMR has tightened enforcement of GB 7718 pre-packaged food labeling standards with specific carbohydrate disclosure requirements for sugar-sweetened beverages. Industrial consequence includes mandatory front-of-pack sugar content indicators that reshape formulation decisions. Premium-positioned brands are responding with stevia and monk fruit reformulations to maintain shelf appeal under heightened nutritional scrutiny.
Urban Chinese millennials are consolidating beverage purchases around digital pantry-management apps that automate replenishment based on consumption velocity. Traditional supermarket and convenience store channels face disintermediation pressure from platform-integrated subscription services. This behavioral pivot is most visible in Shanghai and Shenzhen, where same-day delivery infrastructure supports just-in-time household inventory models.
Bottled Milk Tea Market Segmentation
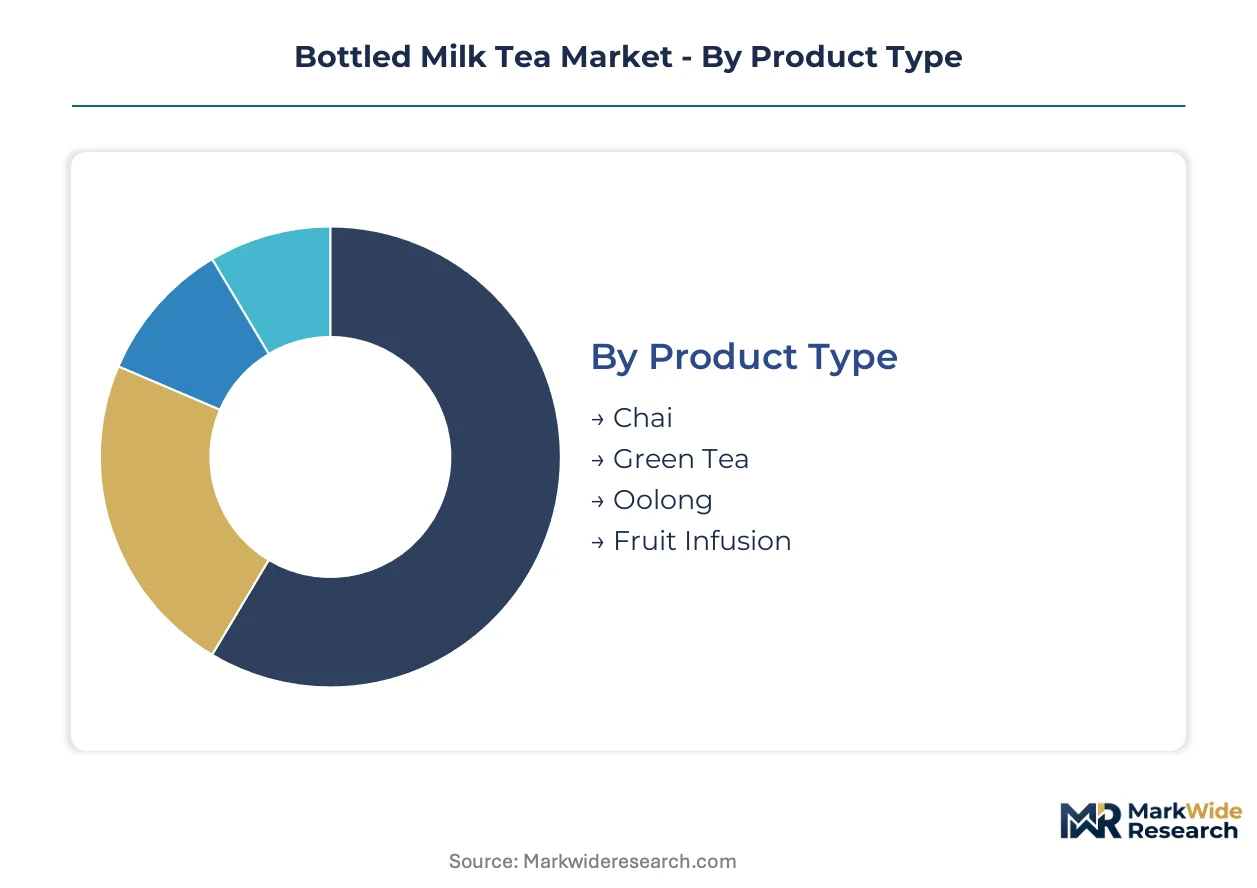
Segmentation in bottled milk tea reveals how formulation, packaging, and channel choices map to distinct consumption occasions and margin profiles. Understanding these splits helps manufacturers allocate R&D and slotting investments where velocity and profitability align.
Product Type:
Green tea variants turn inventory fastest in convenience channels, while oolong sits longer in premium gift sets. Chai and fruit infusion occupy middle velocity tiers with seasonal spikes.
- Green Tea:Brewed from Camellia sinensis leaves with lower oxidation, delivering grassy, astringent profiles that pair with non-dairy creamers. Demand concentrates in Shanghai and Tokyo convenience stores where commuters prioritize refreshment over satiety during morning transit windows. China's SAMR labeling mandates on sugar disclosure are accelerating reformulation toward reduced-sugar variants in this high-volume segment.
- Oolong:Semi-oxidized leaves from high-elevation Taiwanese gardens yield complex floral notes that justify price premiums. Taipei and Shenzhen gift channels drive demand, with terroir narratives supporting margin expansion. Dual certification timelines for FDA dairy facility registration and SAMR GB compliance constrain new entrant supply.
- Chai:Black tea base with cinnamon, cardamom, and clove spice blends. South Asian diaspora communities in urban Malaysia and Singapore sustain niche volume.
- Fruit Infusion:Tea extract combined with mango, peach, or lychee purees. Summer seasonal demand peaks in Vietnam and Thailand convenience networks.
Green tea dominates installed base. Oolong is where expansion concentrates.
Packaging Type:
Cost tiers separate mass-market plastic from premium glass and emerging carton formats, with cold-chain requirements varying sharply across materials.
- Plastic Bottle:PET and HDPE formats with barrier layers achieve 9-12 month ambient stability through aseptic cold-fill processing. Mass-market distribution across East Asian supermarkets and convenience stores depends on this lowest-unit-cost format, though China's evolving extended producer responsibility schemes threaten margin structures.
- Tetra Pak:Aseptic carton technology enables ambient distribution without refrigeration, opening transit-friendly channels in South Korea and Vietnam where portability drives purchase decisions. Convenience operators are testing these formats for commuter consumption beyond traditional cold-chain limits.
- Glass Bottle:Premium positioning in Japanese and Taiwanese gift channels. Higher unit costs limit volume but sustain margin pools.
- Carton:Gable-top formats for shorter-shelf-life fresh products. Direct-to-consumer subscription models in urban China favor this format for perceived sustainability.
Plastic bottle commands volume leadership. Tetra Pak is climbing the fastest as channel diversification accelerates.
Distribution Channel:
Customer type separates impulse convenience purchasers from planned pantry stockers, with online platforms capturing recurring household replenishment.
- Convenience Store:Grab-and-go purchase occasions dominate in dense East Asian urban corridors. Shanghai, Tokyo, and Taipei networks dedicate expanded cooler space to ready-to-drink formats with high turnover velocity. Shelf positioning depends on 9-12 month ambient shelf stability credentials.
- Online Retail:Platform-integrated subscription services capture recurring purchase patterns in Shanghai and Shenzhen, where same-day delivery infrastructure supports just-in-time household inventory models. Digital-native brands bypass conventional retail slotting fees through direct consumer relationships.
- Supermarket:Planned purchase occasions with broader SKU visibility. GB standards harmonization enables single packaging designs across multiple provincial markets.
- Direct Sales:Corporate gifting and institutional channels. Taiwanese oolong variants command price multiples in this premium pathway.
Supermarket channels hold installed base dominance. Online retail is where expansion concentrates.
Flavor Profile:
Maturity curves separate established original formulations from emerging premium variants, with vanilla and chocolate occupying transitional positions.
- Original:Unflavored tea-forward profiles with minimal sweetness modulation. Core volume driver across all East Asian markets with established consumer acceptance.
- Vanilla:Natural and synthetic vanillin additions smooth astringency. Transitional appeal for green tea converts in urban Chinese millennial segments.
- Chocolate:Cocoa powder integration creating dessert-beverage hybrids. Seasonal demand concentration in Japanese winter months.
- Honey:Natural sweetener positioning for reduced-sugar claims. SAMR carbohydrate disclosure requirements are accelerating stevia and monk fruit competition in this positioning space.
Original flavor dominates installed base. Honey-flavored variants are gaining share fastest as sugar-tax exposure reshapes formulation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese oolong exports flow primarily to mainland China and Japan, anchoring premium-tier trade corridors that shape East Asian supply chain configurations. Convenience store penetration rates and regulatory enforcement intensity vary sharply across national boundaries.
China
Urban millennials in Shanghai and Shenzhen drive demand concentration for grab-and-go formats during commute windows. SAMR enforcement of GB 7718 labeling standards mandates front-of-pack sugar disclosure, accelerating reformulation toward stevia and monk fruit alternatives. Yangtze River Delta manufacturing clusters host aseptic cold-fill lines serving both domestic distribution and export markets.
Japan
Working-age consumers in Tokyo and Osaka metropolitan corridors sustain volume for ambient-stable formats in convenience networks. METI energy-drink classification rules create formulation barriers for caffeinated milk tea variants crossing from adjacent categories. Kanto region production facilities specialize in precision blending technology for flavor consistency across large runs.
Taiwan
Gift-channel demand for high-elevation oolong variants supports premium price multiples in Taipei and cross-border shipments to mainland buyers. Taiwan's food additive regulations constrain formulation flexibility relative to export destination requirements. Central Mountain Range sourcing regions provide terroir-linked provenance narratives for blockchain-enabled traceability systems.
South Korea
Convenience operators in Seoul are testing ambient tetra pak formats for transit-friendly commuter consumption beyond traditional cold-chain limits. The country's national food safety regulator enforces strict dairy ingredient sourcing documentation for imported formulations. Busan-Ulsan corridor distribution hubs channel products into both domestic retail and re-export pathways.
Vietnam
Rising urban disposable incomes in Ho Chi Minh City and Hanoi are expanding addressable demand for ready-to-drink tea categories. The country's pre-packaged beverage standards authority is harmonizing labeling requirements with ASEAN regional frameworks. Mekong Delta fruit suppliers provide mango and lychee puree inputs for seasonal infusion variants.
Bottled Milk Tea Market Competitive Landscape
Channel-controlling players compete with product-specialist players across shelf-stable and fresh-format segments. The market structure shows moderate consolidation around beverage conglomerates with dairy sourcing networks and integrated manufacturing bases. Three archetypes dominate: diversified food-and-beverage conglomerates with cross-category scale, dedicated tea specialists with terroir-linked sourcing advantages, and dairy-forward players leveraging authentic milk formulations. Competitive moves center on aseptic processing capacity expansion and packaging format diversification toward ambient-stable cartons.
Among East Asian beverage conglomerates, Uni-President Enterprises Corporation and Suntory Holdings Limited exemplify the integrated manufacturing archetype with cross-border production footprints. Nestlé S.A. occupies a position representing the dairy-specialist vector, leveraging sourcing networks for authentic milk-based formulations. These three anchors illustrate how technical compliance capabilities and supply chain control separate sustained competitors from brand-dependent challengers.
| Leading Market Players |
|---|
| Uni-President Enterprises Corporation |
| Nestlé S.A. |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Ito En, Ltd. |
| Kirin Holdings Company, Limited |
| Asahi Group Holdings, Ltd. |
| Nongfu Spring |
| Otsuka Holdings Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta freight corridors linking Shanghai port facilities to inland manufacturing clusters impose differential logistics costs that stratify bottled milk tea pricing across domestic and export-bound product streams. This corridor's rate volatility compresses margin pools for aseptic cold-fill operators while amplifying price premiums for terroir-linked oolong variants that absorb transport costs through gift-channel positioning.
Pricing Analysis
Cost-plus contracts indexed to global milk powder futures dominate procurement agreements between dairy-integrated formulators and retail channel buyers. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified Taiwanese oolong gift sets from mass-market green tea convenience formats. Pricing pressure stems from China's extended producer responsibility schemes for PET packaging, which manufacturers pass through or absorb against shelf-positioning priorities. Economy-tier private-label buyers exhibit highest price sensitivity, while premium-channel purchasers prioritize provenance verification over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Uni-President Enterprises Corporation and Suntory Holdings Limited operating integrated beverage production bases across Taiwan and mainland China. Raw material sourcing draws from New Zealand milk powder suppliers, Fujian tea extract processors, and Thai non-dairy creamer formulators. Single-source vulnerability in high-elevation Taiwanese oolong leaf supply constrains premium SKU expansion during harvest disruptions. Distribution runs through Yangtze River Delta cold-chain hubs feeding supermarket and convenience store networks, with direct-to-consumer subscription platforms bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bottled milk tea is approaching a platform-economics inflection where pantry-management app integration restructures consumer replenishment relationships around data-driven subscription algorithms rather than retail slotting dominance.
For Market Incumbents: Build data moats through exclusive platform partnerships with Alibaba and Meituan pantry-management ecosystems. Incumbents should deepen captive supply of high-elevation Taiwanese oolong to defend against terroir-claim challengers, while accelerating aseptic technician training programs to unlock secondary Chinese manufacturing hub expansion before talent scarcity hardens. For New Entrants and Emerging Players: Establish a beachhead in South Korean tetra pak convenience channel tests, where ambient carton format adoption remains underdeveloped relative to cold-chain plastic dominance. New entrants should target Vietnamese fruit-infusion seasonal variants leveraging Mekong Delta puree suppliers, entering through direct-to-consumer platforms that bypass incumbent-controlled retail slotting infrastructure. For Investors and Strategic Acquirers: Dairy-specialist mid-cap formulators with FDA-SAMR dual certification capabilities represent the most defensible acquisition archetype as regulatory compliance timelines extend. Long-term viability hinges on reformulation agility under sugar-tax exposure across Thailand, Malaysia, and Singapore. Watch for GB standards harmonization completion as signal that single-packaging regional scale economics have activated.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | Extended shelf-life credentials unlock convenience store cooler space allocation in Shanghai and Tokyo networks. |
| Blockchain Provenance Integration | Taiwanese oolong sourcing verification satisfies mainland Chinese buyer scrutiny for premium gift-channel positioning. |
| Stevia-Monk Fruit Reformulation | SAMR carbohydrate disclosure mandates drive sugar-reduced variant development without sacrificing shelf appeal. |
| Tetra Pak Channel Penetration | Ambient carton distribution bypasses cold-chain limits in South Korean and Vietnamese commuter transit channels. |
| Subscription Platform Partnership | Direct-to-consumer replenishment models capture recurring purchase patterns while eliminating retail slotting fee burdens. |
Research Methodology
A standing panel of beverage brand managers, convenience store category buyers, aseptic processing engineers, and tea sourcing specialists provided ongoing calibration across the study period. Primary interview insights were cross-validated against secondary sources including China SAMR GB standards filings, Japanese METI regulatory bulletins, Taiwan FDA food additive registers, and Nielsen retail audit data for East Asian beverage channels. Bottom-up volume modeling from individual SKU velocities was reconciled with top-down category spend estimates to anchor projection credibility.
Scenario-bracketing around sugar-tax implementation timelines and aseptic technician availability constraints bounded high and low growth paths across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and flavor profile, with regional regulatory cluster effects incorporated for China, Japan, Taiwan, South Korea, and Vietnam. CAGRs were derived from normalized baseline trajectories adjusted for channel-shift elasticity and reformulation investment cycles.
Stress conditions across dairy input price volatility, extended producer responsibility scheme adoption rates, and platform-economy subscription penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding GB standards harmonization completion and METI energy-drink classification stability. Quarterly review of convenience store cooler space allocation trends and SAMR enforcement intensity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Detox Tea Market
Tea
Europe Tea Market
Tea
Pyramid Tea Bags Market
Tea
Mate Tea Market
Tea
Light-Fermented Tea Market
Tea
Smart Tea Maker Market
Tea
Instant Tea Premixes Market
Tea
Natural Tea Extract Market
Tea
Instant Tea Premix Consumption Market
Tea
Nitro Tea Market
Tea
Pu-Erh Tea Market
Tea
Asia-Pacific Tea Market
Tea
China Tea Market
Tea
Matcha Market
Tea
Black Tea Extracts Market
Tea
Green Tea Market