
 Pyramid Tea Bags Market | 2026-2036
Pyramid Tea Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Pyramid Tea Bags Market Analytics
A capital-intensity divergence between automated packing lines and semi-artisan operations is redrawing competitive boundaries in pyramid tea bag manufacturing. Mighty Leaf Tea leverages its integrated blending and packaging infrastructure to sustain margin control across North American premium channels. Twinings competes through century-old sourcing relationships that anchor its supply security for whole-leaf pyramid formats. Harney & Sons differentiates via small-batch production that occupies the ultra-premium gift segment with limited seasonal releases.
Pyramid tea bags are three-dimensional, often tetrahedral sachets constructed from nylon mesh, plant-based Soilon, or biodegradable cornstarch fibers, designed to allow whole-leaf expansion and optimal infusion flow. The structural form maximizes surface area contact between leaf and water, delivering fuller extraction than conventional flat paper bags. Green tea and herbal tea segments lead volume contribution, with herbal variants recording the fastest expansion as wellness positioning drives household pantry penetration. Specialty stores and online channels concentrate margin pools, while supermarket distribution competes primarily on promotional velocity and multi-pack formats.
FDA food-contact substance regulations govern nylon mesh safety in the United States, while the EU F-Gas Regulation and REACH frameworks constrain petrochemical-derived filter materials across European production. BIS packaging standards in India and Japan's JIS quality benchmarks further fragment compliance requirements for exporters. Stakeholders must monitor biodegradable material certification timelines and regional composting infrastructure readiness to align capital deployment with shifting substrate mandates.
Market Dynamics
The EU Single-Use Plastics Directive is forcing substrate transitions across European manufacturing, while biodegradable mesh certification timelines create capital deployment uncertainty for producers balancing compliance against production continuity.
Growth Catalysts
- REACH framework constraints:Petrochemical-derived filter materials face phase-down mandates across EU member states, redirecting R&D expenditure toward plant-based alternatives.
- Premium hospitality specification:Dubai and Riyadh hotel procurement programs now require pyramid sachets for tea service, establishing quality benchmarks that cascade into retail positioning.
- Whole-leaf extraction performance:Tetrahedral geometry maximizes surface area contact, delivering measurable infusion quality advantages over flat paper formats in specialty channels.
Market Restraints
- Cornstarch fiber cost volatility:Agricultural commodity price swings compress margins for biodegradable mesh producers unable to hedge input exposure.
- Composting infrastructure gaps:Industrial-scale biodegradation facilities remain concentrated in Germany and the Netherlands, limiting material viability in peripheral EU markets.
- Nylon mesh substitution pressure:FDA food-contact substance scrutiny elevates compliance costs for legacy petrochemical substrates in North American distribution.
Strategic Opportunities
- Indian specialty retail expansion:BIS packaging standard compliance creates first-mover advantage for certified biodegradable producers entering Mumbai and Bangalore premium channels.
- Direct-to-subscription channel development:Online platforms bypass supermarket promotional velocity requirements, capturing margin pools unavailable through mass retail.
- Soilon material convergence:Plant-based mesh integration with Japanese JIS quality benchmarks opens technical collaboration pathways with METI-supported innovation clusters.
Industry Challenges
- Biodegradable certification timeline compression:EU harmonized standards for industrial compostability remain under development, forcing producers to navigate multiple national approval pathways simultaneously.
- Automated packing line capex intensity:High-speed pyramid forming equipment requires seven-figure capital commitments that exclude semi-artisan competitors from scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyramid Tea Bags Market |
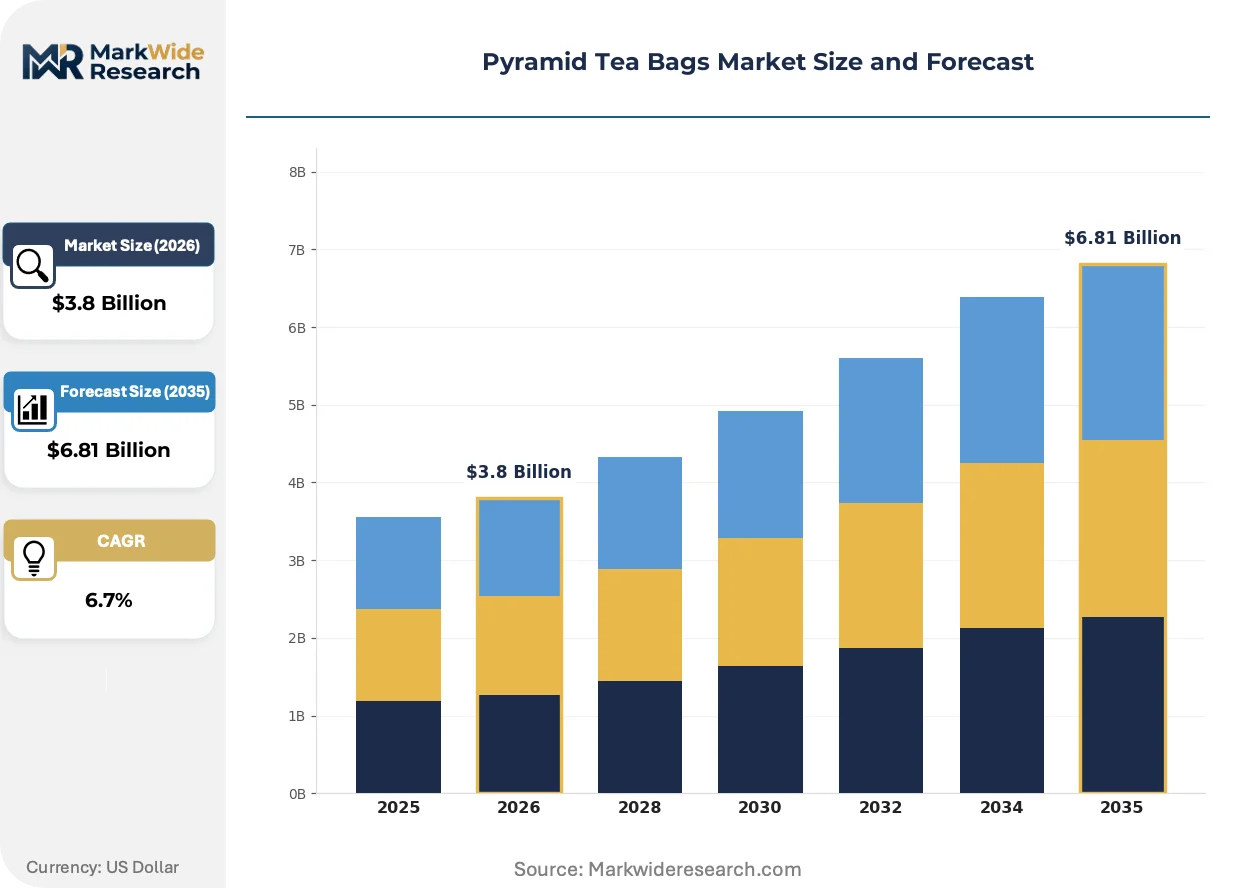
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Flavored Tea End User: Households, Cafes, Restaurants, Retail Stores Packaging Type: Box, Pouch, Jar, Display Case Distribution Channel: Online Store, Supermarket, Specialty Store, Wholesaler |
| Companies Covered | Mighty Leaf Tea, TWG Tea, Dilmah Tea, Yogi Tea, Bigelow Green Tea, Twinings, The Republic of Tea, ITO EN, Harney & Sons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyramid Tea Bags Market Evolving Landscape
Material science advances and regulatory chemistry are redrawing substrate hierarchies faster than supply chains can reconfigure, compressing decision windows for capital-intensive format transitions.
Biodegradable cornstarch fiber mesh is decomposing the nylon dominance that has governed pyramid construction for two decades. Specialty retailers in Germany and France are accelerating procurement transitions ahead of mandate deadlines. The technology is decomposing incumbent supply relationships as organic certification becomes a shelf-space gatekeeper.
EU F-Gas Regulation phase-down schedules are constraining petrochemical-derived filter manufacturing across member states. Production facilities in Italy and Spain face accelerated retooling requirements to maintain market access. Herbal tea segments with wellness positioning show highest sensitivity to substrate provenance claims.
Wellness-driven pantry penetration is rotating demand toward herbal variants with transparent sourcing credentials. Specialty stores and online channels are displacing supermarket dominance for margin-accretive single-origin offerings. Japanese metropolitan consumers demonstrate strongest willingness-to-pay premiums for biodegradable packaging verified against JIS benchmarks.
Pyramid Tea Bags Market Segmentation
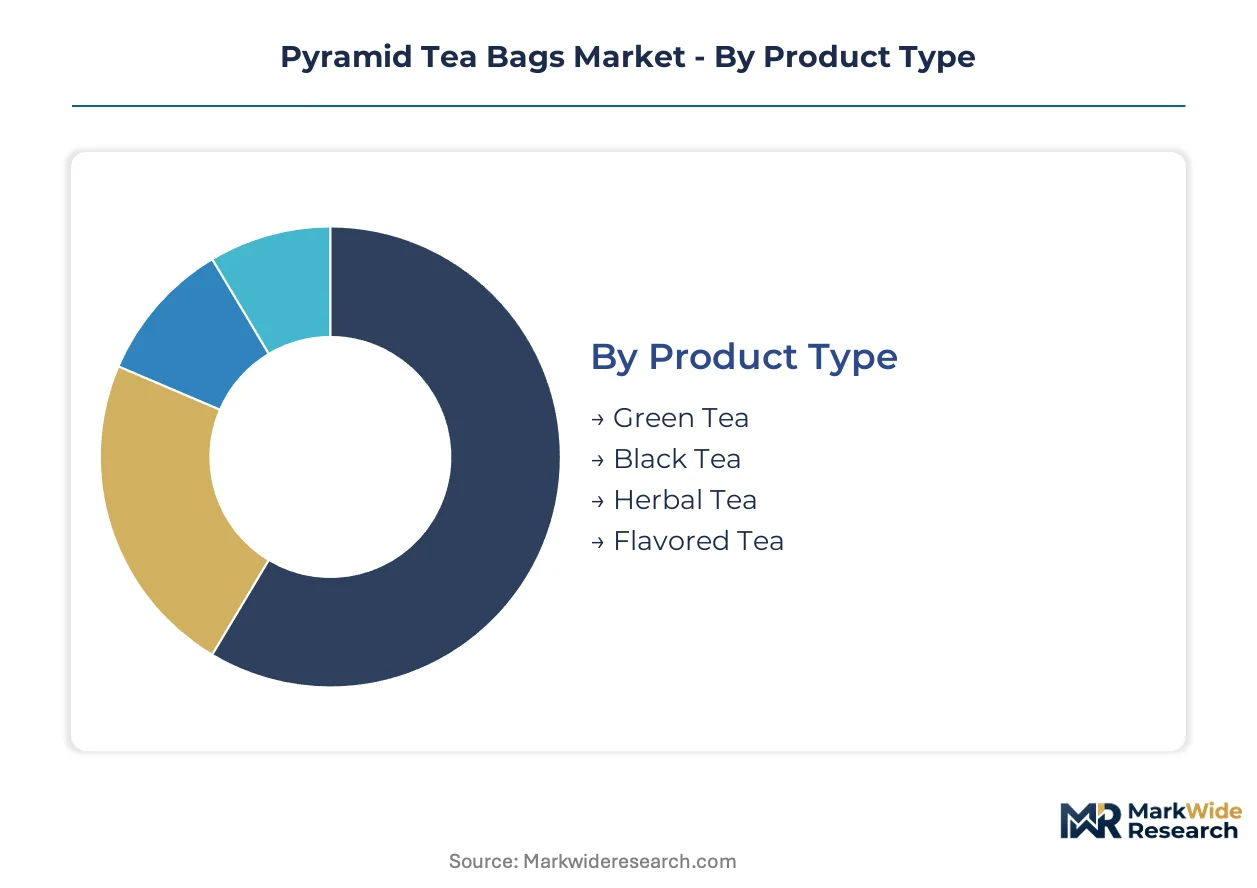
Pyramid tea bag segmentation reveals how substrate choices, channel economics, and end-use specifications fragment addressable markets. Manufacturers must align format investments with the margin structures and compliance requirements of each distinct slice.
Product Type:
Green tea and herbal variants flow disproportionately through specialty retail and direct-to-consumer channels, while black tea concentrates in supermarket promotional velocity programs.
- Green Tea:Whole-leaf sencha and matcha blends require nylon or Soilon mesh to permit full leaf expansion during steeping. Demand clusters in Japanese metropolitan markets and German organic certification channels where JIS and EU organic standards create shelf-space gatekeepers.
- Herbal Tea:Chamomile, rooibos, and wellness-positioned botanical blends drive the steepest expansion trajectory as pantry penetration accelerates. Wellness credentials and transparent sourcing claims command premium pricing in online subscription channels.
- Black Tea:Orthodox and CTC whole-leaf formats dominate hospitality procurement specifications in Dubai and Riyadh, where tetrahedral presentation signals service quality.
- Flavored Tea:Fruit and spice infusions rely on aroma-retentive packaging formats, with seasonal limited releases capturing gift segment margins.
Black tea dominates installed base. Herbal tea is where expansion concentrates.
End User:
Cost tier stratification separates household pantry staples from foodservice specifications that mandate presentation quality and batch consistency.
- Households:Pantry stock-up purchases favor multi-pack box formats and promotional pricing, with biodegradable substrate premiums accepted only in certified organic channels.
- Cafes:Independent coffeehouses specify pyramid sachets for differentiation against commodity flat-bag competitors, sourcing through specialty wholesalers with custom blending capabilities.
- Restaurants:Fine dining establishments in premium hospitality clusters require consistent infusion performance and branded presentation, with procurement centralized through group purchasing organizations.
- Retail Stores:Specialty tea merchants capture the highest per-unit margins through single-origin storytelling and limited seasonal releases.
Households dominate volume throughput. Restaurants are where margin expansion concentrates.
Packaging Type:
Volume scale and margin accretion diverge sharply between protective shipping formats and presentation-ready display configurations.
- Box:Rigid paperboard with foil-lined inner sleeves protects aroma integrity across extended supply chains, dominating supermarket and mass retail distribution.
- Pouch:Flexible stand-up bags with resealable closures reduce unit shipping costs for direct-to-consumer and subscription channel fulfillment.
- Jar:Glass or PET containers with wide-mouth access suit bulk loose-leaf refills, concentrating in specialty retail environments where visual merchandising drives impulse conversion.
- Display Case:Countertop acrylic or bamboo holders position individual sachets for hospitality service programs and premium gift assortments.
Box formats dominate unit shipments. Display cases are where premium positioning concentrates.
Distribution Channel:
Channel selection determines substrate certification requirements, pricing architecture, and working capital intensity for producers.
- Online Store:Direct-to-consumer platforms bypass retail margin stacking, enabling biodegradable premium pricing and subscription-based recurring revenue models.
- Supermarket:Mass retail distribution competes on promotional velocity and multi-pack value formats, with private-label penetration pressuring branded margin structures.
- Specialty Store:Curated assortments in Munich, Paris, and Tokyo premium districts prioritize organic certification and JIS-compliant biodegradable mesh as shelf-space prerequisites.
- Wholesaler:Foodservice and hospitality supply intermediaries aggregate demand across property portfolios, with Dubai and Riyadh hotel procurement programs specifying pyramid formats as service quality benchmarks.
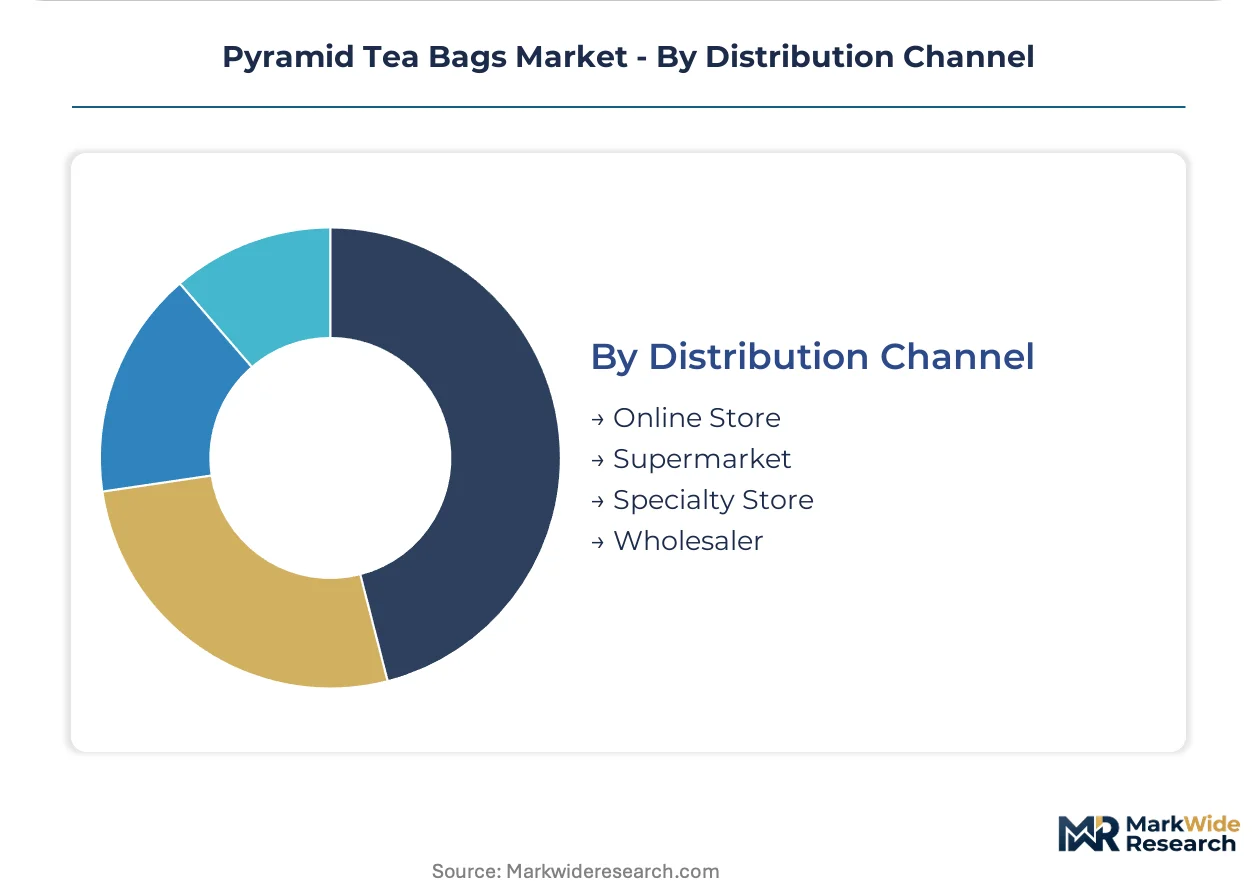
Supermarkets dominate unit volume. Online stores are where margin capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pyramid tea bag substrates and finished sachets concentrate in corridors linking Asian manufacturing hubs to European and Middle Eastern consumption centers. Germany and the Netherlands maintain net import positions for biodegradable mesh materials while serving as redistribution nodes for EU inland markets.
Germany
Specialty retail chains in Munich and Hamburg drive certified organic pyramid sachet procurement ahead of EU mandate deadlines. REACH framework constraints on petrochemical-derived filters redirect domestic blending operations toward plant-based Soilon alternatives. The Cologne-Düsseldorf corridor hosts packaging converters retooling lines for industrial compostability certification.
United States
FDA food-contact substance scrutiny elevates compliance expenditure for nylon mesh importers serving premium hospitality and direct-to-consumer channels. Wellness-positioned herbal variants command biodegradable packaging premiums in California and New York metro subscription markets. Pacific Northwest roasting cooperatives specify whole-leaf pyramid formats for café differentiation programs.
Japan
METI-supported innovation clusters in Tokyo and Osaka advance technical collaboration pathways for Soilon mesh integration with JIS quality benchmarks. Kanto metropolitan consumers demonstrate strongest willingness-to-pay premiums for biodegradable packaging verification. Nagoya-based machinery fabricators supply high-speed tetrahedral forming equipment to regional producers.
United Arab Emirates
Dubai hotel procurement programs specify pyramid sachets as service quality benchmarks, establishing presentation standards that cascade into regional retail positioning. MOHAP food-contact regulations govern import clearance for nylon and plant-based mesh materials. Abu Dhabi hospitality group purchasing organizations centralize tea service specifications across property portfolios.
India
BIS packaging standard compliance creates first-mover positioning for certified biodegradable producers entering Mumbai and Bangalore premium channels. Maharashtra and Karnataka specialty retailers prioritize organic certification as shelf-space gatekeepers. Delhi-NCR foodservice distributors aggregate demand across independent café segments seeking differentiation against commodity flat-bag competitors.
Pyramid Tea Bags Market Competitive Landscape
Concentration sits with heritage blending houses and integrated packaging specialists that control upstream substrate sourcing and downstream channel access. The vendor base spans three distinct tiers: century-old sourcing relationships anchoring supply security, automated packing infrastructure sustaining margin control, and small-batch artisan operations occupying gift segment niches. Strategic moves center on substrate certification pre-positioning ahead of EU mandate deadlines and direct-to-subscription channel development bypassing retail margin stacking.
Among heritage blending houses, Twinings and Harney & Sons exemplify contrasting scale archetypes within premium positioning. Twinings represents integrated supply security through established sourcing relationships, while Harney & Sons occupies the ultra-premium gift tier with limited release formats. Mighty Leaf Tea anchors the infrastructure-intensive vector, with integrated blending and packaging operations sustaining margin control across North American specialty channels. These three entities collectively illustrate how capital deployment diverges between automated scale and artisan batch economics.
| Leading Market Players |
|---|
| Mighty Leaf Tea |
| TWG Tea |
| Dilmah Tea |
| Yogi Tea |
| Bigelow Green Tea |
| Twinings |
| The Republic of Tea |
| ITO EN |
| Harney & Sons |
| Others |
Value Network & Pricing Analysis
High-speed automated packing line utilization rates above 85 percent in Germany and Japan anchor margin structures across the pyramid tea bag value chain, compressing unit economics for semi-artisan competitors while elevating price floors for biodegradable mesh formats. This capacity concentration shapes procurement leverage for hospitality buyers in Dubai and Riyadh, who extract presentation-quality specifications at volume-scaled terms.
Pricing Analysis
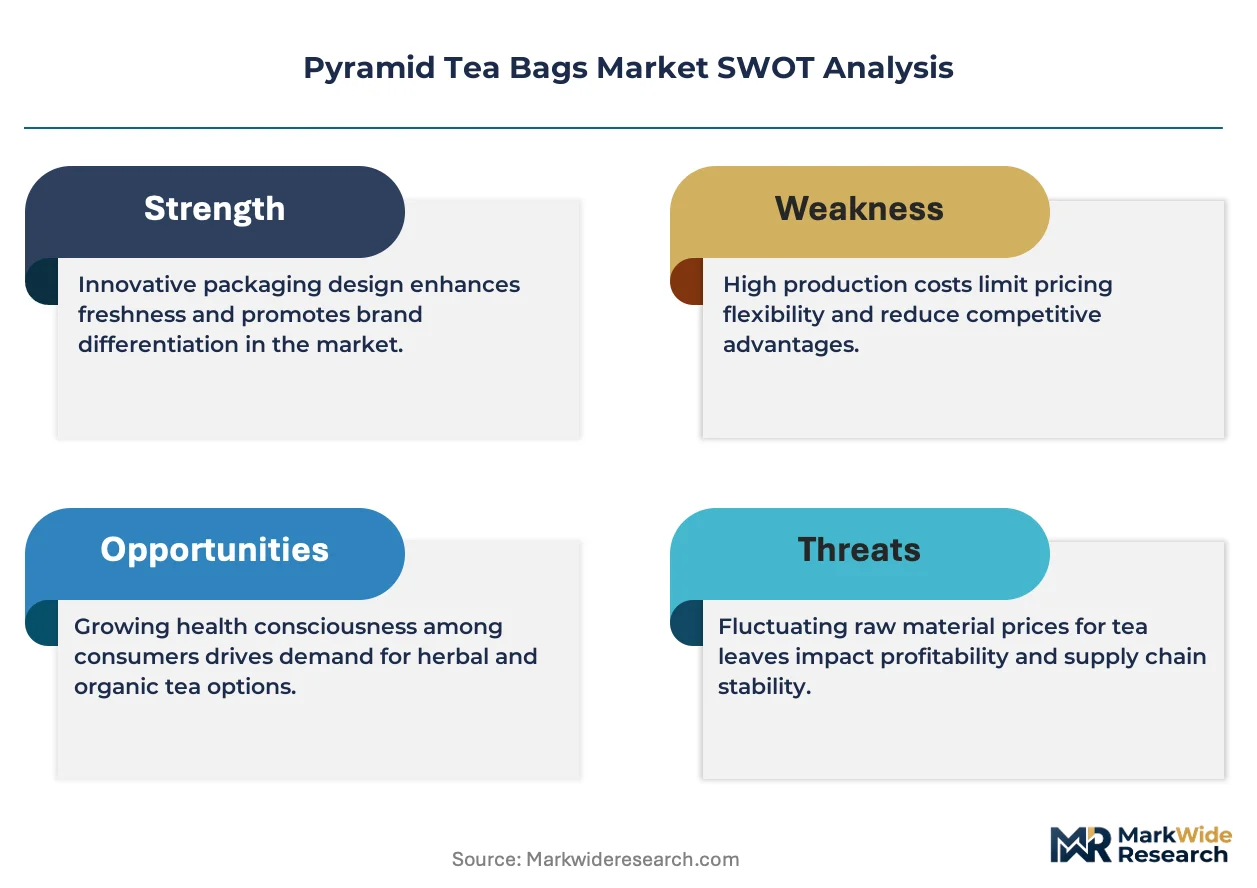
Hospitality procurement managers anchor three-tier pricing structure across premium, standard, and economy levels, with organic certification and JIS-compliant biodegradable mesh commanding shelf-space premiums in Munich and Tokyo specialty channels. Cornstarch fiber input volatility is intensifying cost compression in the biodegradable tier as agricultural commodity swings transmit directly to mesh converters. Supermarket private-label buyers exhibit highest price sensitivity, while Dubai hotel group purchasing organizations demonstrate lowest elasticity due to service-quality mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate European biodegradable mesh procurement as REACH framework phase-down schedules force rapid substrate transitions without strategic stockpile buffers. Manufacturing concentration rests on China for nylon mesh, Japan for Soilon plant-based alternatives, and Germany for cornstarch fiber conversion equipment. Single-source vulnerability runs through Nagoya-based high-speed tetrahedral forming machinery fabricators. Distribution runs through Rotterdam and Hamburg redistribution nodes for EU inland markets, with Dubai Jebel Ali serving Middle East hospitality corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyramid tea bag demand cycles track wellness pantry penetration and regulatory mandate implementation waves, with the current upswing driven by EU Single-Use Plastics Directive compliance deadlines accelerating substrate replacement programs.
For Market Incumbents: Fortify biodegradable certification pipelines ahead of harmonized EU standards completion, locking in industrial compostability approvals across Germany, France, and the Netherlands. Anchor supply security through backward integration into Soilon mesh production or captive cornstarch fiber sourcing, neutralizing agricultural commodity exposure that threatens margin stability. For New Entrants and Emerging Players: Lead with direct-to-subscription channel development targeting California and New York metro wellness consumers, bypassing supermarket promotional velocity requirements that favor scaled incumbents. Penetrate Indian specialty retail through BIS packaging standard compliance as Mumbai and Bangalore organic certification channels expand shelf-space allocation for verified biodegradable formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated packing infrastructure owners with integrated blending capabilities, as seven-figure capital commitments exclude artisan competitors from scale economies. Monitor EU harmonized compostability certification timeline compression as the inflection signal indicating which substrate investments will retain regulatory validity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Mesh Certification | Industrial compostability approval unlocks German and Dutch specialty retail shelf access ahead of mandate deadlines. |
| Direct-to-Consumer Channel Launch | Subscription platforms capture margin pools unavailable through supermarket promotional velocity programs. |
| Backward Integration into Soilon Production | Captive plant-based mesh supply neutralizes agricultural commodity price volatility compressing biodegradable tier margins. |
| Hospitality Procurement Specification | Dubai and Riyadh hotel group purchasing organization mandates establish quality benchmarks cascading into retail positioning. |
| High-Speed Packing Line Automation | Tetrahedral forming equipment ownership excludes semi-artisan competitors from volume-scale economies. |
Research Methodology
The analysis maps green tea, herbal, black, and flavored pyramid formats, each validated through blending house procurement directors, specialty retail category managers, hospitality group purchasing organization executives, and biodegradable mesh converter technical leads. Primary fieldwork combined structured interviews with secondary validation against EU F-Gas Regulation filings, REACH substance restriction updates, BIS packaging standard notifications, and FDA food-contact substance petitions. Bottom-up volume triangulation across substrate types, channel flows, and end-use specifications converged with top-down market sizing against customs trade data and retail audit panels.
Consistency checks validated volume and value outputs against external benchmarks including hospitality procurement database aggregations, specialty tea merchant inventory turnover disclosures, and machinery fabricator order backlogs. The analytical framework segments by product type, end user, packaging configuration, and distribution channel across the projection horizon. CAGRs derived from substrate transition velocity modeling, regulatory mandate implementation schedules, and wellness pantry penetration curves specific to herbal variant demand expansion.
Forecasts assume regulatory continuity in EU REACH and F-Gas frameworks, FDA food-contact substance enforcement, and Japanese JIS quality benchmark maintenance; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as biodegradable certification timeline compression and composting infrastructure deployment gaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
High Protein Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Tea Essence Market
Tea
Instant Tea Premixes Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Green Tea Leaves Market
Tea
Global Tea Market
Tea
Instant Tea Premix Consumption Market
Tea
Oolong Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
Smart Tea Set Market
Tea
Bottled Milk Tea Market
Tea
Natural Tea Extract Market
Tea
Global Ready-To-Drink Green Tea Market