
 India Energy Drinks Market | 2026-2036
India Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
India Energy Drinks Market Foresight
Maharashtra's beverage manufacturing base is rebalancing toward functional drink capacity as energy drink volumes surge. Red Bull India leverages its established motorsport marketing heritage to sustain premium positioning in tier-one cities. Monster Energy competes through aggressive pricing and expanded retail visibility in convenience stores. PepsiCo India anchors its growth via the Sting brand, which dominates smaller-format packaging across semi-urban markets.
India energy drinks are non-alcoholic beverages formulated with caffeine, taurine, B-vitamins, and carbohydrates, typically containing 80-300 mg caffeine per serving, designed to enhance mental alertness and physical performance. Carbonated variants occupy the largest volume share, while sugar-free formulations capture expanding margin pools as health-conscious consumers shift away from high-calorie options. Working professionals and college students represent the fastest-growing end-user clusters, with distribution gravitating toward online retail and convenience stores as channel control becomes decisive.
FSSAI governs caffeine limits and labeling standards, while BIS certification requirements shape packaging material specifications and quality benchmarks. The PLI scheme for food processing indirectly supports domestic manufacturing scale-up, altering cost structures for local producers. Stakeholders must monitor evolving caffeine regulations and state-level excise variations that could reshape profitability across India's fragmented beverage taxation landscape.
Market Dynamics
FSSAI's tightened caffeine labeling norms are forcing reformulation across India's energy drink portfolio, compressing product development cycles and reshaping competitive positioning between established multinationals and domestic challengers.
Growth Catalysts
- Urban Professional Demand:Working professionals in Mumbai and Bengaluru are expanding consumption frequency, creating sustained volume pull for functional beverages.
- PLI Scheme Indirect Support:India's production-linked incentive scheme for food processing is altering domestic manufacturing cost structures for local energy drink producers.
- Convenience Store Expansion:Modern retail formats are penetrating semi-urban Maharashtra and Karnataka, extending distribution reach beyond traditional trade.
Market Restraints
- Caffeine Input Volatility:Synthetic caffeine supply concentrates among a limited set of pharmaceutical-grade suppliers, exposing margins to pharmaceutical sector demand swings.
- State-Level Excise Fragmentation:India's beverage taxation landscape varies across state boundaries, complicating national pricing strategy and inventory deployment.
- Health-Conscious Substitution:Unsweetened functional teas and cold-pressed juices are capturing share among wellness-oriented consumers in premium urban clusters.
Strategic Opportunities
- Sugar-Free Formulation White Space:Health-conscious consumer segments in tier-one cities are creating margin pools for zero-calorie energy drink variants.
- Online Channel Penetration:E-commerce platforms are enabling direct-to-consumer distribution models that bypass traditional retail margin stacking.
- BIS Certification Alignment:Domestic producers leveraging Bureau of Indian Standards packaging specifications can accelerate market access versus import-dependent competitors.
Industry Challenges
- Regulatory Compliance Timeline Compression:FSSAI's evolving caffeine disclosure requirements demand rapid label redesign and supply chain documentation.
- Talent Scarcity in Functional Beverage Formulation:Experienced food technologists with energy drink-specific expertise command premium compensation in India's competitive FMCG labor market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Energy Drinks Market |
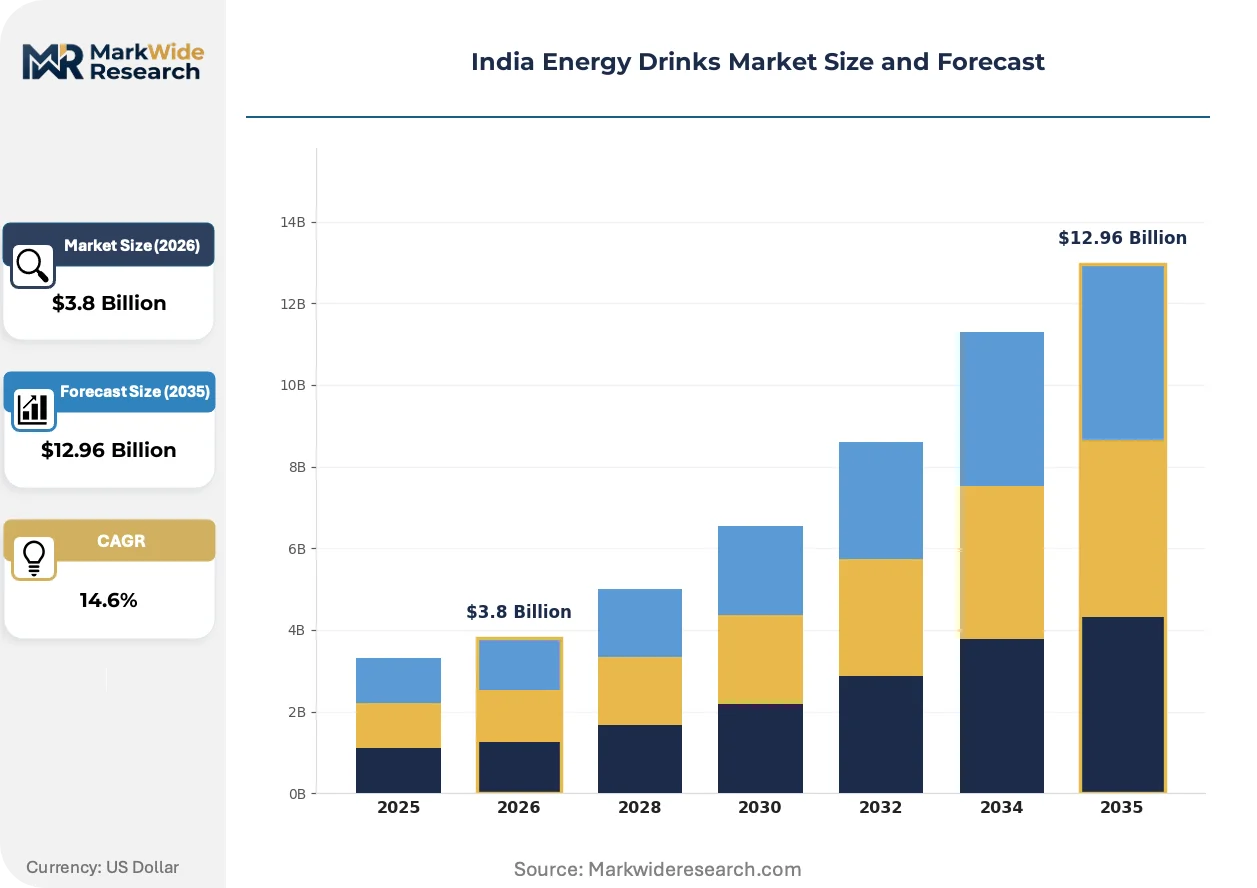
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Sugar-Free, Herbal Packaging Type: Can, Bottle, Tetra Pack, Sachet End User: College Students, Working Professionals, Athletes, Fitness Enthusiasts Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Clubs |
| Companies Covered | Red Bull India, Monster Energy, PepsiCo India (Sting), The Coca-Cola Company (Burn/Charged), Anheuser-Busch InBev India (Budweiser), Celsius Holdings, Tata Consumer Products, Hector Beverages (Tzinga), Hell Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Energy Drinks Market Shifts & Advancements
Product formulation and distribution architecture are undergoing parallel transformation in India's energy drink sector, with regulatory pressure and channel evolution operating as twin accelerants of competitive differentiation.
Natural caffeine extraction from green coffee beans and tea leaves is converging with botanical adaptogen blends to create cleaner-label energy formulations. Health-conscious millennials in Bengaluru and Mumbai are adopting these variants at premium price points. This ingredient shift is compressing the market share of synthetic caffeine-dependent legacy products.
FSSAI's 2024 caffeine disclosure mandate requires per-serving content declaration alongside health advisory warnings. Manufacturers are reformulating portfolios to cluster below 150 mg thresholds that trigger stricter labeling. Smaller-format packaging in Maharashtra is seeing fastest compliance adaptation as brands pre-empt regulatory scrutiny.
College students and young professionals are consolidating purchases through quick-commerce platforms offering sub-30-minute delivery. Convenience stores in urban Karnataka are responding with dedicated energy drink cold-chain sections. This channel rotation is most visible in Mumbai's dense suburban corridors where traditional kirana stores cede share to app-based fulfillment.
India Energy Drinks Market Segmentation
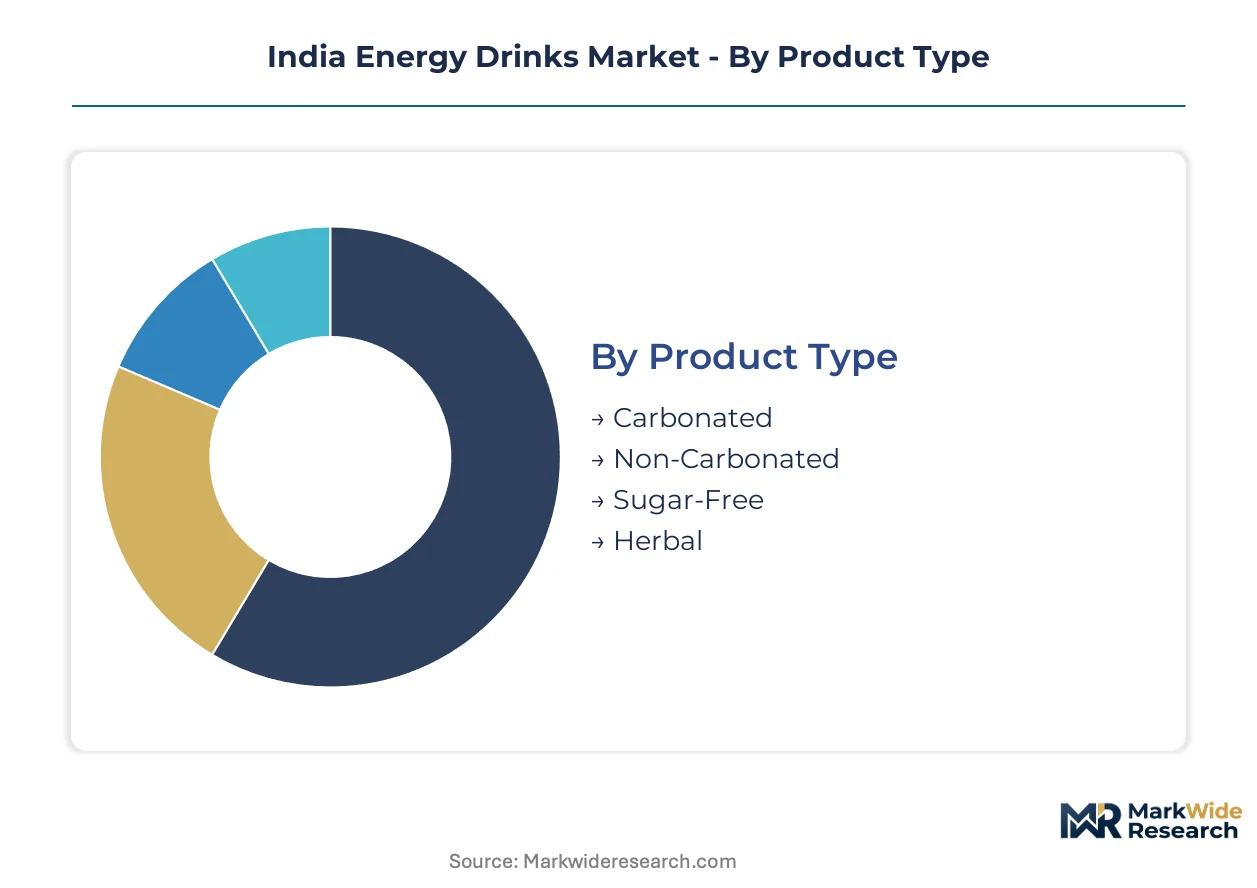
India's energy drink market fragments across four dimensions that determine pricing power, channel access, and formulation requirements. Each segmentation layer reveals distinct competitive dynamics between multinational incumbents and domestic challengers navigating FSSAI compliance.
Product Type:
Volume leadership sits with carbonated variants, while premium margin capture concentrates in health-positioned alternatives. The carbonated-sugar-free split defines current competitive investment priorities.
- Carbonated:Fizzy formulations with 80-150 mg caffeine per serving dominate retail shelf space in Maharashtra and Karnataka. Working professionals in Mumbai drive repeat purchase frequency through convenience store channels.
- Sugar-Free:Zero-calorie variants using artificial sweeteners command 40-60% price premiums in Bengaluru's premium retail clusters. Health-conscious millennials are displacing full-sugar consumption in tier-one urban corridors.
- Non-Carbonated:Still functional beverages appeal to athletes seeking hydration without gastric discomfort during training.
- Herbal:Botanical adaptogen blends with ashwagandha and ginseng extracts target wellness-oriented consumers in metro yoga studios.
Mature deployment sits with Carbonated. Newer deployment is concentrated in Sugar-Free.
Packaging Type:
Format selection directly shapes distribution economics and consumption occasion targeting across India's fragmented retail landscape.
- Can:Aluminum containers enable superior cold-chain performance and premium positioning in urban convenience stores. College students in Bengaluru favor 250 ml formats for on-campus consumption.
- Bottle:PET packaging reduces unit costs for price-sensitive semi-urban expansion in Maharashtra's secondary cities.
- Tetra Pack:Aseptic cartons extend shelf life without refrigeration, penetrating rural Karnataka's traditional trade.
- Sachet:Single-serve powder sachets enable trial conversion among first-time energy drink users in tier-three towns.
Can formats dominate urban deployment. Sachet distribution is expanding fastest in emerging consumption pockets.
End User:
Professional and student clusters are diverging in consumption timing, price sensitivity, and brand loyalty patterns.
- Working Professionals:White-collar employees in Mumbai's financial districts sustain afternoon consumption rituals. FSSAI's caffeine disclosure mandates are shifting purchasing toward transparently labeled products.
- College Students:University populations in Bengaluru and Pune drive late-night study occasion demand. Quick-commerce platforms are capturing this segment through sub-30-minute delivery promises.
- Athletes:Competitive sports participants require electrolyte-enhanced formulations for endurance support.
- Fitness Enthusiasts:Gym-goers in metro premium fitness centers seek pre-workout stimulation with clean-label positioning.
Working Professionals anchor established consumption. College Students are climbing the fastest in volume contribution.
Distribution Channel:
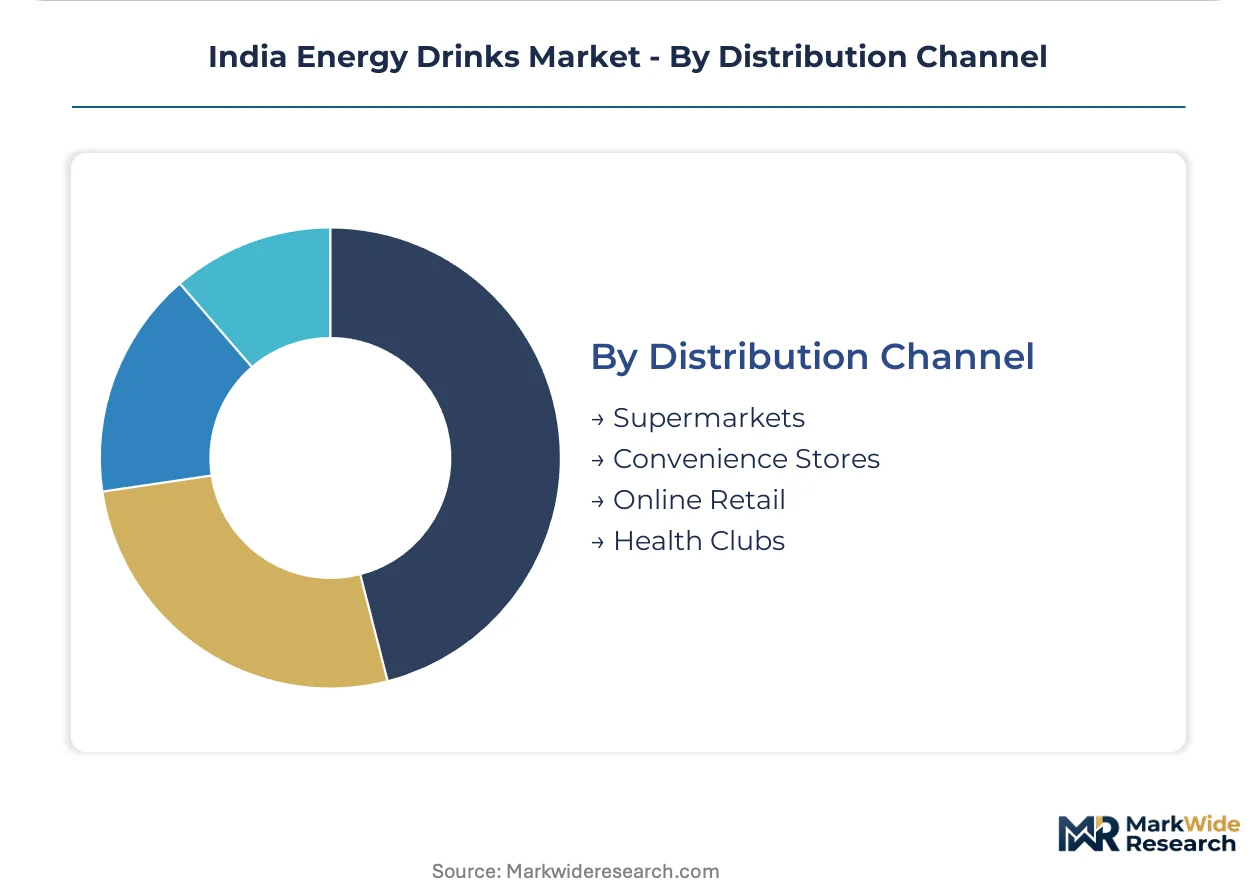
Channel control determines margin stacking and brand visibility in India's evolving beverage retail architecture.
- Convenience Stores:Modern retail formats with dedicated cold-chain sections dominate Mumbai's suburban corridors. 24-hour operations align with professional late-shift consumption patterns.
- Online Retail:Direct-to-consumer platforms bypass traditional distributor margins, enabling subscription models in Bengaluru's tech workforce clusters.
- Supermarkets:Large-format retailers provide brand discovery opportunities through end-cap promotions and multi-pack bundling.
- Health Clubs:Gym-based vending and café integration targets fitness enthusiast segments with contextual placement.
Supermarkets represent mature channel deployment. Online Retail is gaining share fastest among urban professional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caffeine sourcing corridors through Gujarat and Maharashtra anchor India's energy drink manufacturing geography. State-level excise variations and FSSAI compliance timelines create divergent investment climates across India's western and southern manufacturing belts.
Maharashtra
Mumbai's financial district professionals sustain afternoon consumption rituals through convenience store channels. FSSAI's 2024 caffeine disclosure mandate is accelerating label redesign investments among Mumbai-based bottlers. Pune's university corridor drives late-night study occasion demand through quick-commerce platforms.
Karnataka
Bengaluru's technology workforce clusters generate premium demand for sugar-free formulations with transparent ingredient labeling. BIS certification requirements for packaging materials are reshaping supplier qualification protocols among local contract manufacturers. The city's Whitefield and Electronic City corridors concentrate consumption among young professionals.
Gujarat
Ahmedabad's pharmaceutical-grade caffeine suppliers feed formulation requirements across western India. The state's production-linked incentive scheme for food processing is attracting greenfield beverage manufacturing investments. Surat's emerging retail modern trade is extending distribution reach into tier-two consumption pockets.
Delhi-NCR
Gurgaon's corporate office parks generate concentrated demand among consulting and technology sector employees. State excise variations between Delhi and Haryana complicate unified pricing strategies for cross-border distributors. Noida's logistics hubs are emerging as northern India distribution consolidation points.
Tamil Nadu
Chennai's manufacturing base supports canning and aseptic packaging capacity for southern market supply. The state's beverage taxation structure favors localized production over interstate sourcing from western hubs. Coimbatore's college-town demographics are driving trial conversion through single-serve sachet formats.
India Energy Drinks Market Competitive Landscape
Global majors compete with regional champions across pricing tiers and channel access dimensions. The market structure consolidates around three player categories: multinational beverage conglomerates with diversified portfolios, specialized energy drink pure-plays with motorsport marketing heritage, and domestic challengers leveraging localized formulation and distribution agility. Strategic moves concentrate on sugar-free portfolio expansion and quick-commerce channel capture.
Among multinational beverage conglomerates, Red Bull India and PepsiCo India exemplify divergent competitive approaches—one sustaining premium positioning through event marketing heritage, the other driving volume through aggressive convenience store penetration and smaller-format packaging. Monster Energy occupies a position between these archetypes, competing on price-point accessibility while maintaining international brand recognition. Domestic specialists including Hector Beverages and Tata Consumer Products sit within the challenger tier, leveraging BIS certification alignment and regional flavor adaptation to accelerate market access.
| Leading Market Players |
|---|
| Red Bull India |
| Monster Energy |
| PepsiCo India (Sting) |
| The Coca-Cola Company (Burn/Charged) |
| Anheuser-Busch InBev India (Budweiser) |
| Celsius Holdings |
| Tata Consumer Products |
| Hector Beverages (Tzinga) |
| Hell Energy |
| Others |
Supply & Pricing Matrix
Synthetic caffeine procurement costs cascade through India's energy drink value chain from pharmaceutical-grade suppliers in Gujarat and Maharashtra toward retail shelf price tiers. FSSAI's disclosure mandates compress formulation flexibility, forcing manufacturers to absorb compliance costs or pass them through to price-sensitive segments.
Pricing Analysis
Service bundling separates premium positioning from stripped-down economy plays. Red Bull India packages event access and motorsport content with core product, while domestic challengers unbundle to hit lower price points. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, caffeine transparency, and cold-chain investment depth. Cost compression in the sachet tier intensifies because of quick-commerce margin demands. College students in Pune and Coimbatore exhibit highest price sensitivity; Bengaluru tech professionals show lowest.
Supply Chain Analysis
Freight cost volatility from Gujarat's pharmaceutical corridors to Karnataka's retail hubs shapes inventory deployment decisions. Manufacturing concentrates in Maharashtra, Gujarat, and Tamil Nadu, with formulation capacity clustering near Mumbai and Ahmedabad. Synthetic caffeine, aluminum can stock, and natural extract inputs draw from China, domestic pharmaceutical suppliers, and Kerala's botanical processors. Single-source vulnerability sits with pharmaceutical-grade caffeine suppliers exposed to drug sector demand swings. Distribution runs through modern trade consolidation in Mumbai and Bengaluru before radiating to quick-commerce dark stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's tightening caffeine disclosure regime erects a compliance moat favoring incumbents with dedicated regulatory affairs capacity and reformulation budgets. New entrants face capital barriers that scale with label redesign velocity and supply chain documentation depth.
For Market Incumbents: Deploy sugar-free portfolio acceleration as the primary lever. Red Bull India and PepsiCo India should expand zero-calorie variants in Bengaluru and Mumbai premium clusters before health-conscious substitution erodes full-sugar volumes. Channel control through exclusive quick-commerce partnerships defends against Monster Energy's convenience store pricing aggression. Certification investment in BIS-compliant packaging specifications accelerates market access versus import-dependent challengers.
For New Entrants and Emerging Players: Begin with herbal adaptogen positioning in Tamil Nadu's Coimbatore college corridor and Karnataka's tier-two yoga studio networks. The wellness-oriented consumer segment shows lowest multinational penetration and highest willingness to trial domestic formulations. Single-serve sachet distribution through kirana stores enables trial conversion without cold-chain infrastructure investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic specialists with BIS certification alignment and regional flavor pipelines in Maharashtra and Gujarat. Long-term viability hinges on regulatory compliance capacity rather than brand marketing heritage. The signal to watch is FSSAI enforcement velocity in secondary cities, which will separate compliant scale players from marginal operators facing label redesign cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Free Formulation Expansion | Captures margin pools in Bengaluru and Mumbai health-conscious clusters ahead of substitution acceleration. |
| Quick-Commerce Channel Partnership | Bypasses traditional distributor margin stacking for direct access to college student and professional segments. |
| BIS Certification Alignment | Accelerates market access versus import-dependent competitors facing packaging material compliance delays. |
| Natural Caffeine Sourcing Transition | Green coffee and tea leaf extraction meets clean-label demand from premium urban millennials. |
| Regional Manufacturing Scale-Up | Gujarat PLI scheme incentives alter cost structures for domestic producers versus multinational importers. |
Research Methodology
Trade databases, FSSAI regulatory filings, and beverage industry association reports formed the secondary backbone of this analysis. Primary interviews with brand managers at multinational and domestic energy drink producers, category buyers at modern retail chains, and FSSAI compliance officers in Mumbai and Bengaluru supplemented documentary sources. Bottom-up volume modeling from convenience store audit data and quick-commerce platform disclosures triangulated against top-down market sizing from production capacity assessments and caffeine import records.
Bottom-up segmentation analysis across product type, packaging format, end-user archetype, and distribution channel generated volume and value outputs across the projection horizon. CAGRs derived from trend extrapolation of professional consumption frequency, student trial conversion rates, and channel shift velocity. Modeled inputs included FSSAI compliance timeline assumptions, state-level excise variation trajectories, and synthetic caffeine price sensitivity thresholds.
Underlying measurement precision varies by segment; carbonated and sugar-free product categories carry tighter precision than herbal and non-carbonated alternatives where volume data remains fragmented. Forecasts reflect assumptions about regulatory enforcement consistency and quick-commerce penetration rates that could shift with macroeconomic conditions or platform competitive dynamics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Hypertonic Drinks Market
Non-Alcoholic Beverages
Coffee Substitute Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Isotonic Drinks Market