
 Saudi Arabia Fruit Concentrate Market | 2026-2036
Saudi Arabia Fruit Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Fruit Concentrate Market Analytics
The Saudi Arabia fruit concentrate landscape is consolidating around a widening gap between premium cold-pressed concentrates and commodity heat-processed grades. Archer Daniels Midland Company leverages its global procurement network to secure cost-advantaged citrus and apple raw material streams for commodity blending. AGRANA Beteiligungs-AG differentiates through specialized berry concentrates targeting premium dairy and confectionery accounts. Almarai Company anchors the downstream pull, converting fruit concentrates across its integrated beverage and dairy operations in the Kingdom.
Fruit concentrate denotes a reduced-water extract prepared through evaporation, membrane filtration, or freezing, typically yielding soluble solids between 65 and 72 degrees Brix for stable transport and extended shelf life. The product serves primarily as a standardized flavor, color, and sweetness input for beverage reconstitution, bakery fillings, and dairy applications. Citrus concentrates dominate volume flows given established orange and lemon processing infrastructure, while tropical fruit concentrates represent the fastest-expanding category as Saudi beverage brands diversify beyond traditional flavor profiles. Tetra Packs command structural preference in institutional channels due to ambient stability and lower logistics cost per liter of reconstituted juice.
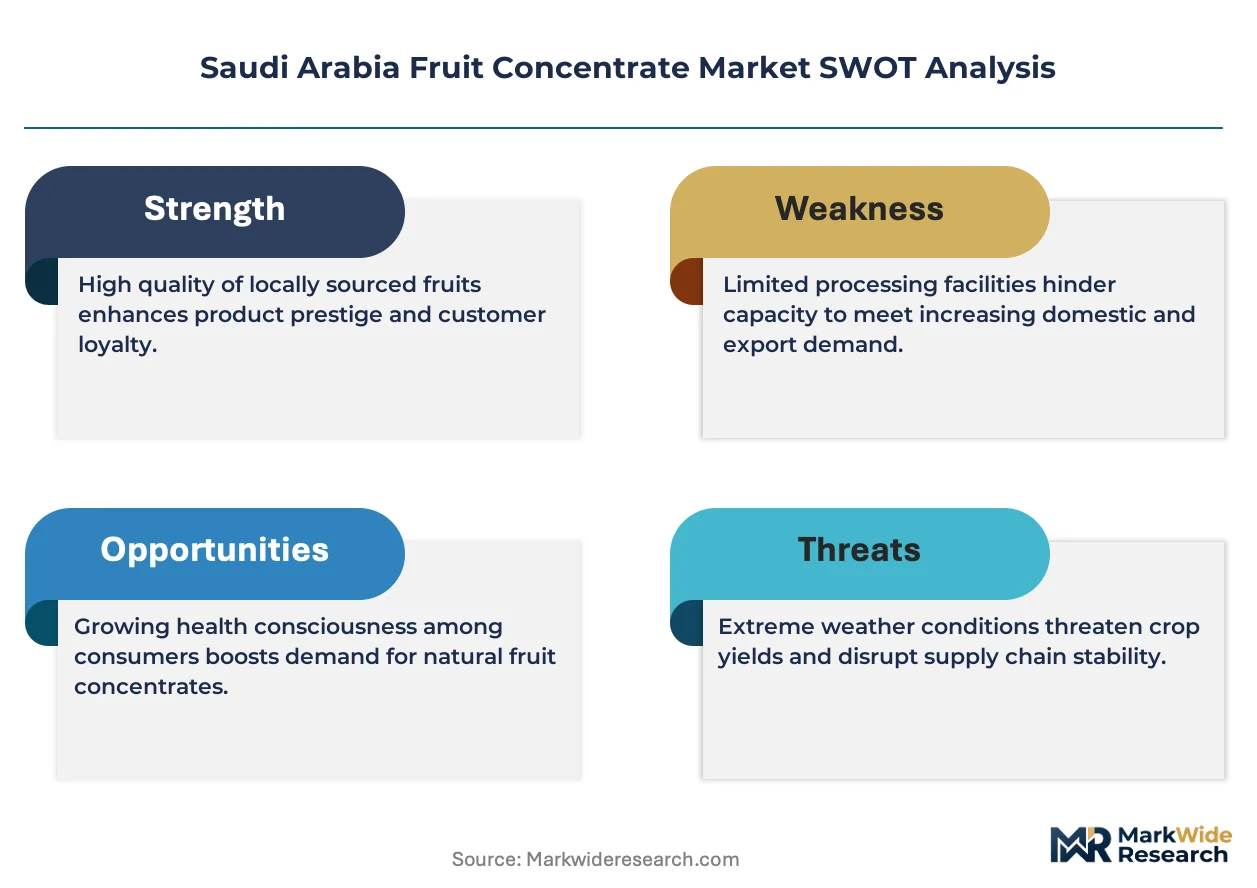
SFDA governs maximum residue limits for pesticides and heavy metals in imported fruit pulp, while SASO enforces the Saudi Quality Mark for packaged concentrates sold through retail channels. Both frameworks elevate compliance costs for smaller traders and favor suppliers with certified in-house laboratories and traceable supply chains. Processors must also navigate MOF customs valuation rules for concentrate imports, which influence landed cost structures relative to regional competitors. Stakeholders should monitor how the Kingdom's evolving food security agenda reshapes import dependency ratios versus domestic fruit processing investments.
Market Dynamics
SFDA pesticide residue limits and SASO quality certification requirements are compressing supplier margins while accelerating consolidation toward traceable, laboratory-equipped processors in Riyadh and Jeddah.
Growth Catalysts
- Beverage Reconstitution Demand:Dairy and juice manufacturers in the Central Region anchor procurement volumes for ready-to-drink formulations.
- SFDA Food Safety Protocols:Tighter additive and labeling standards push processors toward cleaner-label concentrates with certified supply chains.
- Cold-Pressed Processing:Premium extraction methods are capturing share in high-margin dairy and confectionery applications.
Market Restraints
- Import Dependency:MOF customs valuation rules for concentrate shipments elevate landed costs versus regional competitors.
- Heat-Processing Commoditization:Bulk citrus concentrate grades face margin compression from standardized global supply.
- Water Scarcity:Domestic fruit cultivation constraints limit backward integration into local raw material sourcing.
Strategic Opportunities
- Eastern Province Expansion:Underpenetrated food processing clusters in Dammam offer white-space for concentrate distribution.
- Tropical Concentrate Diversification:Mango and passionfruit extracts are displacing traditional orange in premium beverage lines.
- Saudi Quality Mark Acceleration:Retail channel certification mandates create first-mover advantage for compliant suppliers.
Industry Challenges
- Laboratory Certification Timelines:SFDA in-house testing requirements extend product registration cycles for new entrants.
- Legacy Equipment Integration:Membrane filtration upgrades face friction against existing evaporator infrastructure in mid-scale plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Fruit Concentrate Market |
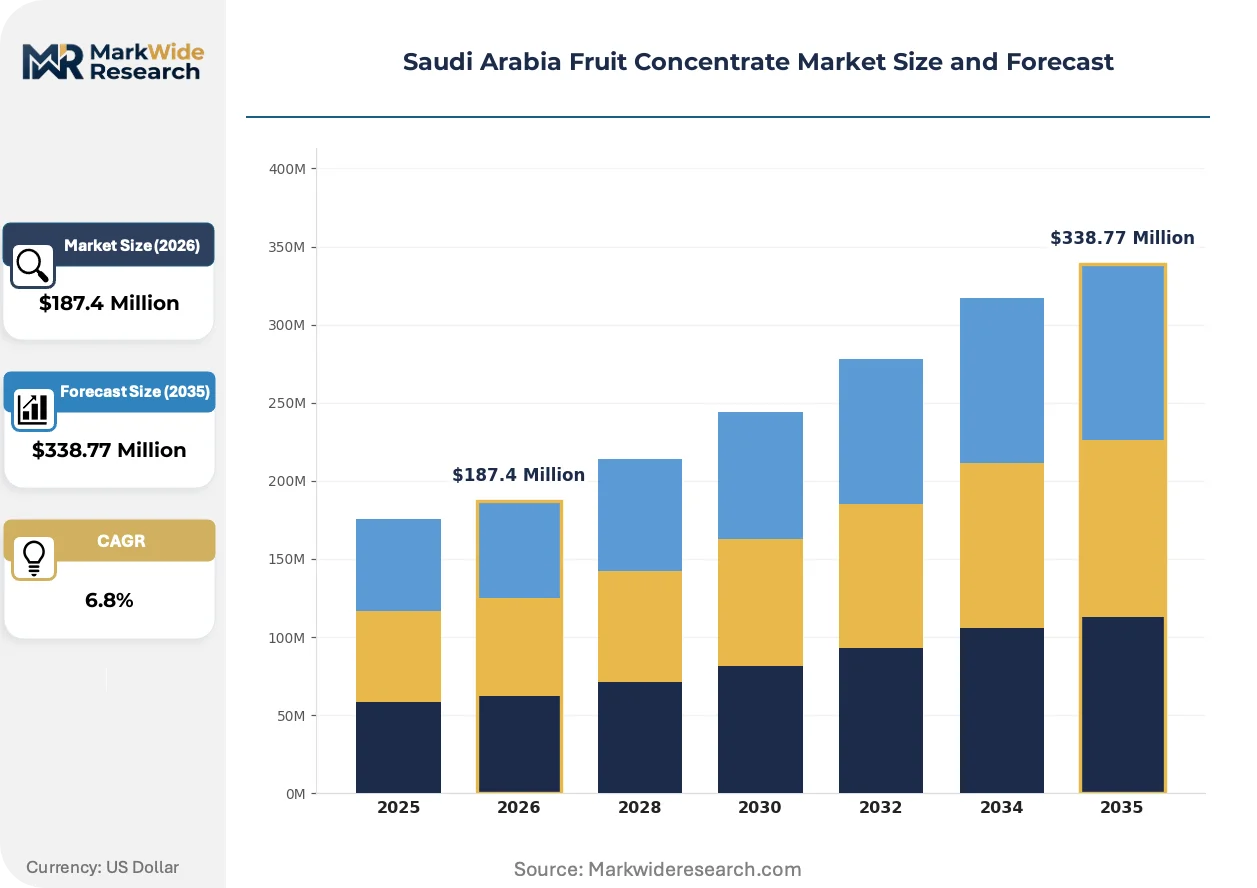
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Apples, Tropical Fruits End User: Beverages, Confectionery, Dairy, Bakery Packaging Type: Bottles, Tetra Packs, Cans, Pouches Sales Channel: Retail, Wholesale, Online, Export |
| Companies Covered | Archer Daniels Midland Company, AGRANA Beteiligungs-AG, Dohler Group, Kerry Group, Symrise AG, Almarai Company, Rubicon Arabia, Alsafi Danone, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Fruit Concentrate Market Evolving Landscape
Membrane filtration and aseptic packaging are compressing traditional heat-processing economics while SFDA enforcement tightens traceability requirements across the Kingdom's concentrate supply base.
Membrane filtration technology removes water through reverse osmosis and nanofiltration at lower thermal exposure, preserving volatile aromatic compounds in berry and tropical concentrates. Beverage manufacturers in Riyadh are adopting these systems for premium juice lines. Cold-pressed extraction is overtaking conventional evaporative methods in high-value dairy and confectionery applications where flavor fidelity commands price premiums.
SFDA maximum residue limits for pesticides and heavy metals in imported fruit pulp now require batch-level testing documentation from all suppliers. This enforcement elevates compliance costs for traders without certified laboratories. Smaller importers are exiting retail channels as SASO Saudi Quality Mark certification becomes a de facto requirement for supermarket listings.
Buyer concentration around Central Region dairy and beverage clusters has shifted procurement toward direct manufacturer relationships and away from trading intermediaries. Large processors in Riyadh now negotiate annual volume contracts with concentrate suppliers, compressing spot market liquidity. This consolidation is most visible in orange concentrate offtake, where three integrated beverage operations account for the majority of national demand.
Saudi Arabia Fruit Concentrate Market Segmentation
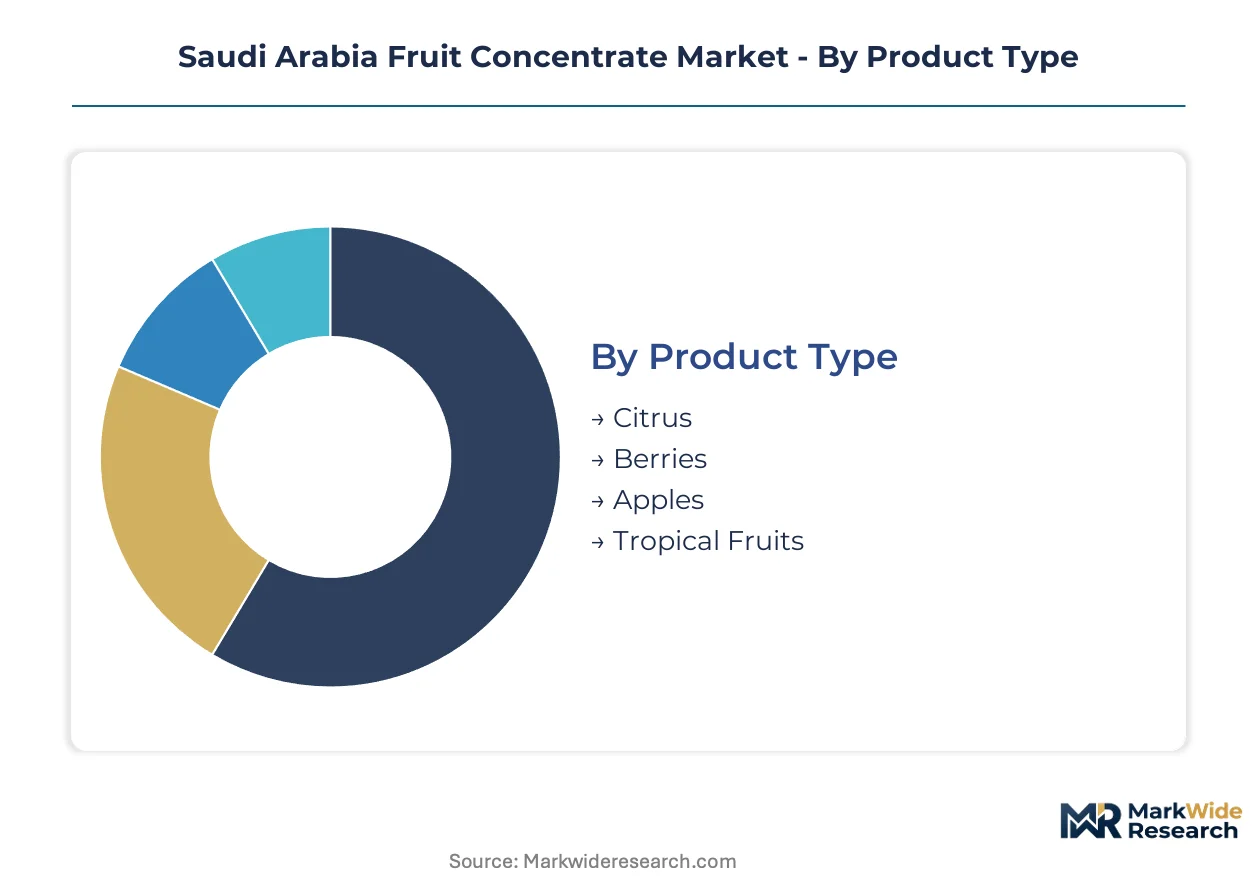
Segmentation in the Saudi Arabia fruit concentrate market reveals how procurement priorities diverge across buyer types. Beverage manufacturers prioritize Brix consistency and cold-press credentials, while dairy processors emphasize color stability and low heat damage for premium positioning.
Product Type:
Buyers differentiate by thermal processing tolerance and flavor volatility requirements, with heat-sensitive applications commanding premium extraction methods.
- Citrus:Orange and lemon concentrates deliver standardized acidity and soluble solids between 65-72 degrees Brix for juice reconstitution. Central Region beverage clusters in Riyadh anchor procurement volumes, though margin pressure intensifies from commoditized global supply.
- Tropical Fruits:Mango and passionfruit extracts undergo membrane filtration to preserve volatile aromatics lost in conventional evaporation. Premium beverage lines in Jeddah are displacing traditional orange formulations with these extracts.
- Berries:Specialized concentrates target dairy and confectionery accounts requiring color fidelity.
- Apples:Neutral flavor profiles serve as blending bases across multiple applications.
Citrus leads volumes today; tropical fruits are gaining share fastest.
End User:
Application-specific formulation requirements determine concentrate specification, with thermal stability and acidity tolerance varying sharply across downstream categories.
- Beverages:Ready-to-drink manufacturers demand consistent Brix levels for dilution economics and shelf-life predictability. Central Region production clusters drive national offtake, with SFDA additive standards pushing processors toward cleaner-label sourcing.
- Dairy:Yogurt and flavored milk operations require concentrates with minimal heat damage to preserve aromatic integrity. Cold-pressed berry and tropical grades command price premiums in this segment.
- Confectionery:Color intensity and sugar-acid balance prioritize specific fruit varieties.
- Bakery:Heat-stable concentrates withstand oven temperatures without flavor degradation.
Beverages lead volumes today; dairy is climbing the fastest.
Packaging Type:
Logistics economics and shelf-life requirements shape format selection, with ambient stability commanding structural preference in institutional channels.
- Tetra Packs:Aseptic brick packaging delivers ambient stability and lower logistics cost per liter of reconstituted juice. Institutional buyers across Riyadh and Jeddah favor this format for inventory efficiency.
- Bottles:Transparent PET and glass formats support retail visibility and premium positioning.
- Cans:Metal packaging suits single-serve beverage applications requiring durability.
- Pouches:Flexible formats reduce material cost for bulk institutional shipments.
Tetra Packs lead volumes today; pouches show steepest expansion trajectory.
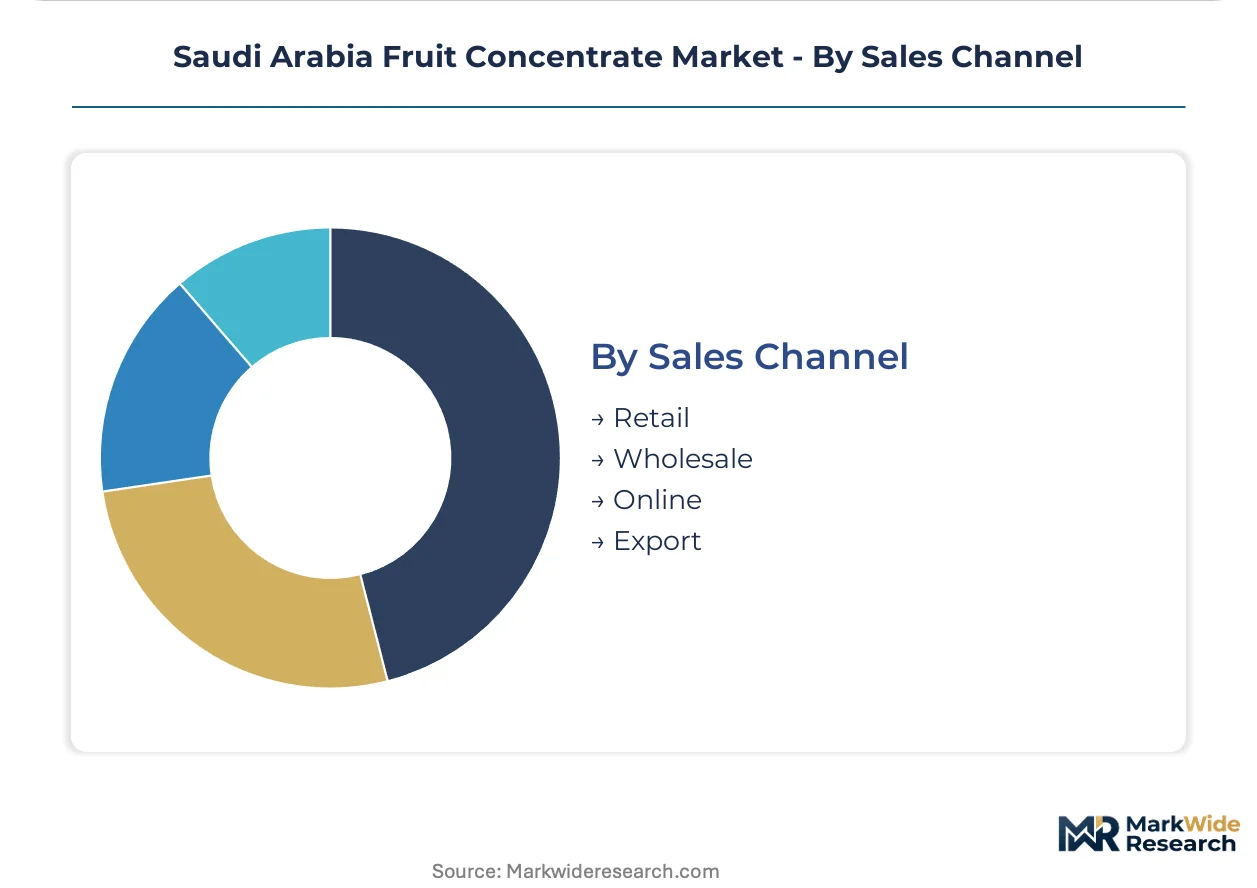
Sales Channel:
Certification requirements and relationship structures concentrate volume flows toward direct manufacturer ties and away from spot market intermediation.
- Wholesale:Direct annual volume contracts between concentrate suppliers and integrated beverage operations dominate national offtake. Large Riyadh processors negotiate terms that compress spot market liquidity.
- Retail:SASO Saudi Quality Mark certification has become a de facto requirement for supermarket listings, forcing smaller traders toward compliant suppliers.
- Online:E-commerce penetration remains limited by bulk logistics constraints.
- Export:Re-export activity to Gulf neighbors leverages Saudi distribution infrastructure.
Wholesale leads volumes today; retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized food technologists and quality assurance specialists cluster around Riyadh and Jeddah, anchoring the Kingdom's concentrate processing capabilities. These technical workforces concentrate in Central Region dairy and beverage manufacturing hubs. Their expertise underpins compliance with SFDA protocols and SASO certification requirements.
Riyadh
Beverage reconstitution demand and dairy processing expansion drive concentrate procurement volumes. SFDA pesticide residue limits and batch-level testing documentation requirements elevate compliance costs for new entrants. The Central Region production cluster anchors national offtake, with integrated beverage operations negotiating direct annual contracts that compress spot market liquidity.
Jeddah
Ready-to-drink formulation demand from Western Region distribution networks pulls tropical and berry concentrates for premium positioning. The Saudi Quality Mark certification has become a de facto requirement for supermarket listings, forcing smaller traders toward compliant suppliers. Cold-pressed extraction adoption is overtaking conventional methods in high-value applications.
Eastern Province
Underpenetrated food processing clusters in Dammam offer white-space for concentrate distribution expansion. MOF customs valuation rules for concentrate shipments elevate landed costs versus regional competitors. Institutional buyers favor Tetra Pack formats for inventory efficiency across ambient-stable supply chains.
NEOM Northwest
Planned food security investments and domestic fruit processing infrastructure aim to reduce import dependency ratios. Water scarcity constraints limit backward integration into local raw material sourcing for concentrate production. The zone targets laboratory-equipped processors with traceable supply chains as anchor tenants.
Saudi Arabia Fruit Concentrate Market Competitive Landscape
Top-tier vendors anchor integrated beverage and dairy operations, while commodity traders and smaller importers face margin compression from certification mandates. The supplier base stratifies between global procurement networks securing cost-advantaged citrus streams and specialized processors targeting premium berry and tropical grades. Three archetypes dominate: multinational ingredient suppliers with certified laboratories, regional dairy integrators with captive demand, and specialized concentrate traders pivoting toward compliance. Consolidation accelerates through direct manufacturer contracts and laboratory certification investments.
Within the multinational ingredient tier, Archer Daniels Midland Company and AGRANA Beteiligungs-AG exemplify divergent sourcing strategies. Dohler Group occupies a position bridging commodity and specialized concentrate supply. Almarai Company anchors the downstream pull as an integrated dairy and beverage operator converting concentrates across captive production lines. These four entities represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| AGRANA Beteiligungs-AG |
| Dohler Group |
| Kerry Group |
| Symrise AG |
| Almarai Company |
| Rubicon Arabia |
| Alsafi Danone |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
A widening performance gap between membrane-filtered cold-press grades and commodity heat-processed concentrates manifests in divergent pricing power and supply chain configurations across the Kingdom. SFDA batch-testing mandates and SASO certification ladders compress margins for traders without laboratory infrastructure while rewarding certified processors with pricing premiums and direct manufacturer relationships.
Pricing Analysis
Commodity spot contracts versus annual volume offtake agreements split the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and extraction method differentiation. Cost compression in heat-processed citrus grades is intensifying because standardized global supply floods institutional channels. Beverage manufacturers in Riyadh show lowest price sensitivity for cold-pressed tropical concentrates, while commodity traders face highest sensitivity to customs valuation adjustments.
Supply Chain Analysis
Imported fruit pulp supply rests on Brazilian orange processors, Indian mango concentrate specialists, and European berry extraction facilities. Raw material flows draw from citrus orchards in São Paulo state, Alphonso mango belts in Maharashtra, and Polish strawberry cultivation regions. Single-source vulnerability concentrates in Brazilian orange concentrate supply during Southern Hemisphere harvest windows. Distribution runs through Jeddah port customs clearance and Central Region cold-chain logistics toward Riyadh beverage clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia fruit concentrate market reads as a late-cycle quality story where dairy and beverage procurement is shifting toward cold-pressed specifications with certified traceability documentation.
For Market Incumbents: Acquire laboratory certification assets to defend against SFDA registration timeline extensions that favor in-house testing capabilities. Secure backward integration into membrane filtration equipment to preserve margin position as heat-processed grades commoditize further. Channel control through direct annual contracts with Central Region dairy operations locks out spot-market competitors. For New Entrants and Emerging Players: SASO Saudi Quality Mark acceleration in retail channels opens a window for compliant suppliers to capture supermarket listings as smaller traders exit. Eastern Province food processing clusters in Dammam offer the most penetrable geography with underdeveloped concentrate distribution infrastructure. A go-to-market angle emphasizing tropical concentrate diversification for premium beverage lines bypasses entrenched orange concentrate incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with laboratory-equipped processors possessing traceable supply chains and existing SFDA compliance documentation. Long-term viability centers on five-to-ten year positioning around domestic fruit processing investments as NEOM food security infrastructure matures. The signal to watch is MOF customs valuation rule adjustments that would reshape landed cost economics for regional competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Cold-press extraction preserves volatile aromatics that SFDA-compliant premium beverage lines now require. |
| SASO Certification Investment | Saudi Quality Mark becomes de facto retail channel entry requirement, forcing competitor exit. |
| Tropical Concentrate Sourcing Agreements | Mango and passionfruit supply contracts displace orange in Jeddah premium formulation demand. |
| Eastern Province Distribution Buildout | Dammam cluster penetration captures white-space institutional buyers favoring Tetra Pack formats. |
| Laboratory Infrastructure Development | In-house SFDA testing capability compresses product registration cycles versus outsourced alternatives. |
Research Methodology
Direct dialogue with beverage procurement directors, dairy operations managers, SFDA compliance officers, and cold-chain logistics providers grounded qualitative findings in operational reality. Secondary validation drew from SASO certification registries, SFDA pesticide residue bulletins, MOF customs valuation rulings, and Central Region industrial cluster development reports. Bottom-up concentrate volume estimates triangulated against top-down beverage production capacity assessments across the analysis window.
Segment-level projections across citrus, tropical, berry, and apple concentrate categories combined with end-use splits in beverages, dairy, confectionery, and bakery applications. CAGRs emerged from regression analysis against historical procurement patterns and forward-looking capacity announcements. Forecast inputs incorporated SFDA enforcement intensity trajectories and NEOM food security infrastructure development timelines.
Revisions become necessary when SFDA maximum residue limit adjustments, MOF customs valuation rule changes, or domestic fruit cultivation breakthroughs materialize outside modeled parameters. A small set of regulatory and infrastructure triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Dried Red Jujube Market