
 Europe Green Tea Market | 2026-2036
Europe Green Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Tea Market Analytics
Specialty retail channels across Europe is reshaping how green tea reaches consumers, with premium positioning now dominating high-street placement. Unilever leverages its multinational logistics network to secure shelf space in continental supermarkets. Finlays Beverages anchors its supply through direct estate partnerships in Kenya and Sri Lanka. Teekanne differentiates via heritage branding and localized flavor portfolios for German-speaking markets.
Green tea comprises minimally oxidized leaves from Camellia sinensis, typically processed through steaming or pan-firing to preserve polyphenol content and deliver antioxidant functionality for beverage and nutraceutical applications. Loose leaf commands the highest margin pools among product type segments, while ready-to-drink formats capture the fastest volume growth in convenience-oriented channels. Organic grade certification now functions as a price floor rather than a premium tier across Northern European markets.
EFSA standards govern health claim substantiation on green tea packaging, while EU Green Deal agricultural protocols constrain pesticide residues in imported leaf. REACH compliance affects extraction processes for concentrated formulations. Stakeholders must monitor evolving ECHA substance evaluations for novel bioactive compounds and align sourcing strategies with tightening residue thresholds before regulatory windows close.
Market Dynamics
EU Green Deal agricultural protocols are compressing permissible pesticide thresholds on imported leaf, forcing estate-level sourcing reconfiguration across Northern European distribution networks. Specialty retail channels in Germany and France now demand residue documentation that exceeds baseline import standards.
Growth Catalysts
- REACH compliance mandates:Concentrated extract formulations face tightened substance evaluation windows under ECHA protocols, advantaging early-adopter processors with pre-validated supply chains.
- Functional beverage demand:Health-conscious millennials in German metropolitan clusters are substituting conventional soft drinks with polyphenol-forward ready-to-drink formats.
- Organic certification normalization:Northern European retail buyers now treat organic grade as a non-negotiable baseline, expanding contract volumes for certified estate operations in Kenya and Sri Lanka.
Market Restraints
- Input cost volatility:Kenyan and Sri Lankan estate labor costs and energy-intensive withering processes create margin pressure on medium-grade leaf processors.
- Supply concentration risk:Premium loose-leaf sourcing depends on a narrow band of high-altitude estates in Nuwara Eliya and Kericho, exposing buyers to climate-induced harvest variability.
- Regulatory friction:EFSA health claim substantiation requirements block antioxidant messaging on packaging unless clinical trial thresholds are met, constraining marketing differentiation.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania lack specialty tea retail infrastructure, creating first-mover positioning for direct-to-consumer subscription models.
- Cold-brew extraction convergence:Nitrogen flushing combined with low-temperature steeping protocols enables flavor stability in ambient distribution, unlocking convenience-channel placement.
- EU Green Deal tailwinds:Carbon border adjustment mechanisms will penalize non-compliant Asian leaf imports, advantaging African estate partnerships with verified emission profiles.
Industry Challenges
- Specialized procurement talent scarcity:Buyers fluent in both estate agronomy and REACH documentation are concentrated in London and Hamburg, creating hiring bottlenecks for expanding distributors.
- Dual certification timelines:Simultaneous organic and Fairtrade accreditation requires 18-24 month audit cycles, delaying new product launches for reformulated blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Tea Market |
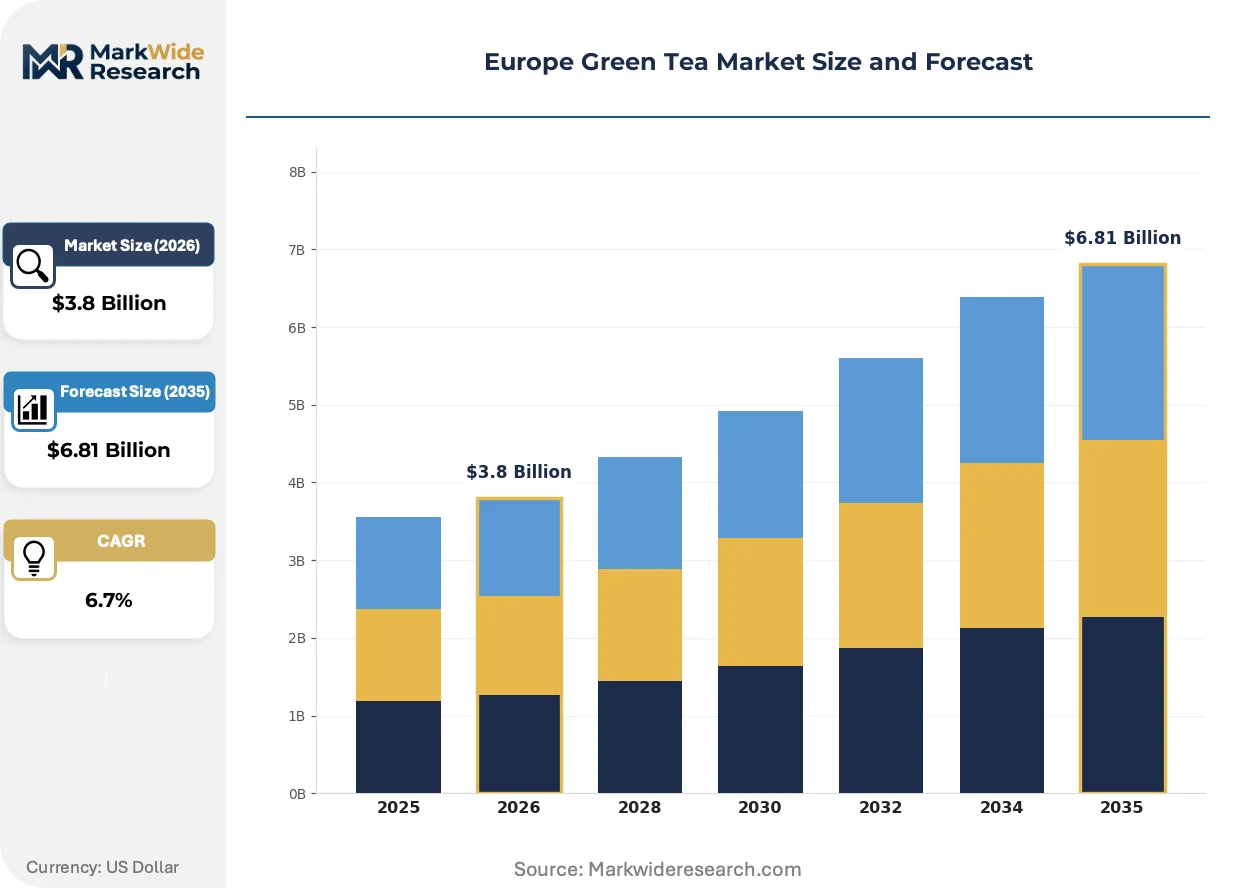
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Bagged Tea, Instant Powder, Ready-to-Drink Grade: Premium, Organic, Conventional, Standard Packaging Type: Box, Pouch, Tin, Bottle Distribution Channel: Retail Stores, Online, Supermarkets, Specialty Shops |
| Companies Covered | Associated British Foods, Unilever, Amore Pacific Corp, Arizona Beverage Company, Cape Natural Tea Products, Celestial Seasonings, Finlays Beverages, Teekanne, Bettys & Taylors of Harrogate, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Tea Market Evolving Landscape
Processing technology and regulatory compliance are converging to reshape how green tea moves from estate to European consumer. Three developments are compressing legacy operational models.
Nitrogen-flushed cold-brew extraction systems are rendering obsolete traditional hot-extraction methods for ready-to-drink formulations. German beverage co-packers are adopting these systems at scale to preserve catechin stability through ambient shelf-life windows. The structural consequence is a compression of flavor differentiation timelines, as extraction consistency becomes table stakes rather than premium positioning.
EFSA's evolving health claim substantiation framework is tightening evidentiary requirements for antioxidant messaging on packaged goods. Processors must now commission human intervention studies to retain functional positioning, diverting R&D budgets from flavor innovation toward clinical validation. Ready-to-drink brands targeting German pharmacy channels face the steepest compliance ramps.
Specialty retail buyers are consolidating procurement authority into centralized sustainability offices, displacing decentralized category-manager purchasing. French and German organic supermarket chains now mandate estate-level carbon accounting as a contract precondition. This behavioral shift is most visible in Hamburg and Munich, where buyer teams audit Kenyan supplier emission profiles before finalizing seasonal contracts.
Europe Green Tea Market Segmentation
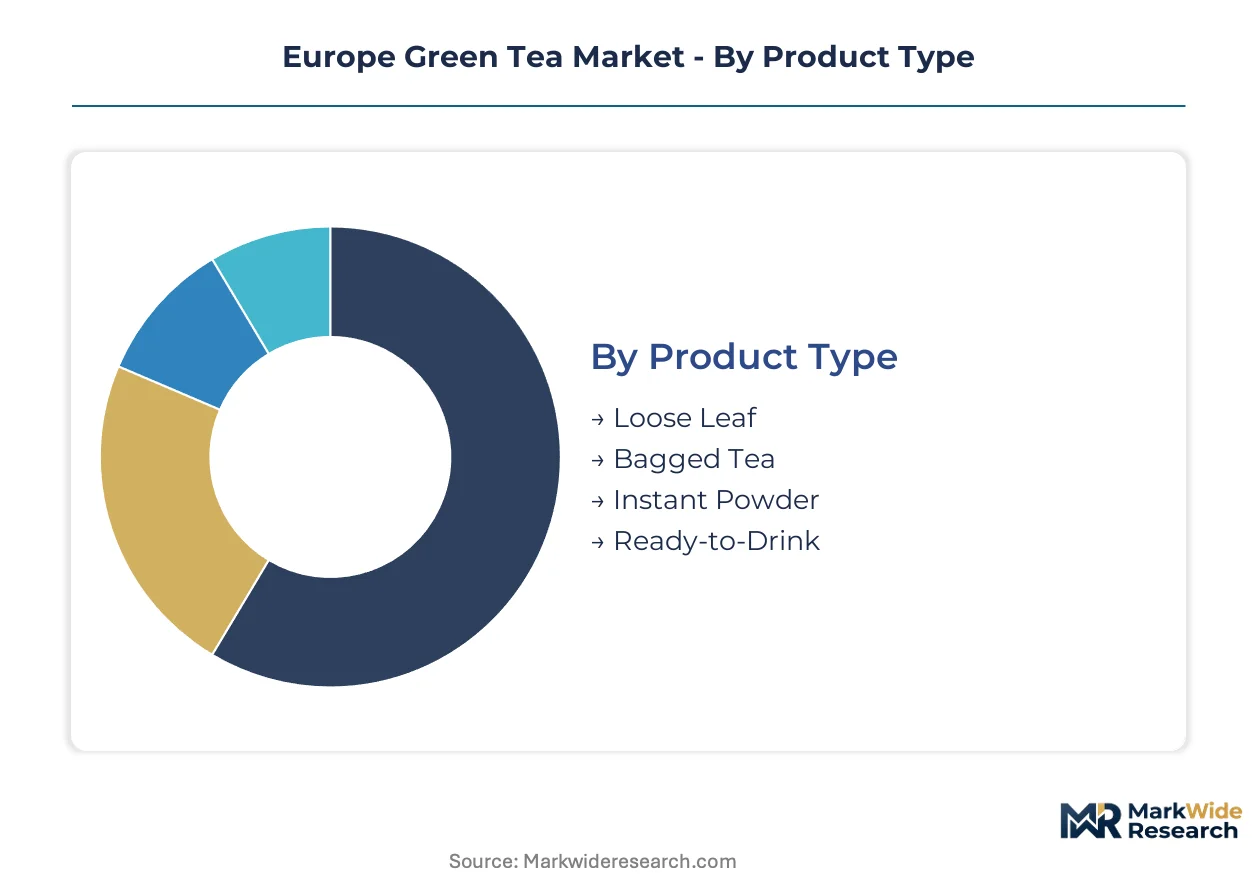
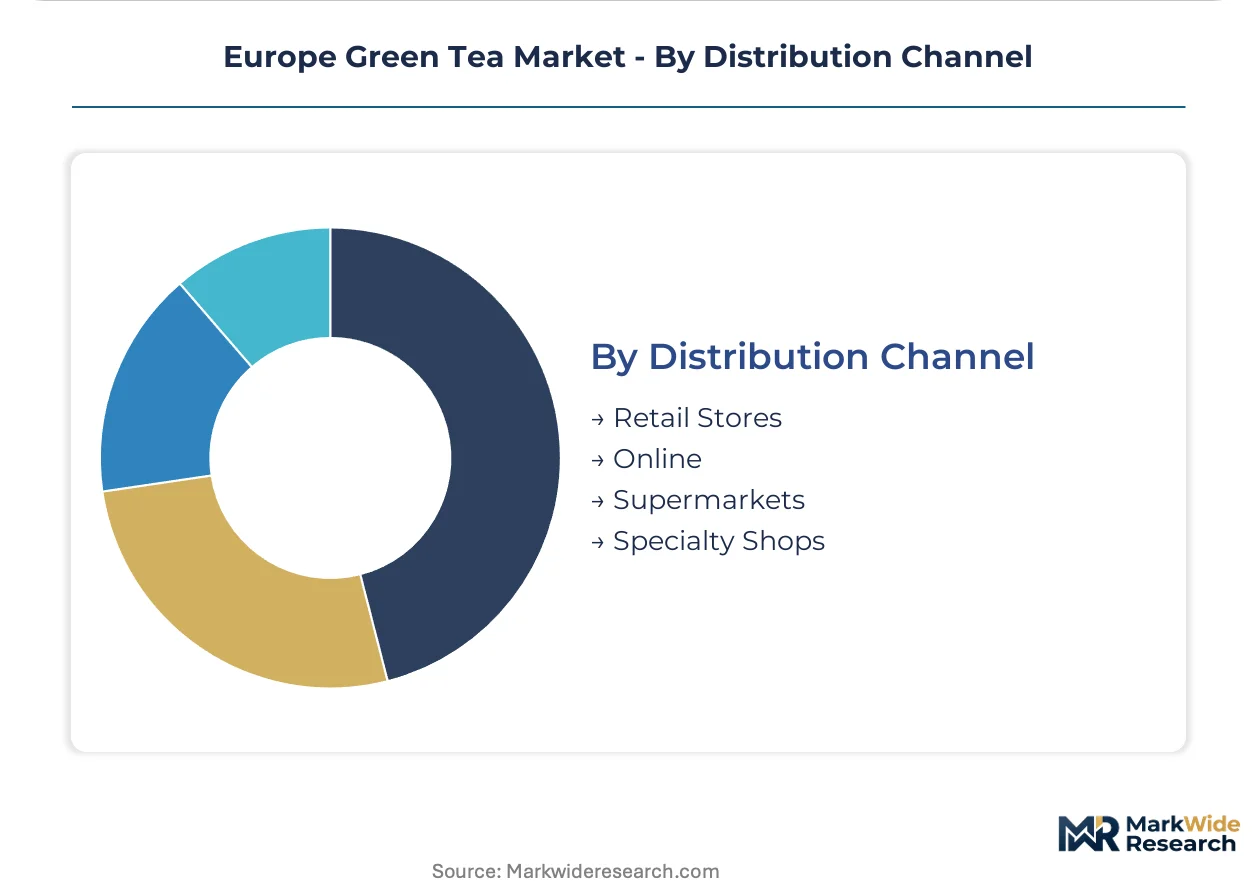
Green tea segmentation across Europe reflects divergent margin structures and channel access patterns. Procurement priorities differ sharply between German organic supermarkets and French pharmacy networks, forcing suppliers to configure separate product-service bundles for each tier.
Product Type:
Cost tier differentiation separates artisan positioning from convenience capture across European retail shelves.
- Loose Leaf:Whole leaves retain maximum catechin integrity through minimal mechanical processing. German specialty tea shops in Hamburg and Munich concentrate procurement here, driven by consumer willingness to pay for ceremonial preparation rituals and origin transparency.
- Ready-to-Drink:Nitrogen-flushed cold-brew formulations preserve polyphenol stability through ambient distribution. French metropolitan millennials are substituting these for conventional soft drinks in Paris and Lyon convenience channels, compressing the premium-accessibility gap.
- Bagged Tea:Standardized cut-leaf portions dominate volume in British and Irish retail, where brewing convenience outweighs origin specificity for daily consumption occasions.
- Instant Powder:Spray-dried extracts serve functional beverage manufacturers and nutraceutical blenders seeking formulation flexibility in Dutch and Belgian processing hubs.
Loose leaf commands the established base. The steepest expansion runs through ready-to-drink.
Grade:
Certification tier now functions as a market-access gate rather than a price-premium mechanism in Northern European sourcing.
- Organic:EU Green Deal residue thresholds and ECHA substance evaluations have normalized organic certification as a contractual baseline. German retail buyers treat this grade as non-negotiable for shelf placement, expanding contract volumes for certified Kenyan and Sri Lankan estates.
- Premium:Single-origin designations from Nuwara Eliya high-altitude estates command ceremonial and gift-channel positioning. French specialty distributors concentrate procurement here for Parisian tea salon networks, constrained by narrow harvest windows and climate variability.
- Conventional:Utility-grade leaf serves price-sensitive foodservice and industrial extraction applications across Eastern European markets where certification premiums face absorption resistance.
- Standard:Mid-tier blending material balances cost and basic quality assurance for private-label supermarket ranges in Spain and Italy.
Premium grade anchors the high-margin core. Organic certification is climbing the fastest as a market-entry requirement.
Packaging Type:
Format selection signals channel strategy and consumer usage occasion across European retail environments.
- Tin:Airtight metal caddies preserve aromatic volatile compounds for premium loose-leaf distribution. German heritage retailers and French gourmet chains deploy this format for counter positioning and gift-market capture.
- Pouch:Flexible laminated films with nitrogen flushing dominate bagged tea volume in UK and Irish supermarkets, optimizing shelf space efficiency and transport cube utilization.
- Box:Paperboard secondary packaging supports brand billboard effects and multi-SKU bundling for retail promotional cycles across Benelux markets.
- Bottle:PET and glass formats enable ready-to-drink placement in German convenience and pharmacy channels where consumption immediacy drives purchase decisions.
Tin packaging secures the premium positioning anchor. Pouch formats are expanding most quickly through mass-market penetration.
Distribution Channel:
Channel concentration determines margin capture and consumer relationship depth for European green tea suppliers.
- Specialty Shops:Curated assortments with estate-level provenance documentation dominate high-value customer acquisition. German independent tea retailers in Berlin and Cologne concentrate here, leveraging staff expertise to justify price premiums and drive repeat purchase loyalty.
- Supermarkets:Centralized category management and sustainability audit requirements define access to German and French organic chains. Buyers in Hamburg and Munich now mandate carbon accounting documentation as a contract precondition, displacing decentralized procurement authority.
- Online:Direct-to-consumer subscription models bypass retail margin capture, particularly effective in underpenetrated Polish and Romanian markets lacking specialty tea infrastructure.
- Retail Stores:General merchandise and pharmacy networks capture functional positioning demand through EFSA-compliant health claim placement in German drugstore chains.
Specialty shops retain the relationship-intensive core. Supermarket channels are gaining share fastest through sustainability-driven procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary entry point for African and Asian leaf shipments into European distribution networks.
Germany
Specialty tea shops in Hamburg and Munich drive demand for ceremonial-grade loose leaf with full provenance documentation. EFSA health claim substantiation requirements constrain antioxidant messaging on packaged goods. Berlin-based organic supermarket chains now mandate estate-level carbon accounting as a contractual precondition for shelf placement.
France
Parisian tea salon networks concentrate procurement of single-origin Nuwara Eliya designations for gift-channel positioning. EU Green Deal agricultural protocols compress permissible pesticide thresholds on imported leaf. Lyon metropolitan millennials substitute nitrogen-flushed cold-brew formats for conventional soft drinks in convenience channels.
United Kingdom
Bagged tea dominates volume in British and Irish retail where brewing convenience outweighs origin specificity. REACH compliance mandates affect concentrated extract formulations for nutraceutical applications. London and Harrogate anchor heritage blending operations with established procurement relationships in Kenyan highland estates.
Netherlands
Dutch processing hubs demand spray-dried instant powders for functional beverage manufacturers seeking formulation flexibility. ECHA substance evaluation windows tighten for novel bioactive compounds. Rotterdam's logistics infrastructure enables re-export distribution into underpenetrated Polish and Romanian markets.
Poland
Warsaw and Krakow lack specialty tea retail infrastructure, creating first-mover positioning for direct-to-consumer subscription models. Organic certification normalization proceeds slower than in Northern European markets. Polish buyers absorb utility-grade leaf for price-sensitive foodservice applications without residue documentation requirements.
Europe Green Tea Market Competitive Landscape
On the supply side, the industry is tiered between multinational beverage conglomerates with integrated logistics networks and heritage specialists with localized flavor portfolios. Strategic archetypes include estate-integrated processors with direct African partnerships, heritage brands leveraging regional identity, and ready-to-drink format innovators capturing convenience-channel placement. Dominant competitive moves center on sustainability audit prequalification for supermarket procurement and cold-brew extraction technology licensing.
Among UK-based diversified food groups, Associated British Foods occupies a position exemplifying scale-driven procurement consolidation. Unilever represents the multinational logistics archetype with continental supermarket shelf access. Within the heritage specialist tier, Teekanne anchors German-speaking market positioning through localized portfolio development. These three entities illustrate the competitive tension between volume efficiency and regional identity capture.
| Leading Market Players |
|---|
| Associated British Foods |
| Unilever |
| Amore Pacific Corp |
| Arizona Beverage Company |
| Cape Natural Tea Products |
| Celestial Seasonings |
| Finlays Beverages |
| Teekanne |
| Bettys & Taylors of Harrogate |
| Others |
Value Network & Pricing Analysis
Kenyan highland estates around Kericho anchor European green tea supply, with their harvest volumes and labor cost trajectories transmitting directly into German supermarket procurement negotiations. Buyers in Hamburg and Munich translate estate-level production constraints into contract price floors, while carbon accounting mandates under EU Green Deal protocols add compliance premiums that compress margin pools for non-certified operators.
Pricing Analysis
Volume-discount tiering structures separate ceremonial-grade loose leaf from commodity bagged formats across European retail channels. Three-tier pricing stratifies across premium single-origin, standard certified organic, and economy conventional grades, with certification level and origin transparency driving the widest spreads. Pricing pressure intensifies in the mid-tier as Kenyan labor costs escalate and energy-intensive withering processes squeeze processor margins. Foodservice buyers in Poland and Romania exhibit highest price sensitivity, while German specialty tea shops absorb premiums for provenance documentation.
Supply Chain Analysis
EU Green Deal agricultural protocols function as export-control mechanisms on residue thresholds, constraining leaf flows from non-compliant Asian origins into Northern European distribution networks. Supply concentrates in Kenya and Sri Lanka, with Nuwara Eliya high-altitude estates and Kericho highlands anchoring premium loose-leaf sourcing. Raw material dependencies include estate labor pools, nitrogen flushing equipment for cold-brew extraction, and laminated film packaging substrates. Single-source vulnerability runs through the narrow band of certified estates meeting German carbon accounting mandates. Distribution runs through Rotterdam and Hamburg port infrastructure into supermarket and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement teams fluent in both estate agronomy and REACH documentation are concentrated in London and Hamburg, creating hiring bottlenecks that constrain expansion timelines for distributors seeking supermarket shelf placement.
For Market Incumbents: Harden estate partnerships through backward integration into Kenyan certified operations, securing volume commitments before carbon border adjustment mechanisms penalize Asian leaf imports. Lock in multi-year contracts with Nuwara Eliya high-altitude estates to defend against climate-induced harvest variability that threatens ceremonial-grade supply. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian direct-to-consumer subscription channels, where specialty tea retail infrastructure remains underdeveloped and digital-native millennials bypass traditional distribution. Lead with nitrogen-flushed cold-brew ready-to-drink formats that align with convenience-channel substitution trends in Warsaw metropolitan clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription operators with proprietary estate relationships and validated carbon accounting documentation. Target acquisition archetypes include Kenyan estate-integrated processors with pre-certified supply chains and German beverage co-packers with cold-brew extraction licensing. Watch for EFSA health claim substantiation rulings as inflection indicators that would revalue functional positioning premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Estate-Level Carbon Certification | EU Green Deal compliance secures German supermarket contract prequalification ahead of border adjustments. |
| Cold-Brew Extraction Licensing | Nitrogen flushing technology enables ambient distribution placement in French pharmacy and convenience channels. |
| Direct-to-Consumer Subscription Launch | Digital bypass captures Polish and Romanian demand absent specialty retail infrastructure. |
| Heritage Brand Portfolio Extension | Localized flavor development defends German-speaking market positioning against multinational entrants. |
| REACH-Compliant Extract Formulation | ECHA pre-validation opens concentrated nutraceutical supply to Dutch and Belgian processing hubs. |
Research Methodology
A spread of perspectives from estate operations managers, German supermarket sustainability officers, French pharmacy channel buyers, Dutch beverage formulators, and Kenyan export coordinators converged on the working assumptions driving supply and demand calibration. Primary fieldwork combined with secondary validation drew from EU Green Deal implementation documents, EFSA health claim registers, ECHA substance evaluation databases, and customs trade flows through Rotterdam and Hamburg. Bottom-up estate production estimates triangulated against top-down retail channel absorption data.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, certification grade, packaging format, and distribution channel dimensions plus estate altitude and processing method as tea-specific variables. CAGRs derived from trend extrapolation of organic certification adoption rates, cold-brew format penetration curves, and supermarket sustainability audit expansion timelines. Forecast inputs incorporated climate variability indices for Nuwara Eliya harvest windows and EU regulatory implementation phasing.
Sensitivities concentrate around EFSA evidentiary requirement tightening, carbon border adjustment mechanism enforcement timing, and Kenyan estate labor cost trajectories. Forecasts reflect documented assumptions on certification adoption curves and channel shift velocities. Material shifts in EU Green Deal agricultural protocol stringency or ECHA substance evaluation windows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Essence Market
Tea
North America Ready-To-Drink Tea Market
Tea
Tea Concentrate Market
Tea
APAC RTD Tea Market
Tea
Single Origin Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Organic Tea Market
Tea
Rooibos Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Ready-To-Drink (RTD) Tea Market
Tea
New Style Tea Drink Market
Tea
Fermented Tea Market
Tea
Tea Subscription Market
Tea
Asia-Pacific Green Tea Market
Tea
Natural Tea Extract Market
Tea
South America Tea Market