
 Camellia Sinensis Leaf Extract Market | 2026-2036
Camellia Sinensis Leaf Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Camellia Sinensis Leaf Extract Market Outlook
Ingredient standardization revenue is rewriting margin economics across the supply base. Givaudan leverages captive botanical sourcing networks to secure consistent catechin profiles for flavor and fragrance applications. Kemin Industries anchors its position through R&D intensity in antioxidant stabilization technologies for food preservation. Taiyo Kagaku specializes in sunphenon-grade green tea extract manufacturing, dominating pharmaceutical-grade supply channels in Japan.
Camellia sinensis leaf extract comprises bioactive polyphenols—principally epigallocatechin gallate (EGCG), epicatechin, and theaflavins—typically standardized to 50-98% total polyphenols through solvent or supercritical CO2 extraction for use as functional ingredients in health products and cosmetic formulations. Powder and liquid extract forms carry the bulk of industrial volume, with powder formats preferred for tablet compression and dry-blend functional foods while liquid extracts serve beverage fortification and cosmetic serum applications. Green tea extract leads product type demand due to established EGCG research, though oolong tea extract is gaining traction in beauty product formulations targeting skin barrier function claims.
EFSA maintains strict botanical health claim evaluation protocols that determine which polyphenol-based claims gain EU market authorization, directly shaping product development pipelines for European-bound extracts. The FDA's New Dietary Ingredient notification requirements and FTC substantiation standards govern US nutraceutical entry, while China's NMPA and SAMR enforce GB standards for food-grade botanical extracts. Stakeholders must monitor evolving Novel Food consultations in Europe and pending NMPA classification updates for concentrated tea polyphenols, as these determinations will redraw permissible application boundaries and compliance investment requirements.
Market Dynamics
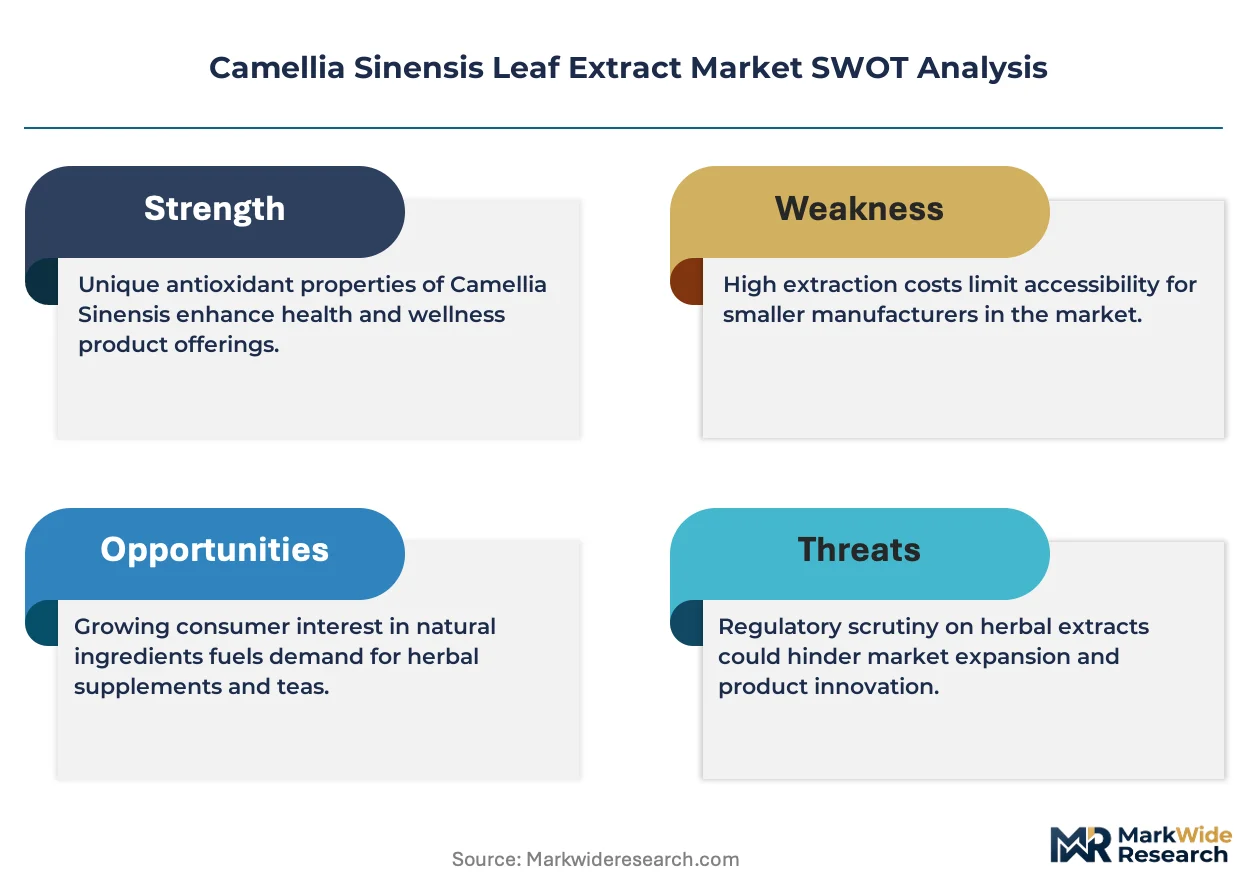
Ingredient standardization is compressing margin structures across the Camellia sinensis leaf extract supply base, forcing processors to invest in captive sourcing networks and pharmaceutical-grade certification to defend pricing power against commoditized polyphenol suppliers.
Growth Catalysts
- EFSA Novel Food authorization:Approved health claims for cardiovascular and cognitive function are opening premium capsule formulations to EU nutraceutical brands, accelerating demand for 95%+ standardized EGCG extracts.
- China's dual carbon goals:SAMR incentives for low-carbon extraction technologies are redirecting capital toward supercritical CO2 systems, upgrading domestic processing capacity for export-grade botanicals.
- Beauty product formulators:Skin barrier function claims utilizing oolong tea theaflavins are displacing synthetic ceramides in K-beauty and Western prestige skincare lines.
Market Restraints
- Camellia sinensis leaf input volatility:Climate-induced harvest fluctuations in Fujian and Zhejiang provinces are compressing processor margins during low-yield cycles.
- EFSA health claim rejection backlog:Pending botanical evaluations are freezing product launch timelines for European-bound extracts awaiting substantiation rulings.
- Synthetic polyphenol substitution:Fermentation-derived EGCG from precision biotechnology platforms is eroding price premiums for agricultural extracts in cost-sensitive supplement segments.
Strategic Opportunities
- Japan's functional food channel:FOSHU approval pathways for tea catechin beverages remain underutilized by Western extractors seeking premium positioning in East Asian markets.
- Supercritical CO2-green solvent hybrid systems:Converging extraction technologies are enabling pharmaceutical-grade purity at nutraceutical cost structures, opening veterinary and infant nutrition applications.
- Direct-to-brand supply contracts:Bypassing trader intermediaries through long-term offtake agreements with finished goods manufacturers is capturing margin currently lost to spot market volatility.
Industry Challenges
- Phytochemical analytical talent scarcity:Qualified chromatography specialists for catechin profiling and stability testing command premium compensation, constraining mid-scale processor expansion.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of USP, EP, and JP monograph compliance is extending product qualification timelines and diverting R&D resources from innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camellia Sinensis Leaf Extract Market |
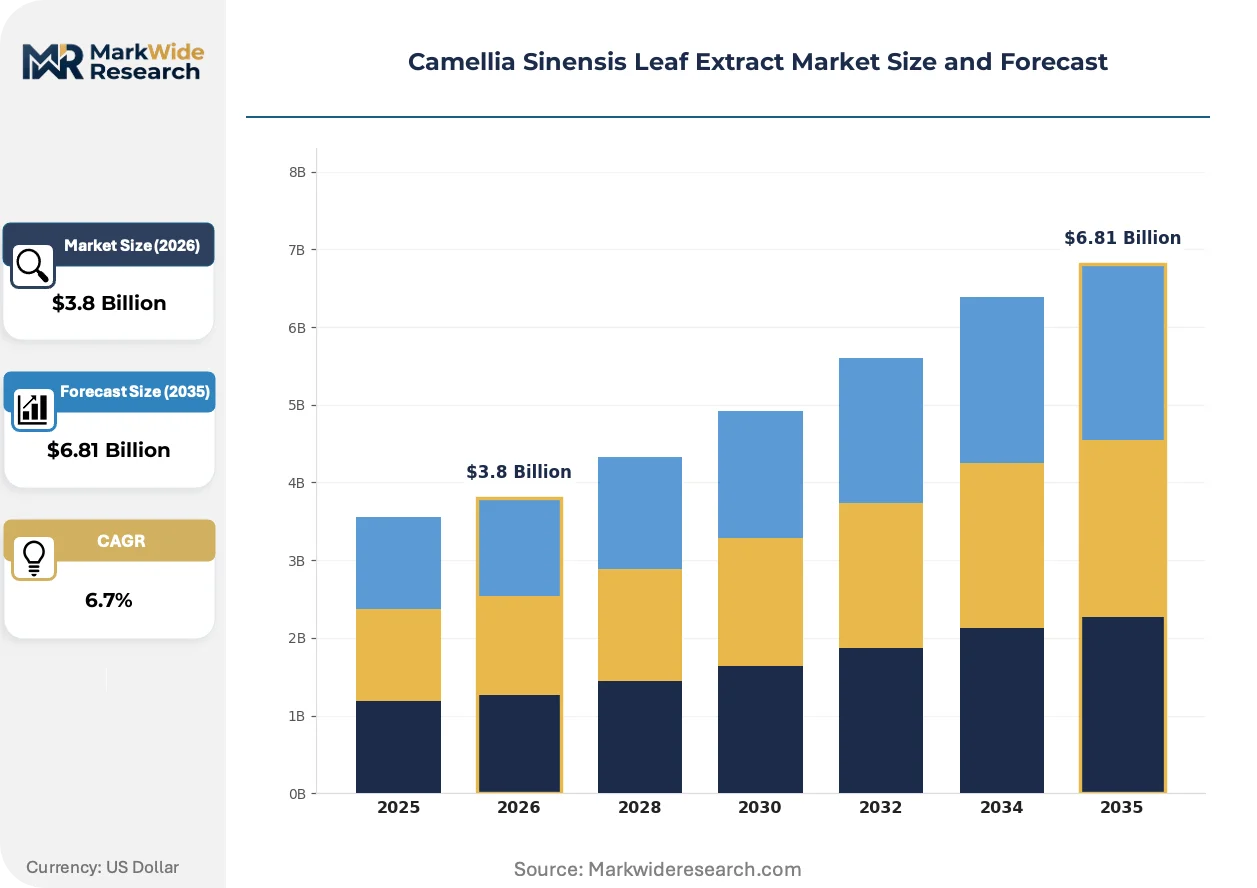
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, White Tea, Oolong Tea End User: Food & Beverage Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Form: Powder, Liquid Extract, Capsules, Tea Bags Application: Health Supplements, Beauty Products, Functional Foods, Beverages |
| Companies Covered | Archer-Daniels-Midland Company (ADM), Givaudan, Synthite Industries Ltd, International Flavors & Fragrances Inc., Finlays, Kemin Industries, Indena S.p.A., Taiyo Kagaku, AVT Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camellia Sinensis Leaf Extract Market Strategic Shifts
Extraction technology convergence and regulatory claim substantiation are restructuring competitive advantage around provenance verification and bioactive consistency rather than commodity volume scale.
Supercritical CO2 extraction is migrating from niche pharmaceutical applications toward mainstream nutraceutical manufacturing as equipment costs decline and throughput scales. Mid-tier processors in India and China are adopting semi-continuous systems previously confined to European botanical houses. This technology migration is compressing solvent residue compliance costs while enabling heat-sensitive catechin preservation that ethanol extraction degrades.
REACH registration requirements for botanical substances are tightening impurity disclosure thresholds for tea extracts entering EU cosmetic and food contact applications. ECHA's updated guidance on botanical complex substances is forcing reformulators to document pesticide and heavy metal profiles across supply tiers. Fragrance and personal care brands are responding by consolidating supplier bases to auditable farm-level traceability systems.
Beauty brands are unbundling serum manufacturing from in-house R&D, outsourcing polyphenol stabilization and emulsion compatibility testing to specialized extractors with formulation laboratories. This service-layer expansion is displacing traditional ingredient-only supply relationships in North American and European premium skincare channels. South Korean contract manufacturers are leading this behavioral shift, demanding turnkey active delivery systems rather than raw extract powders.
Camellia Sinensis Leaf Extract Market Segmentation
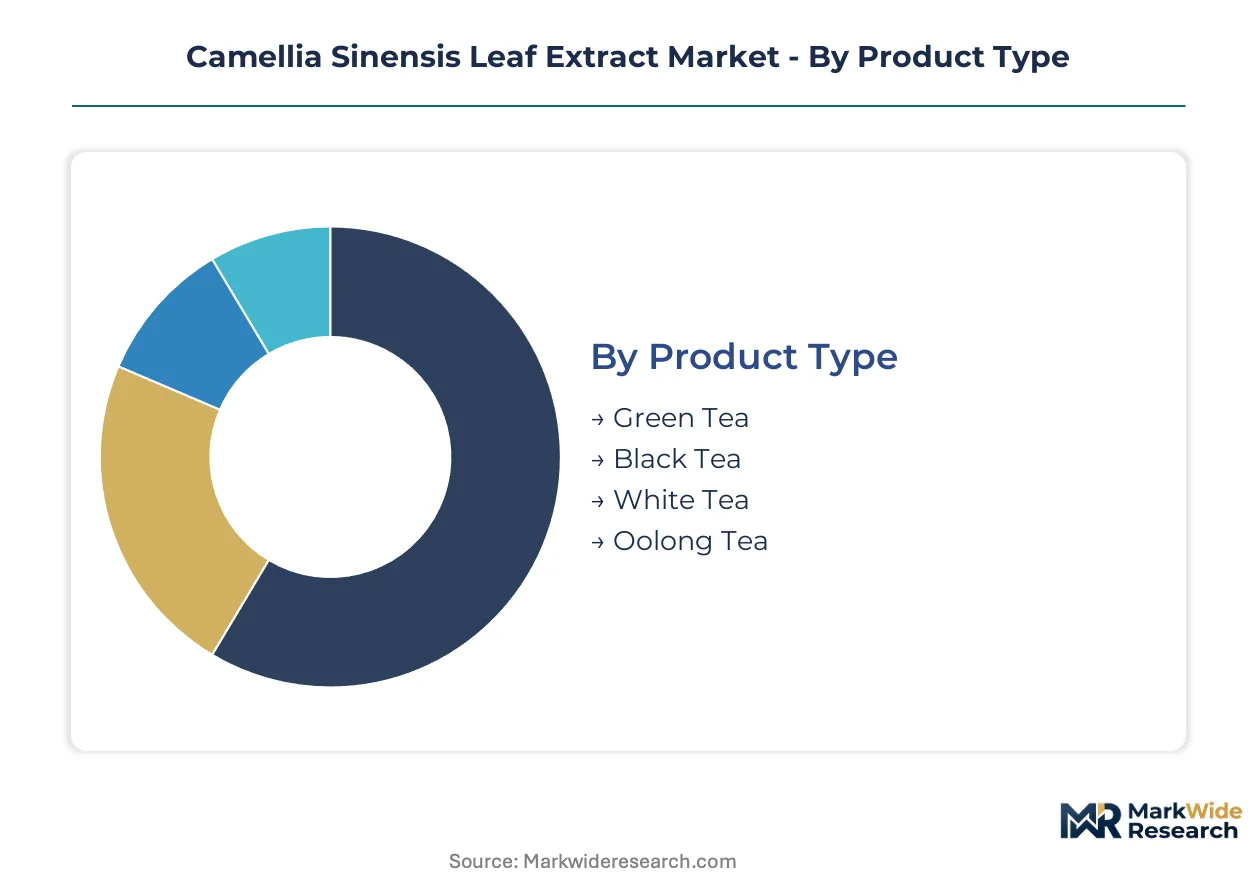
Ingredient formulators navigate distinct technical specifications across extract categories, each demanding tailored stabilization protocols and purity certifications. Procurement teams segment supplier evaluation by end-use regulatory burden, from cosmetic-grade polyphenol thresholds to pharmaceutical monograph compliance.
Product Type:
After-sales service intensity varies sharply across tea varietals, with green tea extract requiring chromatographic batch certification and stability consulting that black tea suppliers rarely provide.
- Green Tea:Standardized EGCG concentrations from 50% to 98% define pharmaceutical and nutraceutical procurement specifications. Demand concentrates in Japan and South Korea for FOSHU-compliant beverages and cognitive health capsules, driven by EFSA cardiovascular claim authorizations opening premium EU channels.
- Black Tea:Theaflavin-rich extracts target oxidation-resistant cosmetic formulations and functional food colorants. European beauty brands in France and Germany are expanding offtake for natural preservative systems displacing synthetic BHT in prestige skincare lines.
- White Tea:Minimal processing preserves delicate catechin profiles for luxury cosmetic serums.
- Oolong Tea:Semi-fermented polyphenol matrices command premium positioning in barrier-repair skincare from Seoul-based contract manufacturers.
By volume, green tea leads. By growth pace, oolong tea is ahead.
End User:
Cost tier stratification separates commodity food-grade extracts from pharmaceutical-certified supply, with nutraceuticals occupying the margin-intensive middle ground.
- Food & Beverage Industry:Beverage fortification and functional food dry-blends absorb standardized powder extracts at 50-70% polyphenol grades. Chinese domestic brands in Shanghai and Hangzhou are scaling captive extraction for export-ready ready-to-drink tea portfolios.
- Cosmetics:Skin barrier function claims utilizing oolong theaflavins and green tea EGCG drive serum and emulsion demand. South Korean formulators in Incheon and Seoul are outsourcing polyphenol stabilization to specialized extractors with integrated formulation laboratories.
- Pharmaceuticals:USP and EP monograph compliance mandates chromatographic purity verification and heavy metal profiling.
- Nutraceuticals:Capsule and tablet manufacturers in the US and Germany procure 95%+ standardized extracts for cardiovascular and cognitive health positioning.
Food and beverage commands absolute volume. Cosmetics is expanding most quickly.
Form:
Application requirements dictate form selection, with dry-blend compatibility and emulsion stability driving procurement specifications across customer types.
- Powder:Spray-dried and freeze-dried formats dominate tablet compression and functional food manufacturing. Indian mid-tier processors in Gujarat and Karnataka are adopting semi-continuous supercritical CO2 systems to reduce solvent residue compliance costs for EU-bound nutraceutical supply.
- Liquid Extract:Glycerin and ethanol-based solutions serve beverage fortification and cosmetic serum applications. Brazilian and Mexican functional drink brands are increasing offtake for natural energy positioning in Latin American markets.
- Capsules:Pre-measured dosing formats align with pharmaceutical and nutraceutical compliance requirements.
- Tea Bags:Whole-leaf and cut-leaf formats retain consumer-facing premium positioning in direct-to-consumer wellness channels.
Powder leads by volume. Liquid extract is gaining share fastest.
Application:
Supply concentration in Fujian and Zhejiang provinces shapes regional availability for high-purity extract categories serving regulated end-uses.
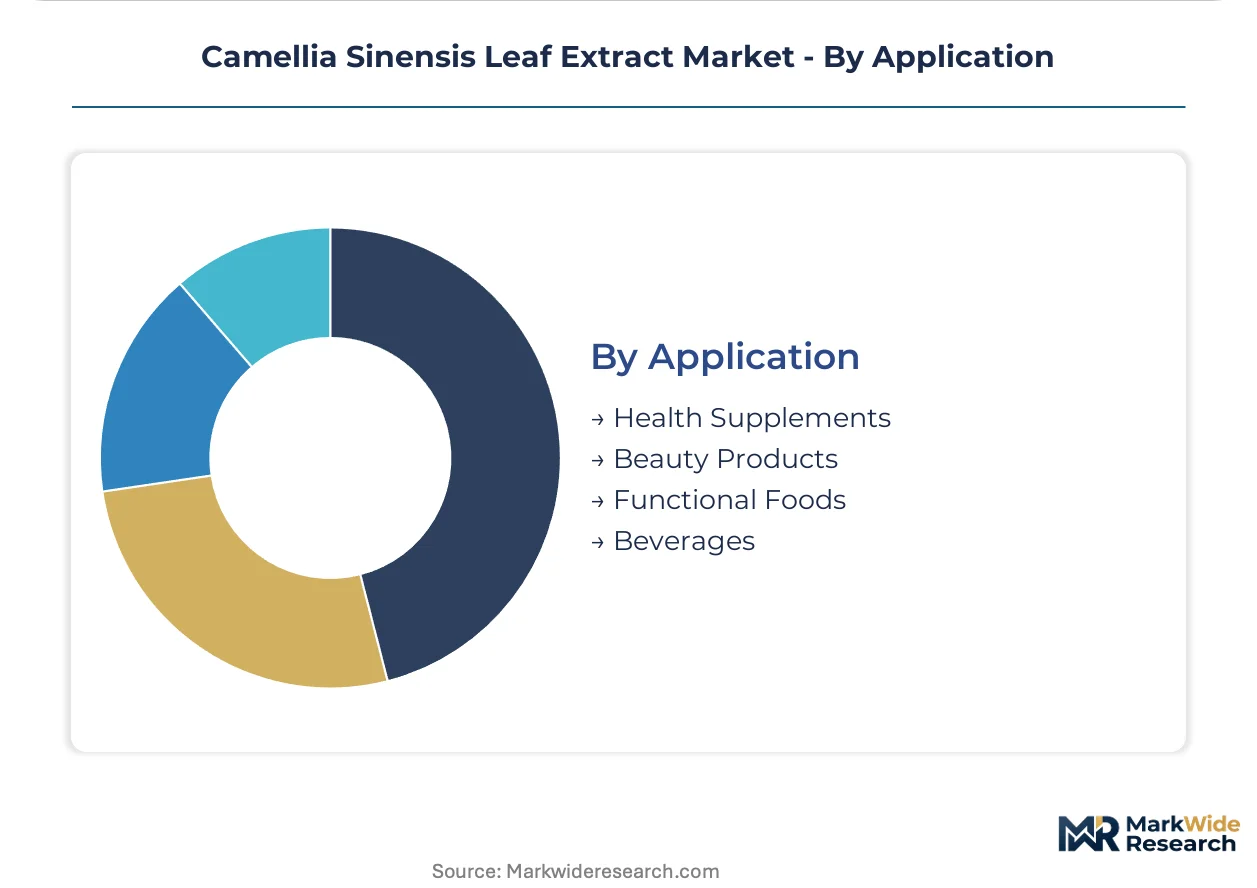
- Health Supplements:Capsule and softgel formulations demand 95%+ EGCG standardization with full pesticide and heavy metal documentation. US supplement brands in Utah and California are consolidating supplier bases to auditable farm-level traceability systems ahead of FTC substantiation enforcement.
- Beauty Products:Serum, cream, and mask applications prioritize oolong theaflavin and white tea catechin matrices for antioxidant and barrier-repair claims. French and Italian prestige houses are displacing synthetic ceramides with botanical polyphenol complexes.
- Functional Foods:Dry-blend fortification of snacks and meal replacements utilizes mid-grade polyphenol extracts.
- Beverages:Ready-to-drink and concentrate formats require heat-stable catechin preservation through advanced extraction technologies.
Health supplements dominate by volume. Beauty products show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes Camellia sinensis leaf extract primarily through functional food and beverage channels, while the United States and Germany concentrate procurement in nutraceutical capsule formulations and premium cosmetic applications respectively.
China
Domestic brands in Shanghai and Hangzhou are scaling captive extraction for export-ready ready-to-drink tea portfolios. SAMR incentives for low-carbon extraction technologies are redirecting capital toward supercritical CO2 systems. Fujian and Zhejiang provinces anchor processing capacity, though climate-induced harvest fluctuations compress margins during low-yield cycles.
United States
Supplement brands in Utah and California are consolidating supplier bases to auditable farm-level traceability systems ahead of FTC substantiation enforcement. FDA New Dietary Ingredient notification requirements govern nutraceutical entry. The Pacific Northwest and Mountain West regions host mid-tier processors adopting semi-continuous extraction systems for EU-bound supply.
Germany
Cosmetic formulators in Hamburg and North Rhine-Westphalia are expanding offtake for natural preservative systems displacing synthetic BHT in prestige skincare lines. EFSA Novel Food Regulation and health claim authorization processes tighten purity benchmarks for botanical extracts. The ECHA REACH registration framework mandates impurity disclosure thresholds tightening across supply tiers.
Japan
FOSHU approval pathways for tea catechin beverages remain underutilized by Western extractors seeking premium positioning in East Asian markets. METI standards and PMDA pharmaceutical-grade requirements shape import specifications. The Kanto region around Tokyo dominates pharmaceutical-grade demand, while Osaka-based formulators drive cosmetic serum applications.
South Korea
Seoul-based contract manufacturers are outsourcing polyphenol stabilization and emulsion compatibility testing to specialized extractors with integrated formulation laboratories. MFDS cosmetic and functional food regulations govern extract purity requirements. The Incheon cluster leads beauty product innovation, with K-beauty brands displacing synthetic ceramides with oolong theaflavin matrices.
Camellia Sinensis Leaf Extract Market Competitive Environment
Capability concentration sits with pharmaceutical-grade specialists commanding chromatographic certification and stability consulting expertise; scale advantage sits with integrated botanical houses leveraging captive sourcing networks across multiple tea-growing regions. The supply base organizes into three tiers: multinational flavor and fragrance conglomerates with backward integration into raw material procurement, mid-scale regional processors specializing in standardized polyphenol extracts, and niche pharmaceutical-grade manufacturers focused on USP and EP monograph compliance. Dominant competitive moves include direct-to-brand supply contracts bypassing trader intermediaries, and technology licensing partnerships for supercritical CO2-green solvent hybrid extraction systems.
Within the multinational integrated tier, Givaudan and Archer-Daniels-Midland Company exemplify scale-driven positioning through captive botanical sourcing networks. Taiyo Kagaku occupies a specialist position representing pharmaceutical-grade manufacturing archetypes with concentrated expertise in sunphenon-grade extract production. Kemin Industries anchors the antioxidant stabilization technology vector, while Indena S.p.A. and International Flavors & Fragrances Inc. sit within the botanical extract diversification archetype serving multiple regulated end-use channels.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company (ADM) |
| Givaudan |
| Synthite Industries Ltd |
| International Flavors & Fragrances Inc. |
| Finlays |
| Kemin Industries |
| Indena S.p.A. |
| Taiyo Kagaku |
| AVT Naturals |
| Others |
Value Chain & Pricing Dynamics
Fujian and Zhejiang province harvest concentration anchors upstream polyphenol supply, concentrating margin capture with processors commanding pharmaceutical-grade certification and chromatographic batch verification while commoditized extractors compete on solvent residue compliance alone.
Pricing Analysis
Long-term offtake agreements now dominate procurement between nutraceutical capsule manufacturers and standardized extract suppliers, displacing spot market transactions that exposed buyers to Fujian harvest volatility. Pricing stratifies across pharmaceutical-grade, nutraceutical-certified, and cosmetic-grade tiers, with USP monograph compliance commanding substantial premiums over food-grade polyphenol supply. Cost compression in mid-grade extracts is intensifying as Indian and Chinese processors adopt semi-continuous supercritical CO2 systems, eroding the pricing power of established European botanical houses. Contract manufacturers in South Korea exhibit lowest price sensitivity due to FOSHU premium positioning, while Latin American beverage fortifiers drive hardest bargain on liquid extract spot purchases.
Supply Chain Analysis
Camellia sinensis leaf feedstock draws from China, India, and Kenya cultivation belts, with Fujian province alone supplying the majority of high-catechin varietals for pharmaceutical extraction. Supercritical CO2 equipment, chromatography solvents, and pharmaceutical-grade packaging materials constitute critical input dependencies for certified supply tiers. Single-source vulnerability concentrates in Fujian-Zhejiang processing corridors, where climate-induced harvest fluctuations cascade through contract fulfillment timelines. Distribution runs through trader intermediaries for spot market volumes, while direct-to-brand supply contracts bypass traditional channels for premium standardized extracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and extraction technology maturity creates niche entry points for specialists, as beauty brand outsourcing of polyphenol stabilization services fragments demand away from commodity extract suppliers.
For Market Incumbents: Harden chromatographic certification depth against synthetic polyphenol substitution threats from precision biotechnology platforms. Expand captive sourcing networks into Karnataka and Gujarat processing corridors to reduce concentration risk in Fujian-Zhejiang supply belts. Invest in supercritical CO2-green solvent hybrid R&D to defend pharmaceutical-grade pricing power against mid-tier processor technology migration. For New Entrants and Emerging Players: Brazil and Mexico functional beverage markets offer underpenetrated white-space for liquid extract fortification, with natural energy positioning commanding premium placement versus established synthetic caffeine formulations. Japan FOSHU approval pathways for tea catechin beverages remain underserved by Western extractors despite premium channel economics. Target turnkey active delivery system partnerships with Seoul-based contract manufacturers rather than commodity powder supply. For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical-grade specialists with concentrated chromatography expertise and USP-EP monograph compliance capabilities, as synthetic substitution pressures commodity tiers while regulatory claim substantiation rewards certified supply. Long-term viability hinges on provenance verification infrastructure and farm-level traceability systems rather than volume scale alone. Watch EFSA botanical health claim authorization velocity as inflection indicator for European premium channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Technology Licensing | Enables pharmaceutical-grade purity at nutraceutical cost structures for veterinary applications. |
| Direct-to-Brand Supply Contracts | Bypasses trader intermediaries to capture margin lost to Fujian harvest spot volatility. |
| FOSHU Approval Pathway Investment | Opens premium positioning in Japanese functional beverage channels for Western extractors. |
| Farm-Level Traceability Infrastructure | Satisfies REACH registration requirements tightening impurity disclosure for EU cosmetic entry. |
| Chromatography Talent Acquisition | Addresses qualified specialist scarcity constraining mid-scale processor expansion timelines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EFSA health claim submissions, SAMR regulatory filings, and customs trade data for botanical extract categories. Extraction technology directors, nutraceutical procurement leads, cosmetic formulation scientists, and FOSHU regulatory consultants provided qualitative input across China, Japan, Germany, and the United States. Secondary validation drew from ECHA REACH guidance documents, USP monograph revisions, and MFDS cosmetic ingredient safety assessments. Bottom-up segment sizing triangulated against top-down trade flow analysis to constrain variance.
Forecast inputs span tea varietal grade tier, end-use regulatory burden from food-grade to pharmaceutical monograph, extraction technology type, and regional certification cluster. Modeled dimensions include product type segmentation, form factor requirements, and application-specific purity thresholds. CAGRs derived from trend extrapolation anchored to documented EFSA authorization timelines and SAMR low-carbon extraction incentive deployment. Polyphenol standardization demand curves and synthetic substitution elasticity informed trajectory bounds across the projection horizon.
Practitioners should monitor EFSA botanical evaluation backlog resolution and NMPA concentrated tea polyphenol classification updates for early signals of regulatory boundary shifts. Forecasts reflect assumptions around climate harvest stability and supercritical CO2 equipment cost decline curves. Cross-checking against EMA botanical drug development pipelines and pharmaceutical extract demand indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
US RTD Organic Tea Market
Tea
Spray-Dried Tea Products Market
Tea
North America Tea Market
Tea
Oolong Tea Market
Tea
Black Tea Market
Tea
Green Tea Leaves Market
Tea
Global Catechin Market
Tea
Tea Polyphenols Market
Tea
Black Tea Base Bubble Tea Market
Tea
Tea Essence Market
Tea
Global Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Black Tea Extracts Market
Tea
Butterfly Pea Flower Tea Market
Tea
Instant Tea Premixes Market
Tea
Smart Tea Set Market