
 Coffee Syrup Market | 2026-2036
Coffee Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Syrup Market Intelligence
A divergence in capital intensity for formulation R&D versus scaled production is rotating competitive advantage among players. Large-scale producers like Nestle leverage global distribution networks and brand recognition to capture mass-market retail share. Boutique specialists such as Monin and Torani differentiate on artisanal flavor profiles and deep penetration into the horeca channel. Meanwhile, ingredient suppliers like Tate & Lyle compete on formulation consistency and cost efficiency for major beverage manufacturers.
Coffee syrup is a concentrated liquid, typically a sugar or sugar-substitute solution, infused with coffee extracts and other flavorings to achieve a specific taste profile and viscosity. Its primary commercial purpose is to add flavor and sweetness to beverages, particularly coffee, as well as to desserts and baked goods. While classic flavors like vanilla and caramel maintain the largest market share, demand for unique, botanical-infused variants is growing in the specialty cafes application. The shift toward at-home coffee preparation is also driving sales through e-commerce platforms and retail channels.
The regulatory environment is shaped by national food safety authorities. In the United States, the FDA enforces stringent labeling requirements for ingredients and allergens. The European Food Safety Authority (EFSA) evaluates the safety of food additives used in syrup formulations, impacting market access across the EU. Navigating this complex web of international standards for sweeteners, colorants, and preservatives remains a critical operational challenge for manufacturers aiming for a global presence.
Market Dynamics
The primary structural force shaping the coffee syrup market is the bifurcation of production models. A clear divergence between the high-volume, cost-optimized approach of mass-market producers and the high-touch, flavor-focused R&D of boutique specialists is defining competitive lanes and value capture.
Growth Catalysts
- Specialty Cafe Culture:Proliferation of specialty cafes in markets like South Korea and Australia stimulates demand for premium and novel syrup flavors to support customized beverage menus and differentiate offerings.
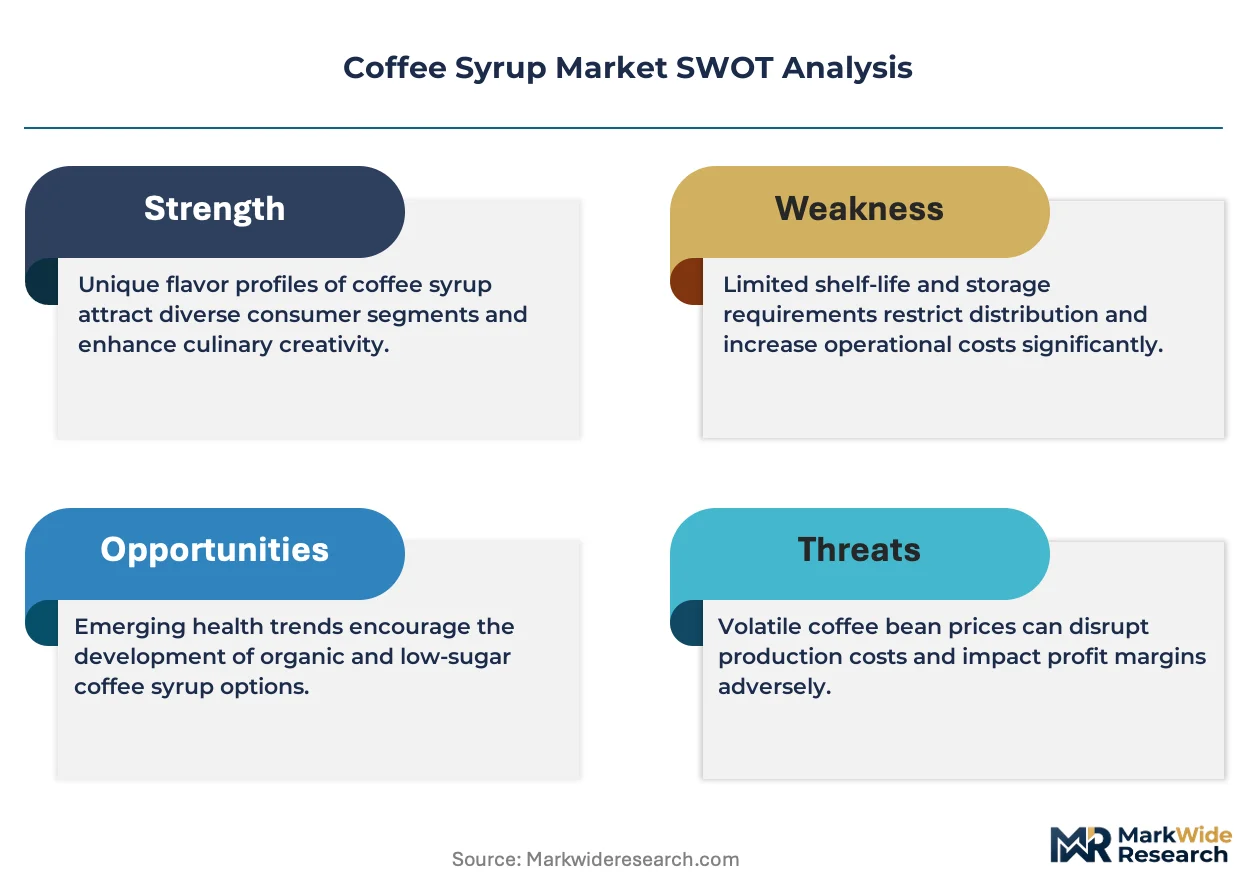
- Clean-Label Demand:Consumer preference for natural and simple ingredients, reinforced by FDA labeling requirements, is driving growth for syrups formulated without artificial colors, sweeteners, or preservatives.
- At-Home Consumption:The normalization of home-based coffee preparation expands the market beyond food service, increasing sales velocity through e-commerce platforms and traditional retail grocery channels.
Market Restraints
- Input Cost Volatility:Fluctuations in the global prices of essential raw materials, particularly sugar and coffee extracts, create margin pressure and introduce pricing instability for manufacturers.
- Regulatory Fragmentation:Navigating the disparate food additive and labeling standards between major regulatory bodies like the US FDA and the European EFSA complicates international trade and increases compliance costs.
- Substitution Threats:Coffee syrups face competition from alternative flavoring formats, including concentrated powders, fruit purees, and flavored coffee beans, which can appeal to different consumer preferences or applications.
Strategic Opportunities
- Functional Formulations:Development of syrups infused with functional ingredients, such as vitamins, probiotics, or adaptogens, opens a new market segment catering to health and wellness-oriented consumers. li>Culinary Application Expansion: Marketing syrups for use beyond coffee, in applications like craft cocktails, mocktails, baking, and as dessert toppings, creates new revenue streams in adjacent food and beverage categories.
- Emerging Market Penetration:Untapped demand in regions with nascent but growing cafe cultures, such as parts of Southeast Asia and Latin America, presents significant geographic expansion opportunities for established brands.
Industry Challenges
- Formulation Consistency:Maintaining consistent flavor profiles, viscosity, and quality across large production volumes and geographically dispersed manufacturing sites remains a significant operational hurdle.
- Compliance Overhead:The administrative and financial burden of securing and maintaining certifications for various international food safety and organic standards is a substantial operational challenge for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Syrup Market |
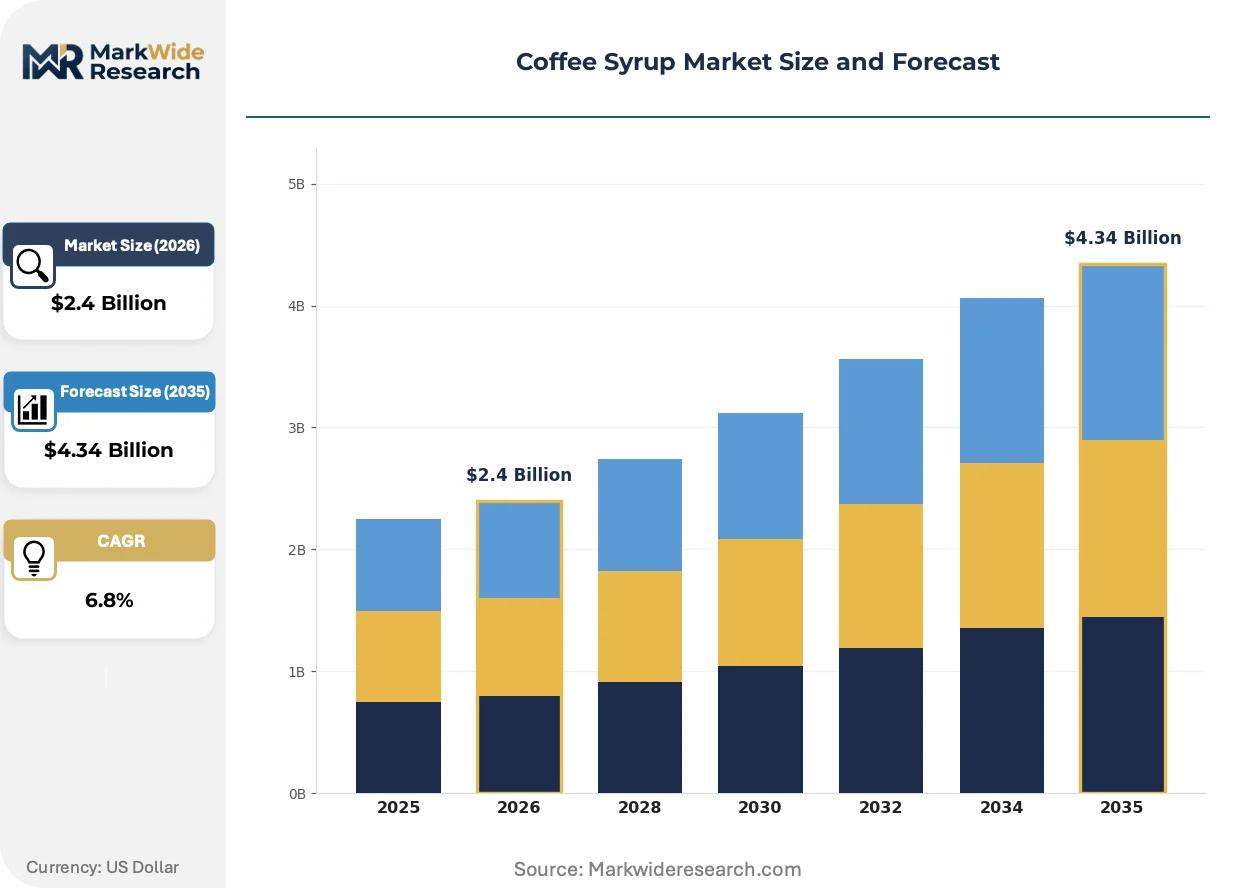
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Caramel, Hazelnut, Vanilla, Chocolate, Mocha Application: Coffee Shops, Bakeries, Beverage Manufacturers, Household Use, Food Service, Specialty Cafes Packaging Type: Glass Bottles, Plastic Bottles, Sachets, Pouches, Bulk Containers Customer Type: Retail Consumers, Horeca, Wholesalers, Distributors, E-commerce Platforms |
| Companies Covered | Nestle, Autocrat, Tate & Lyle, Kraft Heinz, Ghirardelli, Torani, Monin, Kerry Group, DaVinci Gourmet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Syrup Market Strategic Shifts & Innovations
Product innovation is centering on achieving precise flavor delivery and meeting demands for healthier formulations. Technology is enabling more complex sensory experiences, while regulatory pressures and consumer behaviors are pushing manufacturers toward greater transparency and new distribution models.
Flavor encapsulation technology provides a protective barrier for volatile aroma compounds, ensuring controlled release upon use. Premium beverage manufacturers and specialty cafes are the primary adopters, seeking to deliver consistent and impactful flavor profiles in their final products. This technology is decomposing the monolithic structure of traditional syrup flavoring, enabling multi-stage sensory experiences and greater product stability.
The European Food Safety Authority (EFSA) continues to enforce stringent evaluations of food additives, particularly impacting artificial colorants and high-intensity sweeteners. This regulatory pressure compels manufacturers to invest in R&D for natural alternatives, such as plant-based extracts and fruit-derived sweeteners. The specialty beverage segment across the EU is most affected, responding by marketing "clean label" attributes to appeal to discerning consumers.
A demand shift toward customizable, direct-to-consumer (DTC) flavor kits is altering distribution patterns. This model allows consumers to experiment with a variety of syrup flavors in smaller formats, often through a subscription service, bypassing conventional retail gatekeepers. The trend is most prominent among coffee aficionados in the United States and Australia, driven by targeted social media marketing and e-commerce agility.
Coffee Syrup Market Segmentation
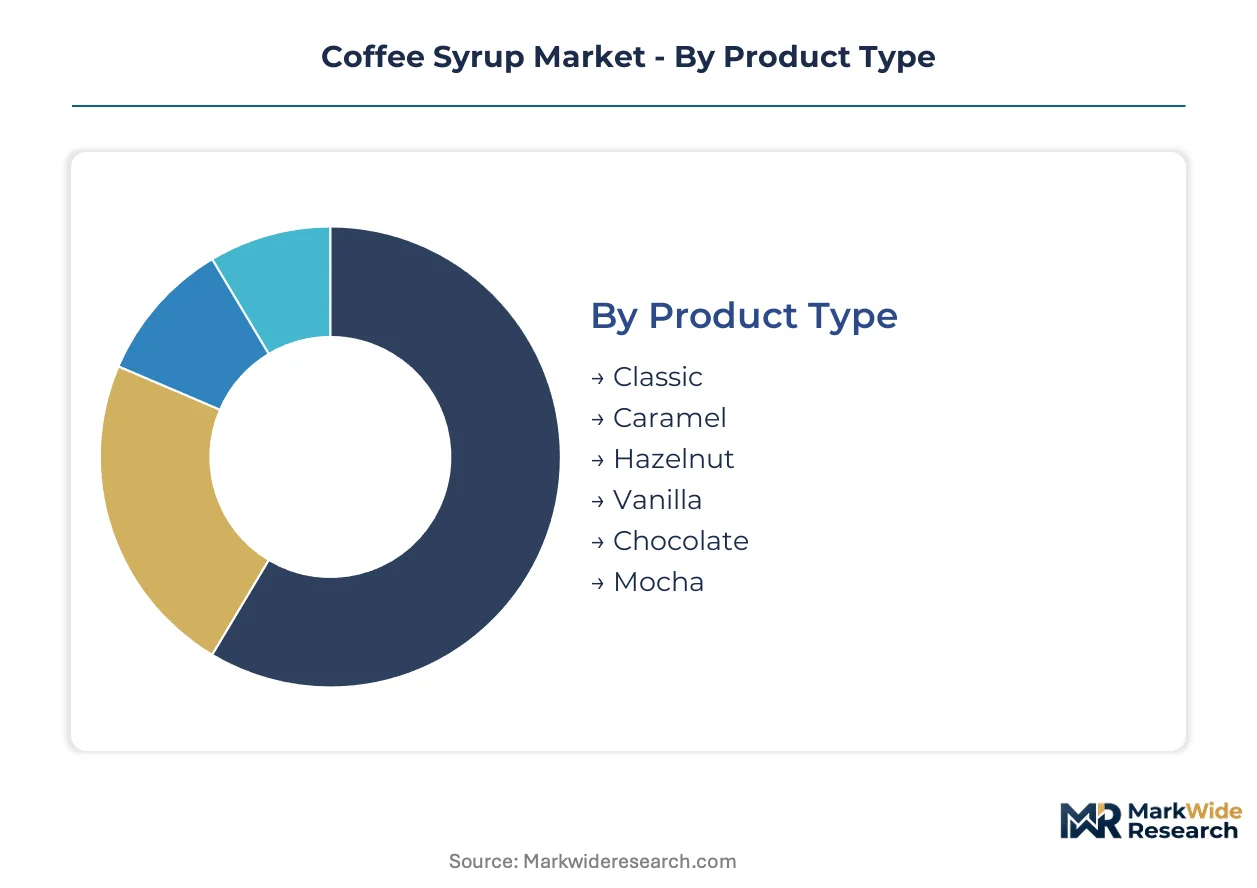
Market segmentation provides a structured view of the coffee syrup landscape, revealing distinct consumer preferences and operational models. Understanding these varied segments allows manufacturers to tailor product development and distribution strategies effectively. This granular analysis illuminates the diverse pathways for value capture across the market.
Product Type:
Regulatory differentiation influences the formulation and marketability of various coffee syrup product types globally. The FDA and EFSA enforce strict ingredient guidelines, particularly for artificial flavors and sweeteners, impacting product development across regions.
- Classic:This category encompasses fundamental flavor profiles like simple syrup or traditional coffee-flavored variants, often forming the base for customization. Demand remains consistently high in mass-market retail channels, driven by broad consumer familiarity and versatility in use.
- Caramel:A highly popular flavor, caramel syrup features a rich, sweet profile derived from caramelized sugar, frequently enhanced with dairy or butter notes. Specialty cafes in South Korea widely adopt caramel for signature beverages, appealing to consumers seeking indulgent and familiar tastes.
- Hazelnut:Hazelnut syrups provide a nutty, aromatic essence, often used in lattes and other coffee preparations. Retail consumers in the United States increasingly purchase hazelnut for at-home beverage customization.
- Vanilla:Vanilla syrup offers a universally appealing, sweet, and fragrant profile, making it a staple in both commercial and home settings. Its widespread acceptance ensures consistent demand across all application types.
- Chocolate:Chocolate syrups deliver a rich, cocoa-based flavor, popular in mocha-style drinks and dessert applications. Beverage manufacturers utilize chocolate variants for ready-to-drink coffee products.
- Mocha:Mocha syrups combine coffee and chocolate flavors, offering a balanced profile for specific beverage creations. Coffee shops integrate mocha into their seasonal and premium drink menus.
Classic flavors handle the majority of throughput; Caramel is the fastest mover on share.
Application:
Application focus drives product innovation and packaging formats, with distinct requirements shaping the syrup offerings for various end-users. Each application segment prioritizes specific attributes like shelf stability, ease of use, and flavor complexity.
- Specialty Cafes:These establishments require a diverse range of premium, often unique, and botanical-infused syrups to support customized beverage menus. Proliferation of specialty cafes in Australia stimulates demand for novel flavor profiles.
- Household Use:This segment comprises individual consumers purchasing syrups for at-home coffee preparation and other culinary uses. The shift toward at-home consumption expands sales through e-commerce platforms.
- Coffee Shops:Traditional coffee shops utilize a core range of popular syrup flavors for standard beverage offerings. Bulk containers and consistent flavor profiles are critical for operational efficiency.
- Bakeries:Bakeries incorporate coffee syrups as ingredients in desserts, glazes, and baked goods, valuing heat stability and concentrated flavor. This application expands the culinary utility beyond beverages.
- Beverage Manufacturers:Large-scale beverage producers integrate syrups into their ready-to-drink coffee and flavored milk products, prioritizing cost efficiency and formulation consistency. Ingredient suppliers cater to their specific volume and quality control needs.
- Food Service:This broad category includes restaurants, hotels, and catering services, which use syrups for various drinks and dessert toppings. Versatility and consistent supply are important for this segment.
Household Use is gaining share fastest; Specialty Cafes exhibit the steepest expansion trajectory.
Packaging Type:
Cost tier considerations significantly influence the choice of packaging type, balancing material expense with product protection and consumer convenience. Different packaging formats cater to varying distribution models and end-user requirements.
- Plastic Bottles:These lightweight and shatter-resistant containers are prevalent for mass-market retail and household consumption, offering cost-effectiveness and safety. Their widespread use supports high-volume distribution through grocery channels.
- Glass Bottles:Often associated with premium products, glass bottles provide an inert barrier for flavor preservation and offer a sophisticated aesthetic. Boutique specialists frequently use glass packaging to differentiate their artisanal syrup profiles.
- Sachets:Small, single-serve sachets offer convenience and portion control, primarily targeting travel, hospitality, or on-the-go consumption. This format minimizes waste and ensures freshness for individual servings.
- Pouches:Flexible pouches provide an efficient and lightweight packaging solution, reducing material use and shipping costs. Some e-commerce brands adopt pouches for refill options or concentrated syrup formulations.
- Bulk Containers:Large-volume containers, such as drums or bag-in-box formats, are designed for industrial use by beverage manufacturers and large food service operations. These containers prioritize cost efficiency and high-volume dispensing.
Plastic Bottles represent the largest volume segment; Pouches are expanding most quickly.
Customer Type:
Customer type defines distinct purchasing behaviors and channel preferences, shaping how coffee syrups are marketed and distributed. Each customer segment requires tailored engagement strategies and product offerings.
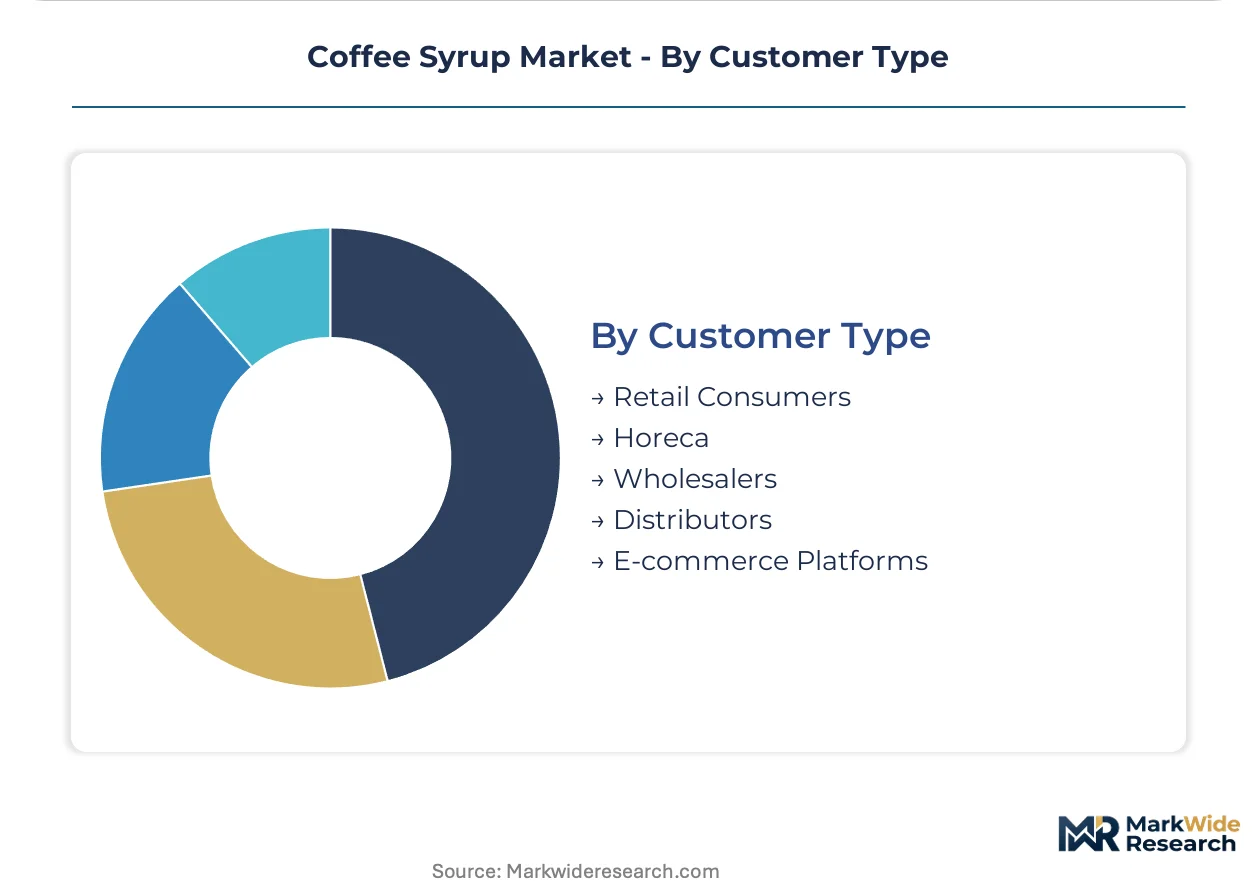
- Retail Consumers:These individuals purchase coffee syrups for personal use through grocery stores, specialty food shops, or online platforms. The shift toward at-home coffee preparation directly drives sales to this segment.
- Horeca:Comprising hotels, restaurants, and cafes, the Horeca channel demands consistent quality, reliable supply, and often specialized flavor profiles. Boutique specialists achieve deep penetration into this channel.
- Wholesalers:Wholesalers act as intermediaries, distributing large volumes of syrup to various retail and food service outlets. Their role is critical in ensuring broad market availability for manufacturers.
- Distributors:Distributors manage logistics and supply chain operations, connecting manufacturers with diverse customer types across regions. They play a vital role in market access and reach.
- E-commerce Platforms:Online marketplaces facilitate direct sales to consumers, particularly for niche or specialty syrup brands. Targeted social media marketing drives adoption within this channel.
Retail Consumers contribute the largest revenue share; E-commerce Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident between mature markets like the United States and emerging economies such as India. Manufacturers in North America often command higher margins due to established brand loyalty and premium product offerings. Conversely, pricing in developing Asian markets is more sensitive to cost-efficiency and local competition.
United States
Retail consumers in the United States drive significant demand for hazelnut and vanilla syrups for at-home beverage customization. The FDA enforces stringent labeling requirements for ingredients and allergens, influencing product transparency. E-commerce platforms in major metropolitan areas like New York facilitate direct-to-consumer sales of specialty syrup kits.
South Korea
South Korea exhibits robust demand for indulgent caramel and mocha syrups within its vibrant specialty cafe culture. The Ministry of Food and Drug Safety (MFDS) oversees food additive approvals, ensuring product safety standards. Seoul's numerous cafes actively experiment with novel flavor profiles, stimulating product innovation and premium offerings.
Germany
German consumers increasingly seek clean-label syrup formulations, boosting demand for natural alternatives in coffee shops. The European Food Safety Authority (EFSA) evaluates food additives, pushing manufacturers toward plant-based extracts. Major cities like Berlin and Hamburg see a concentration of specialty cafes adopting unique botanical-infused syrup variants.
Australia
Australia's thriving specialty cafe scene stimulates demand for unique and botanical-infused syrups, supporting customized beverage menus. The Therapeutic Goods Administration (TGA) regulates functional ingredients if syrups make health claims. Melbourne's coffee culture is a significant driver, with cafes constantly introducing novel flavor combinations to differentiate offerings.
India
India represents an emerging market with growing cafe cultures, particularly in urban centers, creating demand for both classic and new syrup flavors. The Food Safety and Standards Authority of India (FSSAI) sets standards for food additives and labeling. Bengaluru, a major tech hub, sees a rapid increase in coffee shop chains incorporating diverse syrup options.
Coffee Syrup Market Key Industry Players
Concentration sits with large-scale producers leveraging extensive distribution networks for mass-market retail share. The coffee syrup market exhibits a tiered structure, from global food conglomerates to boutique specialists. Strategic archetypes include mass-market volume players, premium flavor innovators, and ingredient suppliers. Portfolio diversification into functional formulations and geographic expansion into emerging markets are dominant competitive moves.
Specialists in artisanal flavor profiles, Monin and Torani, exemplify the boutique segment's approach to deep penetration into the horeca channel. These entities focus on unique and premium flavor development, catering to specialty cafes and discerning consumers with distinctive offerings. Their differentiation strategy revolves around flavor innovation and product quality. Conversely, Nestle represents the large-scale producer archetype, leveraging its global brand recognition and extensive distribution networks to capture significant mass-market retail share. This market positioning highlights the bifurcation of production models, with some players prioritizing high-touch R&D and others focusing on cost-optimized volume and broad accessibility.
| Leading Market Players |
|---|
| Nestle |
| Autocrat |
| Tate & Lyle |
| Kraft Heinz |
| Ghirardelli |
| Torani |
| Monin |
| Kerry Group |
| DaVinci Gourmet |
| Others |
Cost & Logistics Intelligence
Extended raw material procurement lead times, particularly for key agricultural inputs, directly influence the cost structure and pricing power across the coffee syrup market. This dynamic creates a direct linkage between global commodity markets and consumer-facing product costs, impacting manufacturer margins and retail prices.
Pricing Analysis
The customization-premium spread influences pricing across the coffee syrup market, with artisanal formulations commanding higher margins. Pricing stratifies across premium, standard, and economy tiers, differentiated by ingredient quality and brand recognition. Pricing pressure stems from input cost volatility, particularly for sugar and coffee extracts, compressing margins for mass-market producers. Retail consumers exhibit higher price sensitivity for standard flavors, while specialty cafes prioritize premium quality and unique profiles.
Supply Chain Analysis
Brazil and India anchor global sugar production, a primary input for coffee syrups, alongside major coffee-producing nations like Vietnam. The supply chain draws from diverse agricultural regions for coffee extracts and botanical flavorings. Commodity price volatility represents a significant structural risk, affecting manufacturing costs and product stability. Distribution runs through established global networks for large producers and increasingly through e-commerce platforms for niche specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coffee syrup market is an early-cycle expansion story, driven by the increasing penetration of specialty cafe culture globally.
For Market Incumbents:Compound brand recognition through strategic acquisitions of boutique flavor specialists, consolidating market share against emerging artisanal competitors. Invest in advanced flavor encapsulation R&D to deliver consistent, complex profiles, mitigating the threat of substitution from alternative flavoring formats. Leverage global distribution networks to efficiently scale clean-label product lines, responding to evolving consumer preferences and FDA labeling requirements.
For New Entrants and Emerging Players:Differentiate on unique botanical-infused flavor profiles, targeting health-conscious consumers in specialty cafes within Australia and Germany. Focus on functional formulations, such as adaptogen-infused syrups, to create new market segments. Penetrate emerging markets in Southeast Asia and Latin America with agile, localized product offerings. Utilize direct-to-consumer (DTC) e-commerce platforms for targeted marketing and rapid product iteration.
For Investors and Strategic Acquirers:Long-term, this sits as a consumer staples innovation play because customized beverage culture shows sustained growth. Acquisition targets include mid-sized specialty flavor houses with strong clean-label R&D capabilities and established Horeca channel penetration. A signal to watch for inflection is the regulatory harmonization of food additives across major blocs, streamlining international market access for innovative formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch (Functional Formulations) | Introduces health-oriented options for wellness-focused consumers. |
| Distribution Channel Expansion (E-commerce) | Captures at-home consumption trends and broadens market reach. |
| Acquisition of Specialist Firm (Boutique Flavor House) | Integrates unique artisanal profiles and expands Horeca penetration. |
| Green Manufacturing Transition (Sustainable Sourcing) | Addresses clean-label demand and enhances brand reputation. |
| Geographic Expansion (Southeast Asia) | Penetrates untapped regions with nascent but growing cafe cultures. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research validated findings. Primary insights gathered from beverage R&D leads, Horeca procurement managers, specialty cafe owners, and e-commerce platform managers. Secondary sources included FDA enforcement records, EFSA additive evaluations, national food safety authority reports, and retail sales data, triangulated for bottom-up and top-down validation.
The forecast window spans a nine-year period, integrating market dynamics and historical growth patterns. Segmentation dimensions modeled included product type, application, packaging type, customer type, and regional cafe culture maturity. Compound annual growth rates were derived through a weighted average of segment-specific projections. Key industry-specific forecast inputs included consumer preference shifts for natural ingredients and global coffee consumption trends.
Material uncertainties — commodity price volatility and unforeseen regulatory shifts — sit outside the modeled envelope, influencing future market trajectories. Forecasts reflect assumptions regarding stable economic conditions and consistent technological progress. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Italy Coffee Market
Coffee
Germany Coffee Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Oceania Coffee Market
Coffee
Smart Coffee Maker Market
Coffee
Single-Serve Coffee Containers Market
Coffee
US Instant Coffee Market
Coffee
Portable Espresso Machines Market
Coffee
Middle East Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
Global Coffee Market
Coffee
Decaf Coffee Market