
 US Ready to Drink Tea Market | 2026-2036
US Ready to Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
US Ready to Drink Tea Market Insights
Bottled beverage production across the southeastern United States is shifting toward aseptic cold-fill lines capable of handling low-acid formulations. PepsiCo, Inc. leverages its Gatorade manufacturing network to co-produce ready to drink tea at scale. The Coca-Cola Company anchors its position through Gold Peak Tea's refrigerated distribution footprint. Keurig Dr Pepper, Inc. competes via Snapple's legacy brand equity in the Northeast corridor.
Ready to drink tea denotes brewed, packaged tea beverages preserved through pasteurization, hot-fill processing, or aseptic technology, typically containing tea extract, water, sweeteners, and acidulants, with a shelf life ranging from several weeks to twelve months depending on processing method. Black tea formulations dominate volume due to established consumer familiarity and lower raw material costs, while green tea segments command premium shelf positioning based on antioxidant positioning. Bottles retain the largest packaging share by value, though cans accelerate in convenience channels and foodservice accounts seeking single-serve portability. Supermarkets still control the primary volume throughput, yet online retail captures disproportionate growth in subscription-based repeat purchases.
FDA enforces juice and beverage labeling standards under 21 CFR 101 that govern nutrient content claims and added sugar disclosures, directly constraining formulation architectures. State-level excise taxes on sugar-sweetened beverages in jurisdictions like Philadelphia and Seattle force price architecture adjustments or reformulation toward zero-calorie sweetener systems. USDA organic certification requirements influence sourcing decisions for premium private label programs. Stakeholders must monitor evolving municipal tax regimes and clean label audit trails to preserve margin structures.
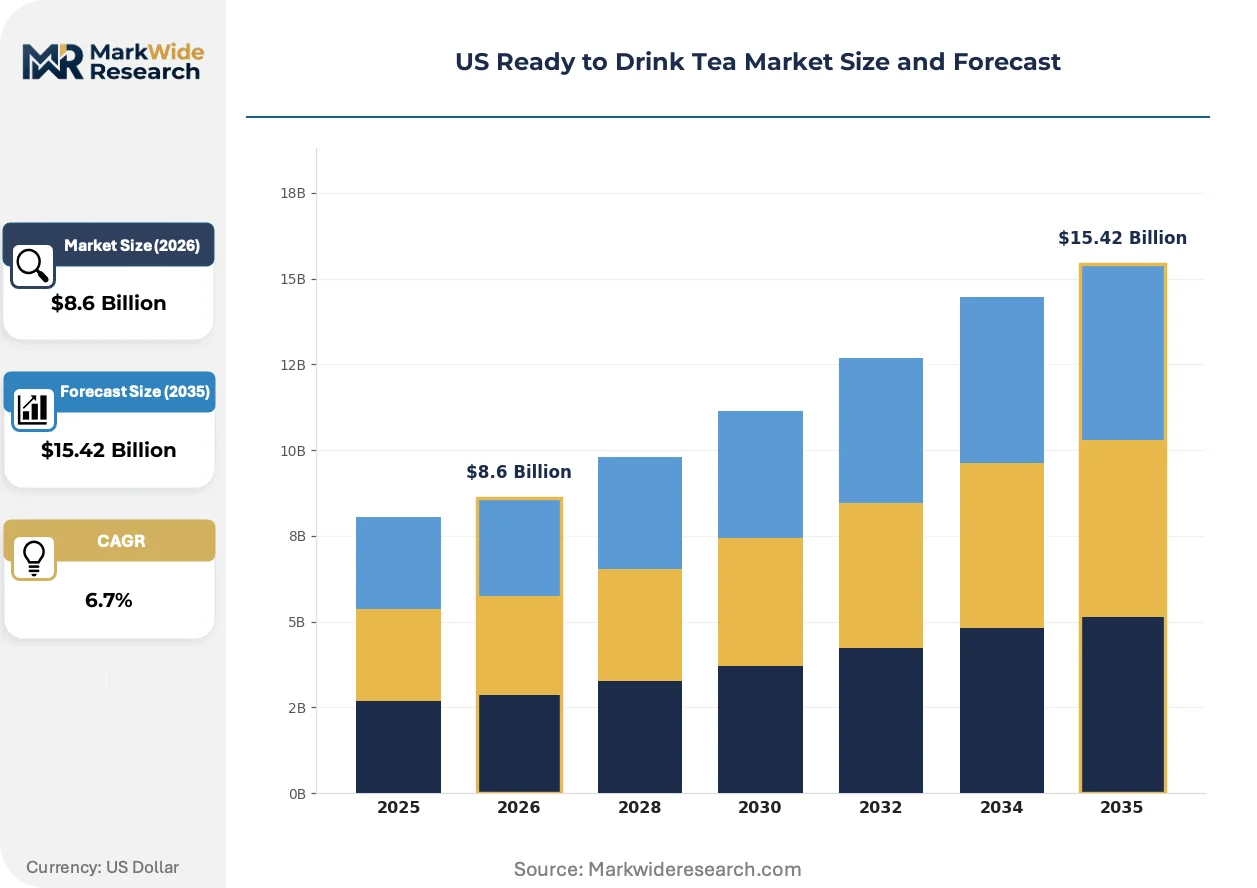
Market Dynamics
State-level sugar-sweetened beverage taxes and FDA labeling mandates under 21 CFR 101 are forcing reformulation across the US ready to drink tea landscape, compressing margin structures while accelerating zero-calorie sweetener adoption.
Growth Catalysts
- ASEPTIC COLD-FILL TECHNOLOGY:Advanced aseptic processing lines in southeastern manufacturing clusters now handle low-acid tea formulations without preservatives, extending shelf life while meeting clean label demands from urban millennials.
- California Climate Premium:Year-round warm weather in California, Texas, and Florida sustains consistent consumption velocity unmatched in seasonal northern markets, anchoring national volume baselines.
- USDA Organic Certification:Premium private label programs increasingly require certified organic sourcing, creating tiered positioning opportunities above conventional black tea segments.
Market Restraints
- ALUMINUM CAN INPUT VOLATILITY:Can packaging acceleration in convenience channels exposes producers to commodity aluminum price swings and tariff-sensitive supply chains.
- SUGAR TAX CASCADES:Municipal excise taxes in Philadelphia, Seattle, and other jurisdictions force parallel price architectures or margin-eroding reformulation investments.
- REFRIGERATED DISTRIBUTION CONCENTRATION:Cold-chain dependent premium SKUs concentrate volume in Gold Peak's refrigerated footprint, creating bottlenecks outside PepsiCo's ambient Gatorade network.
Strategic Opportunities
- SUBSCRIPTION COMMERCE WHITE SPACE:Online retail channels capture disproportionate repeat purchase velocity through direct-to-consumer subscription models bypassing supermarket slotting fees.
- GREEN TEA ANTIOXIDANT POSITIONING:Premium shelf positioning for green tea variants remains underexploited relative to black tea volume dominance, offering margin expansion potential.
- FOODSERVICE CAN PENETRATION:Single-serve aluminum formats accelerate in convenience channels and foodservice accounts seeking portability without refrigeration dependency.
Industry Challenges
- SWEETENER SYSTEM REFORMULATION TIMELINES:FDA GRAS determination processes for novel zero-calorie alternatives compress product development cycles against tax deadline pressures.
- ASEPTIC LINE CAPEX INTENSITY:Transition from hot-fill to aseptic cold-fill processing demands eight-figure capital commitments per facility upgrade.
- CLEAN LABEL AUDIT TRAIL COMPLEXITY:Organic certification and non-GMO verification require documented sourcing transparency through multi-tier tea extract supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ready to Drink Tea Market |
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $15.42 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Fruit Tea Packaging Type: Bottles, Cans, Tetra Packs, Pouches Flavor Profile: Peach, Lemon, Mint, Chai Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafés |
| Companies Covered | PepsiCo, Inc., The Coca-Cola Company, Keurig Dr Pepper, Inc., Arizona Beverages USA, Unilever, Milo’s Tea Company, Inc., ITO EN (North America) Inc., Honest Tea, Gold Peak Tea, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ready to Drink Tea Market Trends and Innovations
Formulation science and distribution technology are reshaping competitive positioning in US ready to drink tea, with cold-chain capabilities and sweetener chemistry separating premium from value tiers.
Aseptic cold-fill processing is converging with high-pressure processing (HPP) in pilot installations across southeastern manufacturing corridors. Mid-sized co-packers in Georgia and North Carolina are adopting hybrid lines that preserve volatile aromatic compounds in green tea extracts. This technology convergence is compressing the shelf-life gap between refrigerated and ambient tea segments, enabling premium positioning without cold-chain dependency.
FDA enforcement of added sugar disclosure rules under 21 CFR 101.60 is forcing front-of-package redesigns across supermarket SKUs. The regulation mandates single-serve serving size alignment with actual consumption patterns, exposing true sugar loads in historically understated 8-ounce presentations. Black tea formulations in conventional supermarkets face the steepest compliance costs, accelerating migration toward zero-calorie stevia and monk fruit systems.
Urban Gen Z buyers are consolidating repeat purchases through subscription-based direct-to-consumer platforms, displacing traditional supermarket restocking rituals. This channel shift concentrates lifetime value capture in digitally native brands while eroding slotting-fee economics for legacy supermarket-dependent portfolios. California and Florida metropolitan corridors exhibit the highest subscription penetration, correlating with warm-climate consumption frequency and delivery logistics density.
US Ready to Drink Tea Market Segmentation
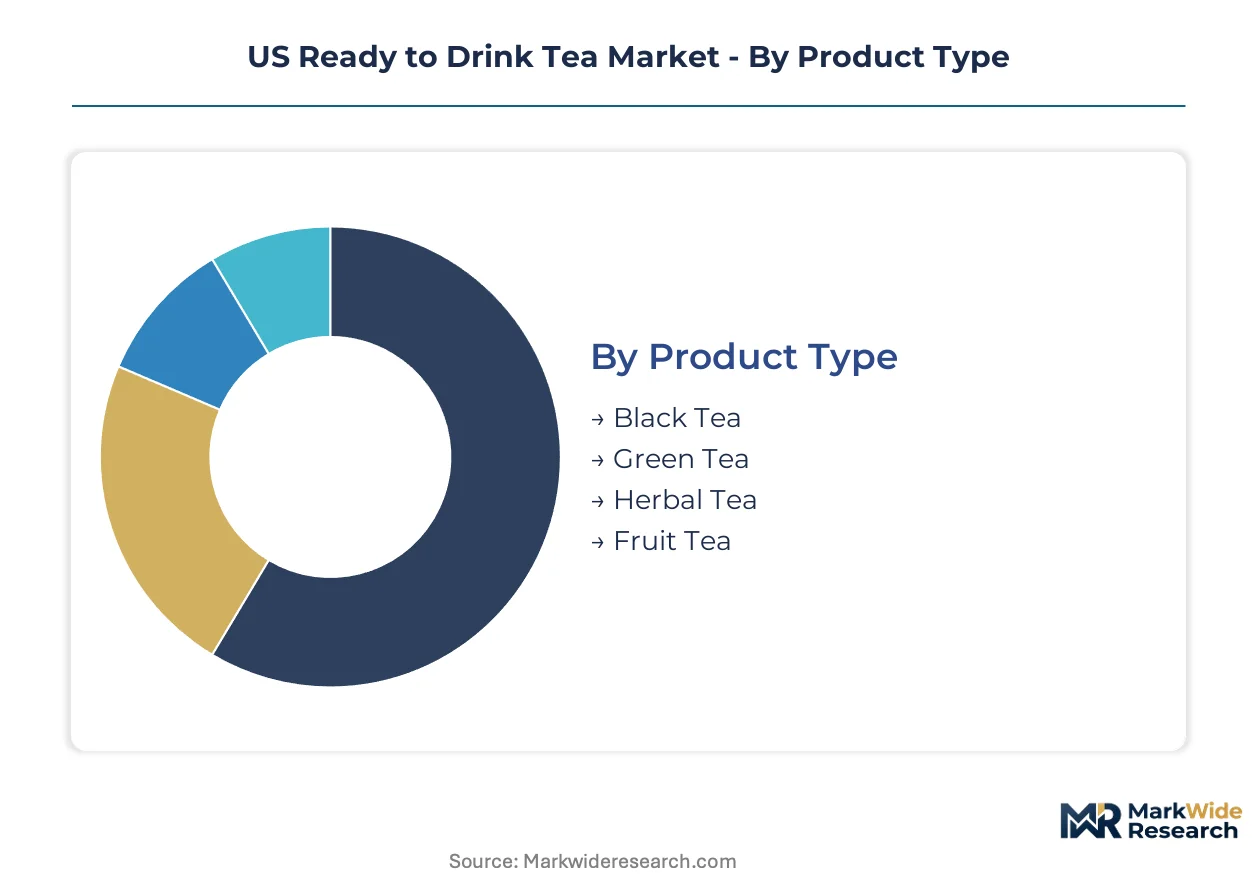
US ready to drink tea segmentation reflects divergent compliance burdens across product architectures. FDA labeling mandates under 21 CFR 101 and state-level sugar taxes create tiered certification requirements that reshape margin structures by segment.
Product Type:
USDA organic certification and FDA GRAS determinations for novel sweeteners impose distinct burdens across tea extract categories.
- Black Tea:Conventional formulations face the steepest reformulation pressure from FDA added sugar disclosure rules. Volume concentrates in conventional supermarkets across California, Texas, and Florida where warm climates sustain year-round consumption velocity.
- Green Tea:Premium antioxidant positioning commands higher shelf placement but requires documented sourcing transparency through multi-tier tea extract supply chains. Demand clusters in urban Gen Z subscriptions and refrigerated convenience channels in metropolitan corridors.
- Herbal Tea:Caffeine-free positioning attracts functional wellness buyers seeking evening consumption occasions.
- Fruit Tea:Blended formulations with juice content trigger stricter FDA juice labeling standards under 21 CFR 101.
Leading the category by volume: Black Tea. Growing fastest: Green Tea.
Packaging Type:
Cost tiers separate cold-chain dependent formats from ambient-stable alternatives, with capital intensity scaling inversely to distribution flexibility.
- Bottles:PET and glass formats retain the largest value share, though hot-fill processing limits shelf life extension. Demand concentrates in supermarket ambient aisles and refrigerated premium sets in Gold Peak's distribution footprint.
- Cans:Aluminum formats accelerate in convenience channels seeking single-serve portability without refrigeration dependency. PepsiCo's Gatorade network favors can production for ambient distribution efficiency.
- Tetra Paks:Aseptic carton technology enables extended shelf life for organic private label programs.
- Pouches:Flexible formats target foodservice accounts and on-the-go consumption in transit corridors.
Dominating value capture: Bottles. Expanding most quickly: Cans.
Flavor Profile:
Application-driven segmentation maps flavor innovation to named consumption occasions and channel-specific velocity patterns.
- Peach:Southern and Sun Belt markets drive repeat purchase velocity in convenience stores and vending accounts.
- Lemon:Classic positioning anchors conventional black tea formulations in mainstream supermarket sets.
- Mint:Refreshment-forward profiles target foodservice and café channels seeking differentiation from standard offerings.
- Chai:Spiced formulations capture premium positioning in specialty retail and subscription commerce.
Widest distribution: Lemon. Steepest expansion trajectory: Chai.
Distribution Channel:
Customer type separation distinguishes high-frequency replenishment from planned stock-up occasions, with digital native buyers displacing traditional supermarket rituals.
- Supermarkets:Slotting-fee economics dominate volume throughput, though reformulation costs from sugar tax exposure compress margins. Black tea SKUs face front-of-package redesign mandates under FDA serving size alignment rules.
- Online Retail:Subscription-based direct-to-consumer models capture disproportionate repeat purchase velocity among urban Gen Z buyers. California and Florida metropolitan corridors exhibit highest penetration, correlating with delivery logistics density.
- Convenience Stores:Single-serve can formats accelerate in 24-hour retail seeking portability without cold-chain investment.
- Cafés:Premium refrigerated SKUs target on-premise consumption with higher per-unit pricing.
Highest volume throughput: Supermarkets. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camellia sinensis cultivation in Southeast Asia and East Africa supplies the tea extracts that anchor US ready to drink tea formulation, with processing and packaging infrastructure concentrated in domestic manufacturing corridors.
California
Warm-climate consumption velocity sustains year-round demand velocity unmatched in seasonal northern markets. Los Angeles and San Francisco metropolitan corridors exhibit the highest subscription commerce penetration for direct-to-consumer tea brands. FDA labeling enforcement under 21 CFR 101 drives front-of-package redesign investments across conventional supermarket SKUs in the state.
Texas
Urban millennial and Gen Z buyers in Dallas-Fort Worth and Houston drive convenience channel acceleration for single-serve can formats. State-level absence of sugar-sweetened beverage taxes permits conventional sweetener formulations unavailable in taxed jurisdictions. Aseptic cold-fill processing lines in the southeastern manufacturing corridor supply ambient-stable products for Texas distribution networks.
Florida
Year-round warm weather sustains consistent consumption baselines for both refrigerated premium SKUs and ambient bottle formats. Miami and Tampa metropolitan areas concentrate foodservice account demand for portable single-serve packaging. The state's logistics density supports rapid inventory turnover for perishable refrigerated tea products.
Southeast Manufacturing Corridor
Georgia and North Carolina host advanced aseptic processing installations capable of handling low-acid tea formulations without preservatives. PepsiCo leverages its Gatorade manufacturing network in this region for ambient tea production at scale. The Coca-Cola Company's Gold Peak refrigerated distribution footprint concentrates cold-chain dependent premium volume in adjacent southeastern markets.
Northeast Corridor
Philadelphia and Seattle municipal sugar taxes force parallel price architectures or zero-calorie reformulation for products entering these jurisdictions. Keurig Dr Pepper competes via Snapple's legacy brand equity concentrated in metropolitan New York and Boston. Urban Gen Z subscription penetration lags warm-climate states but accelerates in dense delivery logistics corridors.
US Ready to Drink Tea Market Competitive Landscape
Global beverage majors compete with regional tea specialists across distribution architecture and temperature-control requirements. The vendor base separates into ambient-scale producers, refrigerated premium networks, and digitally native subscription brands. Three strategic archetypes dominate: diversified multinational beverage conglomerates with cross-category manufacturing infrastructure; heritage tea specialists with extract sourcing relationships; and direct-to-consumer entrants bypassing supermarket slotting economics. Consolidation pressure concentrates in aseptic line capacity expansion and subscription platform acquisition.
Within the diversified multinational tier, PepsiCo, Inc. and The Coca-Cola Company occupy positions defined by contrasting distribution strategies. Keurig Dr Pepper, Inc. anchors the heritage brand specialist archetype with regional density in the Northeast corridor. These three companies exemplify how scale-driven manufacturing networks, refrigerated cold-chain investments, and legacy brand equity respectively define competitive positioning in the US ready to drink tea landscape.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Keurig Dr Pepper, Inc. |
| Arizona Beverages USA |
| Unilever |
| Milo's Tea Company, Inc. |
| ITO EN (North America) Inc. |
| Honest Tea |
| Gold Peak Tea |
| Others |
Pricing and Supply Chain Analysis
Urban convenience store operators and subscription platform buyers concentrate purchasing power across divergent pricing architectures, with cold-chain dependent formats commanding shelf-life premiums and ambient-stable alternatives competing on unit economics.
Pricing Analysis
Service bundling separates refrigerated distribution networks from ambient shelf-stable alternatives, with Gold Peak's cold-chain logistics unbundled from base product pricing while PepsiCo's Gatorade network embeds delivery economics into wholesale rates. Three-tier pricing structure across premium organic, standard conventional, and economy private label levels stratifies the category. Price differentiation hinges on USDA organic certification tier and after-sales velocity guarantees to retailers. Cost compression in conventional black tea segments is intensifying because FDA added sugar disclosure rules force front-of-package redesign investments. Foodservice accounts exhibit highest price sensitivity due to volume concentration, while direct-to-consumer subscribers show lowest sensitivity tied to loyalty program lock-in.
Supply Chain Analysis
Reverse logistics for refrigerated SKUs concentrate returns and refurbishment flows through Coca-Cola's closed-loop distribution network, with temperature excursion claims driving asset recovery programs in southeastern cold-chain hubs. Tea extract sourcing draws from India, Kenya, and Sri Lanka for black tea varieties, with Chinese and Japanese origins dominating green tea procurement. Aluminum can sheet, PET resin, and natural sweetener inputs anchor raw material dependencies. Single-source vulnerability concentrates in aseptic line equipment suppliers serving southeastern manufacturing clusters. Distribution runs through direct-store-delivery for refrigerated premium products and warehouse club networks for ambient bulk formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure favors scale players with aseptic line capacity, as eight-figure capital requirements for cold-fill technology force regional co-packers toward exit or acquisition.
For Market Incumbents: To counter subscription commerce displacement of supermarket slotting economics, incumbents should acquire direct-to-consumer platform capabilities and deepen cold-chain density in California and Florida metropolitan corridors. Aseptic line capacity expansion in the southeastern manufacturing corridor offers defensive moat construction against ambient-format competitors. For New Entrants and Emerging Players: Digital-native subscription platforms represent the most penetrable channel architecture, with white space concentrated in green tea antioxidant positioning and chai flavor premiumization. Foodservice can penetration in Sun Belt convenience channels offers lowest barrier-to-entry go-to-market angle through co-packer relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized organic-certified co-packers in Georgia and North Carolina with underutilized aseptic capacity and established retailer relationships. Long-term viability centers on cold-chain infrastructure ownership and clean label certification assets. Practitioners should monitor municipal sugar tax expansion patterns and aluminum tariff announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | PepsiCo's Gatorade network enables ambient tea production at scale without preservative dependencies. |
| Direct-to-Consumer Platform Launch | Subscription models bypass supermarket slotting fees and capture lifetime value in California and Florida corridors. |
| USDA Organic Certification Investment | Premium private label programs require documented sourcing transparency through multi-tier tea extract supply chains. |
| Zero-Calorie Reformulation Program | FDA GRAS determinations for stevia and monk fruit systems address sugar tax exposure in Philadelphia and Seattle. |
| Foodservice Can Format Penetration | Single-serve aluminum packaging accelerates in convenience channels seeking portability without refrigeration dependency. |
Research Methodology
Independent corroboration across brand managers at multinational beverage conglomerates, category buyers at supermarket chains, and supply planners at southeastern co-packers underwrites the qualitative findings in this study. Primary interviews with channel sales heads and technical R&D directors combined with secondary validation from FDA 21 CFR 101 filings, USDA organic certification databases, Nielsen retail audit data, and state-level excise tax records anchored the analysis. Bottom-up volume triangulation across packaging formats and top-down value reconciliation against manufacturer revenue disclosures ensured consistency.
Rate-of-change decomposition across the analysis window separated volume drivers from price-mix effects in the modeling framework. Segmentation dimensions include product type, packaging format, flavor profile, and distribution channel, with regional climate velocity and regulatory tax exposure as industry-specific forecast inputs. CAGRs were derived from trend extrapolation adjusted for technology adoption curves and policy implementation timelines.
Caveats apply where municipal sugar tax expansion, aluminum tariff adjustments, or aseptic equipment supply constraints could materially shift the outlook. Forecasts reflect assumptions about FDA enforcement consistency and consumer sweetener acceptance patterns. Practitioners should monitor state legislative calendars and commodity aluminum price movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Instant Tea Premix Consumption Market
Tea
Matcha Tea Market
Tea
South America Tea Market
Tea
Bottled Tea Market
Tea
Smart Tea Maker Market
Tea
Probiotic Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
High Protein Tea Market
Tea
Asia-Pacific Organic Tea Market
Tea
Fermented Tea Market
Tea
Pyramid Tea Bags Market
Tea
Herbal Tea Market
Tea
White Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Bottled Milk Tea Market
Tea
Moringa Tea Market