
 Black Tea Base Bubble Tea Market | 2026-2036
Black Tea Base Bubble Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Black Tea Base Bubble Tea Market Insights
EU Green Deal packaging sustainability targets is hardening requirements for single-use cups and straws in European bubble tea outlets. Gong Cha leverages captive procurement of Assam and Ceylon estates to secure black tea supply consistency. CoCo Fresh Tea & Juice anchors its competitive stance through automated brewing systems that standardize extraction across franchise locations. Chatime differentiates by operating proprietary tapioca pearl manufacturing in Taiwan, insulating margins from starch price swings.
Black tea base bubble tea denotes a cold or hot beverage prepared by steeping oxidized Camellia sinensis leaves at 90–95°C, then combining the concentrate with tapioca starch pearls, sweeteners, and optional dairy or plant milk. The oxidation level, typically 80–100% for Assam or Darjeeling bases, determines tannin structure and astringency balance in the finished drink. Milk tea variants within the product type category command the widest margin pools due to dairy premiumization and customizable sweetness tiers. Distribution through cafés dominates volume, though online retail channels are capturing health-conscious consumers seeking low-sugar formulations with transparent ingredient labeling.
FDA oversees color additive and GRAS status for tapioca pearls entering the US market, while FSSAI in India mandates food-grade starch certification for bubble tea components sold through quick-service formats. Taiwan's Ministry of Health and Welfare enforces plastic straw phase-outs that push chains toward biodegradable alternatives, raising per-unit packaging costs. Stakeholders must monitor how divergent national packaging mandates reshape capital allocation between dine-in infrastructure and delivery-optimized formats.
Market Dynamics
Taiwan's Ministry of Health and Welfare plastic straw phase-outs are forcing café chains to absorb higher per-unit packaging costs while reconfiguring store layouts for dine-in versus delivery optimization. This regulatory pressure compounds with EU Green Deal packaging mandates to reshape capital allocation across the value chain.
Growth Catalysts
- EU Green Deal packaging sustainability targets:European bubble tea outlets face hardening requirements for single-use cups and straws, accelerating biodegradable material adoption across Germany, France, and the Netherlands.
- Specialty café chain expansion:Southeast Asian metropolitan clusters in Vietnam and Thailand are seeing flagship store rollouts that normalize black tea bubble tea as daily consumption occasions.
- Automated brewing standardization:Franchise operators deploy extraction systems that reduce variance between locations, enabling quality consistency without skilled tea masters at every unit.
Market Restraints
- Starch input volatility:Tapioca pearl production remains exposed to cassava price swings in Thailand and Vietnam, compressing margins for chains without captive manufacturing.
- Regulatory fragmentation:Divergent national packaging mandates between Taiwan's plastic phase-outs, EU Green Deal targets, and FDA color additive rules create compliance complexity for multi-country operators.
- Ready-to-drink substitution:Bottled tea beverages with extended shelf life threaten café-format bubble tea in convenience-oriented consumption occasions.
Strategic Opportunities
- Low-sugar formulation channels:Online retail platforms capture health-conscious consumers seeking transparent ingredient labeling beyond café reach.
- Assam and Ceylon estate captive procurement:Direct sourcing relationships insulate supply consistency against auction market volatility for oxidized Camellia sinensis bases.
- Proprietary pearl manufacturing:In-house starch processing capabilities eliminate third-party dependency and protect margin pools from commodity swings.
Industry Challenges
- Food-grade starch certification timelines:India's FSSAI mandates create extended approval windows for quick-service bubble tea component introductions.
- Additive disclosure compliance:Taiwan's tightened ready-to-drink beverage rules demand reformulated labeling systems and supply chain documentation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Tea Base Bubble Tea Market |
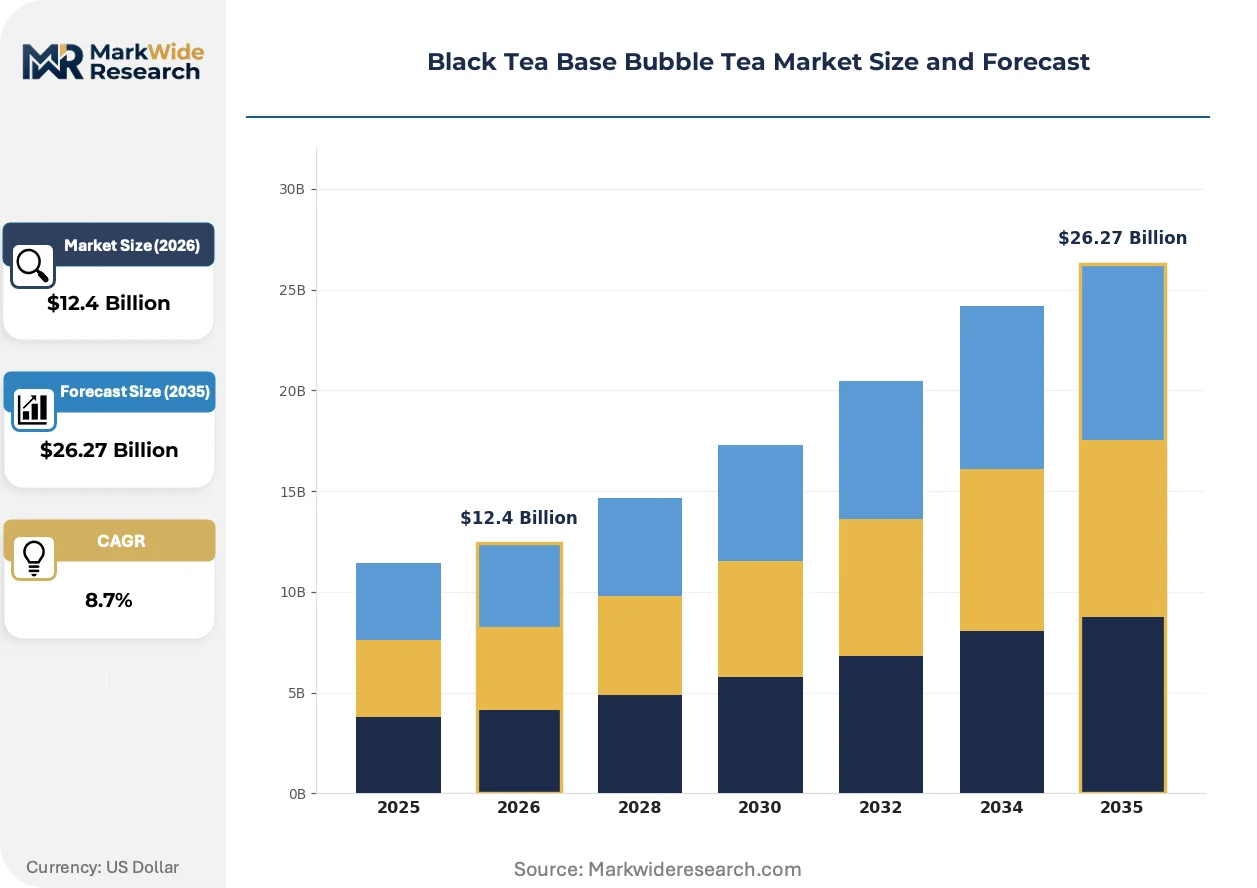
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Bubble Tea, Fruit-Infused Tea, Milk Tea, Herbal Blend Consumer Segment: Teens, Young Adults, Families, Health-Conscious Consumers Distribution Channel: Cafés, Restaurants, Online Retail, Supermarkets Flavor Profile: Sweet, Traditional, Creamy, Spiced |
| Companies Covered | Gong Cha, Chatime, CoCo Fresh Tea & Juice, Kung Fu Tea, Tiger Sugar, Sharetea, Xing Fu Tang, The Alley, Boba Guys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Tea Base Bubble Tea Market Trends and Innovations
Automation and regulatory pressure are converging to reshape how black tea bubble tea moves from raw leaf to finished cup. Three distinct vectors are altering competitive positioning across extraction technology, compliance architecture, and distribution economics.
Automated brewing systems are modularizing quality control across franchise networks. These platforms standardize 90–95°C extraction parameters for oxidized Camellia sinensis leaves, eliminating location-specific variance. Multi-unit operators in Taiwan and Vietnam are deploying these systems rapidly to reduce training overhead and customer complaint rates. The technology is modularizing the traditional tea-master role into replaceable hardware components that compress labor costs while tightening output consistency.
REACH and EU Green Deal packaging directives are hardening material specifications for European bubble tea outlets. Single-use cup and straw regulations now mandate biodegradable alternatives with traceable supply chains. Chains operating in Germany, France, and the Netherlands are reformulating procurement criteria and supplier qualification processes. The specialty café segment faces the steepest compliance burden as dine-in volume concentrates in markets with the most aggressive phase-out timelines.
Health-conscious buyers are rotating toward transparent ingredient disclosure as a purchase determinant. Low-sugar and dairy-alternative formulations are displacing traditional milk tea variants in online retail channels. This pattern concentrates in metropolitan Vietnam and Thailand where digital-native consumers cross-reference nutritional claims against regulatory databases. The shift is compressing formulation cycles as brands race to publish complete additive manifests ahead of competitors.
Black Tea Base Bubble Tea Market Segmentation
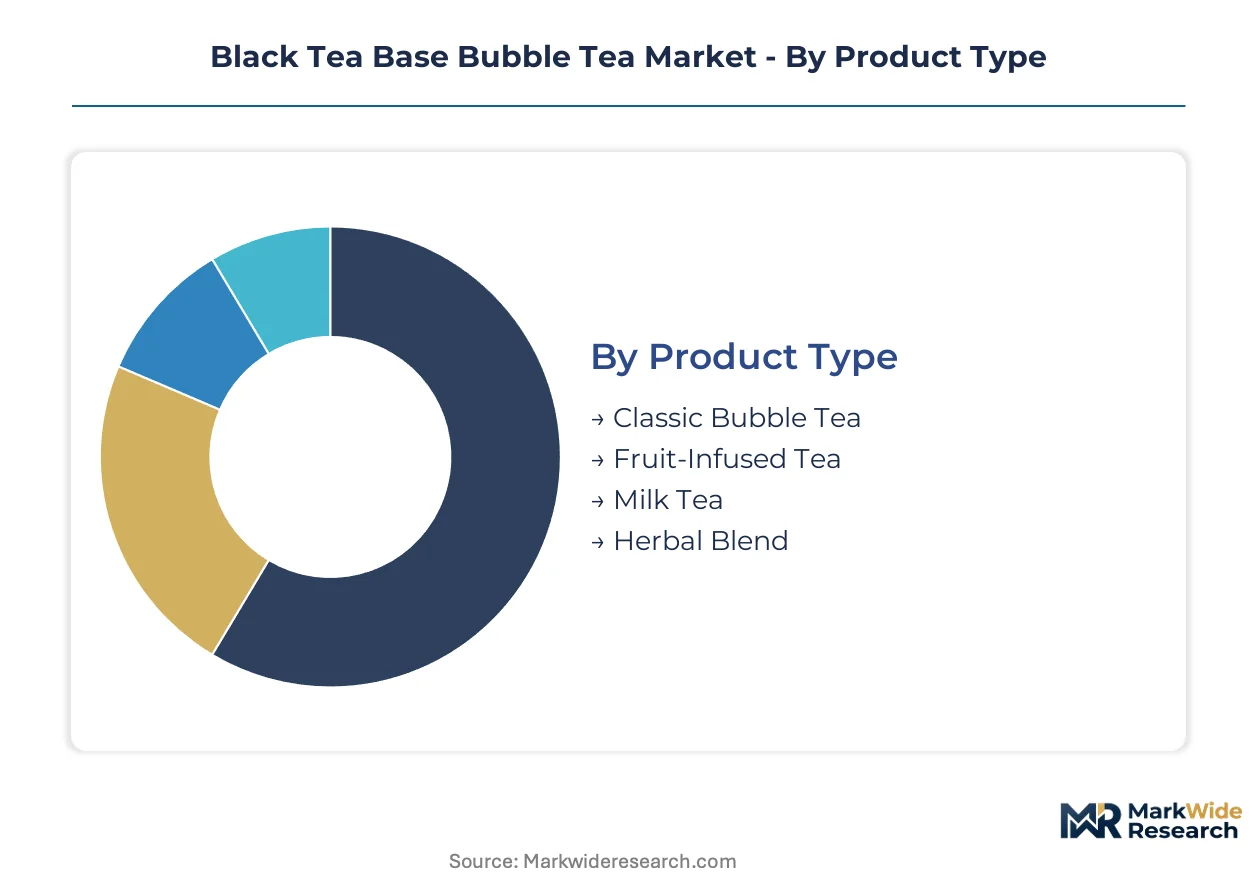
Black tea bubble tea segments fracture along preparation method, consumer occasion, and purchase context. Each axis commands distinct margin profiles and capital deployment requirements across extraction infrastructure and channel buildout.
Product Type:
Oxidation levels and dairy integration define the technical differentiation within this category.
- Milk Tea:Combines 80–100% oxidized Camellia sinensis concentrate with dairy or plant-based milk alternatives. Demand clusters in metropolitan Vietnam and Thailand where Gong Cha and CoCo Fresh Tea & Juice operate flagship locations, driven by premiumization of sweetness customization tiers.
- Classic Bubble Tea:Unadulterated black tea base with tapioca starch pearls and standard sweetener ratios. Serves as the volume foundation for franchise standardization efforts, with automated brewing systems from Taiwan normalizing extraction consistency across multi-unit deployments.
- Fruit-Infused Tea:Black tea concentrate blended with fruit purees or syrups, requiring extended cold-chain handling. Appeals to seasonal menu rotation strategies in Southeast Asian specialty cafés.
- Herbal Blend:Black tea base augmented with botanical additives such as chrysanthemum or osmanthus. Faces tighter disclosure requirements under Taiwan's Ministry of Health and Welfare additive rules.
Mature deployment sits with Classic Bubble Tea. Newer deployment is concentrated in Milk Tea variants with plant-based dairy alternatives.
Consumer Segment:
Purchase frequency and price sensitivity separate cohorts more sharply than demographic labels alone.
- Young Adults:Digital-native consumers aged 18–30 with elevated willingness to pay for transparent ingredient labeling and low-sugar formulations. Demand concentrates in online retail channels where nutritional database cross-referencing occurs before purchase.
- Health-Conscious Consumers:Buyers prioritizing additive disclosure and reduced glycemic load over traditional sweetness profiles. Steep expansion trajectory in metropolitan Thailand and Vietnam where regulatory transparency databases influence brand selection.
- Teens:Price-elastic cohort driving volume through social consumption occasions. Concentrated in dine-in café formats with limited packaging sustainability concern.
- Families:Multi-person purchase units seeking shareable formats and predictable flavor profiles. Serves weekend and holiday traffic spikes in suburban café locations.
Volume leadership rests with Teens. Margin expansion is climbing the fastest among Health-Conscious Consumers.
Distribution Channel:
Capital allocation diverges sharply between fixed-location infrastructure and logistics-dependent formats.
- Cafés:Dedicated preparation environments with automated brewing systems and proprietary pearl manufacturing capabilities. Absorb Taiwan's plastic straw phase-out costs through biodegradable packaging upgrades while reconfiguring layouts for delivery optimization.
- Online Retail:Direct-to-consumer platforms capturing health-conscious buyers seeking low-sugar formulations with complete additive manifests. Requires reformulated labeling systems compliant with divergent national disclosure mandates.
- Restaurants:Secondary menu placement in full-service and quick-service formats with limited customization infrastructure.
- Supermarkets:Ready-to-drink bottled formats threatening café-format consumption in convenience-oriented occasions, subject to Taiwan's tightened ready-to-drink beverage rules.
Established revenue concentration sits with Cafés. Channel investment is accelerating most rapidly in Online Retail.
Flavor Profile:
Sweetness intensity and texture modification determine formulation complexity and supply chain inputs.
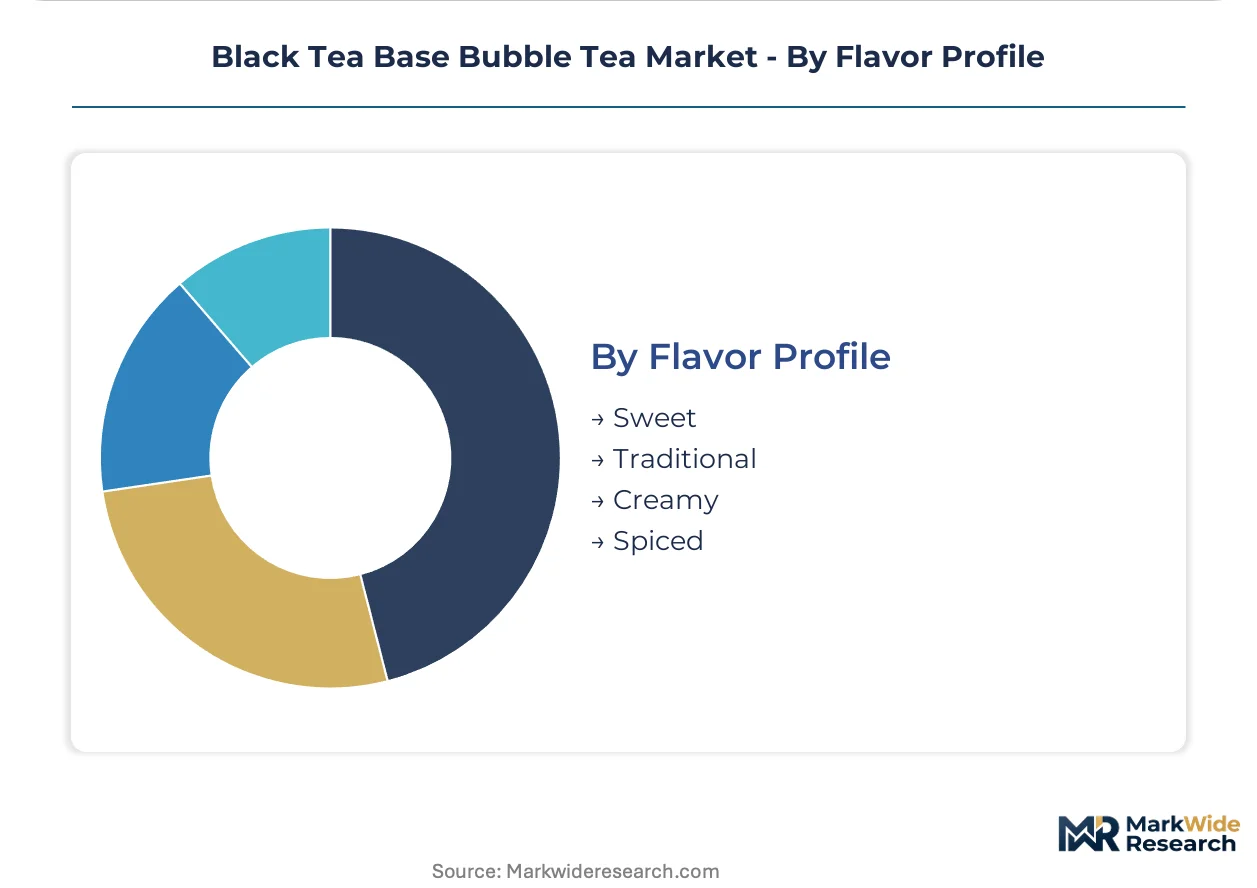
- Sweet:Elevated sucrose or fructose ratios with minimal bitterness masking. Dominates teen and family segments with standardized syrup procurement.
- Creamy:Dairy-forward mouthfeel requiring milk fat stability across temperature variants. Faces EU Green Deal packaging sustainability targets for cold-chain cup materials.
- Traditional:Astringency-forward profiles preserving tannin structure from Assam or Ceylon estate bases. Appeals to consumers with developed palate preferences in Taiwan and Vietnam.
- Spiced:Cinnamon, cardamom, or ginger additions requiring extended steeping protocols and specialized equipment cleaning cycles.
Volume scale concentrates in Sweet formulations. Premium pricing power is expanding most quickly in Creamy variants with plant-based alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei anchors global black tea bubble tea innovation through Gong Cha and Chatime headquarters operations that standardize extraction protocols across franchise networks.
Taiwan
Specialty café chains drive domestic consumption density in Taipei and Taichung. The Ministry of Health and Welfare enforces plastic straw phase-outs that push operators toward biodegradable packaging alternatives. Tainan's proprietary tapioca pearl manufacturing clusters supply captive starch processing for margin insulation.
Vietnam
Metropolitan Ho Chi Minh City and Hanoi concentrate flagship store rollouts from Gong Cha and CoCo Fresh Tea & Juice. Local food safety authorities mandate additive disclosure upgrades for ready-to-drink beverage formats. Da Nang's emerging café corridor attracts health-conscious consumers seeking low-sugar formulation transparency.
Thailand
Bangkok's Sukhumvit and Silom districts host dense specialty café penetration with automated brewing system deployments. The Thai Food and Drug Administration tightens food-grade starch certification timelines for quick-service bubble tea components. Chiang Mai's university-adjacent clusters normalize daily consumption occasions among young adult demographics.
United States
Coastal metropolitan markets in California and New York absorb FDA color additive oversight for tapioca pearl imports. The Los Angeles and San Francisco Bay Area corridors concentrate Boba Guys and Kung Fu Tea locations with plant-based milk alternative menus. Texas metro expansion accelerates through standardized franchise extraction protocols.
Germany
Berlin and Munich specialty cafés face EU Green Deal packaging sustainability mandates for single-use cups and straws. ECHA REACH directives harden biodegradable material traceability requirements. Hamburg's port logistics clusters facilitate Assam and Ceylon estate tea concentrate imports for captive procurement networks.
Black Tea Base Bubble Tea Market Competitive Landscape
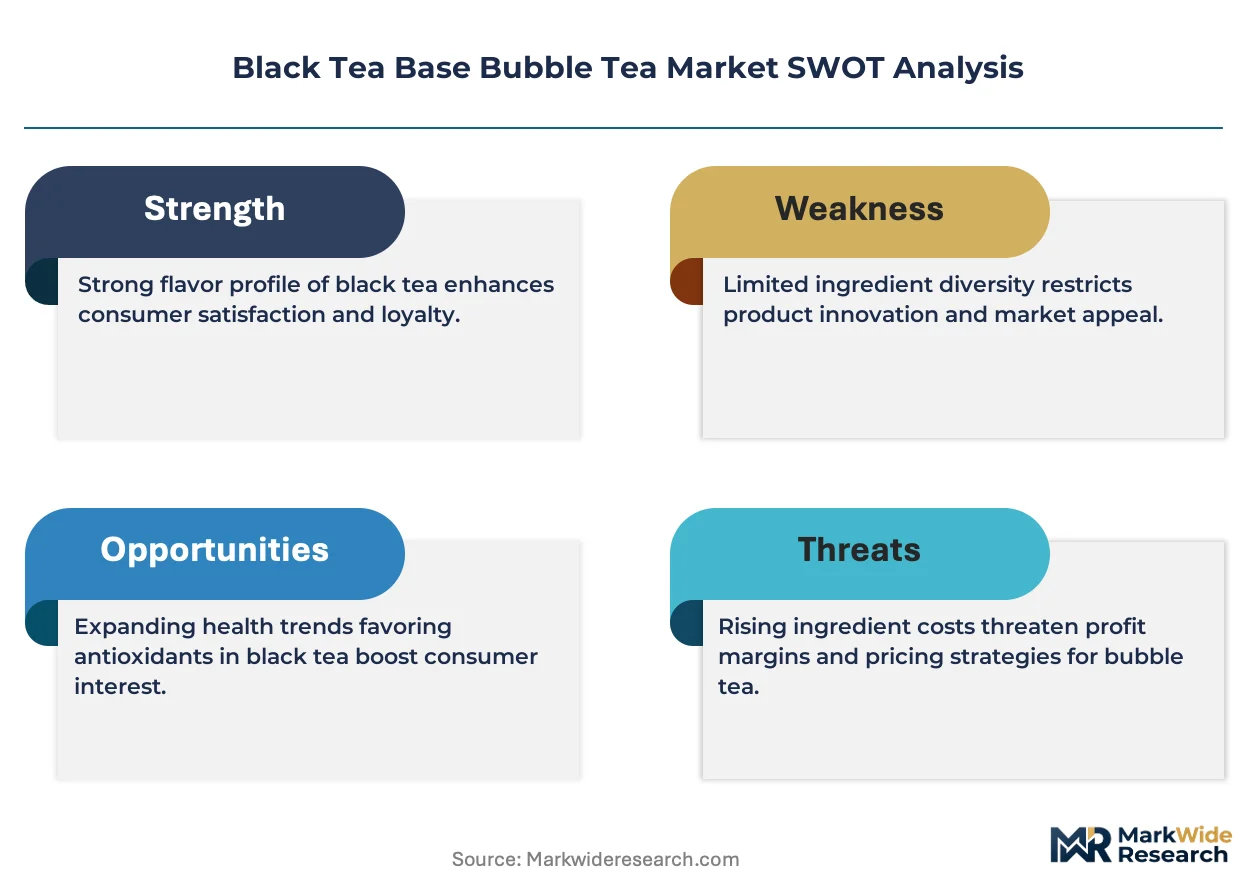
Premium-margin players sit above commodity-margin players across supply chain control and extraction technology deployment. The market structures around three tiers: estate-captive sourcing specialists with proprietary pearl manufacturing, automated brewing system deployers optimizing franchise consistency, and format-agnostic retailers dependent on third-party starch suppliers. Strategic moves concentrate on backward integration into tapioca processing and geographic licensing partnerships for menu standardization.
Within the estate-captive tier, Gong Cha exemplifies direct Assam and Ceylon sourcing relationships that insulate supply consistency. Chatime anchors proprietary manufacturing capabilities in Taiwan that eliminate third-party pearl dependency. CoCo Fresh Tea & Juice represents automated extraction standardization across multi-unit deployments. These three occupy distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Gong Cha |
| Chatime |
| CoCo Fresh Tea & Juice |
| Kung Fu Tea |
| Tiger Sugar |
| Sharetea |
| Xing Fu Tang |
| The Alley |
| Boba Guys |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal packaging mandates for biodegradable cups and straws are forcing European specialty cafés to absorb 15-25% packaging cost inflation, compressing operating margins and accelerating supplier consolidation toward certified material providers with traceable supply chains.
Pricing Analysis
Value-based pricing anchors on extraction consistency and supply security rather than commodity tea grades. Three-tier pricing separates estate-captive Assam and Ceylon bases from auction-sourced alternatives and economy-grade concentrates. Price differentiation rests on oxidation certification and automated brewing compatibility. Pricing pressure stems from cassava starch volatility in Thailand and Vietnam, squeezing chains without proprietary pearl manufacturing. Teens exhibit highest price sensitivity, while health-conscious consumers in metropolitan Vietnam and Thailand accept premiums for transparent additive disclosure.
Supply Chain Analysis
Freight cost inflation on cold-chain tapioca pearl shipments from Taiwan and Vietnam is reshaping procurement geography toward regional starch processing hubs. Supply concentrates in Taiwan for proprietary pearl manufacturing, Vietnam for cassava cultivation, and India for food-grade starch certification under FSSAI timelines. Raw material dependencies span oxidized Camellia sinensis leaves, food-grade tapioca starch, and biodegradable packaging substrates. Single-source vulnerability sits with Thailand's cassava price swings. Distribution runs through captive café networks with automated brewing standardization, supplemented by direct-to-consumer online retail for low-sugar formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive procurement of Assam and Ceylon estates constrains supply expansion, propping pricing power for backward-integrated operators while exposing dependent chains to auction market volatility.
For Market Incumbents: Deepen proprietary tapioca pearl manufacturing capabilities in Taiwan to eliminate third-party starch dependency and insulate margins from Thai cassava price swings. Fortify automated brewing system deployments across Southeast Asian franchise networks to standardize extraction consistency without skilled tea masters at every unit. Prioritize EU Green Deal packaging certification for biodegradable cup and straw suppliers to defend European market access against compliance-disqualified competitors. For New Entrants and Emerging Players: Enter via online retail channels targeting health-conscious consumers in metropolitan Thailand and Vietnam seeking low-sugar formulations with complete additive manifests. Exploit underdeveloped proprietary pearl manufacturing capacity in secondary Vietnamese cities outside Ho Chi Minh City and Hanoi. Position around transparent ingredient labeling as the primary go-to-market wedge against established café chains with opaque supply chains. For Investors and Strategic Acquirers: The window for entry favors estate-captive sourcing specialists with backward-integrated starch processing capabilities. Long-term viability hinges on supply security rather than format expansion, given constrained Assam and Ceylon auction volumes. Target acquisition archetypes combine proprietary pearl manufacturing with automated brewing technology deployment. Monitor FSSAI food-grade starch certification timeline extensions in India as the inflection signal for supply chain restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Pearl Manufacturing | Eliminates Thai cassava price exposure and protects margin pools from commodity volatility. |
| Automated Brewing Deployment | Standardizes 90–95°C extraction parameters across Gong Cha and CoCo Fresh Tea & Juice franchise networks. |
| Estate-Captive Procurement | Secures Assam and Ceylon supply consistency against auction market volatility for oxidized Camellia sinensis bases. |
| Biodegradable Packaging Transition | Complies with EU Green Deal mandates and Taiwan's Ministry of Health and Welfare plastic straw phase-outs. |
| Online Retail Channel Expansion | Captures health-conscious consumers seeking low-sugar formulations with transparent additive labeling beyond café reach. |
Research Methodology
Document review covered Taiwan Food and Drug Administration filings, EU ECHA REACH substance databases, FSSAI starch certification records, and trade customs data for tapioca derivatives, complemented by interviews with specialty café chain procurement directors, automated brewing system manufacturers, Assam and Ceylon estate operations managers, biodegradable packaging suppliers, and quick-service beverage regulatory consultants. Secondary validation drew from Taiwan Ministry of Health and Welfare additive disclosure guidelines, EU Green Deal packaging directives, and FDA color additive GRAS determinations. Bottom-up volume modeling triangulated against top-down value projections across café, online retail, restaurant, and supermarket channels.
Segmented outputs across product type, consumer demographic, distribution channel, and flavor profile dimensions fed into analytical frameworks spanning the projection horizon. CAGRs derived from regression analysis of historical consumption patterns, regulatory implementation timelines, and channel shift trajectories. Industry-specific inputs included automated brewing system deployment rates, EU biodegradable packaging compliance deadlines, and FSSAI certification queue lengths for quick-service bubble tea components.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended FSSAI approval delays, abrupt EU packaging mandate acceleration, or Thai cassava harvest disruptions. Forecasts reflect documented assumptions about regulatory implementation pacing and supply chain restructuring velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Smart Tea Set Market
Tea
Probiotic Tea Market
Tea
Instant Tea Market
Tea
Europe Green Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Bottled Milk Tea Market
Tea
US Ready to Drink Tea Market
Tea
Tea Infuser Market
Tea
Light-Fermented Tea Market
Tea
China Tea Market
Tea
Matcha Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Moringa Tea Market
Tea
Matcha Tea Market
Tea
Oolong Tea Market
Tea
APAC RTD Tea Market