
 Slimming Tea Market | 2026-2036
Slimming Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Slimming Tea Market Intelligence
The wellness retail sector is repositioning slimming tea as a functional beverage rather than a commodity. ITO EN leverages its Japanese green tea expertise to anchor premium positioning in East Asian markets. Nestlé competes through broad distribution networks that span supermarkets and online retail channels. Unilever differentiates via brand portfolio depth across herbal and infused tea varieties.
Slimming tea comprises botanical blends formulated with catechins, polyphenols, and thermogenic herbs designed to support metabolic function and weight management. Manufacturing involves controlled oxidation levels, standardized extraction of active compounds, and moisture content stabilization below six percent to preserve efficacy. Green tea and herbal tea categories lead volume due to established consumer familiarity and documented polyphenol content. Ready-to-drink formats represent the fastest-growing form segment as convenience-seeking buyers shift from loose leaf preparation. Tea bags retain the largest margin pool through premium single-origin positioning and subscription channel economics.
FDA dietary supplement regulations and EFSA health claim frameworks enforce strict substantiation requirements on weight management assertions, compelling reformulation and label adjustments. China's SAMR and national food safety standards govern maximum allowable active compound concentrations and prohibit undeclared pharmaceutical adulterants. Stakeholders must monitor evolving enforcement patterns across these jurisdictions to anticipate compliance cost trajectories and market access barriers.
Market Dynamics
EFSA health claim verification and FDA dietary supplement labeling rules are compressing formulation freedom and forcing manufacturers to rebuild substantiation pipelines from clinical trial data rather than traditional use claims.
Growth Catalysts
- Green tea catechin standardization:Advances in epigallocatechin gallate extraction and stabilization are unlocking consistent potency claims that satisfy EFSA substantiation thresholds for European market entry.
- China's dual carbon goals:National emissions targets are accelerating organic cultivation certification across Yunnan and Fujian provinces, reducing synthetic input residues that trigger SAMR import scrutiny.
- Ready-to-drink convenience formats:Urban Chinese fitness consumers are displacing loose-leaf preparation with ambient-stable bottled formulations, expanding addressable occasions beyond home brewing.
Market Restraints
- Camellia sinensis supply concentration:Premium leaf sourcing clusters in China's mountainous provinces, exposing blenders to climate-driven harvest volatility and quality inconsistency.
- Active compound degradation:Polyphenol oxidation during extended distribution cycles limits shelf-life claims and constrains export radius from production centers.
- Adulterant detection protocols:SAMR's expanded pharmaceutical screening requirements are extending batch release timelines and raising compliance overhead for botanical ingredient suppliers.
Strategic Opportunities
- Subscription channel economics:Direct-to-consumer replenishment models in the United States are capturing recurring revenue pools that supermarket distribution cannot access.
- Functional beverage convergence:Collagen-infused and adaptogenic hybrid formulations are attracting wellness buyers who previously rejected single-purpose weight management positioning.
- Japan's Foods with Function Claims system:PMDA's streamlined approval pathway for documented ingredients is enabling faster market entry than EFSA's centralized authorization process.
Industry Challenges
- Clinical substantiation talent scarcity:Qualified investigators capable of designing EFSA-compliant weight management trials command premium fees that strain mid-tier brand R&D budgets.
- Cross-border formulation harmonization:Divergent maximum catechin limits between FDA guidance and China's GB standards force parallel SKU development rather than unified global products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slimming Tea Market |
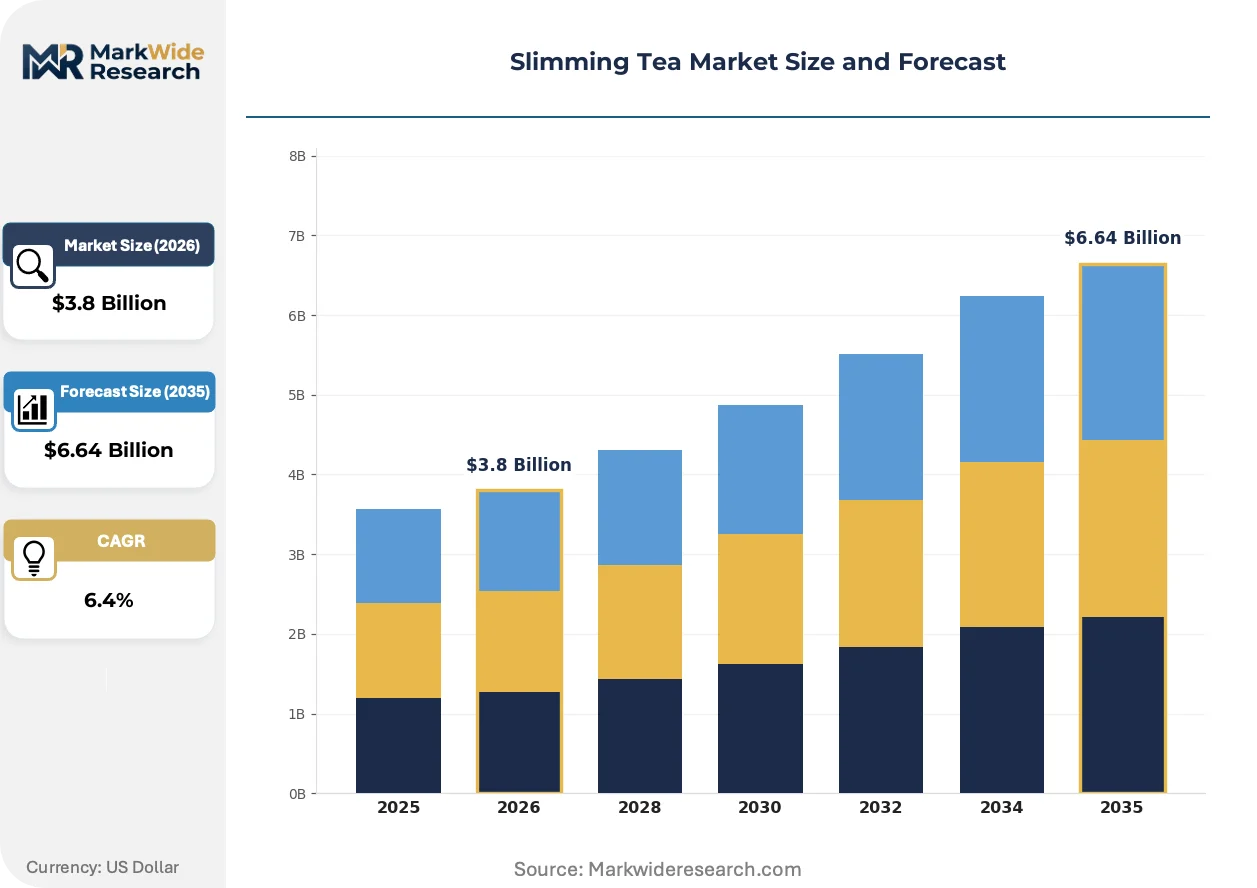
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Tea, Green Tea, Black Tea, Infused Tea Form: Loose Leaf, Tea Bags, Powder, Ready-to-Drink End User: Health-Conscious Individuals, Fitness Enthusiasts, Weight Watchers, Diet Plan Adopters Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores |
| Companies Covered | ITO EN, The Hain Celestial Group, Nestlé, Dilmah Ceylon Tea Company, Associated British Foods, Unilever, Celestial Seasonings, Tata Global Beverages, Tata Consumer Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slimming Tea Market Strategic Shifts & Innovations
Cold-brew extraction protocols and bioavailability enhancement technologies are displacing conventional hot-infusion manufacturing, enabling manufacturers to deliver higher functional compound loads in ready-to-drink formats.
Nano-encapsulation of green tea catechins using liposomal delivery systems is rewriting absorption benchmarks for functional beverages. Sports nutrition buyers in the United States and Japan are adopting these enhanced formulations at premium price multiples. This technology is compressing the efficacy gap between beverage and supplement categories, forcing traditional tea brands to acquire delivery-system capabilities or concede the performance-positioned segment.
EFSA's 2023 clarification on botanical health claim substantiation is tightening evidentiary requirements for weight management assertions. Manufacturers must now submit human intervention studies rather than relying on epidemiological meta-analyses. European blenders are responding by reformulating toward general wellness positioning or withdrawing specific slimming claims entirely.
Chinese fitness enthusiasts are consolidating purchases through Douyin and Xiaohongshu live-commerce channels, bypassing traditional retail intermediaries. This disintermediation is transferring margin from distributors to content creators and platform algorithms. Domestic brands with in-house influencer networks are capturing disproportionate share of emerging consumer cohorts in tier-one cities.
Slimming Tea Market Segmentation
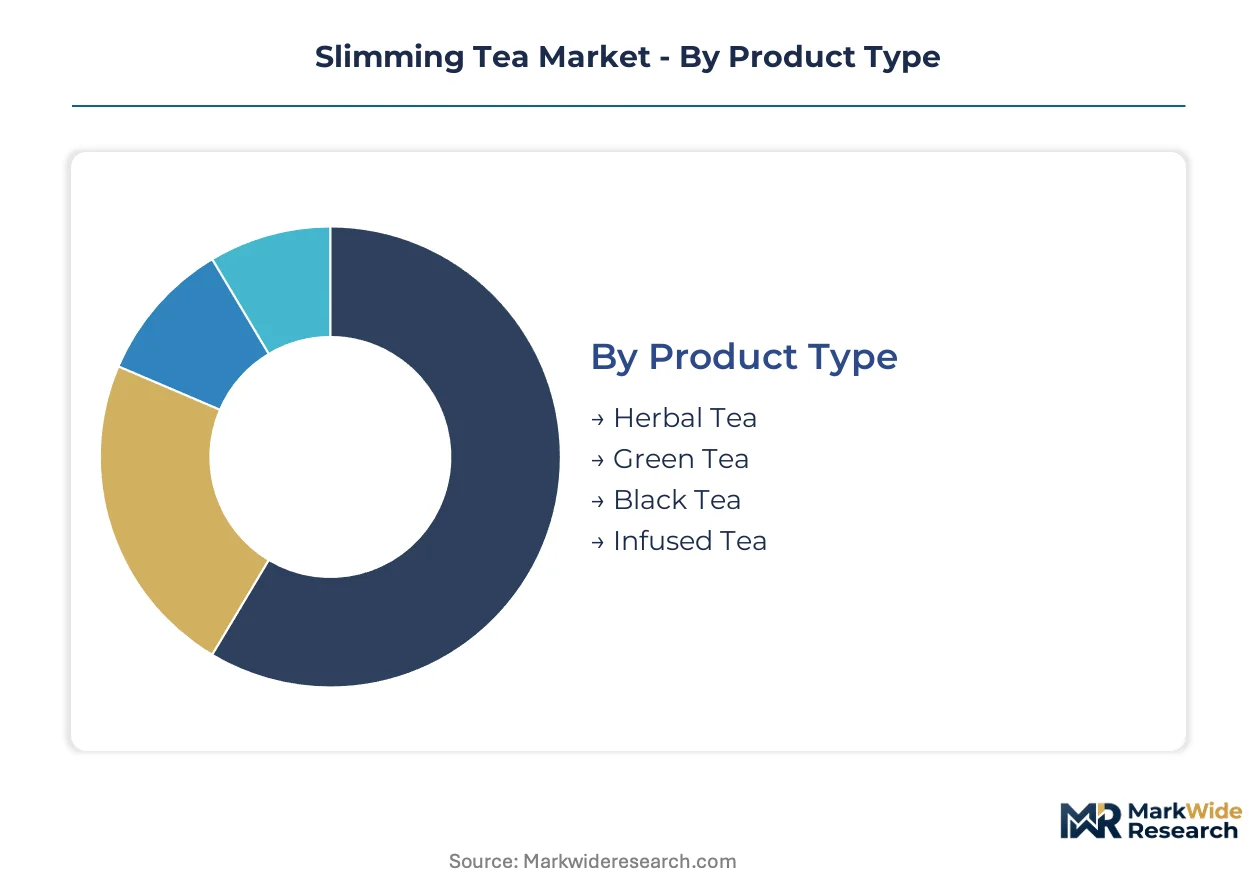
Slimming tea manufacturers navigate a fragmented demand landscape where formulation specificity, consumption occasion, and channel economics create distinct value pools. Understanding segment-level drivers enables targeted resource allocation across R&D, procurement, and distribution investments.
Product Type:
Customization intensity spans from standardized commodity blends to proprietary formulations requiring botanical sourcing relationships and extraction IP.
- Herbal Tea:Formulations deploy thermogenic botanicals including senna, dandelion root, and garcinia cambogia with standardized active compound profiles. Traditional medicine practitioners in China and Ayurvedic wellness centers in India drive concentrated procurement of multi-herb digestive blends.
- Green Tea:Camellia sinensis leaves undergo minimal oxidation to preserve epigallocatechin gallate concentrations. Japanese fitness consumers and South Korean beauty-positioned buyers anchor demand for ceremonial-grade matcha and shade-grown sencha variants.
- Black Tea:Fully oxidized leaf processing yields theaflavin-rich compositions with distinct tannin structures. British and Russian traditional tea markets sustain volume for breakfast-style slimming-positioned blends.
- Infused Tea:Fruit, flower, and spice inclusions create differentiated sensory profiles without caffeine dominance. German and French organic retail channels favor hibiscus-rosehip combinations for evening consumption occasions.
Leading the category by volume: Green Tea. Expanding most quickly: Herbal Tea.
Form:
Processing sophistication determines shelf stability, bioavailability claims, and margin capture across preparation modalities.
- Loose Leaf:Whole or broken leaf formats preserve volatile oil integrity and enable custom blending ratios. Premium positioning in Chinese tier-one cities and Japanese department store channels rewards provenance documentation and harvest date transparency.
- Tea Bags:Heat-sealed filter paper or silk pyramid constructions standardize dosing convenience. Subscription commerce in the United States and United Kingdom monetizes single-origin assortments through recurring replenishment economics.
- Powder:Micronized leaf or extract concentrates dissolve for instant beverage preparation. South Korean café culture and Australian functional beverage startups adopt matcha and green tea extract powders for latte formulations.
- Ready-to-Drink:Aseptically processed bottled formulations with pH stabilization and light-blocking packaging. Convenience-seeking urban Chinese fitness consumers displace home brewing with ambient-stable retail formats.
Dominating shelf space: Tea Bags. Climbing the fastest: Ready-to-Drink.
End User:
Behavioral segmentation tracks motivation intensity, regimen adherence, and price sensitivity across wellness commitment levels.
- Health-Conscious Individuals:Broad wellness seekers integrating tea into preventive lifestyle routines without strict caloric targets. German and Scandinavian organic retail penetration sustains steady replenishment cycles.
- Fitness Enthusiasts:Gym-attending consumers prioritizing thermogenic and hydration-supporting formulations. Protein-aligned brands in the United States and Japan bundle slimming tea with sports nutrition portfolios.
- Weight Watchers:Calorie-tracking consumers seeking meal-replacement or appetite-suppression support. British and Australian commercial diet program participants drive seasonal purchasing around New Year resolution cycles.
- Diet Plan Adopters:Structured regimen followers including ketogenic, intermittent fasting, and medically supervised protocols. Clinician-recommended positioning in French and Italian pharmacy channels commands premium pricing.
Capturing largest user base: Health-Conscious Individuals. Gaining share fastest: Fitness Enthusiasts.
Distribution Channel:
Channel selection determines margin structure, consumer data access, and regulatory exposure across retail formats.
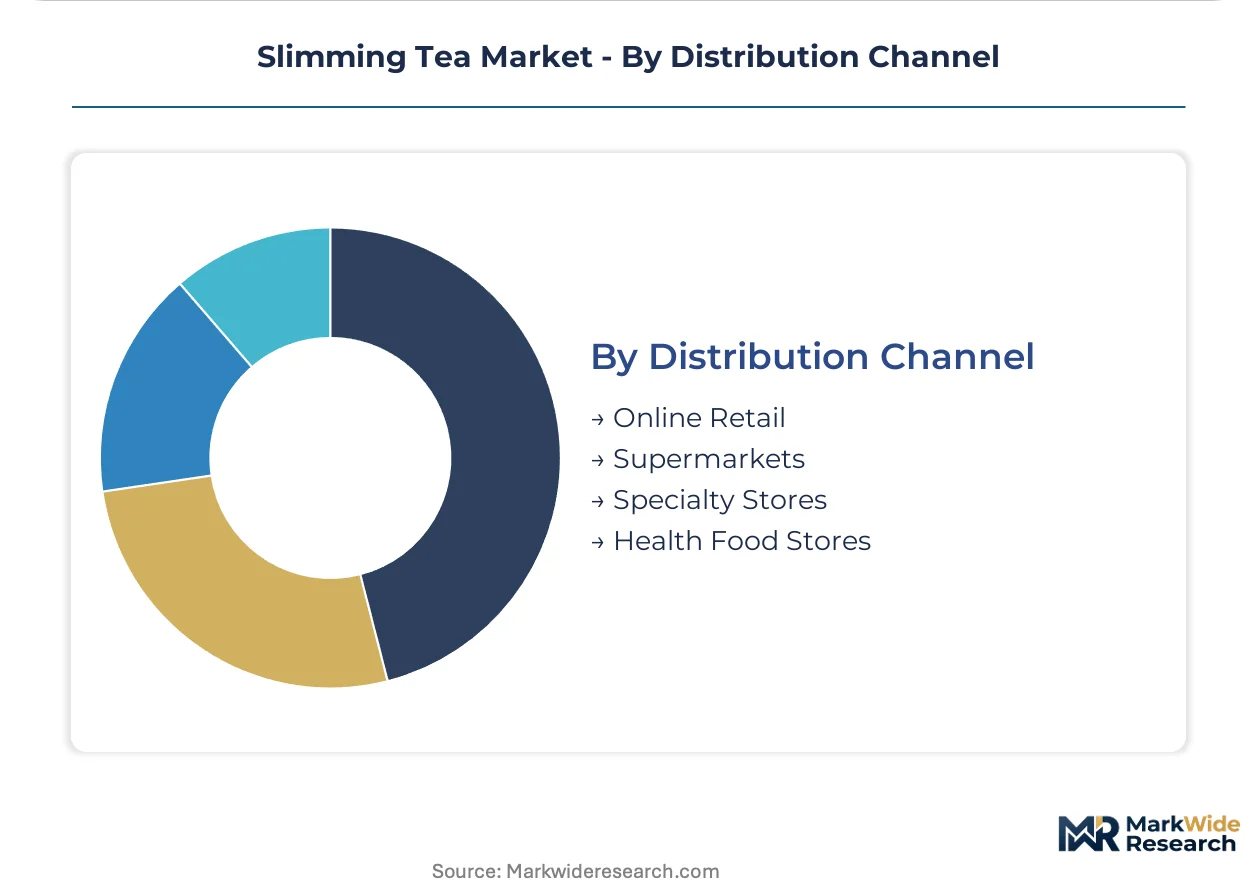
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription mechanics and influencer attribution. Douyin live-commerce in China and Amazon Subscribe & Save in the United States concentrate growth investment.
- Supermarkets:Mass-market shelf placement with promotional dependency and private label competition. British and German grocery consolidation limits brand count to top-performing SKUs.
- Specialty Stores:Curated assortments with staff consultation and tasting infrastructure. Japanese depachika basement food halls and Chinese shopping mall tea boutiques sustain experiential positioning.
- Health Food Stores:Natural product retailers with certified organic and non-GMO verification requirements. United States Whole Foods and Sprouts Networks gatekeep entry through ingredient transparency audits.
Generating highest transaction volume: Supermarkets. Steepest expansion trajectory: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yunnan's cross-border e-commerce pilot zones concentrate slimming tea export licensing and duty-free processing infrastructure. Chinese provincial authorities coordinate organic certification acceleration with Fujian's low-carbon cultivation mandates. European and North American import compliance requirements reshape regional production priorities.
China
Fujian and Yunnan provinces anchor Camellia sinensis cultivation for premium green tea extracts. SAMR's pharmaceutical adulterant screening protocols extend batch release timelines for export-bound formulations. Hangzhou and Shanghai live-commerce studios disintermediate traditional distribution through Douyin and Xiaohongshu influencer networks.
United States
Fitness enthusiasts and weight watchers drive subscription commerce through Amazon Subscribe & Save and direct-to-consumer replenishment models. FDA dietary supplement labeling rules compel clinical substantiation for weight management claims rather than traditional use assertions. California functional beverage startups and Colorado-based organic tea blenders concentrate product development and influencer marketing operations.
Japan
PMDA's Foods with Function Claims system enables faster market entry for documented catechin formulations than EFSA's centralized authorization process. Tokyo and Osaka metropolitan fitness consumers anchor ceremonial-grade matcha and shade-grown sencha demand. Kyoto-based tea houses and Nagoya extraction facilities concentrate premium processing and bioavailability enhancement R&D.
Germany
EFSA health claim verification requirements enforce strict substantiation thresholds on botanical weight management assertions. Berlin and Hamburg organic retail channels sustain hibiscus-rosehip infused tea positioning for evening wellness occasions. Bavarian and Baden-Württemberg botanical suppliers coordinate standardized active compound extraction for European blender networks.
United Kingdom
Commercial diet program participants drive seasonal purchasing cycles around New Year resolution periods. British grocery consolidation limits brand shelf presence to top-performing SKUs in Tesco and Sainsbury's networks. London specialty tea boutiques and Manchester-based subscription commerce operations sustain premium single-origin and provenance-documented positioning.
Slimming Tea Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The market structures around three tiers: multinational beverage conglomerates with broad distribution networks, regional tea specialists with provenance expertise, and functional beverage startups with delivery-system technology. Strategic moves concentrate on portfolio diversification toward hybrid wellness formulations and geographic expansion through regulatory pathway arbitrage.
Within the Japanese green tea specialist tier, ITO EN exemplifies premium positioning anchored in East Asian market expertise. Among multinational beverage conglomerates, Nestlé and Unilever occupy positions spanning supermarket and online retail channel access. Tata Consumer Products Limited represents the integrated origin-to-brand archetype with cultivation and blending capabilities concentrated in Indian and Sri Lankan sourcing regions.
| Leading Market Players |
|---|
| ITO EN |
| The Hain Celestial Group |
| Nestlé |
| Dilmah Ceylon Tea Company |
| Associated British Foods |
| Unilever |
| Celestial Seasonings |
| Tata Global Beverages |
| Tata Consumer Products Limited |
| Others |
Cost & Logistics Intelligence
Cold-brew extraction and nano-encapsulation technologies are compressing unit economics while concentrating premium production capabilities among Japanese and South Korean facilities with proprietary liposomal delivery IP. This technological bifurcation simultaneously raises entry costs for standardized formats and extends margin capture for bioavailability-enhanced formulations.
Pricing Analysis
Short-lead-time premiums command significant markups in ceremonial-grade matcha and single-origin Fujian green tea segments, while spot inventory of commodity-grade Camellia sinensis trades at discounts to contract offtake. Three-tier pricing structure across premium, standard, and economy levels separates subscription-channel single-origin SKUs from mass-market supermarket blends and bulk ingredient supply. Pricing pressure stems from SAMR compliance cost pass-through and extended batch release timelines. Health-Conscious Individuals exhibit highest price sensitivity, while Diet Plan Adopters in French pharmacy channels show lowest elasticity.
Supply Chain Analysis
Organic certification and dual carbon compliance gating restricts supplier pools to Yunnan and Fujian provinces meeting MEE emissions standards and SAMR residue limits. Raw material flows draw from shade-grown tea gardens, standardized catechin extract facilities, and aseptic bottling infrastructure. Single-source vulnerability concentrates in premium leaf procurement from China's mountainous provinces exposed to climate volatility. Distribution runs through Douyin live-commerce studios and Amazon Subscribe & Save replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slimming tea supply remains structurally constrained by qualified organic acreage and clinical substantiation talent scarcity, with premium pricing sustained by capacity bottlenecks in EFSA-compliant formulation development.
For Market Incumbents: Acquire extraction technology IP and clinical trial capabilities to defend against functional beverage startups with nano-encapsulation advantages. Consolidate backward integration into Yunnan organic cultivation to secure SAMR-compliant supply buffers against climate-driven harvest volatility. For New Entrants and Emerging Players: Enter via collagen-adaptogenic hybrid formulations targeting wellness buyers who reject single-purpose weight management positioning. White space concentrates in Japanese Foods with Function Claims pathway and US subscription channel economics with influencer attribution models. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational beverage conglomerates seeking delivery-system capabilities and East Asian market access. Long-term viability favors targets with PMDA or EFSA substantiation pipelines and captive organic supply. The signal to watch is SAMR enforcement intensity on pharmaceutical adulterant screening protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Bioavailability Enhancement Acquisition | Liposomal catechin delivery systems compress the efficacy gap between beverage and supplement categories. |
| Organic Certification Acceleration | Dual carbon compliance in Fujian and Yunnan reduces synthetic residue triggers for SAMR import scrutiny. |
| Subscription Channel Launch | Direct-to-consumer replenishment captures recurring revenue pools inaccessible through supermarket distribution. |
| Functional Hybrid Formulation | Collagen-infused positioning attracts wellness buyers beyond traditional weight management segments. |
| Regulatory Pathway Arbitrage | PMDA's streamlined Foods with Function Claims system enables faster market entry than EFSA authorization. |
Research Approach
Multi-period observation of catechin standardization protocols, EFSA substantiation timelines, and SAMR enforcement patterns anchored the trend analysis, supplemented by interviews with tea processing facility managers, organic certification auditors, live-commerce platform operators, and functional beverage R&D directors. Secondary validation drew from FDA dietary supplement guidance documents, EFSA botanical health claim registers, Chinese customs trade data, and Nielsen retail audit records. Bottom-up volume builds across product type, form, end user, and distribution channel segments triangulated against top-down market sizing.
Input-output matrices modeled Camellia sinensis harvest volumes, extraction yield rates, and channel-specific pricing elasticities across the analysis window. Segmentation dimensions included product type, form, end user motivation intensity, and distribution channel economics. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory compliance cost inflections and technology adoption curves in nano-encapsulation and cold-brew processing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR pharmaceutical screening escalation or EFSA evidentiary requirement tightening. Model assumptions reflect documented clinical trial pipelines, organic certification expansion rates, and platform algorithm shifts in Chinese live-commerce. A model refresh is warranted upon material change in PMDA Foods with Function Claims approval velocity or climate-driven harvest disruption in Yunnan province.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Tea Subscription Market
Tea
Smart Tea Maker Market
Tea
Bottled Milk Tea Market
Tea
Black Tea Extracts Market
Tea
RTD Tea Market
Tea
Herbal Tea Market
Tea
South America Tea Market
Tea
Oolong Tea Market
Tea
Global Catechin Market
Tea
High Protein Tea Market
Tea
Butterfly Pea Flower Tea Market
Tea
Black Tea Base Bubble Tea Market
Tea
US Ready to Drink Tea Market
Tea
Instant Tea Market
Tea
Rooibos Tea Market
Tea
Africa Tea Market