
 Green Tea Market | 2026-2036
Green Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Market Intelligence
The shift toward certified organic and single-origin green tea is redrawing the competitive landscape for premium brands. Ito En Ltd specializes in high-grade Japanese teas like Matcha and Sencha, targeting discerning consumers. Unilever Plc leverages its vast global distribution to push its Lipton and Pukka Herbs brands into mainstream retail channels. Tata Consumer Food Limited sustains its market position through extensive control over tea plantations in India.
Green tea is an unoxidized beverage derived from the leaves of the Camellia sinensis plant. Its characteristic green color and flavor profile are preserved through processes like steaming or pan-firing, which halt enzymatic oxidation and maintain high levels of polyphenols, particularly EGCG. While ready-to-drink (RTD) formats represent the fastest-growing product type by volume, traditional loose-leaf teas command higher price points. The beverage application remains the largest segment, though use in cosmetics and nutraceuticals for antioxidant properties is creating new value streams.
Market access and product labeling are shaped by varied international regulations. In the United States, the FDA scrutinizes health claims, while the EFSA in Europe maintains a strict list of approved nutritional and health statements. Similarly, the FSSAI in India sets standards for safety and quality, including limits on contaminants. Navigating these divergent regulatory environments for health-related marketing will be a critical determinant of brand success.
Market Dynamics
The fundamental market structure is being reshaped by the increasing demand from the nutraceutical sector for high-catechin green tea extracts. This shift elevates green tea from a traditional beverage to a functional ingredient, influencing cultivation, processing, and pricing models.
Growth Catalysts
- Regulatory Frameworks:Japan's FOSHU (Foods for Specified Health Uses) system provides a clear pathway for brands to make scientifically-backed health claims, creating a premium segment for clinically validated green tea products.
- Nutraceutical Demand:The global nutraceutical industry's focus on antioxidants drives volume for high-potency green tea extracts, particularly those rich in epigallocatechin gallate (EGCG), for use in dietary supplements and functional foods.
- Consumer Health Consciousness:Concentrated in the United States, a growing consumer base actively seeks functional beverages for preventive health, supporting robust sales of both ready-to-drink (RTD) green teas and premium loose-leaf varieties.
Market Restraints
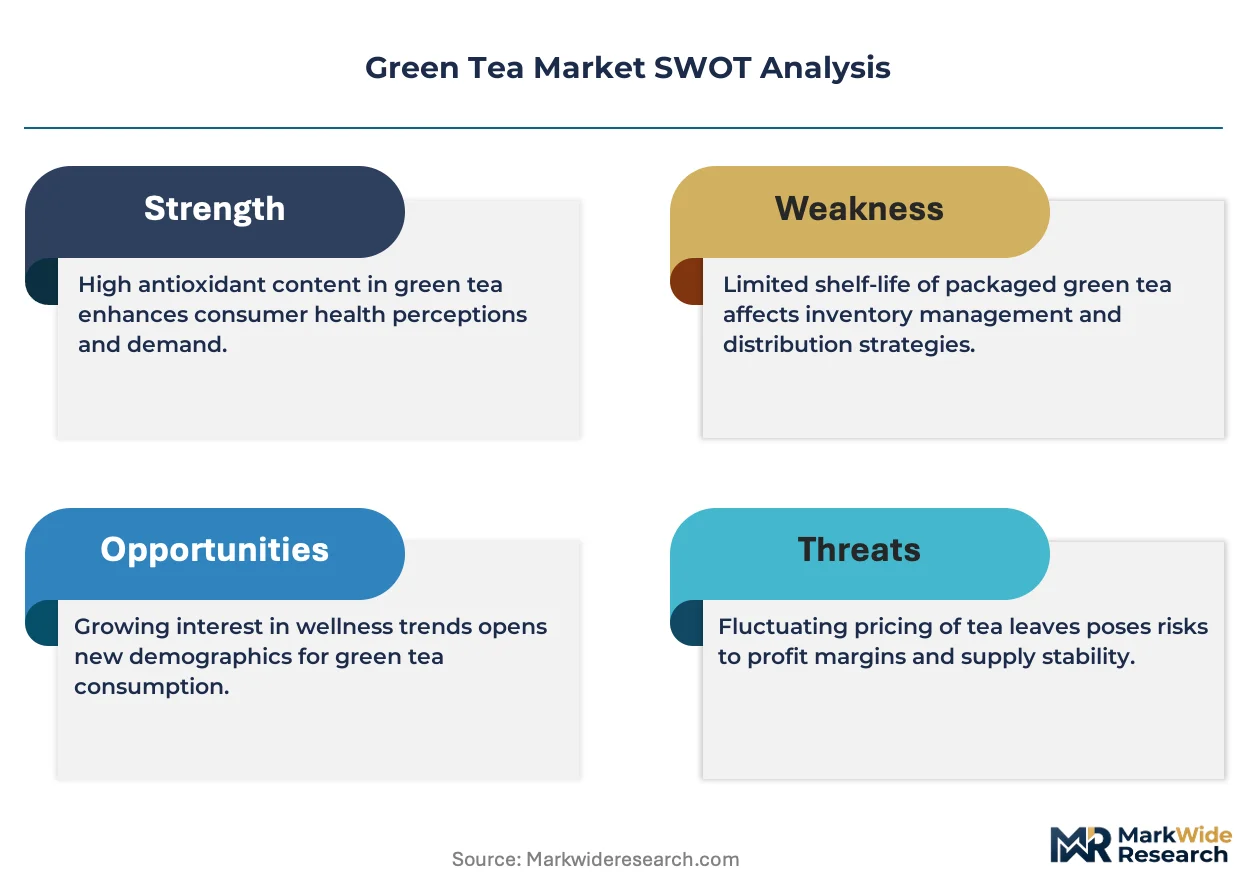
- Climate Vulnerability:Yields of the Camellia sinensis plant are susceptible to climate change-induced weather volatility, creating unpredictable raw material costs and potential supply disruptions for tea growers in key regions like India and China.
- Divergent Health Claim Regulations:Marketers face significant friction navigating the disparity between the FDA's stringent review of health claims in the US and the EFSA's pre-approved list in Europe, complicating global branding strategies.
- Substitution from Herbal Infusions:Green tea competes directly with a growing market of other functional herbal teas, such as hibiscus and rooibos, which also market themselves on antioxidant properties and caffeine-free wellness benefits.
Strategic Opportunities
- Cosmetic Applications:The use of green tea extracts in skincare and cosmetic formulations for their antioxidant and anti-inflammatory properties represents a high-value, non-beverage growth avenue for ingredient suppliers.
- Geographic Expansion:Markets in Eastern Europe and Latin America, where traditional coffee consumption dominates, present an opportunity for market entry by positioning green tea as a novel wellness beverage.
- Direct-to-Consumer Channels:E-commerce platforms enable producers of single-origin and artisanal teas to bypass traditional retail, building a direct relationship with discerning consumers and capturing higher margins.
Industry Challenges
- Certification Complexity:The transition to certified organic or fair-trade production involves lengthy, multi-stage audits and significant administrative overhead, posing a barrier for smaller tea estates and cooperatives.
- Traceability Infrastructure:Substantiating single-origin claims requires investment in transparent supply chain technologies like blockchain or QR-code systems, an operational challenge for a traditionally fragmented agricultural sector.
- Artisanal Skill Scarcity:The production of high-grade specialty teas, such as hand-ground Matcha or meticulously steamed Sencha, depends on a diminishing pool of experienced tea masters, creating a production bottleneck.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Market |
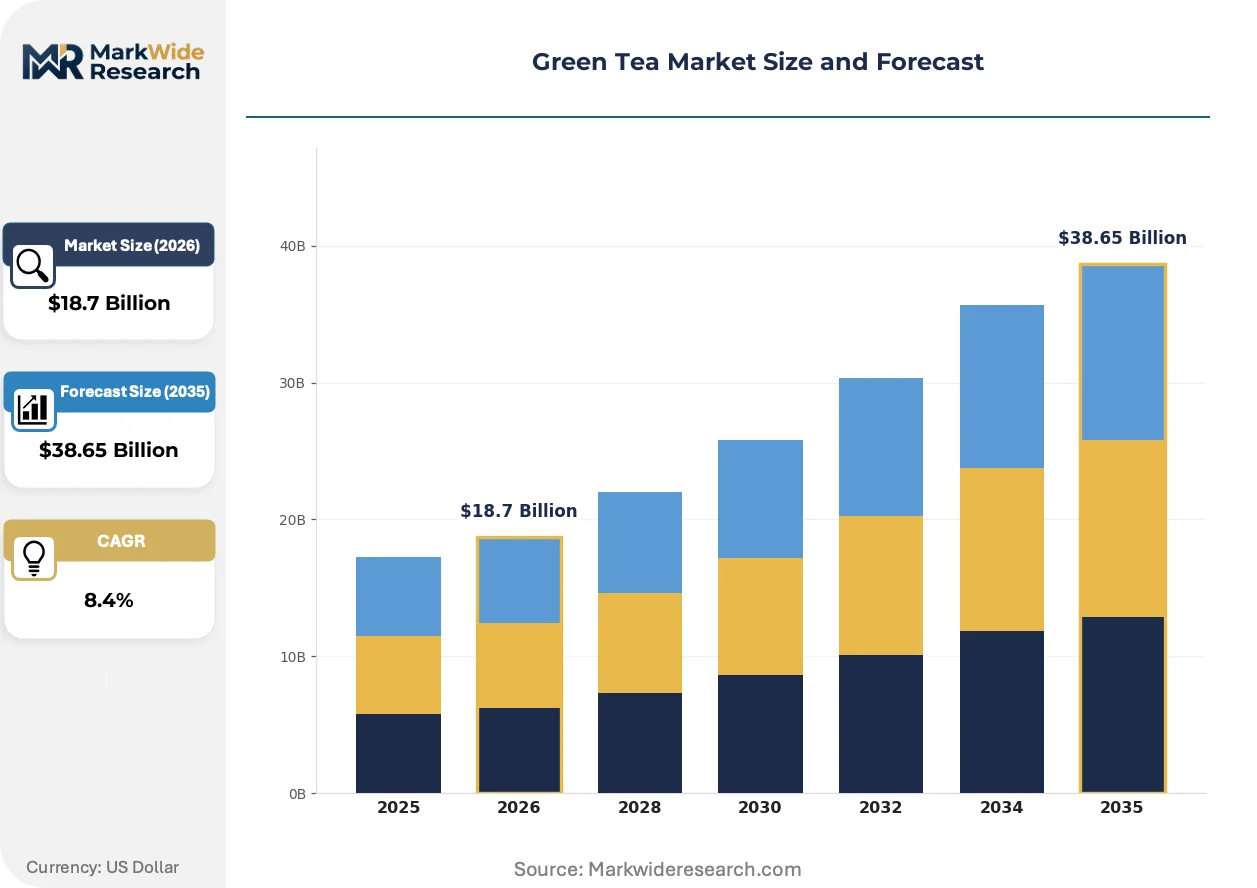
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Powder, Extracts, Ready-to-Drink Application: Beverages, Cosmetics, Pharmaceuticals, Nutraceuticals, Food Additives Customer Type: Health Enthusiasts, Retail Consumers, Foodservice Providers, Dietary Supplement Makers Packaging Type: Boxes, Tins, Sachets, Bottles, Cartons |
| Companies Covered | Starbucks Corporation, Associated British Foods plc, Unilever Plc, Hain Celestial Group, Ito En Ltd, Nestlé SA, PepsiCo, Dilmah Ceylon Tea Company, Tata Consumer Food Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Market Strategic Shifts & Innovations
Product innovation is increasingly driven by scientific advancements in isolating bioactive compounds, while consumer demand for transparency is altering distribution channels. These forces are creating a more segmented market where value is defined by verifiable health benefits and provenance, not just taste.
Advanced extraction technology allows for the precise isolation of specific polyphenols from tea leaves. The nutraceutical and functional food industries are rapidly adopting these high-purity catechin extracts for use in targeted supplements. This technological capability is decomposing the perception of tea as a monolithic beverage, breaking it into its constituent bioactive compounds for specialized, high-value applications.
European food safety regulations, particularly the EFSA's strict rules on health claims, are setting a high bar for scientific substantiation. This forces companies to invest heavily in clinical trials or pivot their marketing away from specific health benefits. The RTD and functional beverage segments in Europe are most affected, now emphasizing organic and clean-label attributes over unapproved health statements.
A notable behavioral shift is the consumer prioritization of traceability and provenance in purchasing decisions. This trend is disrupting the dominance of mass-market blends, as consumers increasingly favor single-estate teas with verifiable origins. This is most visible in North America, where QR codes on packaging allow shoppers to digitally trace a product's journey from a specific garden.
Green Tea Market Segmentation
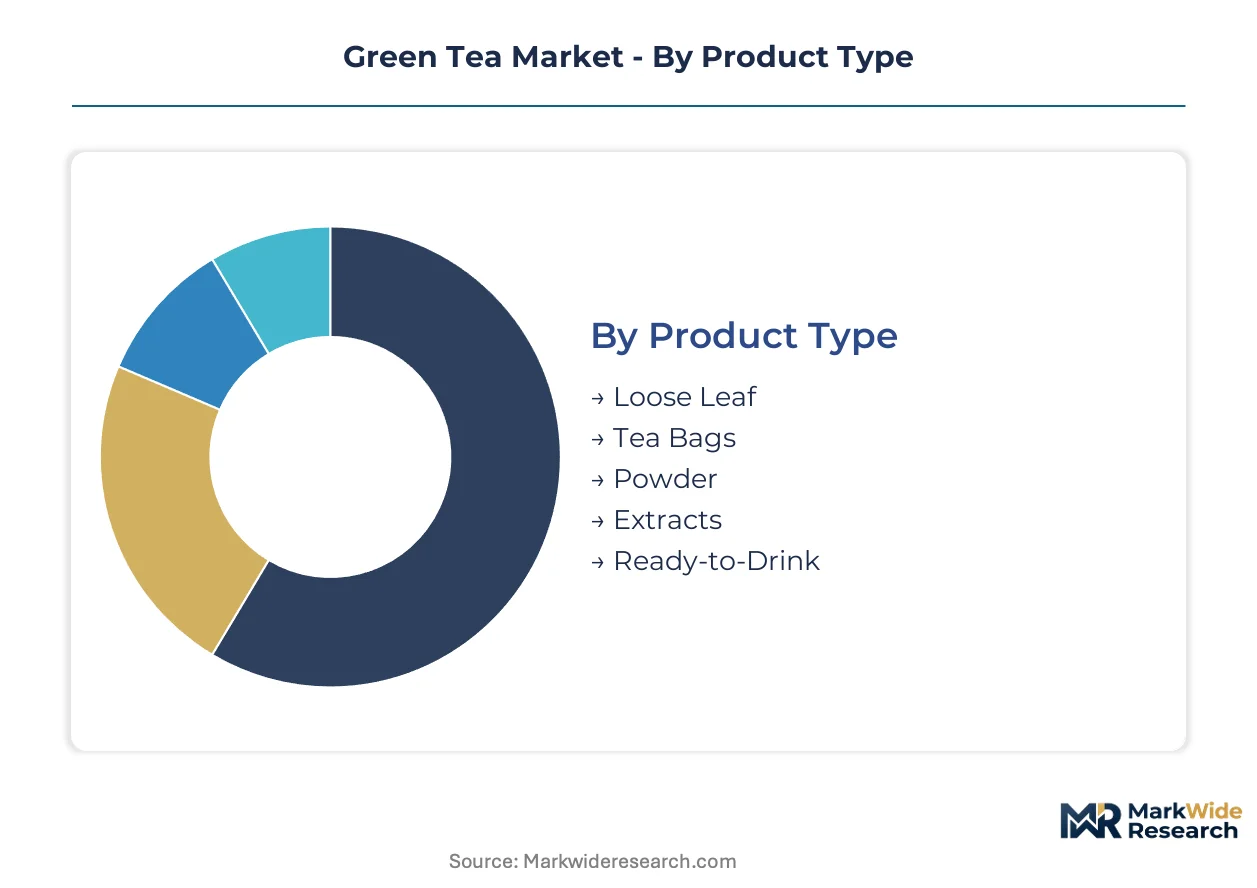
The green tea market's segmentation reveals distinct value propositions across product forms and end-use applications. Understanding these divisions helps identify key growth vectors and targeted consumer groups. This analysis dissects the market into fundamental components, highlighting areas of concentrated demand and emerging opportunities for specialized products. Each segment reflects unique processing requirements or consumer preferences.
Product Type:
Margin pools within the product type category are increasingly influenced by processing intensity and functional benefits.
- Ready-to-Drink:These pre-brewed, often sweetened or flavored, green tea beverages offer ultimate convenience for on-the-go consumption. Demand is strong among health-conscious consumers in the United States, driven by a preference for functional beverages and ease of access.
- Extracts:Concentrated forms of green tea compounds, particularly high-purity catechins like EGCG, are isolated through advanced extraction technologies. The nutraceuticals sector drives volume for these extracts, valuing their potent antioxidant properties for dietary supplements.
- Loose Leaf:Traditional unoxidized tea leaves, often sold in bulk, require brewing by the consumer.
- Tea Bags:Pre-portioned green tea leaves enclosed in permeable bags offer convenience for quick preparation.
- Powder:Finely ground green tea leaves, such as Matcha, are used in beverages, culinary applications, and supplements.
The dominant share belongs to Ready-to-Drink formats, while Extracts are closing the gap fastest.
Application:
Cost stratification within green tea applications reflects the value added through processing and formulation complexity.
- Beverages:This segment encompasses all forms of green tea consumed as a drink, from traditional hot infusions to ready-to-drink formulations. This remains the largest segment by volume, with consumption concentrating in Asian markets and the United States.
- Nutraceuticals:Green tea extracts are incorporated into dietary supplements, functional foods, and health-promoting ingredients, valued for their high antioxidant content. Demand expands in the global nutraceutical industry, driven by consumer interest in preventive health solutions.
- Cosmetics:Green tea extracts are utilized in skincare products for their antioxidant and anti-inflammatory properties, serving the beauty industry.
- Pharmaceuticals:Specific green tea compounds are researched for potential therapeutic benefits and included in certain medicinal formulations.
- Food Additives:Green tea ingredients function as natural preservatives, colorants, or flavor enhancers in various food products.
The largest volume is consumed by the Beverages segment, with Nutraceuticals showing significant expansion.
Customer Type:
Volume concentration for green tea products often aligns with specific consumer segments seeking functional benefits or convenience.
- Health Enthusiasts:Individuals actively seeking functional foods and beverages for preventive health and wellness benefits constitute this discerning group. This consumer base shows high activity notably in the United States, driving sales of premium loose-leaf and functional RTD green teas.
- Dietary Supplement Makers:Companies formulating and manufacturing health supplements and functional foods procure green tea extracts and powders. The global nutraceutical industry's demand for high-potency EGCG extracts influences procurement patterns among these manufacturers.
- Retail Consumers:General consumers purchasing green tea products for home consumption through supermarkets, convenience stores, and online channels.
- Foodservice Providers:Restaurants, cafes, hotels, and institutional caterers serving green tea beverages to their patrons.
The largest customer base is Retail Consumers, while Dietary Supplement Makers represent a high-growth niche.
Packaging Type:
The maturity of packaging solutions varies across the green tea market, reflecting product format and consumer convenience demands.
- Bottles:Primarily used for ready-to-drink (RTD) green tea beverages, offering single-serving convenience and portability. Demand for bottled green tea is high in North America, catering to busy consumers seeking functional hydration options.
- Cartons:A common packaging for multi-serve RTD green teas and some powdered products, providing extended shelf life and often eco-friendly options. This format is gaining traction in Europe due to its light weight and recyclability.
- Boxes:Traditional packaging for tea bags and some loose-leaf varieties, offering protection and brand display.
- Tins:Often used for premium loose-leaf green teas, providing an airtight seal to preserve freshness and perceived quality.
- Sachets:Small, individual packets of powdered green tea or extracts, designed for single-use convenience.
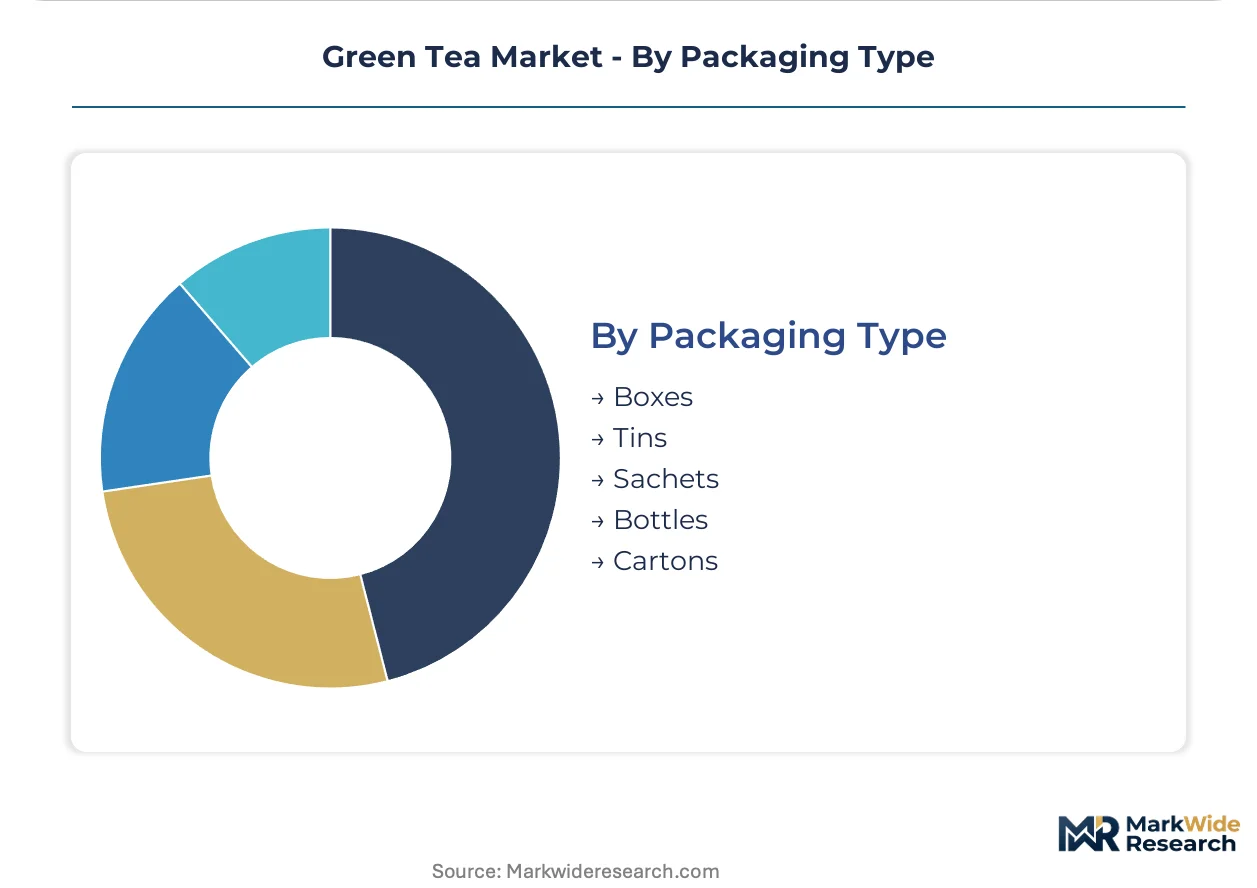
Bottles dominate the packaging landscape, with Cartons gaining traction due to convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The green tea market exhibits a complex interplay of import and export dynamics, shaping regional consumption and production patterns. Demand for functional beverages in North America drives significant imports, while traditional tea-producing nations in Asia continue to dominate cultivation and processing. These trade flows influence local market development and strategic investments across continents.
United States
Demand for functional beverages and natural health products drives green tea consumption in the United States. The FDA scrutinizes health claims, influencing marketing strategies for RTD and supplement brands. Major metropolitan areas like New York and Los Angeles see high sales of premium loose-leaf and organic varieties.
Japan
Japan maintains a strong domestic demand for high-grade green teas like Matcha and Sencha, rooted in cultural traditions. The FOSHU system provides a clear regulatory pathway for health-focused green tea products, validating functional claims. Shizuoka and Uji remain central to premium tea cultivation and artisanal processing techniques.
China
China's vast domestic market consumes substantial volumes of green tea, alongside its significant role as a global exporter. The SAMR sets standards for food safety and quality, impacting both local and international trade. Provinces like Zhejiang and Anhui are renowned for their diverse green tea production and processing hubs.
India
India's green tea market is expanding due to health consciousness and a shift from traditional black tea, particularly in urban areas. The FSSAI mandates strict quality and safety standards for all tea products, including contaminant limits. Assam and Darjeeling are key tea-growing regions, increasingly diversifying into green tea production.
Germany
Germany demonstrates a rising demand for organic and specialty green teas, driven by consumer preferences for natural and healthy products. EFSA regulations influence product labeling and health claims across the European Union, affecting import strategies. Hamburg serves as a significant port for tea imports and a hub for tea blending and distribution across Europe.
Green Tea Market Key Industry Players
Concentration sits with global beverage conglomerates and diversified food companies, which leverage extensive distribution networks and brand recognition. The market structure exhibits a tiered consolidation, with large players dominating mainstream segments and specialized brands capturing premium niches. Strategic archetypes include multinational beverage giants focused on convenience, traditional tea specialists emphasizing authenticity, and health-focused organic brands targeting wellness consumers. Geographic expansion into emerging markets and portfolio diversification into functional green tea products represent common competitive moves among these entities.
Multinational corporations with broad portfolios exemplify the scale-driven segment, extending their reach across various product types. Unilever Plc, a global consumer goods company, represents a major player in the mainstream tea market through its well-established brands and extensive retail presence. Ito En Ltd, a Japanese corporation, occupies a position as a specialist in high-grade traditional green teas, catering to discerning consumers seeking authentic experiences. Tata Consumer Food Limited, an Indian entity, anchors its market presence through extensive control over tea plantations and a wide product range, particularly in its home market.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Associated British Foods plc |
| Unilever Plc |
| Hain Celestial Group |
| Ito En Ltd |
| Nestlé SA |
| PepsiCo |
| Dilmah Ceylon Tea Company |
| Tata Consumer Food Limited |
| Others |
Cost & Logistics Intelligence
Demand for high-catechin green tea extracts is reshaping cultivation practices and processing methods, influencing pricing models and supply chain concentration across Asia.
Pricing Analysis
Dietary Supplement Makers anchor contract-based long-term offtake agreements for high-purity green tea extracts. Catechin concentration and organic certification serve as primary price differentiation drivers. Pricing softness stems from commodity price volatility for raw tea leaves. Retail Consumers exhibit high price sensitivity, while Nutraceutical buyers prioritize efficacy and purity over cost.
Supply Chain Analysis
China and India anchor green tea leaf cultivation, supplying the global market with diverse varieties. The supply chain draws from Camellia sinensis leaves, water, and specialized processing agents. Climate change-induced weather volatility poses a significant supply disruption risk for key growing regions. Distribution runs through global trading houses and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green tea market requires a robust substitution defense against other functional herbal infusions. These alternatives continually compete for health-conscious consumers.
For Market Incumbents: Shield market share by diversifying product portfolios beyond traditional beverage formats. Invest in advanced extraction technologies for high-purity catechin compounds, directly addressing nutraceutical demand. This counters the substitution threat from other functional herbal infusions. Prioritize certification investment, such as FOSHU, to validate health claims and premiumize offerings.
For New Entrants and Emerging Players: Differentiate on verifiable provenance and sustainability credentials. Target cosmetic applications with specialized green tea extracts for high-value growth avenues. Eastern Europe presents a penetrable geography for novel wellness beverages, leveraging existing coffee consumption habits. Direct-to-consumer e-commerce platforms offer a powerful go-to-market angle, building direct consumer relationships.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized ingredient suppliers and premium brand consolidators. Long-term viability remains strong, driven by sustained consumer health consciousness and functional ingredient demand. Target niche players with strong intellectual property in advanced extraction technologies or unique single-origin supply chains. Increased regulatory harmonization of health claims across major markets serves as a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Nutraceuticals | Addresses growing demand from the global nutraceutical industry for high-potency EGCG. |
| Investment in Advanced Extraction Technology | Enables precise isolation of specific polyphenols for specialized, high-value applications. |
| Direct-to-Consumer Channel Expansion | Builds direct relationships with discerning consumers, capturing higher margins for artisanal teas. |
| Organic Certification Pursuit | Meets consumer demand for natural and healthy products, particularly in Germany. |
| Geographic Expansion into Eastern Europe | Positions green tea as a novel wellness beverage in traditional coffee-drinking markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of academic journals, industry reports, and government publications. This approach integrates insights from tea estate owners, nutraceutical formulators, retail category managers, and cosmetic R&D leads. Secondary validation utilized USDA agricultural statistics, EFSA scientific opinions, FSSAI regulations, and company annual reports. A bottom-up approach aggregated granular data, validated through top-down market sizing and expert consensus.
Product type, application, customer type, packaging type, and regional consumption patterns define the segmentation dimensions modeled. The analytical framework integrates historical data and forward-looking projections across the analysis window. Compound annual growth rates derive from a regression analysis of demand drivers and supply-side capabilities. Consumer health consciousness trends and nutraceutical sector investment serve as key forecast inputs.
Decision-makers should treat outputs as directional under current climate stability and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect documented assumptions; however, climate vulnerability and divergent health claim regulations present specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Organic Tea Market
Tea
Light-Fermented Tea Market
Tea
Global Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Matcha Tea Market
Tea
Global Tea Extract Market
Tea
Asia-Pacific Tea Market
Tea
Africa Tea Market
Tea
Spray-Dried Tea Products Market
Tea
Europe Ready-To-Drink Tea Market
Tea
South America Tea Market
Tea
New Style Tea Drink Market
Tea
Moringa Tea Market
Tea
US Ready to Drink Tea Market
Tea
Fermented Tea Market
Tea
Butterfly Pea Flower Tea Market