
 White Tea Market | 2026-2036
White Tea Market Size, Share, and Industry Trends Forecast 2026-2036
White Tea Market Analysis
Specialty tea e-commerce is rewriting procurement patterns for white tea buyers worldwide. Zhejiang Tea Group Co. Ltd. leverages its state-backed logistics network to dominate bulk exports from eastern China. Rare Tea Company Ltd. differentiates through direct-origin sourcing, bypassing auction houses to capture margin. Wollenhaupt Tee GmbH anchors European blending operations with consistent German inventory standards.
White tea consists of minimally processed Camellia sinensis buds and young leaves, typically withered and dried without oxidation to preserve high catechin content and delicate flavor profiles. Its primary commercial purpose centers on premium beverage applications and antioxidant extract supply for nutraceutical formulators. Silver Needle commands the highest price tier among product types due to labor-intensive hand-plucking of unopened buds. Powdered and extract forms are expanding fastest as wellness centers and functional food developers seek concentrated polyphenol delivery. Loose leaf retains maturity in traditional HoReCa channels where ceremony and provenance drive selection.
China's SAMR enforces GB standards on maximum residue limits for tea imports, while the EU's EFSA and REACH frameworks scrutinize botanical contaminants and packaging material compliance. These overlapping regimes elevate testing costs but also filter out informal suppliers, tightening market access for certified operators. Stakeholders must monitor evolving MRL harmonization between Asian origin authorities and European destination regulators to anticipate sourcing cost shifts.
Market Dynamics
White tea supply chains face intensifying pressure from the EU's Farm to Fork Strategy, which tightens pesticide residue thresholds and forces origin consolidation toward certified Fujian estates capable of meeting dual GB standards and REACH compliance.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory reduction in chemical inputs across imported agricultural products filters informal suppliers, tightening market access for certified operators with compliant Fujian sourcing.
- Functional beverage formulators:Wellness centers and nutraceutical developers drive demand for concentrated polyphenol extracts, expanding powdered and extract format adoption.
- Silver Needle cultivation zones:Labor-intensive hand-plucking of unopened buds in Fuding and Zhenghe counties sustains premium pricing tiers that subsidize broader category development.
Market Restraints
- Input cost volatility:Weather-sensitive bud yields in northern Fujian create harvest uncertainty that propagates through contracted supply agreements.
- Supply concentration risk:Over-reliance on eastern Chinese processing infrastructure exposes buyers to logistics disruptions at Ningbo and Xiamen port clusters.
- Regulatory friction:Divergent MRL harmonization between SAMR's GB standards and EFSA's evolving thresholds elevates testing costs for cross-border operators.
Strategic Opportunities
- Underpenetrated extract applications:Cosmetic formulators in South Korea and Japan represent untapped demand for EGCG-rich white tea derivatives in topical antioxidant products.
- Direct-origin e-commerce channels:Specialty tea platforms bypass traditional auction houses, capturing margin through transparent provenance storytelling and certified organic positioning.
- EU Green Deal alignment:Carbon-neutral processing investments qualify certified estates for preferential procurement by sustainability-mandated European retailers.
Industry Challenges
- Skilled plucker scarcity:Generational transition away from agricultural labor in Fujian's mountainous tea zones threatens Silver Needle quality consistency.
- Dual certification timelines:Parallel organic and geographic indication audits create 18-24 month compliance windows that delay market entry for new estate operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Tea Market |
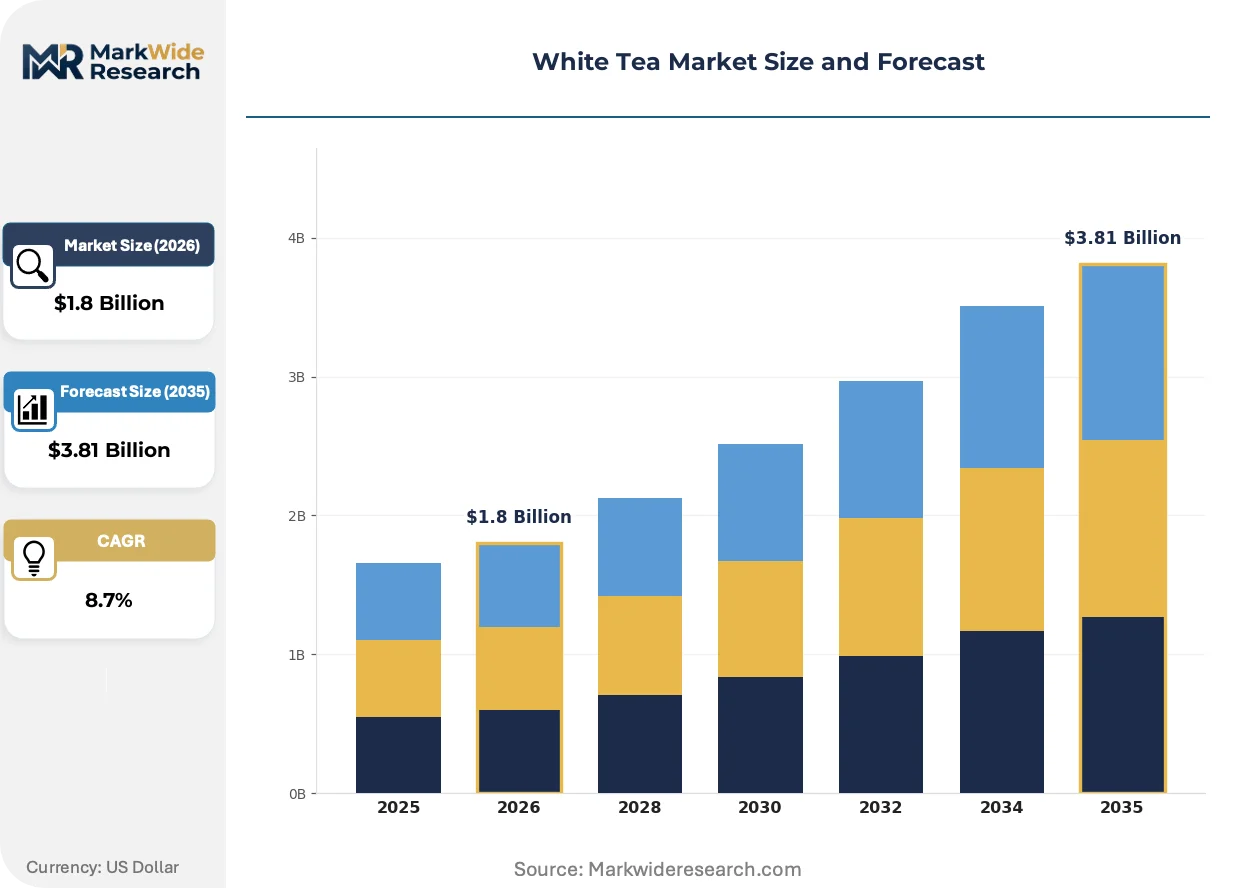
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Needle, White Peony, Ceylon White, Darjeeling White Form: Loose Leaf, Tea Bags, Powdered, Extract End User: Retail Consumers, HoReCa, Online Sellers, Wellness Centers Packaging Type: Boxes, Pouches, Tins, Bottles |
| Companies Covered | Dilmah Ceylon Tea Company PLC, Carrubba Inc., Botaniex, Inc., Arihant Tea Company, Wollenhaupt Tee GmbH, Zhejiang Tea Group Co. Ltd., Shaanxi Iknow Biotechnology Co. Ltd., Solanki Tea Co., Rare Tea Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Tea Market Emerging Trajectories
Digital traceability infrastructure and cold-chain logistics are compressing traditional procurement cycles, while regulatory convergence between Asian origin authorities and European destination frameworks rewrites certification requirements for premium tea categories.
Blockchain-enabled origin verification is virtualizing provenance documentation for white tea lots. German and Dutch specialty importers now mandate digital chain-of-custody records for Silver Needle and White Peony purchases. This technology is virtualizing the role of traditional auction intermediaries, compressing margin extraction points and accelerating direct estate-to-blender relationships.
REACH framework amendments scrutinize botanical contaminants and packaging material compliance for imported teas entering European customs zones. Industrial consequence includes mandatory third-party laboratory testing for polycyclic aromatic hydrocarbons and heavy metals. Fujian-based exporters with in-house ISO 17025 accredited labs capture preferential positioning against competitors reliant on external certification.
Wellness-oriented buyers now specify catechin content thresholds in procurement contracts rather than accepting traditional grade-based pricing. Functional beverage developers in North America and Western Europe displace loose-leaf ceremonial specifications with standardized extract potency requirements. This specification shift concentrates contract awards toward estates with integrated processing and analytical capabilities.
White Tea Market Segmentation
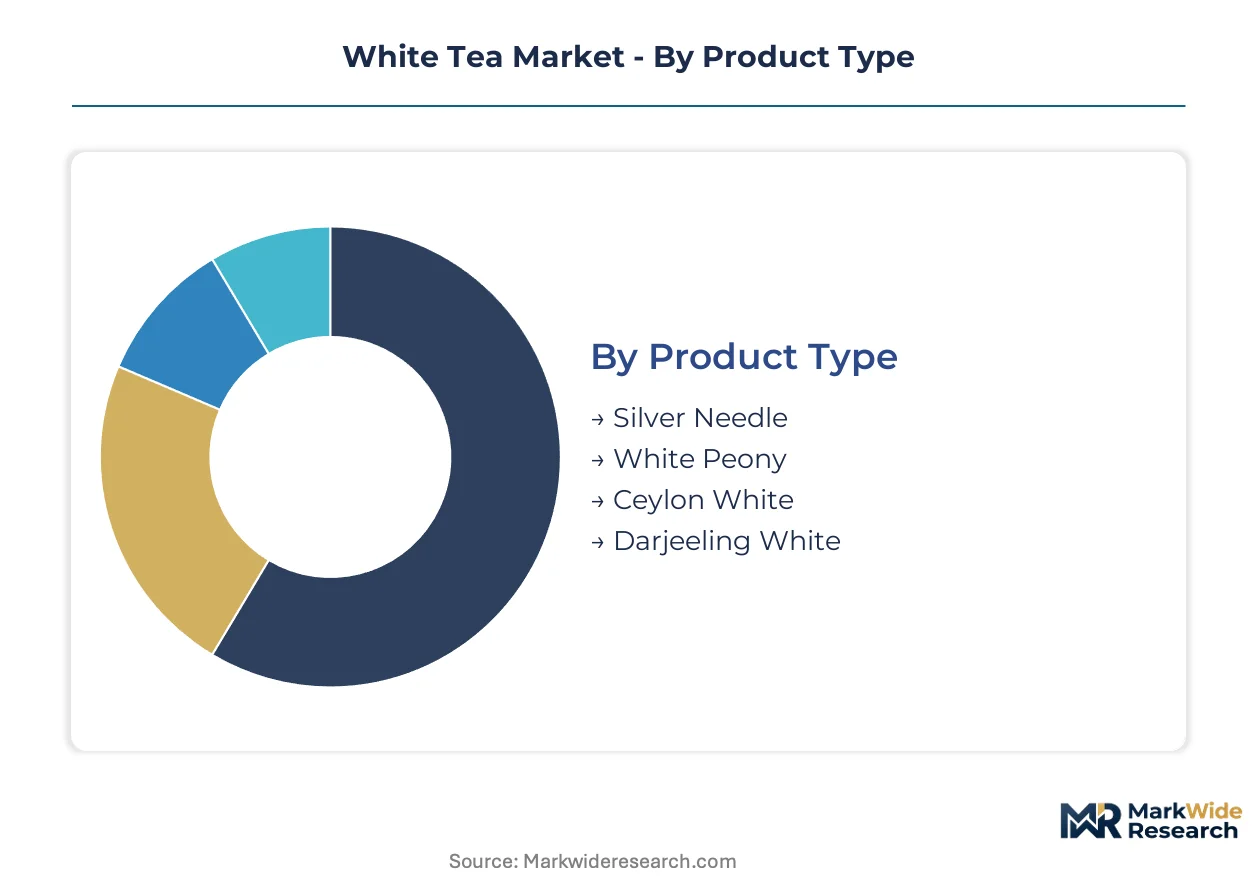
White tea procurement patterns diverge sharply across product grades, preparation formats, and channel requirements. Buyers in premium wellness and foodservice segments impose distinct specification regimes that reshape supplier capability investments.
Product Type:
After-sales intensity concentrates in Silver Needle contracts, where buyers demand lot-specific traceability and replacement guarantees for quality deviations.
- Silver Needle:Composed exclusively of unopened Camellia sinensis buds hand-plucked during early spring harvest windows. Fujian's Fuding and Zhenghe counties dominate contracted supply for European wellness brands seeking EGCG standardization. Labor scarcity in these mountainous zones threatens consistent bud quality.
- White Peony:Blends unopened buds with young leaves in a 1:1 to 2:1 ratio, delivering fuller body at accessible price points. HoReCa channels in Germany and France specify White Peony for house-blend programs where provenance storytelling supports menu premiums. Harvest timing flexibility reduces supply volatility versus pure-bud grades.
- Ceylon White:Sri Lankan high-elevation cultivars processed with partial oxidation protocols distinct from Fujian methods. Niche positioning among specialty importers seeking origin diversification.
- Darjeeling White:Himalayan terroir expressions from Indian estates with limited annual output. Auction house concentration creates procurement friction for direct-origin buyers.
By volume, White Peony leads. By growth pace, Silver Needle is ahead.
Form:
Cost tier stratification separates ceremonial loose-leaf specifications from convenience-oriented formats targeting functional beverage developers.
- Loose Leaf:Traditional presentation preserving whole-leaf integrity for brewing control. Premium HoReCa accounts in Italy and Spain require visible leaf structure for tableside service rituals. Inventory turnover constraints limit adoption in mass retail.
- Powdered:Finely milled leaf material enabling instant dissolution and precise dosing. Nutraceutical formulators in South Korea specify powdered white tea for capsule and sachet applications where catechin bioavailability drives procurement. Processing heat exposure degrades volatile compounds without cold-milling infrastructure.
- Tea Bags:Standardized portioning for hospitality and office channels. Pyramid formats with whole-leaf filling command price premiums over conventional dust grades.
- Extract:Concentrated polyphenol isolates standardized to EGCG or total catechin content. Functional beverage developers in North America displace commodity tea purchases with potency-guaranteed inputs.
Loose Leaf retains the largest volume position. Extract formats are climbing the fastest.
End User:
Customer type determines specification granularity, with wellness centers imposing analytical requirements that retail channels rarely match.
- Wellness Centers:Clinical and spa environments specifying white tea for antioxidant therapy programs. Japanese and South Korean operators require third-party catechin assays with each delivery. Certification maintenance costs filter supplier pools.
- HoReCa:Hotels, restaurants, and cafes sourcing for beverage menus and guest amenities. European procurement consortia increasingly mandate organic certification and carbon footprint disclosure.
- Retail Consumers:Supermarket and specialty store purchasers responding to packaging and price cues. Direct-to-consumer platforms capture margin through subscription models.
- Online Sellers:Marketplace vendors and dedicated tea platforms leveraging provenance transparency for differentiation. Blockchain-enabled origin verification reduces return rates.
Retail Consumers dominate current volume. Wellness Centers are gaining share fastest.
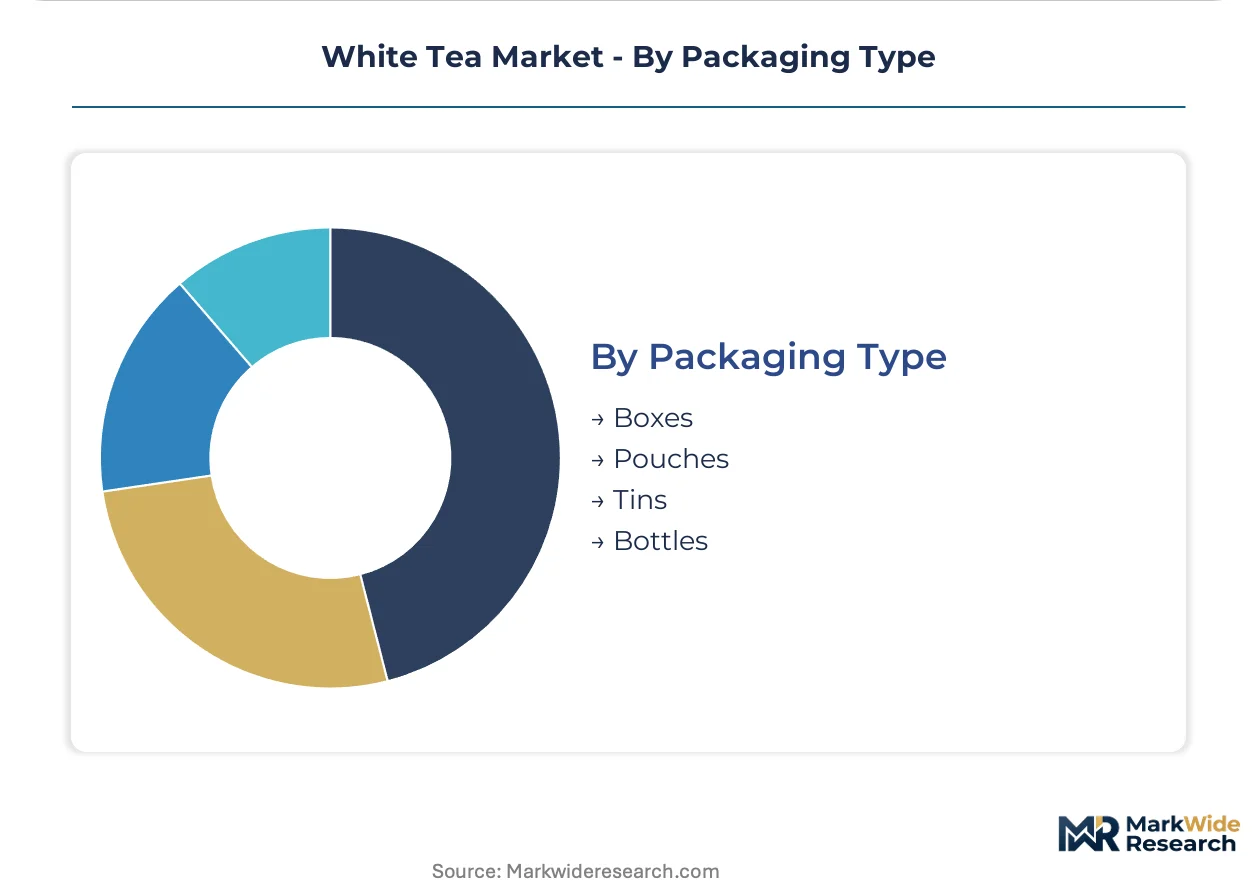
Packaging Type:
Margin structure varies by material and closure complexity, with tin formats supporting gift positioning that subsidizes commodity pouch sales.
- Pouches:Flexible laminated barriers with resealable closures for loose-leaf retail distribution. German and Dutch supermarkets specify recyclable mono-material constructions to meet EU Green Deal requirements.
- Tins:Rigid metal containers preserving aroma integrity through multi-year storage. Premium gifting segments in China and Japan sustain demand despite higher unit costs.
- Boxes:Paperboard secondary packaging for multi-unit retail presentation. Shelf-ready designs reduce restocking labor for grocery channels.
- Bottles:Ready-to-drink formats for cold-brew white tea beverages. North American convenience store distribution drives specification for UV-protective amber glass or PET.
Pouches lead by shipment volume. Bottles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo and Xiamen port clusters anchor white tea export infrastructure, channeling Fujian-origin product through maritime corridors to European and North American destinations.
China
Fujian province concentrates ancestral cultivation of Silver Needle and White Peony cultivars in Fuding and Zhenghe counties. SAMR enforces GB standards on maximum residue limits, filtering informal suppliers from export channels. Zhejiang Tea Group leverages state-backed logistics networks to dominate bulk shipments through Ningbo port.
Germany
Specialty importers in Hamburg and Bremen mandate blockchain-enabled origin verification for Silver Needle purchases. REACH framework amendments scrutinize botanical contaminants and packaging material compliance. Wollenhaupt Tee anchors European blending operations with consistent inventory standards from ISO 17025-accredited Fujian partners.
United States
Functional beverage developers in California and New York specify catechin content thresholds in procurement contracts rather than grade-based pricing. FDA oversight of dietary supplement labeling shapes extract import requirements. Direct-to-consumer platforms capture margin through subscription models targeting wellness-oriented households.
United Kingdom
London-based specialty tea platforms bypass traditional auction houses through transparent provenance storytelling. Rare Tea Company exemplifies direct-origin sourcing models that capture margin from certified organic positioning. Brexit-related customs friction elevates documentation requirements for EU-transshipped Fujian product.
Japan
Cosmetic formulators in Osaka and Tokyo represent untapped demand for EGCG-rich white tea derivatives in topical antioxidant products. METI guidance on natural ingredient labeling influences extract procurement specifications. Cold-chain logistics investments compress traditional procurement cycles for high-catechin powder formats.
White Tea Market Vendor Landscape
On the supply side, the industry is bifurcated between state-backed Chinese exporters with captive logistics infrastructure and European specialty blenders with analytical certification capabilities. Tiered competitive positioning separates premium direct-origin specialists from commodity bulk handlers. Three archetypes dominate: state-affiliated export conglomerates, German precision blenders, and boutique provenance curators. Capacity expansion in Fujian's certified estates and backward integration into cold-milling infrastructure constitute the dominant competitive moves.
Within the state-affiliated tier, Zhejiang Tea Group Co. Ltd. represents scale-driven export consolidation from eastern China. Among European precision blenders, Wollenhaupt Tee GmbH exemplifies analytical rigor in contract specification. Rare Tea Company Ltd. occupies the boutique provenance curator position, anchoring direct-origin e-commerce channels that bypass traditional intermediaries.
| Leading Market Players |
|---|
| Dilmah Ceylon Tea Company PLC |
| Carrubba Inc. |
| Botaniex, Inc. |
| Arihant Tea Company |
| Wollenhaupt Tee GmbH |
| Zhejiang Tea Group Co. Ltd. |
| Shaanxi Iknow Biotechnology Co. Ltd. |
| Solanki Tea Co. |
| Rare Tea Company Ltd. |
| Others |
Supply Flow & Price Mechanics
Fujian's Fuding and Zhenghe counties anchor global Silver Needle capacity, with labor-intensive bud plucking creating natural scarcity premiums that cascade through downstream contract tiers. Certified estates with dual GB and REACH compliance capture pricing power against informal competitors filtered by tightening EU Farm to Fork thresholds.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs white tea procurement. Silver Needle commands premium positioning through hand-plucked unopened buds, while White Peony fills mid-market HoReCa channels and powdered extracts serve economy-tier nutraceutical formulators. Price differentiation hinges on certification grade and catechin standardization capabilities. Cost compression in mid-tier loose-leaf segments intensifies as logistics disruptions at Ningbo and Xiamen propagate through contracted agreements. Wellness centers exhibit lowest price sensitivity due to clinical therapy positioning, whereas retail consumers in supermarket channels drive volume through promotional responsiveness.
Supply Chain Analysis
Camellia sinensis bud feedstock draws from Fujian province in China, with secondary sourcing from Sri Lankan high-elevation estates and limited Himalayan output from Indian Darjeeling zones. Raw material dependencies center on spring harvest timing, skilled plucker availability, and cold-milling infrastructure for powder formats. Single-source vulnerability concentrates in eastern Chinese processing clusters exposed to port logistics disruptions. Distribution runs through maritime corridors from Ningbo and Xiamen to European specialty importers and North American functional beverage developers, with direct-origin e-commerce platforms compressing traditional auction house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White tea market fragmentation creates entry niches as wellness buyers displace grade-based procurement with catechin potency specifications that favor estates with integrated analytical capabilities.
For Market Incumbents: Pre-empt margin erosion in loose-leaf ceremonial tiers by securing backward integration into cold-milling infrastructure for extract formats. Defensive certification investments in ISO 17025 laboratory accreditation filter emerging competitors dependent on external testing. Channel control through blockchain-enabled origin verification locks in German and Dutch specialty importer relationships against direct-origin platform disruption. For New Entrants and Emerging Players: Cosmetic formulators in South Korea and Japan represent the most penetrable entry point for EGCG-rich topical antioxidant derivatives, a white-space application with limited incumbent specialization. Direct-origin e-commerce channels with transparent provenance storytelling bypass auction house margin extraction. Go-to-market execution should anchor on certified organic positioning with carbon-neutral processing credentials aligned to EU Green Deal procurement mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors estates with integrated processing and analytical capabilities over commodity bulk handlers. Long-term viability rests on dual certification maintenance and cold-chain logistics infrastructure. Acquisition target archetypes include Fujian-based operators with captive GB-compliant sourcing and in-house ISO 17025 labs. The signal to watch is MRL harmonization progress between SAMR and EFSA frameworks, which would accelerate consolidation toward compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Milling Infrastructure Investment | Captures powdered and extract format growth from nutraceutical formulators specifying catechin bioavailability. |
| Dual Certification Acceleration | Parallel organic and geographic indication audits filter competitors through 18-24 month compliance windows. |
| Blockchain Origin Verification | German and Dutch importers now mandate digital chain-of-custody records for Silver Needle procurement. |
| Carbon-Neutral Processing Certification | EU Green Deal alignment qualifies estates for preferential procurement by sustainability-mandated European retailers. |
| Direct-Origin E-Commerce Launch | Specialty platforms bypass auction intermediaries through transparent provenance storytelling and subscription models. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with estate operators, specialty tea importers, and nutraceutical procurement managers; and secondary validation through customs records, EU EFSA regulatory filings, and SAMR GB standard documentation. Bottom-up volume modeling triangulated against top-down category spend estimates from wellness center and HoReCa channel assessments.
Forecast inputs across the modeling period incorporated product type segmentation by Silver Needle, White Peony, and extract formats; preparation form including loose-leaf, powdered, and tea bag configurations; and end-user channels spanning wellness centers, HoReCa, and retail consumers. CAGRs derived from regression analysis against historical trade flows and regulatory compliance cost trajectories. Specific inputs included EU Farm to Fork Strategy implementation timelines and Fujian bud yield sensitivity to weather patterns.
Macroeconomic conditions sit as an overlay; deviation in euro-yuan exchange rates or maritime freight indices would shift the trajectory for European import demand. Forecasts reflect documented assumptions regarding MRL harmonization progress and skilled labor availability in Fujian's mountainous tea zones. Cross-checking against customs trade data and specialty importer inventory disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Pu-Erh Tea Market
Tea
Tea Pitchers Market
Tea
Global Fruit Tea Market
Tea
Tea Infuser Market
Tea
Africa Ready to Drink Tea Market
Tea
White Tea Extract Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Middle East Ready to Drink Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Europe Tea Market
Tea
Asia-Pacific Tea Market
Tea
Green Tea Leaves Market
Tea
Global Tea Extract Market
Tea
Probiotic Tea Market
Tea
Light-Fermented Tea Market
Tea
Europe Ready-To-Drink Tea Market