
 Gynecomastia Procedures Market | 2026-2036
Gynecomastia Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Gynecomastia Procedures Market Analytics
Market Context
Energy-based modalities using radiofrequency-assisted lipolysis is realigning cost structures away from traditional surgical excision. InMode Ltd. leverages proprietary radiofrequency platforms to capture premium outpatient volumes. Apollo Hospitals anchors South Asian demand through integrated cosmetic surgery centers. Cynosure LLC competes on laser- and light-based tissue remodeling systems across multiple geographies.
Technical Definition and Segment Structure
Gynecomastia procedures encompass surgical and nonsurgical interventions to reduce benign male breast tissue enlargement, employing tumescent infiltration, glandular excision, or selective adipocyte thermolysis with power settings typically between 20–40 W depending on modality. The primary commercial purpose is restoration of masculine chest contour with minimized scar burden and reduced recovery intervals. Liposuction dominates procedural volume due to lower anesthesia requirements and same-day discharge eligibility, while laser therapy captures the fastest expansion as outpatient clinics invest in compact, multi-application platforms. Tissue grafting occupies a narrow premium tier serving revision cases and transgender-affirming care pathways where autologous reconstruction is prioritized.
Regulatory Environment
FDA premarket notification pathways for radiofrequency and laser devices govern device safety and efficacy claims in the United States, while CE marking under the EU MDR imposes enhanced clinical evidence requirements for energy-based aesthetic systems sold in Europe. Brazil's ANVISA and South Korea's MFDS maintain parallel but distinct registration frameworks that shape market entry timelines and labeling restrictions. Stakeholders must monitor evolving reclassification of energy-based devices from aesthetic to therapeutic indications, as this shift would trigger stricter reimbursement and post-market surveillance obligations across major jurisdictions.
Market Dynamics
Radiofrequency-assisted lipolysis is compressing recovery intervals and shifting procedure volumes from inpatient surgical suites to ambulatory settings, restructuring capital deployment across clinic networks.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearances for energy-based devices reduce time-to-market for radiofrequency and laser platforms, stimulating equipment upgrade cycles in United States outpatient centers.
- Medical tourism infrastructure:Brazil's integrated cosmetic surgery corridors and South Korea's recovery hospitality packages attract international patients seeking combined aesthetic procedures at bundled rates.
- Adipocyte thermolysis protocols:Refinement of 20–40 W power settings enables precise tissue targeting with reduced thermal damage, expanding treatable patient profiles beyond traditional surgical candidates.
Market Restraints
- Capital intensity of multi-modality platforms:Laser and radiofrequency systems require $150,000–$400,000 upfront investment, constraining independent clinic participation and favoring hospital-affiliated networks.
- EU MDR clinical evidence burdens:Enhanced post-market surveillance and technical documentation requirements for CE-marked energy devices extend registration timelines and inflate regulatory compliance costs.
- Reimbursement exclusion:Aesthetic classification of gynecomastia procedures across major insurance frameworks limits patient access to cash-pay segments, capping volume in price-sensitive demographics.
Strategic Opportunities
- Revision surgery segment:Tissue grafting techniques for post-operative contour deformities command premium pricing and build recurring referral relationships with primary surgeons.
- Transgender-affirming care pathways:Autologous reconstruction demand from gender confirmation programs creates specialized service lines with distinct informed-consent protocols and multidisciplinary care teams.
- Compact platform leasing models:Subscription-based equipment access lowers barrier-to-entry for standalone cosmetic clinics, expanding addressable provider base in secondary metropolitan markets.
Industry Challenges
- Cross-specialty training deficits:Safe radiofrequency lipolysis execution requires combined plastic surgery and dermatology competencies, creating certification bottlenecks as device manufacturers scale training infrastructure.
- Standardization of outcome metrics:Absence of validated photographic assessment protocols and patient-reported outcome instruments complicates marketing claims and informed consent documentation across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gynecomastia Procedures Market |
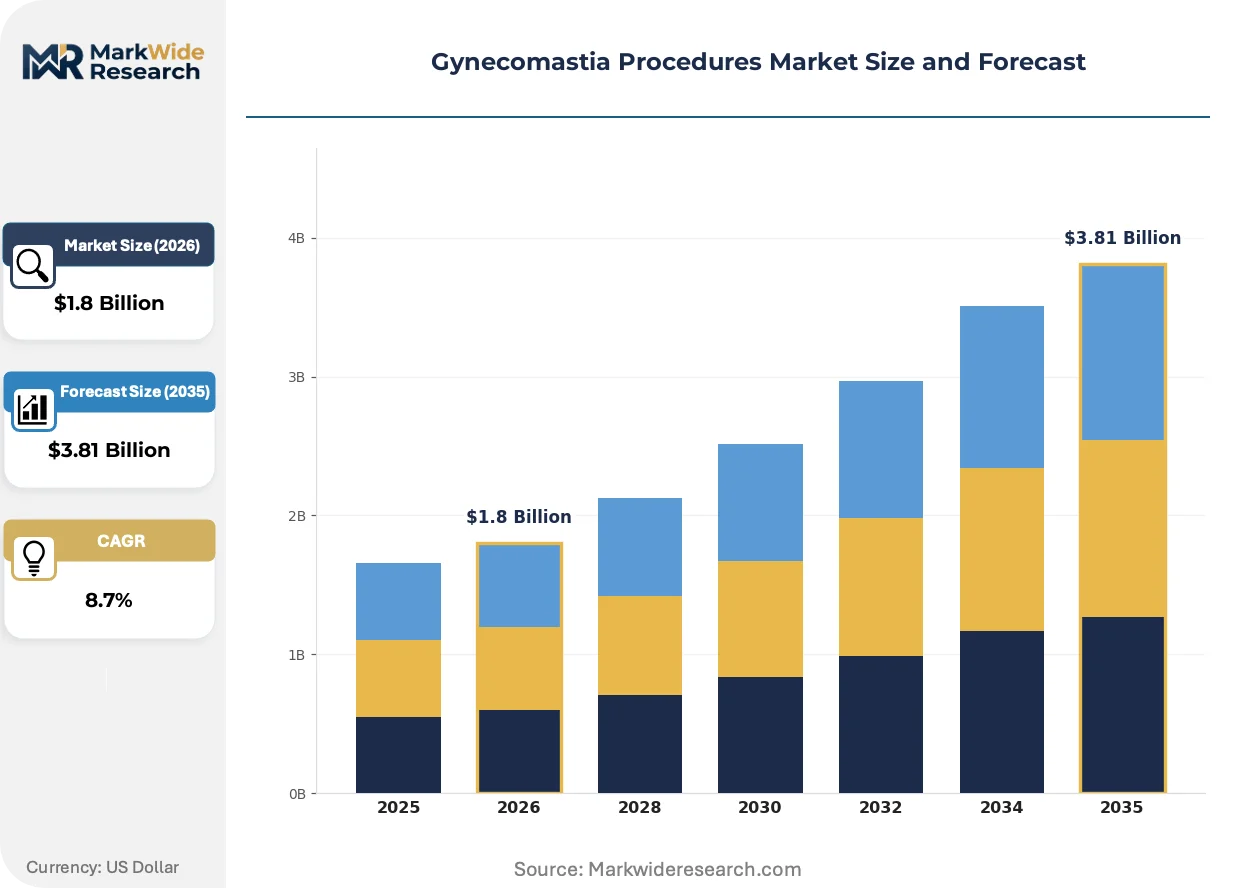
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Liposuction, Surgical Excision, Tissue Grafting, Laser Therapy Delivery Mode: Inpatient, Outpatient, Telemedicine, Private Clinic Patient Demographics: Adolescents, Young Adults, Middle-Aged Men, Seniors Cost Tier: Low-Cost, Mid-Range, High-End, Premium |
| Companies Covered | Spire Healthcare Group plc, Apollo Hospitals, InMode Ltd., Medipol Mega University Hospital, Bumrungrad International Hospital, Lumenis Ltd., Max Healthcare, ID Hospital, Cynosure LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gynecomastia Procedures Market Evolving Landscape
Energy-based modalities are fragmenting the traditional surgical monopoly on gynecomastia correction, enabling procedure migration toward minimally invasive formats that reshape clinic economics and patient acquisition strategies.
Radiofrequency-assisted lipolysis systems is expanding into outpatient cosmetic surgery centers as the primary modality for pseudogynecomastia cases with predominant adipose component. Young adult male patients seeking rapid return-to-activity are driving same-day discharge protocols. This technology is compressing average revenue per procedure while expanding total addressable procedure volume through lower price points.
CE marking under EU MDR is elevating clinical evidence requirements for energy-based aesthetic devices previously cleared under lighter touch regimes. Manufacturers must now submit post-market clinical follow-up data and maintain vigilance systems for adverse events. European distribution partners are prioritizing suppliers with established PMCF programs, reshaping vendor selection criteria.
Direct-to-consumer digital marketing is displacing traditional physician referral networks as the dominant patient acquisition channel. Social media platforms and before-after photography galleries on clinic websites now drive initial consultation requests, particularly among 18–34 year-old demographics. South Korea and Brazil exhibit the most advanced deployment of influencer partnerships and virtual consultation workflows.
Gynecomastia Procedures Market Segmentation
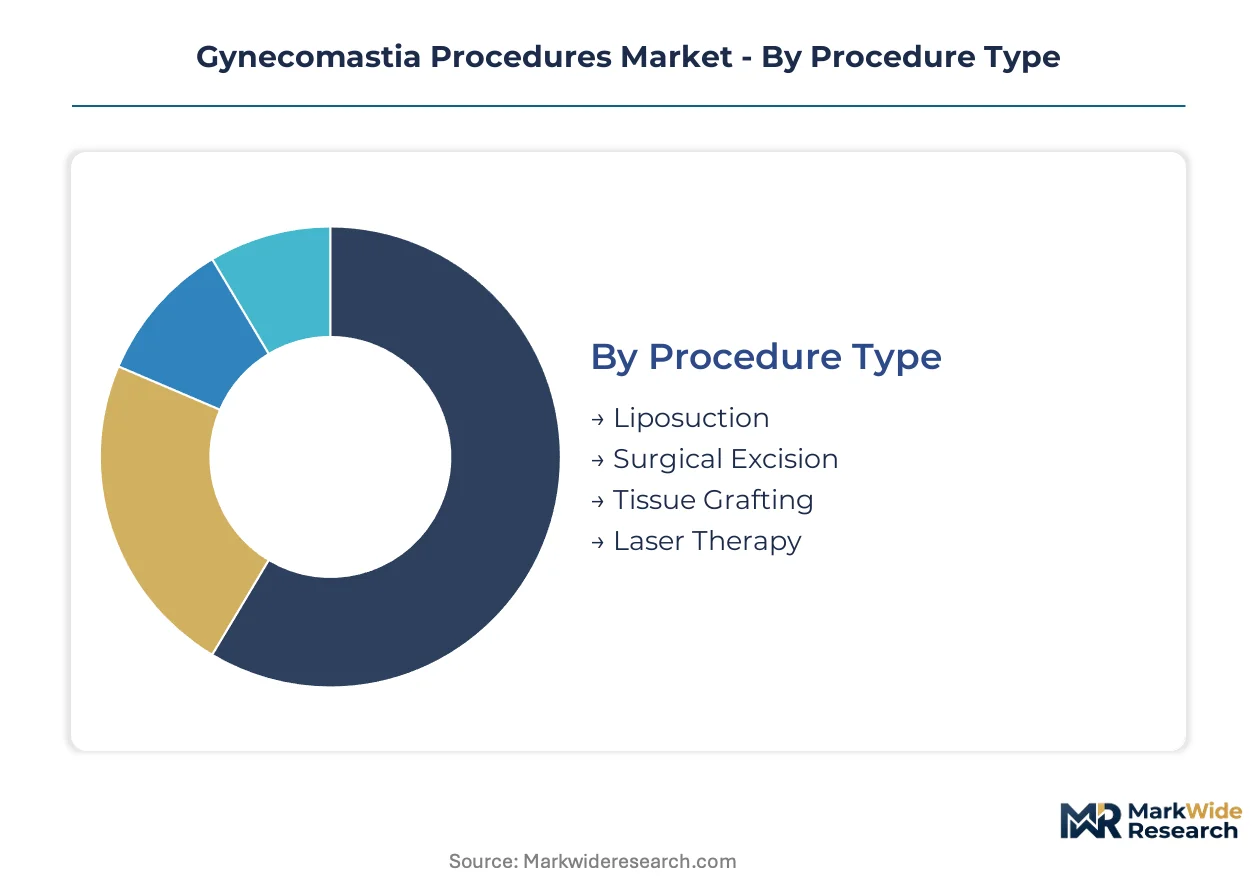
Segmentation in gynecomastia procedures reveals how clinical modality, care setting, patient life stage, and price positioning interact to determine provider economics and patient access. Each dimension carries distinct regulatory, reimbursement, and competitive implications that shape strategic positioning across clinic networks.
Procedure Type:
Patient tolerance for anesthesia, recovery duration, and scar burden drives selection between surgical and energy-based modalities.
- Liposuction:Tumescent infiltration combined with suction-assisted lipectomy removes adipose-dominant tissue through small incisions. Demand concentrates in United States outpatient centers where same-day discharge protocols maximize facility throughput and minimize anesthesia costs.
- Surgical Excision:Direct glandular resection through periareolar or inframammary approaches addresses fibrous tissue unresponsive to liposuction alone. Brazil's hospital-based cosmetic surgery corridors favor this modality for severe cases requiring combined skin tightening.
- Tissue Grafting:Autologous fat transfer and structural grafting for revision cases and chest wall reconstruction.
- Laser Therapy:Selective photothermolysis and laser-assisted lipolysis for minimal-downtime adipocyte reduction.
Volume sits with liposuction; growth tilts toward laser therapy.
Delivery Mode:
Capital requirements and reimbursement classification determine where procedures migrate across the care continuum.
- Outpatient:Ambulatory surgical centers and office-based surgical suites equipped with local anesthesia and monitored sedation capabilities. South Korea's cosmetic surgery districts in Gangnam deploy high-throughput outpatient models with dedicated recovery hospitality infrastructure.
- Private Clinic:Independent cosmetic surgery practices with integrated consultation, procedure, and follow-up capabilities. United States dermatology-plastic surgery hybrid clinics capture premium pricing through concierge service bundling and direct-pay patient bases.
- Inpatient:Hospital-based surgical suites for complex revision cases or comorbid patients requiring overnight monitoring.
- Telemedicine:Virtual consultation, preoperative assessment, and postoperative follow-up platforms.
Procedure economics favor outpatient settings; regulatory scrutiny is intensifying for telemedicine preoperative clearance.
Patient Demographics:
Physiologic tissue composition and psychological motivation vary sharply across age cohorts, dictating modality suitability.
- Young Adults:Men aged 18–34 seeking aesthetic correction of persistent pubertal gynecomastia or lifestyle-resistant adipomastia. Social media-driven body image concerns propel consultation volumes in Brazil, South Korea, and United States metropolitan markets.
- Adolescents:Post-pubertal males under 18 with persistent glandular enlargement beyond 24 months. Conservative management protocols dominate, with surgery reserved for severe psychosocial distress or diagnostic uncertainty.
- Middle-Aged Men:Patients 35–55 addressing androgen decline-related fat redistribution and medication-induced gynecomastia.
- Seniors:Older patients with age-related tissue laxity and comorbidity profiles favoring minimal-intervention approaches.
Young adults generate highest procedure volumes; middle-aged men show steepest expansion trajectory as awareness of hormonal influences spreads.
Cost Tier:
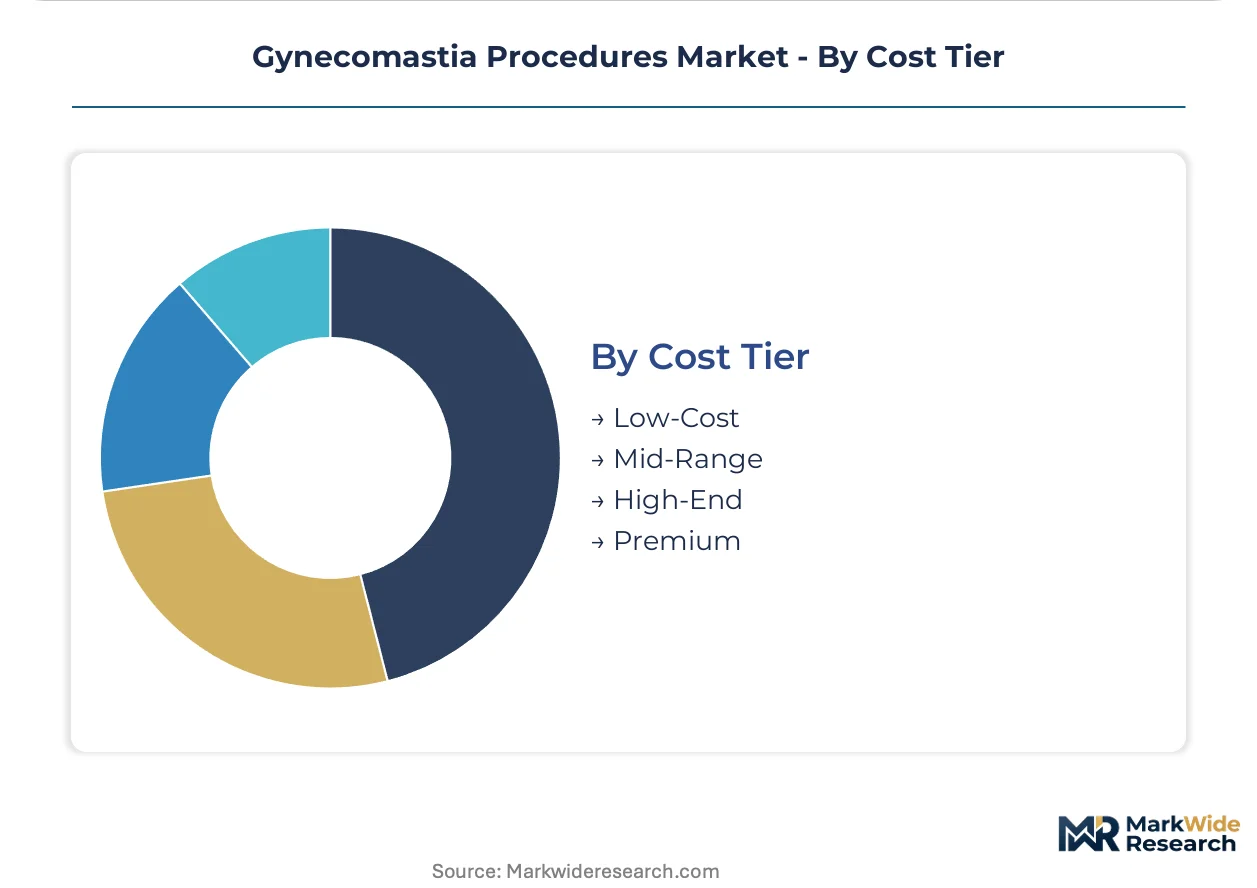
Price positioning segments patients by payment method, facility accreditation, and surgeon credentialing level.
- Mid-Range:Board-certified plastic surgeons in accredited ambulatory centers with transparent bundled pricing. United States markets concentrate demand here as patients trade academic medical center premiums for specialist expertise in private practice settings.
- Premium:Celebrity-affiliated surgeons, proprietary technique branding, and luxury recovery accommodations. South Korea's Gangnam corridor and Brazil's Jardins district command 3–5x standard pricing through reputation-driven patient acquisition.
- Low-Cost:Training institution procedures, non-specialist providers, and medical tourism package deals.
- High-End:Academic medical center specialists with research portfolios and complex case specialization.
Mid-range tier captures dominant volume share; premium positioning gains traction fastest among international medical tourism segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient volumes concentrate in markets where aesthetic medicine infrastructure intersects with high disposable income and medical tourism capacity. The United States, Brazil, South Korea, Germany, and Thailand collectively anchor procedural demand through distinct regulatory and commercial pathways.
United States
Young adult males aged 18–34 drive consultation volumes through social media-mediated body image concerns. FDA 510(k) premarket notifications govern energy-based device clearances, compressing time-to-market for radiofrequency platforms. Outpatient cosmetic surgery centers in Miami, Los Angeles, and New York deploy same-day discharge protocols to maximize facility throughput.
Brazil
Integrated cosmetic surgery corridors attract international patients seeking bundled aesthetic procedures at competitive rates. ANVISA registration frameworks shape market entry timelines for laser and radiofrequency equipment. São Paulo's Jardins district and Rio de Janeiro's Ipanema corridor command premium positioning through reputation-driven patient acquisition.
South Korea
Gangnam's cosmetic surgery district deploys high-throughput outpatient models with dedicated recovery hospitality infrastructure. MFDS device registration maintains parallel but distinct pathways from Western regulators, influencing labeling restrictions. Seoul Capital Area clinics pioneer virtual consultation workflows and influencer partnership strategies for patient acquisition.
Germany
CE marking under EU MDR elevates clinical evidence requirements for energy-based aesthetic devices previously cleared under lighter regimes. Post-market clinical follow-up obligations extend registration timelines and inflate compliance costs. Bavaria and North Rhine-Westphalia host specialized aesthetic surgery networks with established vigilance systems.
Thailand
Medical tourism packages combine gynecomastia correction with recovery hospitality at bundled rates below Western pricing tiers. The national pharmaceutical regulator maintains distinct import licensing for aesthetic energy devices. Bangkok's private hospital clusters compete on international accreditation and English-language care coordination.
Gynecomastia Procedures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with device vendors capturing recurring revenue through platform upgrades while hospital networks compete on patient volume and geographic reach. The vendor base organizes around three strategic archetypes: energy-based platform developers, integrated hospital systems with cosmetic surgery divisions, and specialized aesthetic clinic chains. Consolidation pressure concentrates among device manufacturers seeking expanded indications, while hospital operators pursue geographic densification through ambulatory center networks.
Among energy-based platform developers, InMode Ltd. and Cynosure LLC exemplify the technology-led archetype with proprietary radiofrequency and laser systems. Apollo Hospitals anchors the integrated hospital system model across South Asian markets. Within the specialized clinic tier, Spire Healthcare Group plc occupies a position representing the European private provider archetype with accredited ambulatory networks.
| Leading Market Players |
|---|
| Spire Healthcare Group plc |
| Apollo Hospitals |
| InMode Ltd. |
| Medipol Mega University Hospital |
| Bumrungrad International Hospital |
| Lumenis Ltd. |
| Max Healthcare |
| ID Hospital |
| Cynosure LLC |
| Others |
Value Network & Pricing Analysis
Private clinic networks in the United States and Brazil concentrate purchasing power for energy-based platforms, locking in tiered pricing structures that stratify across premium, standard, and economy levels based on surgeon credentialing and facility accreditation tiers.
Pricing Analysis
Volume concentrates in mid-range liposuction procedures while margins concentrate in premium surgical excision and tissue grafting tiers. Price differentiation hinges on surgeon board certification status and FDA 510(k) device tier, with CE marking under EU MDR adding compliance cost premiums. Pricing pressure stems from compact platform leasing models that compress per-procedure equipment amortization. Young adult cash-pay patients exhibit highest price sensitivity; medical tourism corridors show lowest sensitivity due to bundled recovery hospitality packaging.
Supply Chain Analysis
Radiofrequency and laser device manufacturing clusters in Israel, the United States, and South Korea face tightening technical workforce availability for precision optical and thermal engineering roles. Component sourcing draws from German optical foundries, Japanese semiconductor suppliers, and Chinese precision machining operations. Single-source vulnerability concentrates in solid-state laser diode supply. Distribution runs through specialized aesthetic device distributors with regulatory clearance capabilities, bypassing general medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as device manufacturers pursue downstream control over clinic network equipment deployment and hospital systems pursue upstream captive supply of energy-based platforms.
For Market Incumbents: Extend platform upgrade cycles through software-locked consumable ecosystems that increase switching costs for outpatient cosmetic surgery centers. Deepen backward integration into radiofrequency generator component supply to defend margin position against emerging Asian device vendors. Prioritize MFDS and ANVISA registration acceleration to preempt competitive entry in medical tourism corridors. For New Entrants and Emerging Players: Launch via subscription-based equipment access models targeting standalone cosmetic clinics in secondary United States metropolitan markets and Tier-2 Brazilian cities. White-space opportunity concentrates in transgender-affirming care service lines where autologous reconstruction protocols command premium pricing and face limited specialized competition. Direct-to-consumer digital marketing partnerships with influencer networks offer lowest patient acquisition cost entry vector. For Investors and Strategic Acquirers: The window for entry favors vertically integrated clinic chains with captive device deployment and training infrastructure capabilities. Long-term viability hinges on consolidation of fragmented outpatient cosmetic surgery networks in South Korea and Brazil. Watch for FDA reclassification of energy-based devices from aesthetic to therapeutic indications as the critical inflection signal triggering reimbursement expansion and volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements reshape vendor selection criteria for European distribution partners prioritizing established PMCF programs. |
| Hospital System Partnership | Integrated cosmetic surgery divisions at Apollo Hospitals and Bumrungrad International anchor high-throughput outpatient models with dedicated recovery hospitality. |
| Software Companion Development | Virtual consultation workflows and AI-assisted preoperative assessment tools reduce geographic friction in patient acquisition for Gangnam corridor clinics. |
| Reimbursement Strategy | Therapeutic indication lobbying for persistent pubertal gynecomastia cases could unlock insurance coverage in United States and German markets. |
| Geographic Manufacturing Footprint | Regional assembly capabilities in Brazil and South Korea compress ANVISA and MFDS registration timelines while reducing import duty exposure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plastic surgery department heads, biomedical equipment procurement managers at hospital networks, aesthetic clinic operations directors, and energy-based device regulatory affairs specialists. FDA 510(k) premarket notification databases, ANVISA registration records, MFDS device approval filings, and EU MDR technical documentation repositories provided procedural volume and clearance timeline benchmarks. Bottom-up procedure counts triangulated against top-down device shipment and installed base estimates.
Segmentation granularity modeled procedure type, delivery mode, patient demographic cohort, and cost tier at the country level across the analysis window. CAGRs derived from weighted average of historical procedure growth, device replacement cycles, and demographic penetration curves. Forecast inputs incorporated social media sentiment indices for body image concern tracking and medical tourism package pricing elasticity estimates from Brazilian and Thai corridor operators.
Regulatory reclassification timelines, energy device safety incident reporting thresholds, and macroeconomic disposable income shocks are the dominant revision risks for forecast trajectories. Material deviation in FDA or EU MDR energy-based device classification decisions warrants pause and re-evaluation of volume and pricing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Cosmetic Surgery Products Market