
 Dermatology Imaging Market | 2026-2036
Dermatology Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Imaging Market Intelligence
Equipment leasing and pay-per-scan financing is fragmenting competitive dynamics in dermatology imaging. FotoFinder Systems GmbH leverages its specialized dermoscopy hardware to anchor premium clinic relationships across Europe. GE HealthCare competes through integrated enterprise imaging workflows that extend hospital system penetration. Canfield Scientific, Inc. dominates aesthetic dermatology channels with controlled whole-body photography installations.
Dermatology imaging encompasses optical, acoustic, and computational modalities that capture skin morphology at resolutions spanning macroscopic to cellular scales, typically employing wavelengths from visible to near-infrared spectra for lesion characterization and treatment monitoring. Diagnostic scanners and imaging software together constitute the core revenue architecture, with artificial intelligence emerging as the fastest-expanding technology layer where algorithmic triage tools reshape clinical workflow economics. Multispectral imaging sustains premium positioning in melanoma detection protocols, while mobile devices occupy emerging access points in decentralized care models.
The FDA regulates AI-enabled diagnostic software as Software as a Medical Device, requiring clinical validation studies that lengthen commercialization timelines but elevate barrier thresholds for entrants. In Europe, the MDR and GDPR impose dual compliance burdens on imaging data storage and cross-border telemedicine transmission. Stakeholders must monitor evolving reimbursement codes for algorithm-assisted diagnosis as payors recalibrate coverage frameworks.
Market Dynamics
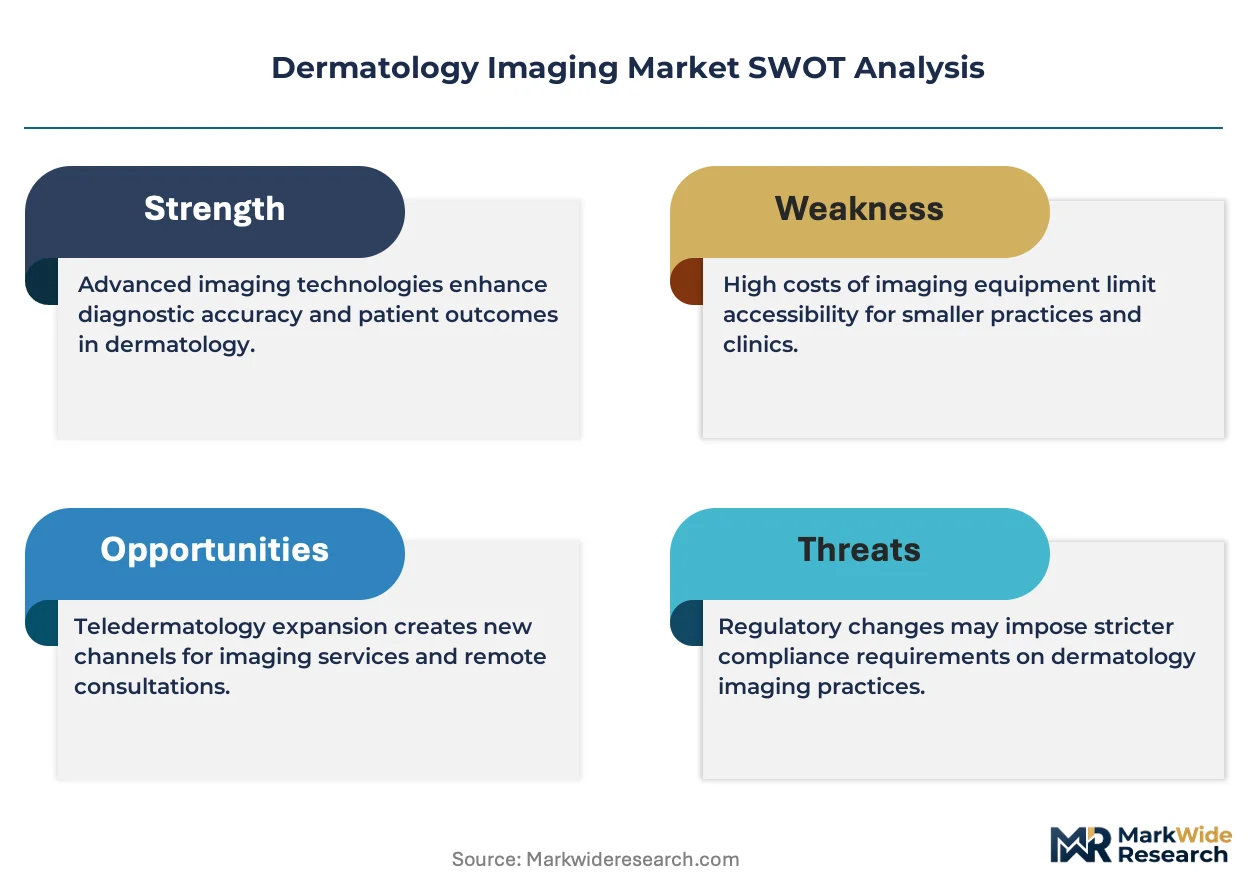
AI-enabled diagnostic software is restructuring competitive economics in dermatology imaging by compressing validation timelines and elevating compliance costs for new entrants. The FDA's Software as a Medical Device framework now demands clinical evidence packages that favor established vendors with regulatory infrastructure.
Growth Catalysts
- Teledermatology reimbursement frameworks:Germany's statutory health insurance now covers remote imaging consultations, expanding addressable patient populations beyond physical clinic footprints.
- Multispectral imaging protocols:Academic medical centers in the United States are embedding advanced lesion characterization into melanoma screening pathways, driving hardware refresh cycles.
- Optical coherence tomography:Non-invasive subsurface imaging is penetrating dermatopathology workflows, reducing biopsy dependency for initial assessments.
Market Restraints
- MDR-GDPR dual compliance:European imaging data storage requirements impose cross-border transmission restrictions that fragment telemedicine scalability.
- Specialized dermoscopy hardware concentration:Premium optical component supply chains cluster in German and Japanese precision manufacturing corridors, creating input bottlenecks.
- Algorithmic validation costs:FDA-mandated prospective studies for AI diagnostic tools extend commercialization timelines beyond typical venture capital horizons.
Strategic Opportunities
- Decentralized care models:Mobile dermoscopy attachments for smartphones are penetrating rural health systems in India where specialist density remains critically low.
- EU AI Act alignment:Conformity assessment pathways for high-risk medical AI create first-mover advantage windows for vendors with established quality management systems.
- Aesthetic dermatology integration:Whole-body photography installations are converging with cosmetic procedure tracking, opening recurring software subscription revenue streams.
Industry Challenges
- Computational pathology skill gaps:Clinical workflows require hybrid training in dermatology and machine learning interpretation that existing residency programs rarely deliver.
- Enterprise imaging interoperability:Hospital system procurement demands HL7-FHIR compliance that fragments smaller vendors lacking health IT integration resources.
- Software update validation:Continuous learning algorithms trigger re-certification obligations under FDA guidance, complicating DevOps cycles for AI-enabled products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Imaging Market |
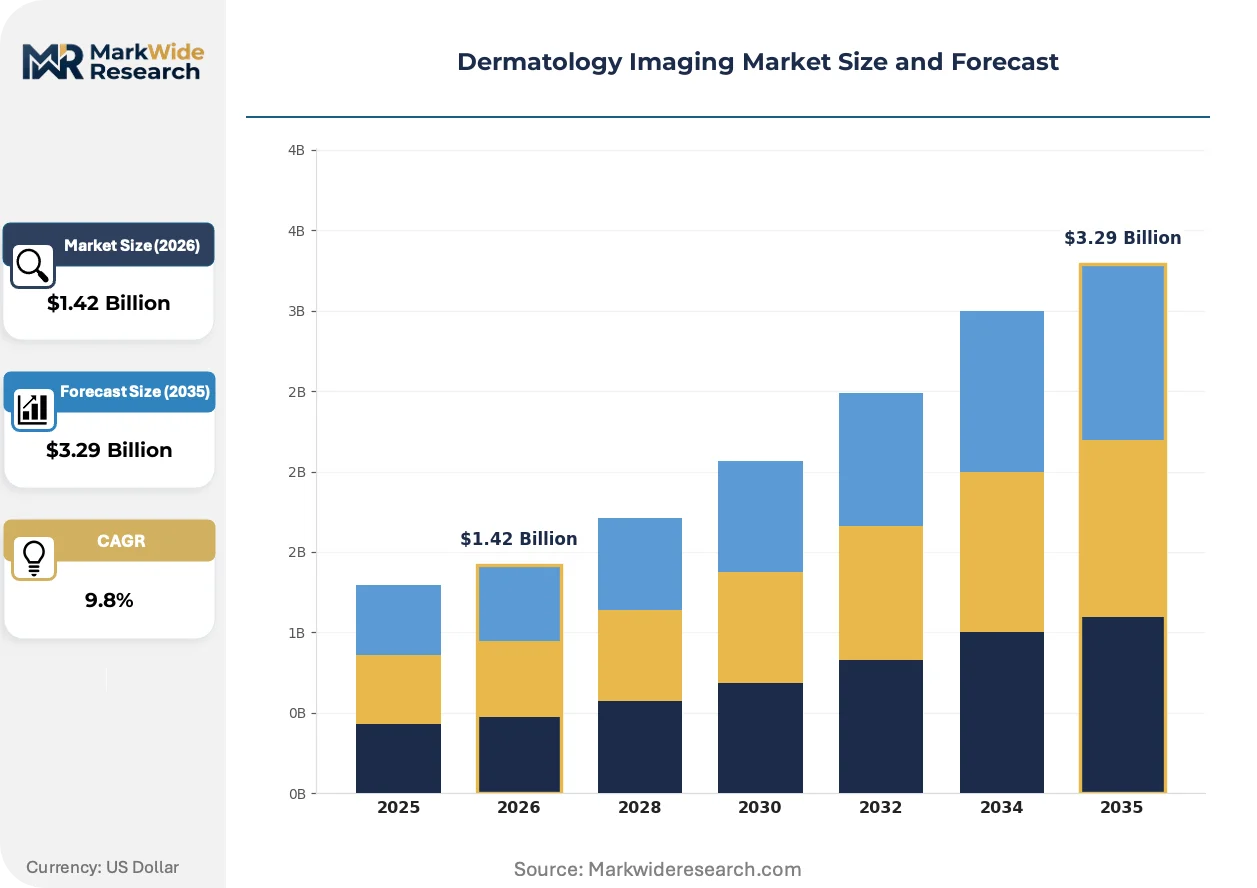
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Cameras, Diagnostic Scanners, Imaging Software, Mobile Devices Technology: Photodynamic Therapy, Ultrasound, Multispectral Imaging, Artificial Intelligence End User: Dermatology Clinics, Hospitals, Research Institutions, Telemedicine Platforms Application: Skin Cancer Diagnosis, Mole Mapping, Psoriasis Assessment, Acne Treatment |
| Companies Covered | FotoFinder Systems GmbH, Cutera, Inc., GE HealthCare, Michelson Diagnostics Ltd, Cynosure Inc., Canfield Scientific, Inc., Alma Lasers Ltd., Courage+Khazaka electronic GmbH, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Imaging Market Strategic Shifts & Innovations
Computational modalities are displacing hardware-centric diagnostic workflows across dermatology imaging, compressing capital requirements while elevating software monetization potential. Three interconnected developments are restructuring value capture in the sector.
Confocal laser scanning microscopy is virtualizing histopathological assessment by delivering cellular-resolution imaging without tissue excision. Academic dermatology departments in the United States and Germany are piloting these systems for real-time margin assessment during Mohs surgery procedures. The technology is virtualizing traditional pathology laboratory workflows into point-of-care diagnostic capabilities that compress turnaround times from days to minutes.
The EU AI Act's high-risk system classification is mandating conformity assessments for diagnostic algorithms that exceed current FDA software validation stringency. European medical device manufacturers are restructuring quality management systems to accommodate post-market performance monitoring obligations. Vendors with existing MDR infrastructure are absorbing compliance costs more efficiently than new entrants lacking notified body relationships.
Subscription-based software licensing is displacing perpetual hardware-software bundles in hospital procurement negotiations. Health system purchasing committees in the United States are prioritizing interoperable platforms with predictable operational expenditure profiles over capital-intensive proprietary installations. This shift concentrates purchasing power among integrated delivery networks with standardized enterprise imaging architectures.
Dermatology Imaging Market Segmentation
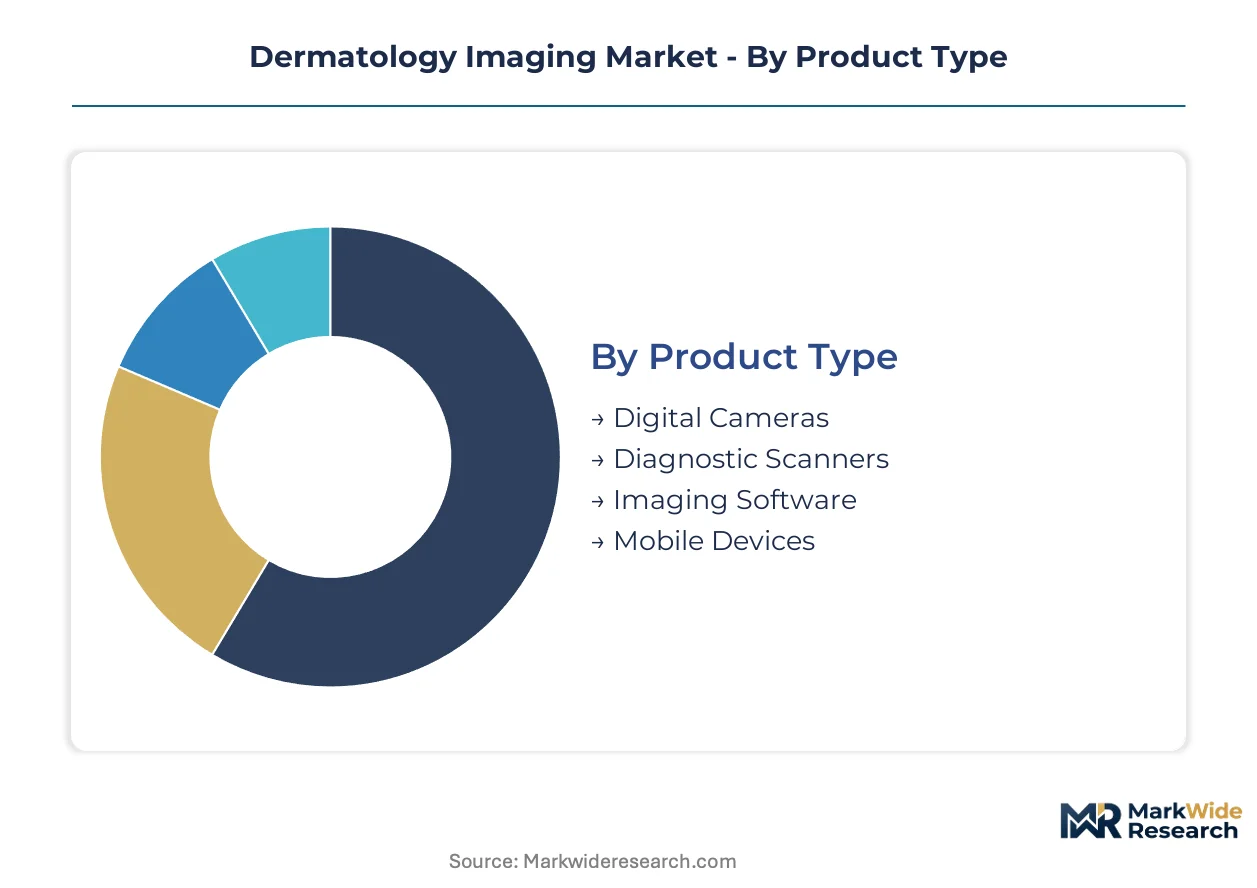
Segmentation in dermatology imaging reveals how capital intensity, clinical setting, and reimbursement pathways fragment purchasing behavior across hardware, software, and service layers. Vendors must align product architecture with distinct validation requirements and workflow integration demands that vary sharply by technology type and end-user environment.
Product Type:
The use-case spectrum spans from high-resolution documentation in academic medical centers to point-of-care triage in decentralized health systems.
- Digital Cameras:Fixed-mount and handheld systems capture standardized lesion photography for longitudinal tracking. Demand clusters in United States dermatology practices where Medicare reimbursement codes reward documented surveillance protocols.
- Diagnostic Scanners:Multispectral and confocal devices deliver cellular-resolution subsurface imaging without biopsy. German university hospitals are embedding these systems into melanoma screening pathways, accelerating hardware refresh cycles despite premium price positioning.
- Imaging Software:Algorithmic triage tools and lesion measurement platforms integrate with electronic health records. Regulatory validation under FDA Software as a Medical Device framework elevates compliance costs for new entrants.
- Mobile Devices:Smartphone dermoscopy attachments penetrate rural health systems in India where specialist density remains critically low. Cost tier positioning enables volume deployment where capital equipment procurement fails.
Established volume favors Diagnostic Scanners; emerging adoption favors Mobile Devices.
Technology:
Cost tier stratification separates capital-intensive hardware modalities from software-centric computational approaches with lower upfront deployment barriers.
- Photodynamic Therapy:Light-activated therapeutic imaging combines diagnosis with treatment for actinic keratosis and superficial skin cancers. United States outpatient surgical centers are expanding reimbursement-driven installation bases.
- Ultrasound:High-frequency acoustic imaging maps lesion depth and vascularity for pre-surgical planning. Japanese dermatology departments pioneered clinical protocols now diffusing into European academic centers.
- Multispectral Imaging:Multi-wavelength capture separates melanin from hemoglobin signatures to improve melanoma detection specificity. The technology commands premium positioning in academic screening protocols but faces price pressure from AI-augmented standard photography.
- Artificial Intelligence:Deep learning algorithms classify lesion probability from consumer-grade images, compressing hardware requirements while elevating software monetization potential. FDA validation timelines favor established vendors with clinical evidence infrastructure.
Margin concentration sits with Artificial Intelligence; hardware refresh cycles sustain Multispectral Imaging.
End User:
Customer type determines procurement authority, with hospital systems demanding enterprise interoperability and independent clinics prioritizing workflow simplicity.
- Dermatology Clinics:Specialized practices drive adoption of dermoscopy systems and whole-body photography for high-volume lesion surveillance. German statutory reimbursement for teledermatology consultations is expanding addressable patient populations beyond physical footprints.
- Hospitals:Integrated delivery networks prioritize HL7-FHIR compliant platforms that embed into enterprise imaging architectures. Procurement committees favor predictable operational expenditure profiles over capital-intensive proprietary installations.
- Research Institutions:Academic medical centers pilot confocal laser scanning microscopy and computational pathology workflows. Validation studies conducted here generate regulatory submission packages for commercial translation.
- Telemedicine Platforms:Asynchronous consultation services demand low-friction image capture and algorithmic triage tools. GDPR cross-border transmission restrictions fragment European scalability despite demand concentration.
Purchasing power concentrates in Hospitals; workflow innovation originates in Dermatology Clinics.
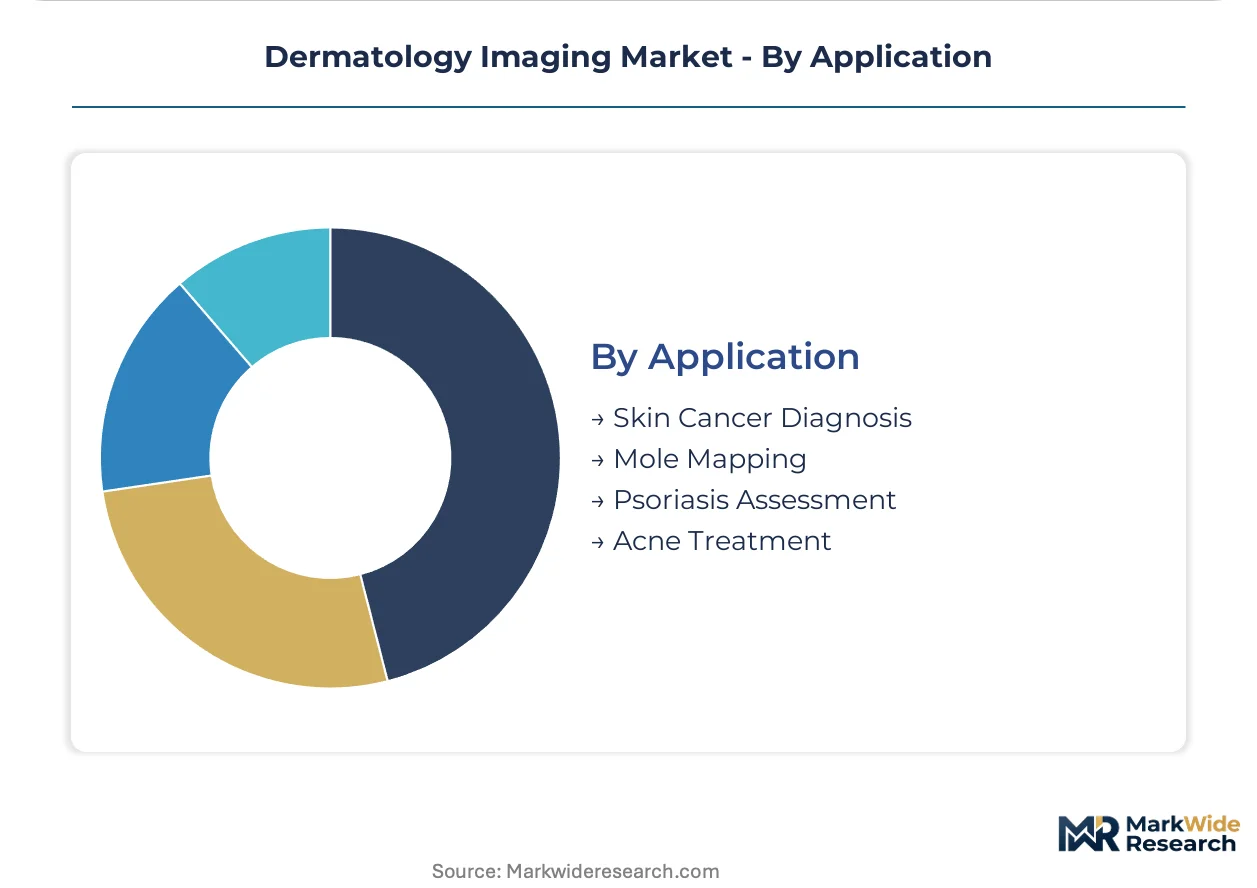
Application:
Maturity differentiation separates established screening protocols with defined reimbursement from emerging indications where clinical utility evidence is still accumulating.
- Skin Cancer Diagnosis:Melanoma and non-melanoma detection represents the primary revenue anchor, with multispectral and AI-augmented modalities competing for screening pathway integration. United States academic centers are embedding advanced characterization into standardized protocols.
- Mole Mapping:Longitudinal photography surveillance tracks lesion evolution over time, creating recurring patient encounter revenue. Australian dermatology practices lead protocol standardization given elevated population risk profiles.
- Psoriasis Assessment:Severity scoring from standardized imaging supports biologic therapy authorization and response monitoring. European payors are piloting algorithm-assisted severity grading for reimbursement decision support.
- Acne Treatment:Lesion counting and inflammation tracking guide therapeutic adjustment in aesthetic dermatology channels. Canfield Scientific dominates this segment with controlled photography installations converging cosmetic procedure tracking.
Revenue scale favors Skin Cancer Diagnosis; expansion velocity favors Psoriasis Assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy shifts in Germany established precedent for teledermatology coverage, accelerating hardware deployment across statutory health insurance networks. The United States FDA's Software as a Medical Device framework lengthens validation timelines but elevates compliance barriers protecting incumbent vendors. Japanese precision manufacturing clusters supply specialized optical components constraining global dermoscopy production capacity.
United States
Academic medical centers in Boston and New York are embedding confocal laser scanning microscopy into Mohs surgery workflows, compressing histopathological turnaround times. The FDA mandates prospective clinical studies for AI diagnostic algorithms under its Software as a Medical Device guidance, extending commercialization timelines beyond typical venture capital horizons. Medicare reimbursement codes reward documented lesion surveillance protocols, concentrating digital camera demand in dermatology practices across the Midwest and Southeast.
Germany
Statutory health insurance reimbursement for remote imaging consultations expanded addressable patient populations beyond physical clinic footprints in Bavaria and North Rhine-Westphalia. The EU AI Act's high-risk system classification mandates conformity assessments exceeding current FDA validation stringency, restructuring quality management systems for notified body relationships. Precision manufacturing corridors in Baden-Württemberg cluster specialized optical component supply chains, creating input bottlenecks for multispectral device production.
Japan
High-frequency ultrasound protocols for pre-surgical lesion depth mapping originated in Tokyo and Osaka dermatology departments before diffusing into European academic centers. The PMDA regulates AI-enabled diagnostic software with clinical evidence requirements that parallel FDA frameworks but accommodate modified predicate device pathways. Manufacturing clusters in the Chubu region supply confocal microscopy optical assemblies constraining global hardware refresh cycle velocity.
India
Smartphone dermoscopy attachments penetrate rural health systems in Maharashtra and Karnataka where dermatologist density remains critically low relative to population burden. The CDSCO regulates medical device software imports with data localization requirements complicating cloud-based algorithm deployment. Telemedicine platforms in Telangana pilot asynchronous consultation services with algorithmic triage tools, though cross-state licensing fragments scalability.
Australia
Dermatology practices in New South Wales and Victoria lead protocol standardization for longitudinal mole mapping surveillance given elevated population melanoma risk profiles. The TGA regulates AI diagnostic software with clinical evidence benchmarks aligned to FDA and European precedents, streamlining multi-jurisdiction submissions for established vendors. Research institutions in Queensland pilot computational pathology workflows generating regulatory submission packages for commercial translation.
Dermatology Imaging Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: specialized dermoscopy hardware fabricators, integrated enterprise imaging platforms, and algorithmic software vendors. Equipment leasing and pay-per-scan financing fragment competitive dynamics by lowering capital barriers for independent clinics. Dominant competitive moves include strategic partnerships between hardware manufacturers and AI developers, plus geographic expansion through distributor networks into decentralized care markets.
Within the specialized hardware tier, FotoFinder Systems GmbH and Canfield Scientific, Inc. exemplify divergent positioning strategies. FotoFinder anchors premium clinic relationships through German-engineered dermoscopy systems, while Canfield occupies aesthetic dermatology channels with controlled photography installations. GE HealthCare represents the integrated platform archetype, leveraging hospital system relationships through enterprise imaging workflow compatibility. Michelson Diagnostics Ltd and Courage+Khazaka electronic GmbH occupy mid-scale specialist positions serving academic and clinical research segments respectively.
| Leading Market Players |
|---|
| FotoFinder Systems GmbH |
| Cutera, Inc. |
| GE HealthCare |
| Michelson Diagnostics Ltd |
| Cynosure Inc. |
| Canfield Scientific, Inc. |
| Alma Lasers Ltd. |
| Courage+Khazaka electronic GmbH |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Japanese precision optical assemblies determines both tiered hardware pricing spreads and supply chain vulnerability across dermatology imaging markets. FDA validation timelines for AI-enabled diagnostic software compress margins in the algorithmic tier while elevating compliance costs that fragment vendor economics.
Pricing Analysis
Certification level (FDA Software as a Medical Device versus CE-MDR tier) creates the primary spread between premium diagnostic scanners and economy mobile attachments. Subscription-based SaaS licensing for algorithmic triage tools displaces perpetual hardware-software bundles, compressing upfront capital requirements while elongating revenue recognition. Pricing pressure stems from hospital procurement committees demanding predictable operational expenditure profiles over proprietary installations. Independent dermatology clinics exhibit highest price sensitivity, while integrated delivery networks absorb premium positioning for enterprise interoperability.
Supply Chain Analysis
Specialized optical feedstocks for confocal microscopy and multispectral sensors concentrate manufacturing in Japan, Germany, and select South Korean precision component corridors. German-engineered dermoscopy hardware draws from Baden-Württemberg precision manufacturing clusters, while Japanese Chubu region suppliers dominate high-resolution lens assemblies. Tariff exposure on semiconductor-based imaging sensors threatens cost structures for AI-enabled device manufacturers. Distribution runs through authorized medical device distributors with regulatory compliance capabilities, bypassing general electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid clinical-engineering talent scarcity constrains algorithmic product development velocity, creating acquisition premiums for teams with FDA submission experience and dermatology workflow integration expertise.
For Market Incumbents: Pre-empt regulatory capture by accelerating MDR notified body relationships ahead of EU AI Act high-risk system classification deadlines. Anchor hospital system relationships through HL7-FHIR compliant enterprise imaging architectures that raise switching costs for competing platforms. Absorb compliance infrastructure investments across broader product portfolios to dilute per-SKU validation burdens. For New Entrants and Emerging Players: Rural health system penetration in India offers the most accessible white-space target, where smartphone dermoscopy attachments bypass capital equipment procurement barriers entirely. Telemedicine platform partnerships in Telangana and Maharashtra provide algorithmic triage deployment channels without direct hardware fabrication requirements. Pursue CDSCO data localization compliance as a differentiated entry credential against cloud-dependent competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors quality management system infrastructure over pure algorithmic performance. Long-term viability hinges on regulatory submission velocity rather than technical benchmark superiority. Target acquisition profiles center on notified body relationships and post-market surveillance capabilities. Monitor FDA guidance document releases on continuous learning algorithms as the critical inflection signal for AI-enabled product economics.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Notified Body Relationship Development | Accelerates EU AI Act conformity assessment pathways for algorithmic diagnostic tools. |
| Hospital System Partnership Formation | Secures procurement committee access for enterprise imaging workflow integration. |
| Software Companion Development | Extends hardware installations into recurring subscription revenue streams. |
| Reimbursement Strategy Execution | Aligns product positioning with Germany's statutory teledermatology coverage frameworks. |
| Geographic Expansion via Distributor Networks | Penetrates decentralized care markets in India without direct sales infrastructure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, hospital biomedical engineers, GPO contracts managers, and AI diagnostic software product leads. Secondary validation drew from FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement code databases, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Calibration against historical validation timelines and reimbursement policy shifts anchored projection models across the analysis window. Segmentation modeling incorporated hardware capital intensity, software deployment architecture, clinical setting workflow requirements, and regional regulatory cluster variations. CAGRs derived from weighted average of technology adoption curves and replacement cycle dynamics specific to dermoscopy hardware refresh rates and algorithmic software update frequencies.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or medical device tariff regimes would shift the trajectory. Forecasts reflect assumptions regarding FDA software validation timeline stability and EU AI Act implementation pacing. Cross-checking against CMS reimbursement code revision schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Computed Tomography Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market