
 North America Cosmetic Surgery Market | 2026-2036
North America Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cosmetic Surgery Market Insights
Non-surgical procedure revenue is tilting toward minimally invasive modalities as patients prioritize shorter recovery windows. Allergan Aesthetics (AbbVie) anchors its position through captive supply of botulinum toxin portfolios across North American dermatology channels. Galderma S.A. differentiates via R&D intensity in biostimulatory fillers and integrated skincare-to-injectable ecosystems. Stryker Corporation dominates surgical instrumentation for body contouring suites in ambulatory settings.
Cosmetic surgery encompasses elective and reconstructive procedures performed to reshape or enhance normal structures of the body, utilizing technologies such as laser-assisted lipolysis, radiofrequency skin tightening, and hyaluronic acid-based dermal fillers with particle sizes ranging from 200 to 1000 microns for varying tissue planes. Its primary commercial purpose centers on aesthetic outcome optimization with measurable safety profiles. Invasive procedures maintain the largest revenue pool due to high per-procedure pricing, while non-invasive services represent the fastest-expanding segment driven by medical spa channel proliferation. Botox procedures occupy the dominant share within procedure type breakdowns, though liposuction sustains premium positioning in surgical suites.
FDA regulates all aesthetic devices and injectable biologics through premarket notification or approval pathways, directly conditioning market entry timelines and clinical evidence requirements for manufacturers. State medical boards across California, Texas, and Florida impose facility accreditation standards that shape clinic operating costs and geographic expansion feasibility. The Federal Trade Commission monitors advertising claims in direct-to-consumer aesthetic marketing, constraining how providers communicate efficacy outcomes. Stakeholders must monitor evolving state-level scope-of-practice debates that could expand or restrict nurse practitioner and physician assistant autonomy in injectable administration.
Market Dynamics
Medical spa channel expansion is compressing traditional surgical suite utilization as outpatient aesthetic services capture procedure volume previously directed toward hospital-based settings. This structural reconfiguration is redistributing capital deployment across the provider ecosystem.
Growth Catalysts
- Botulinum toxin portfolio standardization:Dermatology channels in California and Texas now demand consistent formulation availability across multi-site clinic networks, consolidating procurement patterns toward integrated supply relationships.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for novel hyaluronic acid formulations is compressing commercialization timelines for injectable biologics targeting mid-dermal tissue planes.
- Radiofrequency skin tightening:Ambulatory surgery centers in Florida are integrating this technology into combination treatment protocols, expanding addressable procedure mix beyond traditional surgical modalities.
Market Restraints
- Biostimulatory filler input concentration:Poly-L-lactic acid supply chains concentrate among limited European specialty chemical manufacturers, creating vulnerability to batch consistency disruptions.
- State facility accreditation heterogeneity:Divergent operating standards between California, Texas, and Florida medical boards inflate multi-state clinic network compliance costs.
- Laser-assisted lipolysis substitution pressure:Non-invasive cryolipolysis systems are capturing abdominal contouring cases previously requiring surgical intervention.
Strategic Opportunities
- Texas metropolitan corridor penetration:Dallas-Fort Worth and Houston exhibit clinic density gaps relative to disposable income-adjusted demand potential for premium injectable services.
- Integrated skincare-to-injectable ecosystems:Pre- and post-procedure topical regimens represent attach-rate expansion opportunity within medical spa channel workflows.
- Nurse practitioner scope expansion:Legislative debates in Florida and Texas could extend autonomous injectable administration authority, amplifying provider supply without physician labor cost structure.
Industry Challenges
- Injectable administration certification timelines:State medical board supervised training hour requirements vary significantly across California, Texas, and Florida, complicating standardized workforce development.
- Device-software integration complexity:Next-generation radiofrequency systems require coordinated hardware and algorithm updates that strain legacy clinic IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cosmetic Surgery Market |
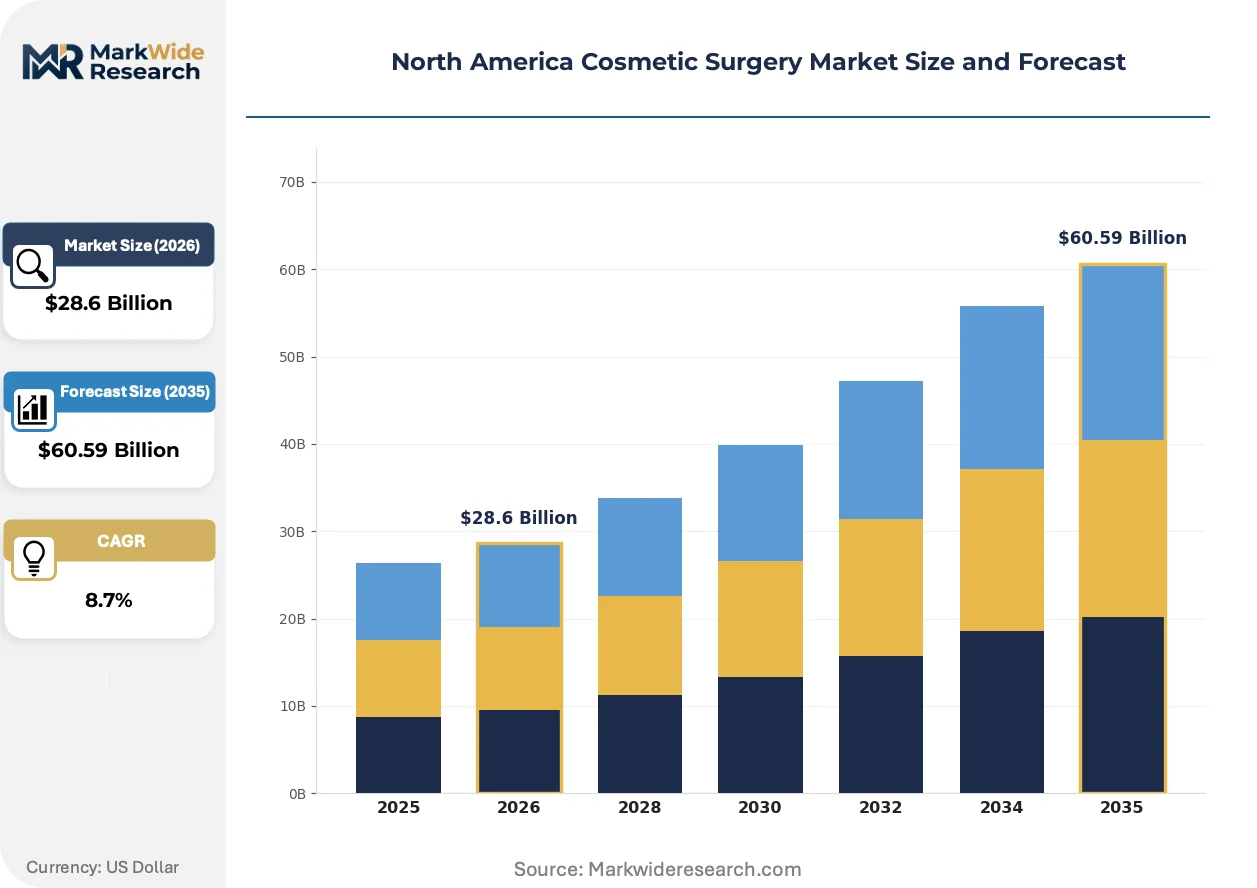
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Botox, Liposuction, Rhinoplasty, Facelift Service Type: Invasive, Non-Invasive, Minimally Invasive, Reconstructive End User: Clinics, Hospitals, Ambulatory Surgery Centers, Medical Spas Demographics: Men, Women, Teens, Elderly |
| Companies Covered | Allergan Aesthetics (AbbVie), Galderma S.A., Johnson & Johnson, Integra Life Sciences, Revance Therapeutics Inc., Merz, Stryker Corporation, Evolus, InMode, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cosmetic Surgery Market Trends and Innovations
Minimally invasive modalities are actively displacing traditional surgical protocols as recovery window compression becomes the dominant patient selection criterion across North American aesthetic channels.
High-intensity focused ultrasound technology for subdermal tissue lifting is migrating from academic medical center demonstration settings to high-volume medical spa environments. Dermatology groups in Southern California are deploying this modality at scale within standalone aesthetic facilities. The technology is migrating from premium positioning toward mid-market accessibility, compressing average revenue per procedure while expanding total addressable treatment volume.
Federal Trade Commission scrutiny of direct-to-consumer efficacy claims is intensifying enforcement actions against before-and-after imagery in social media marketing. This regulatory pressure is forcing providers toward standardized photography protocols and third-party outcome validation. California-based clinic networks are responding by centralizing compliance functions and pre-approving all patient-facing promotional materials.
Subscription-based maintenance programs for neurotoxin and filler regimens are displacing single-session transactional purchasing in affluent urban markets. Medical spas in Manhattan and Beverly Hills are bundling quarterly touch-up appointments with skincare product allotments. This behavioral shift is most visible in coastal metropolitan corridors where patient lifetime value calculations now dominate customer acquisition strategy design.
North America Cosmetic Surgery Market Segmentation
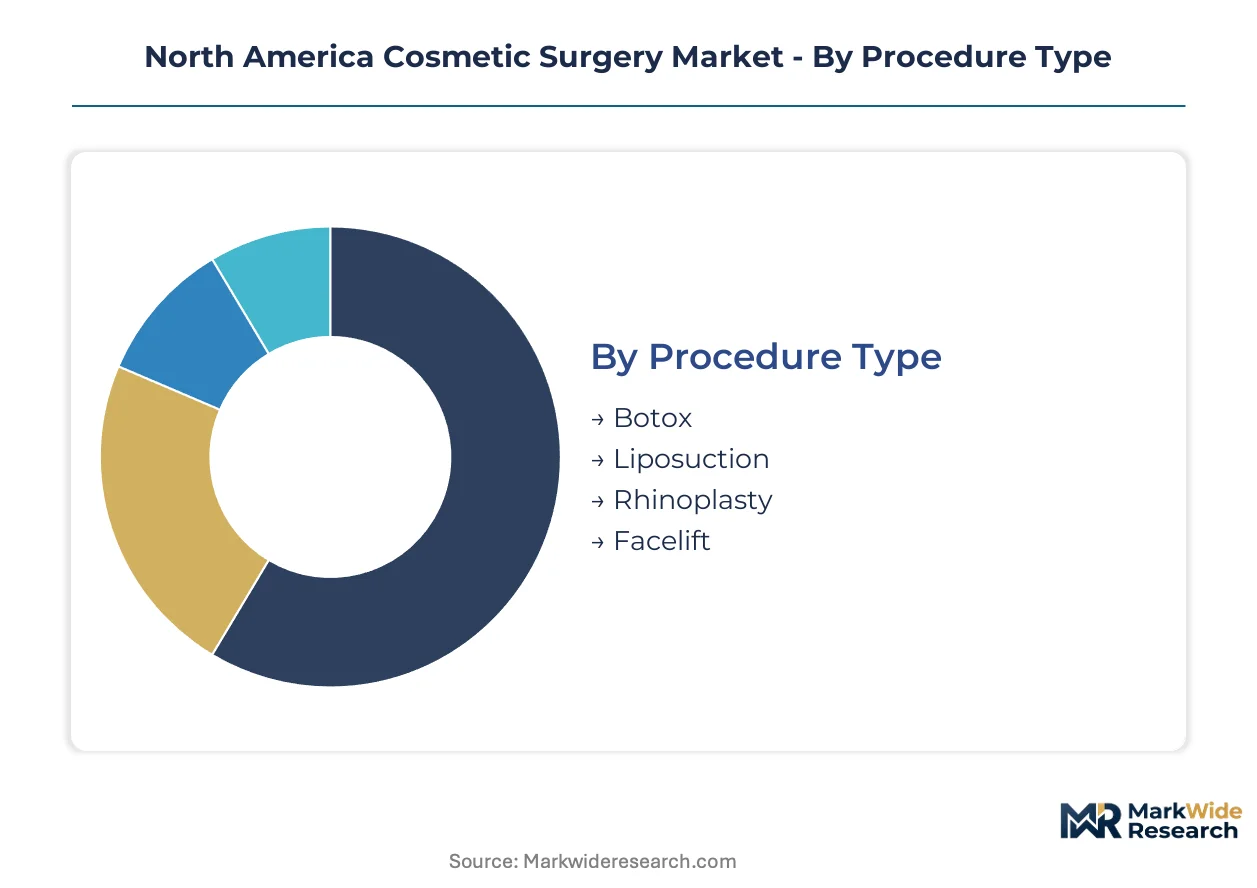
Segmentation in North American cosmetic surgery reveals how procedure economics, service modality, and channel configuration redistribute revenue across provider ecosystems. Each dimension captures distinct procurement patterns and regulatory exposure that shape competitive positioning.
Procedure Type:
Cost tier stratification across procedure types concentrates revenue in high-unit-price surgical interventions while neurotoxin injections capture volume.
- Botox:Botulinum toxin formulations target dynamic rhytides through neuromuscular junction blockade with effects persisting three to four months. Demand clusters in California and Texas medical spa channels where quarterly maintenance regimens dominate patient scheduling patterns.
- Liposuction:Suction-assisted lipectomy removes adipose deposits via tumescent infiltration and cannula aspiration, commanding premium pricing in ambulatory surgery center settings. Florida facilities report highest per-procedure margins due to combination protocol bundling with radiofrequency skin tightening.
- Rhinoplasty:Open and closed techniques reshape nasal osseocartilaginous framework for aesthetic or functional correction.
- Facelift:Superficial musculoaponeurotic system suspension elevates midface and cervicofacial tissues.
Botox holds installed capacity. Liposuction is rotating up the share rankings.
Service Type:
Application intensity varies by invasiveness level, with outpatient modalities compressing recovery windows and expanding addressable patient pools.
- Invasive:Surgical procedures requiring general anesthesia and tissue excision maintain revenue concentration through high per-case pricing. Hospital-based suites in Texas and California capture complex revision cases requiring overnight observation.
- Non-Invasive:Energy-based devices and topical protocols target superficial tissue layers without breach of skin integrity. Medical spas across Florida deploy cryolipolysis and intense pulsed light systems at volume throughput rates exceeding surgical scheduling capacity.
- Minimally Invasive:Needle or micro-incision techniques deliver implants or energy with local anesthesia.
- Reconstructive:Restoration of form and function following trauma, oncologic resection, or congenital anomaly correction.
Invasive procedures hold installed capacity. Non-Invasive is climbing the fastest.
End User:
Channel volume distribution reflects capital requirements, regulatory burden, and patient convenience preferences across settings.
- Clinics:Physician-owned aesthetic practices combine consultation, procedure, and follow-up in dedicated facilities. California dermatology groups leverage multi-site networks to standardize injectable procurement and centralize compliance functions.
- Medical Spas:Hybrid medical-aesthetic facilities supervised by licensed physicians deploy non-physician providers for routine services. Texas metropolitan corridors exhibit fastest channel expansion as nurse practitioner scope debates create labor supply flexibility.
- Hospitals:Academic and community medical centers maintain surgical suites for complex cases requiring anesthesia support.
- Ambulatory Surgery Centers:Standalone facilities optimize throughput for same-day surgical procedures with lower overhead than hospital settings.
Clinics hold installed capacity. Medical Spas is rotating up the share rankings.
Demographics:
Customer type segmentation captures differential price sensitivity, procedure preference, and lifetime value potential across age and gender cohorts.
- Women:Female patients drive majority volume across all service categories, with concentration in facial injectables and body contouring. Beverly Hills and Manhattan medical spas target this demographic through subscription maintenance programs bundling neurotoxin with skincare allotments.
- Men:Male aesthetic demand concentrates in hair restoration, gynecomastia correction, and jawline definition procedures. Texas clinics report fastest male patient acquisition rates for minimally invasive facial sculpting.
- Teens:Rhinoplasty and otoplasty represent primary approved indications with parental consent requirements.
- Elderly:Patients over sixty-five pursue functional restoration and age-appropriate aesthetic maintenance.
Women hold installed capacity. Men is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply by sub-region. California and Texas concentrate high-volume medical spa channels, while Canada emphasizes reconstructive procedures within hospital networks and Mexico attracts cross-border surgical tourism seeking cost arbitrage on invasive interventions.
United States
California and Texas dominate injectable volume through dense medical spa networks in Los Angeles, Beverly Hills, Dallas-Fort Worth, and Houston. FDA 510(k) clearance pathways for novel hyaluronic acid formulations accelerate product launches targeting mid-dermal tissue planes. Southern California dermatology groups deploy high-intensity focused ultrasound technology at scale within standalone aesthetic facilities, compressing average revenue per procedure while expanding treatment volume.
Canada
Provincial health systems in Ontario and Quebec channel reconstructive procedures through hospital-based suites, creating distinct demand bifurcation from elective aesthetic services. Health Canada regulates aesthetic devices through premarket licensing requirements that parallel FDA timelines but impose additional bilingual labeling mandates. Toronto and Vancouver concentrate private clinic networks serving affluent demographics seeking premium injectable maintenance regimens.
Mexico
Tijuana, Cancun, and Mexico City attract North American patients seeking cost-advantaged liposuction and rhinoplasty procedures outside US pricing structures. COFEPRIS regulates medical devices and biologics through registration pathways that foreign manufacturers navigate for market entry. Baja California and Quintana Roo have developed specialized surgical tourism infrastructure with ambulatory facilities catering to cross-border clientele.
North America Cosmetic Surgery Market Competitive Landscape
Capability concentration sits with integrated pharmaceutical-aesthetic conglomerates; scale advantage sits with diversified medical device manufacturers. The market structures around three tiers: captive biologics suppliers controlling botulinum toxin and filler formulations, surgical instrumentation specialists dominating body contouring suites, and emerging energy-based device developers capturing medical spa channel expansion. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic licensing of combination therapy protocols.
Within the integrated biologics tier, Allergan Aesthetics (AbbVie) and Galderma S.A. occupy positions anchoring neurotoxin and dermal filler procurement patterns across multi-site dermatology networks. Stryker Corporation represents the surgical instrumentation archetype with presence in ambulatory body contouring settings. These three entities exemplify divergent strategic postures: pharmaceutical-captive supply relationships versus device-centric capital equipment deployment.
| Leading Market Players |
|---|
| Allergan Aesthetics (AbbVie) |
| Galderma S.A. |
| Johnson & Johnson |
| Integra Life Sciences |
| Revance Therapeutics Inc. |
| Merz |
| Stryker Corporation |
| Evolus |
| InMode |
| Others |
Pricing and Supply Chain Analysis
Los Angeles-Long Beach port congestion surcharges on European-sourced hyaluronic acid raw materials cascade through California medical spa networks, amplifying price spreads between premium Allergan-procured formulations and standard-grade alternatives while compressing margins on mid-tier injectable bundles.
Pricing Analysis
Long-term offtake contracts dominate botulinum toxin procurement across multi-site dermatology networks, locking in volume commitments that insulate large clinic chains from spot-market volatility in poly-L-lactic acid supplies. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised surgical suites from nurse-administered medical spa services and budget cryolipolysis chains. Cost compression in standard-tier hyaluronic acid fillers intensifies because Galderma and Revance Therapeutics are expanding manufacturing scale. Price-sensitive patients cluster in Texas metropolitan corridors, while least-sensitive demand concentrates in Beverly Hills and Manhattan subscription maintenance programs.
Supply Chain Analysis
Export control regimes on laser-assisted lipolysis device components limit flows of precision optical assemblies from Germany and Japan into US ambulatory surgery centers, forcing InMode and domestic competitors toward dual-source qualification strategies. Active pharmaceutical ingredient production for biostimulatory fillers concentrates in France, Italy, and South Korea, with hyaluronic acid fermentation drawing from bacterial culture stocks and cross-linked gel processing equipment. Single-source vulnerability pervades poly-L-lactic acid granule supply from European specialty chemical manufacturers. Distribution runs through integrated pharmaceutical-aesthetic conglomerates with captive wholesale channels, though independent medical spa buying groups are consolidating procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated dermatology networks and medical spa chains that command volume-based procurement terms, fragmenting pricing power previously concentrated with biologics manufacturers.
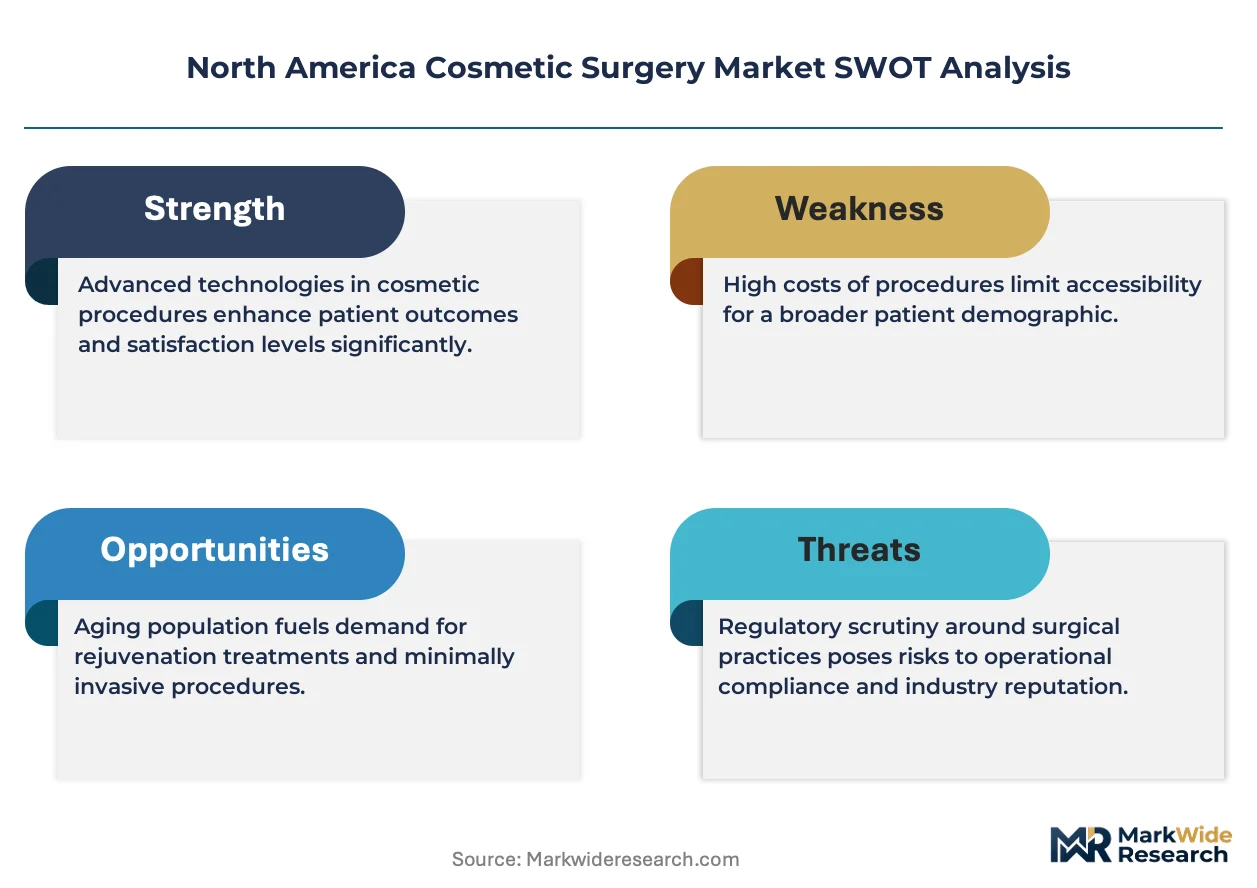
For Market Incumbents: Insulate botulinum toxin market position through backward integration into bacterial fermentation capacity and exclusive long-term supply agreements with California and Texas clinic networks. The emerging threat of high-intensity focused ultrasound devices for subdermal lifting demands accelerated R&D investment in combination therapy protocols that bundle neurotoxin maintenance with energy-based tightening. For New Entrants and Emerging Players: Dallas-Fort Worth corridor underpenetration relative to disposable income-adjusted demand offers white-space entry for premium injectable services with streamlined nurse practitioner administration models. Florida's scope-of-practice legislative debates create regulatory arbitrage opportunity for autonomous injectable clinic formats. Target ambulatory surgery center partnerships as the go-to-market angle, bypassing saturated medical spa channel acquisition costs. For Investors and Strategic Acquirers: Mid-scale energy-based device developers with FDA 510(k) clearance momentum represent the priority acquisition archetype for portfolio exposure to medical spa channel expansion. Long-term viability across the analysis window hinges on software-hardware integration capabilities that sustain recurring revenue streams beyond initial capital equipment sales. Monitor FDA enforcement action intensity against direct-to-consumer advertising claims as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Captive poly-L-lactic acid production reduces batch consistency risk from European chemical manufacturers. |
| Nurse Practitioner Scope Expansion | Texas and Florida legislative shifts amplify provider supply without physician labor cost structure. |
| Combination Therapy Protocol Licensing | Bundled radiofrequency skin tightening with liposuction commands premium pricing in Florida ASCs. |
| Subscription Maintenance Program Rollout | Quarterly neurotoxin touch-ups with skincare allotments lock in patient lifetime value in Manhattan. |
| Software-Defined Device Development | Algorithm-updatable radiofrequency systems strain legacy clinic IT infrastructure but enable recurring revenue. |
Research Methodology
Initial hypotheses were tested against primary input from medical spa operators, dermatology group procurement directors, biomedical device engineers, and state medical board administrators and refined through secondary validation against FDA 510(k) clearance databases, Health Canada premarket licensing records, GPO contracts for ambulatory surgery centers, and SEC filings from AbbVie and Stryker. Bottom-up procedure volume estimates from California, Texas, and Florida clinic networks triangulated with top-down market sizing from pharmaceutical-aesthetic conglomerate revenue disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling procedure type segmentation by invasiveness level, service modality by recovery window, end-user channel by capital intensity, and demographic cohort by lifetime value potential. CAGRs derived from fitted growth curves applied to medical spa channel expansion rates and FDA clearance timeline compression. Forecast inputs incorporated state-level scope-of-practice legislative tracking and biostimulatory filler manufacturing capacity announcements.
Practitioners should monitor FDA enforcement priority shifts on direct-to-consumer advertising, poly-L-lactic acid supply disruptions from European manufacturers, and Texas scope-of-practice legislative outcomes for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
US Gender Reassignment Surgery Market