
 Breast Reconstruction Surgery and Treatment Market | 2026-2036
Breast Reconstruction Surgery and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Reconstruction Surgery and Treatment Market Outlook
A capital-intensity divergence between high-volume implant manufacturers and specialized autologous tissue providers is reorganizing competitive dynamics in breast reconstruction. Allergan (AbbVie) leverages its broad silicone implant portfolio and direct-to-surgeon training infrastructure to sustain share in hospital systems. Mentor Worldwide LLC (Johnson & Johnson) anchors its position through extensive clinical data libraries and long-term safety registries that differentiate its textured and smooth device lines. Establishment Labs Holdings Inc. competes on proprietary silicone gel technologies and regional manufacturing scale in Latin American markets.
Breast reconstruction surgery and treatment encompasses surgical restoration of breast form following mastectomy, lumpectomy, or congenital absence, employing silicone or saline-filled implants, autologous tissue transfer, or combined approaches with specific shell surface textures, gel cohesivity grades, and pocket placement techniques to achieve aesthetic symmetry and patient-reported quality-of-life outcomes. Flap procedures command premium positioning in academic centers due to durable vascularized tissue outcomes and favorable long-term complication profiles relative to implant-dependent methods. Implant-based reconstruction occupies the highest procedural volume segment, though nipple reconstruction represents a concentrated margin pool as microsurgical refinement techniques diffuse from specialized centers into broader surgical practice.
The FDA enforces rigorous premarket approval pathways and post-approval safety surveillance through the National Breast Implant Registry, while the EU Medical Device Regulation mandates enhanced clinical evidence and unique device identification tracking across European markets. These frameworks elevate compliance costs but simultaneously filter out marginal competitors and reinforce demand for transparent safety data among hospital procurement committees. Stakeholders must monitor evolving regulatory divergence between FDA and EMA silicone device classifications, as divergent approval timelines will reshape geographic launch sequencing and manufacturing capacity allocation decisions.
Market Dynamics
Pre-pectoral implant placement protocols are compressing operative timeframes and reducing postoperative pain, forcing hospital procurement committees to reevaluate supplier qualification criteria around surgical training infrastructure and device compatibility matrices.
Growth Catalysts
- Insurance Mandate Expansion:The Women's Health and Cancer Rights Act in the United States mandates coverage parity, eliminating cost barriers that previously suppressed procedural volumes in underserved patient populations.
- Autologous Flap Maturation:Deep inferior epigastric perforator techniques now achieve superior aesthetic outcomes with reduced donor-site morbidity, pulling demand toward academic medical centers with microsurgical capability.
- Silicone Gel Cohesivity Grades:Fifth-generation cohesive gel formulations reduce capsular contracture rates and enable anatomic shaping, expanding reconstructive options beyond traditional round implants.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade silicone precursor costs fluctuate with petrochemical markets, compressing margins for implant manufacturers without backward integration into raw material supply.
- Regulatory Divergence Friction:FDA premarket approval timelines and EU MDR clinical evidence requirements create asynchronous launch windows, forcing manufacturers to maintain parallel compliance teams.
- Allograft Substitution Pressure:Acellular dermal matrices from human and porcine sources compete for tissue expander coverage applications, threatening synthetic mesh revenue pools in certain procedural niches.
Strategic Opportunities
- Fat Grafting Convergence:Combination approaches merging autologous adipose transfer with implant-based reconstruction address contour irregularities, opening premium positioning in aesthetic-focused private practices.
- Nipple-Sparing Protocol Diffusion:Oncoplastic surgical techniques preserving nipple-areolar complexes expand eligible patient pools beyond traditional mastectomy candidates, requiring specialized retractor and marking instrument ecosystems.
- Post-Mastectomy Radiation Sequencing:Immediate reconstruction in radiotherapy-eligible patients creates demand for radiation-tolerant expander technologies and specialized surgical planning software.
Industry Challenges
- Microsurgical Talent Pipeline:Perforator flap proficiency requires fellowship-trained surgeons, and training program capacity constraints limit technique diffusion outside major metropolitan clusters.
- Device Traceability Infrastructure:Unique device identification mandates under EU MDR and FDA registry requirements force hospital IT system upgrades and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Reconstruction Surgery and Treatment Market |
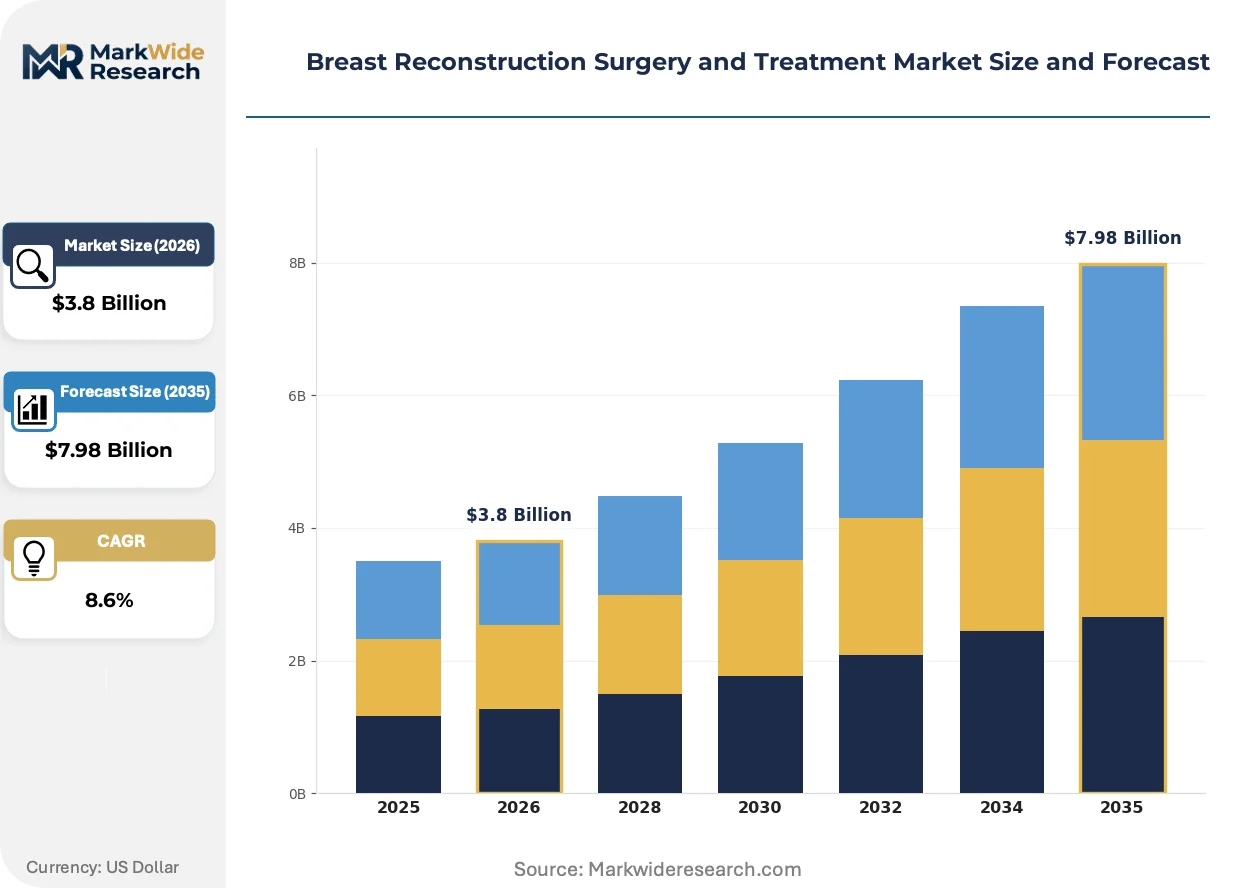
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Tissue Expanders, Flap Procedures, Nipple Reconstruction Delivery Mode: Outpatient, Inpatient, Telehealth, Home Care End User: Hospitals, Surgical Centers, Clinics, Rehabilitation Facilities Indication: Cancer Recovery, Congenital Defects, Trauma Repair, Aesthetic Improvement |
| Companies Covered | Allergan (AbbVie), Mentor Worldwide LLC (Johnson & Johnson), Sientra, Inc., Establishment Labs Holdings Inc., GC Aesthetics Ltd, POLYTECH Health & Aesthetics GmbH, Integra LifeSciences Corporation, RTI Surgical, Groupe Sebbin SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Reconstruction Surgery and Treatment Market Strategic Shifts
Three interconnected developments are compressing the traditional reconstruction pathway from months to weeks while elevating patient-reported outcome metrics as central purchasing criteria.
Pre-pectoral implant placement is bifurcating the reconstructive algorithm into muscle-sparing and submuscular tracks. High-volume community hospitals are adopting this approach for its reduced postoperative narcotic requirements and faster return to baseline function. The technique is compressing demand for traditional tissue expander sequences and forcing manufacturers to develop specialized pre-pectoral-compatible device portfolios.
EU MDR implementation is elevating clinical evidence thresholds for silicone breast devices. Manufacturers must submit post-market surveillance data and maintain EUDAMED registration, filtering out marginal competitors without robust safety registries. Academic medical centers in Germany, France, and Italy are prioritizing suppliers with established MDR technical documentation.
Patient-reported outcome measures now dominate surgeon selection and device procurement conversations. Hospital value-analysis committees in the United States are integrating BREAST-Q scores into supplier scorecards, displacing pure cost-per-procedure metrics. This behavioral shift is most visible in California and New York health systems with established enhanced recovery after surgery protocols.
Breast Reconstruction Surgery and Treatment Market Segmentation
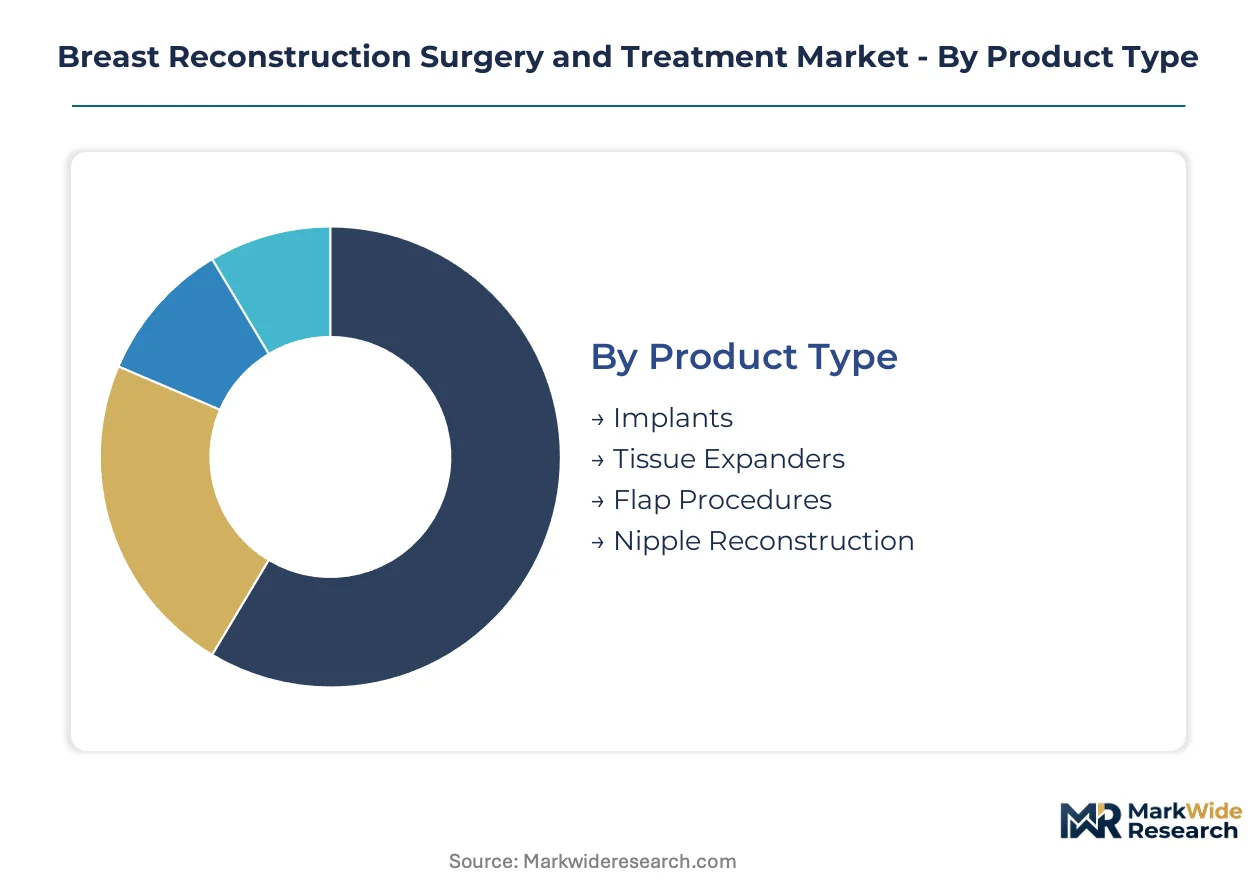
Product configuration and care setting selection in breast reconstruction determine reimbursement pathways, regulatory scrutiny intensity, and capital equipment requirements. Surgeons, hospital administrators, and payers each prioritize distinct segment attributes when evaluating treatment options.
Product Type:
FDA premarket approval pathways and EU MDR clinical evidence mandates create divergent competitive barriers across implant versus autologous tissue categories.
- Implants:Silicone gel-filled and saline-filled devices with varying shell textures and gel cohesivity grades. Demand concentrates in high-volume community hospitals in the United States seeking standardized, reimbursable procedures with predictable operative timeframes.
- Tissue Expanders:Temporary inflatable devices enabling gradual skin envelope expansion prior to permanent implant placement. Academic medical centers in Germany and France prioritize radiation-tolerant expander portfolios for immediate reconstruction in adjuvant therapy-eligible patients.
- Flap Procedures:Autologous tissue transfer techniques including DIEP and TRAM flaps requiring microsurgical expertise.
- Nipple Reconstruction:Microsurgical and graft-based techniques for areolar complex restoration.
Established volume favors Implants; emerging adoption favors Flap Procedures.
Delivery Mode:
Cost tier stratification separates capital-intensive facility-based care from emerging remote monitoring and home-based recovery protocols.
- Outpatient:Ambulatory surgical procedures with same-day discharge protocols. United States surgical centers in Texas and Florida exploit outpatient reimbursement differentials to capture pre-pectoral implant placement volumes previously routed to inpatient settings.
- Inpatient:Overnight hospital stays for complex flap reconstructions or complication management. Major metropolitan academic centers in New York and California maintain inpatient preference for microsurgical cases requiring intensive postoperative monitoring.
- Telehealth:Remote consultation and postoperative follow-up via video platforms.
- Home Care:Post-surgical recovery and wound management in residential settings.
Reimbursement compression favors Outpatient; clinical complexity favors Inpatient.
End User:
Customer type determines procurement authority, with hospital value-analysis committees wielding distinct criteria compared to independent surgical center owners.
- Hospitals:Integrated health systems with centralized procurement and registry participation mandates. United States hospital networks in the Midwest and Southeast prioritize suppliers with FDA-established safety registries and National Breast Implant Registry compatibility.
- Surgical Centers:Independent or hospital-affiliated ambulatory facilities focused on throughput optimization.
- Clinics:Office-based practices handling consultation, surveillance, and minor procedures.
- Rehabilitation Facilities:Post-acute care centers managing functional recovery and lymphedema prevention.
Procurement scale favors Hospitals; margin capture favors Surgical Centers.
Indication:
Application urgency and payer mix separate oncologic reconstruction with mandated coverage from elective aesthetic procedures with variable reimbursement.
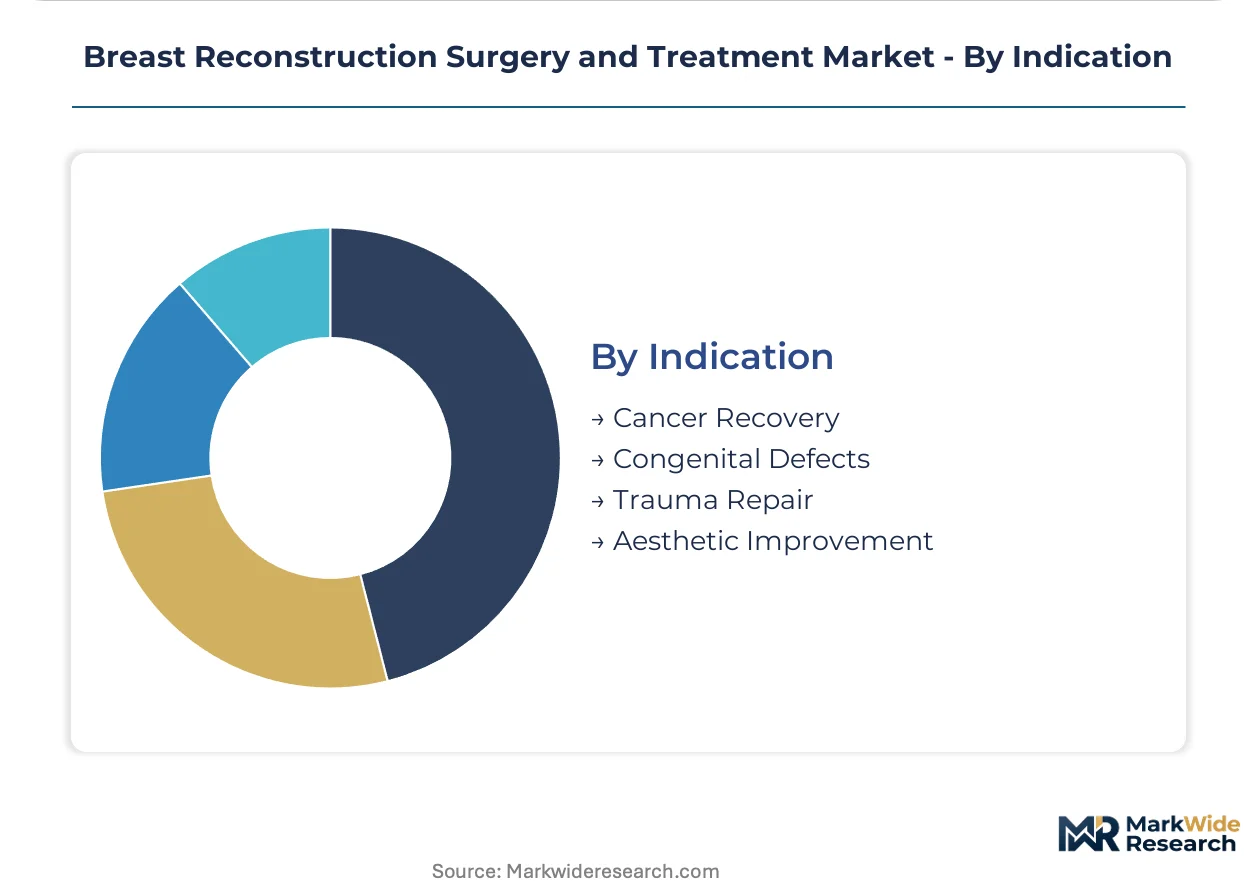
- Cancer Recovery:Post-mastectomy or post-lumpectomy reconstruction following breast cancer treatment. United States demand concentrates in states with dense academic medical center networks where Women's Health and Cancer Rights Act compliance ensures coverage parity.
- Congenital Defects:Correction of Poland syndrome, tuberous breast deformity, and other developmental anomalies.
- Trauma Repair:Reconstruction following accidental injury or burns.
- Aesthetic Improvement:Elective enhancement or revision procedures without oncologic indication. Private practices in California and New York target this segment with fat grafting convergence techniques and BREAST-Q outcome optimization protocols.
Policy protection favors Cancer Recovery; margin expansion favors Aesthetic Improvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes breast reconstruction through implant-dominant pathways, while Germany and Japan favor autologous flap techniques requiring specialized microsurgical infrastructure. This procedural mix divergence shapes supplier deployment strategies and capital equipment requirements across national health systems.
United States
Academic medical centers in New York and California drive adoption of DIEP flap protocols and pre-pectoral implant placement. The Women's Health and Cancer Rights Act mandates coverage parity, expanding procedural access beyond traditional metropolitan clusters. Texas and Florida surgical centers exploit outpatient reimbursement differentials to capture pre-pectoral volumes previously routed to inpatient settings.
Germany
University hospitals in Bavaria and North Rhine-Westphalia prioritize autologous reconstruction for superior long-term aesthetic outcomes. The EU Medical Device Regulation elevates clinical evidence thresholds, filtering suppliers without robust post-market surveillance infrastructure. Berlin-based procurement consortia emphasize MDR technical documentation compatibility in supplier qualification.
Japan
PMDA silicone device classifications create distinct approval timelines from Western regulators, shaping manufacturer launch sequencing. Tokyo and Osaka metropolitan clusters concentrate microsurgical fellowship programs, limiting flap technique diffusion to secondary cities. METI reimbursement frameworks favor incremental innovation over disruptive technique shifts.
France
ANSM vigilance reporting requirements reinforce demand for transparent safety data among hospital procurement committees. Île-de-France academic centers anchor national training pipelines for perforator flap techniques. Lyon and Marseille clusters demonstrate growing adoption of fat grafting convergence approaches in private practice settings.
United Kingdom
NHS England commissioning frameworks prioritize implant-based reconstruction for cost predictability in high-volume pathways. London teaching hospitals maintain specialized microsurgical capacity for complex revision cases. Scotland and Wales exhibit coverage variability for autologous techniques, creating geographic access disparities.
Breast Reconstruction Surgery and Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational medical device conglomerates controlling silicone implant supply while regional manufacturers capture autologous tissue niches. The upper tier leverages direct-to-surgeon training infrastructure and long-term safety registries to defend hospital system contracts. Mid-tier specialists compete on proprietary gel formulations and regional manufacturing scale. Dominant competitive moves include portfolio diversification across implant textures and cohesivity grades, plus backward integration into medical-grade silicone precursor supply.
Within the integrated multinational tier, Allergan (AbbVie) and Mentor Worldwide LLC (Johnson & Johnson) exemplify scale-driven positioning through broad device portfolios and established clinical data libraries. Establishment Labs Holdings Inc. occupies a specialist position, representing regional manufacturing scale advantages in Latin American markets. POLYTECH Health & Aesthetics GmbH anchors the European specialist fabricator segment, while Sientra, Inc. sits within the premium-tier vector focused on specialized silicone technologies.
| Leading Market Players |
|---|
| Allergan (AbbVie) |
| Mentor Worldwide LLC (Johnson & Johnson) |
| Sientra, Inc. |
| Establishment Labs Holdings Inc. |
| GC Aesthetics Ltd |
| POLYTECH Health & Aesthetics GmbH |
| Integra LifeSciences Corporation |
| RTI Surgical |
| Groupe Sebbin SAS |
| Others |
Value Chain & Pricing Dynamics
FDA premarket approval pathways and EU MDR clinical evidence mandates simultaneously gate supplier qualification and stratify price tiers across implant portfolios. These regulatory filters concentrate procurement authority among hospital value-analysis committees that demand transparent safety registries, compressing margins for manufacturers without backward integration into medical-grade silicone precursor supply.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between high-volume hospital systems and established implant manufacturers, locking in volume commitments that insulate premium-tier suppliers from spot-market volatility. Price differentiation hinges on FDA-established safety registry participation and gel cohesivity grade certification, with fifth-generation cohesive gel formulations commanding premium positioning over standard round implants. Cost compression in economy-tier saline devices is intensifying because petrochemical feedstock volatility squeezes manufacturers lacking captive silicone supply. Academic medical centers exhibit lowest price sensitivity due to outcome-based procurement criteria, while independent surgical centers in Texas and Florida prioritize per-unit cost minimization.
Supply Chain Analysis
Port congestion across transpacific trade lanes elevates inbound logistics costs for medical-grade silicone precursor shipments originating from German and Japanese chemical manufacturers. Supply concentrates in the United States, Germany, and Japan, with domestic production of silicone gel devices anchored in California and Texas manufacturing clusters. Raw material dependencies include medical-grade silicone elastomers, platinum catalysts, and specialized shell texturing equipment. Single-source vulnerability pervades the fifth-generation cohesive gel segment, where proprietary formulations limit qualified suppliers. Distribution runs through hospital procurement consortia and GPO contracts that aggregate demand across integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breast reconstruction market exhibits cyclical recovery characteristics tied to insurance mandate expansion under the Women's Health and Cancer Rights Act, which creates predictable demand baselines for reconstructive procedures following cancer diagnosis peaks.
For Market Incumbents: Consolidate market position through exclusive hospital system partnerships that embed your safety registries into value-analysis committee scorecards, neutralizing emerging entrants lacking National Breast Implant Registry compatibility. Deepen backward integration into medical-grade silicone precursor supply to offset petrochemical cost volatility threatening margin compression in economy-tier device lines. Prioritize certification investment in EU MDR technical documentation to defend European academic center contracts against regional specialists.
For New Entrants and Emerging Players: CE marking fast-track pathways through notified body partnerships in Germany and France offer accelerated European market access before FDA premarket approval timelines conclude. Target the radiation-tolerant tissue expander segment serving immediate reconstruction patients eligible for adjuvant therapy, where incumbent portfolios show coverage gaps. Pursue white-space opportunities in Latin American markets through regional manufacturing scale advantages that undercut transpacific logistics costs for established multinationals.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across autologous flap procedure ecosystems as microsurgical fellowship program expansion requires specialized capital equipment investments. Long-term viability favors platforms combining implant-based volume with fat grafting convergence capabilities that capture premium positioning in aesthetic-focused private practices. Acquisition target archetypes include regional silicone device fabricators with established MDR technical documentation and underutilized manufacturing capacity. Monitor FDA-EU regulatory divergence timelines as the primary inflection signal for geographic launch sequencing advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Embedding safety registries into GPO contracts locks out competitors lacking National Breast Implant Registry participation. |
| CE Marking Pathway | Accelerated EU MDR technical documentation approval filters out marginal competitors before FDA timelines conclude. |
| Backward Integration | Captive medical-grade silicone precursor supply insulates margins from petrochemical volatility compressing economy-tier devices. |
| Software Companion Development | Specialized surgical planning platforms for post-mastectomy radiation sequencing differentiate radiation-tolerant expander portfolios. |
| Reimbursement Strategy | Women's Health and Cancer Rights Act compliance documentation expands procedural access beyond traditional metropolitan clusters. |
Study Parameters
A standing panel of plastic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. These practitioner insights combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement records, and hospital procurement contract repositories. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data to reconcile segment-level figures.
Consistency checks validated volume and value outputs against external benchmarks including National Breast Implant Registry participation rates and academic medical center case mix indices. The analytical framework modeled product type, delivery mode, end user, and indication dimensions across the projection horizon. CAGRs derived from regression analysis of historical procedural growth patterns adjusted for insurance mandate expansion trajectories. Forecast inputs incorporated silicone gel cohesivity grade adoption curves and microsurgical fellowship program capacity constraints.
Decision-makers should treat outputs as directional under assumptions of stable insurance mandate enforcement and continued FDA-EU regulatory divergence; material deviation would warrant model refresh. Specific risk factors include polymer feedstock cost spikes, MDR implementation delays, and allograft substitution acceleration in tissue expander applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Rhytidectomy Market