
 India Cosmetic Surgery Market | 2026-2036
India Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
India Cosmetic Surgery Market Insights
Market Dynamics
Hospital-based cosmetic surgery delivery is narrowing as corporate chains consolidate outpatient aesthetics into dedicated day-surgery centers. Manipal Hospitals leverages its south Indian network to anchor high-volume rhinoplasty and liposuction units across Bengaluru and Mangaluru. Max Super Speciality Hospital competes on technology density, sustaining investments in laser and endoscopic suites at its Delhi and Mohali facilities. Fortis Memorial Research Institute differentiates through its Gurgaon flagship, dominating premium inpatient reconstructive and cosmetic procedures for NCR's affluent patient base.
Technical and Segment Analysis
Cosmetic surgery encompasses elective surgical and minimally invasive procedures that reshape, enhance, or restore human anatomy using implants, autologous tissue transfer, energy-based devices, and injectable formulations, with outcomes measured by aesthetic symmetry, scar minimization, and recovery time. Its primary purpose serves patient-driven aesthetic goals and psychological wellbeing across facial contouring, body sculpting, and skin rejuvenation applications. Liposuction and rhinoplasty lead procedure type volumes due to established surgical protocols and predictable outcomes, while radiofrequency and laser technologies capture expanding margin pools as patients shift toward reduced-downtime alternatives. Day surgery and outpatient service types are growing fastest, reflecting anesthesia advances and pressure from insurance-excluded pricing that rewards shorter facility stays.
Regulatory Environment and Outlook
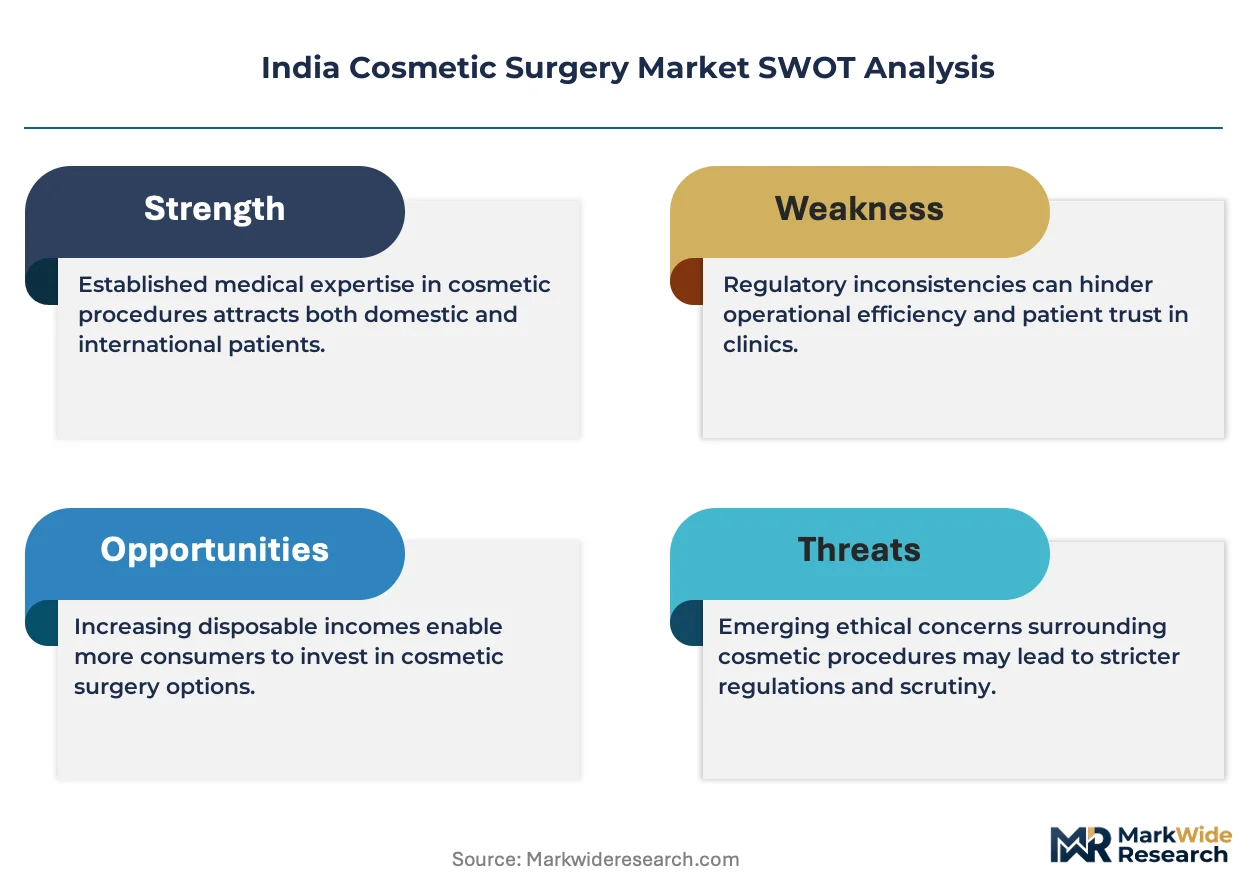
The Central Drugs Standard Control Organization regulates implantable devices and energy-based surgical equipment through import licensing and clinical trial requirements, while the National Medical Commission governs practitioner qualifications and facility accreditation standards that determine market access. The Medical Device Rules framework classifies increasing numbers of aesthetic devices, tightening post-market surveillance and shaping procurement decisions for hospital chains. Stakeholders must monitor evolving CDSCO risk-based classification shifts and NMC advertising guidelines that will determine which technologies and service formats gain scalable deployment across India's fragmented provider landscape.
Market Dynamics
Day-surgery center consolidation is compressing hospital-based cosmetic surgery delivery across India, as corporate chains redirect high-margin aesthetic procedures into dedicated outpatient facilities with streamlined anesthesia protocols and reduced facility overhead.
Growth Catalysts
- CDSCO Medical Device Rules:Risk-based classification of energy-based surgical equipment is accelerating import licensing standardization, enabling faster deployment of radiofrequency and laser platforms in accredited centers.
- Urban millennial demand:Bengaluru, Mumbai, and Delhi NCR patient cohorts are driving volume for minimally invasive facial contouring, with super-specialty chains capturing recurring injectable and thread-lift visits.
- Radiofrequency-assisted liposuction:This technology is expanding addressable patient pools through reduced downtime and enhanced skin retraction outcomes compared to traditional suction techniques.
Market Restraints
- Import dependency for energy devices:Laser and radiofrequency equipment concentrates among US, German, and South Korean suppliers, exposing procurement to currency volatility and extended lead times.
- NMC advertising restrictions:National Medical Commission guidelines constrain direct-to-consumer marketing for aesthetic procedures, limiting patient acquisition channels for standalone clinics.
- Alloplastic implant costs:Silicone and polymer-based facial and body implants carry substantial landed costs, compressing margins on augmentation procedures outside premium tier pricing.
Strategic Opportunities
- Tier-2 city expansion:Pune, Hyderabad, and Chennai present underpenetrated demand for outpatient aesthetics, with disposable income growth outpacing local provider density.
- PLI scheme alignment:Production-linked incentive frameworks for medical devices offer domestic manufacturing pathways for sutures, cannulas, and disposables currently imported.
- Combination therapy protocols:Convergence of injectable neurotoxins with fractional laser resurfacing is creating bundled service models that elevate per-patient revenue and retention rates.
Industry Challenges
- Aesthetic surgeon certification gaps:Formal fellowship pathways in cosmetic surgery remain limited relative to procedure volume growth, constraining qualified practitioner supply for chain expansion.
- CDSCO post-market surveillance compliance:Adverse event reporting obligations for implantable devices and energy-based equipment impose documentation burdens on smaller clinic operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cosmetic Surgery Market |
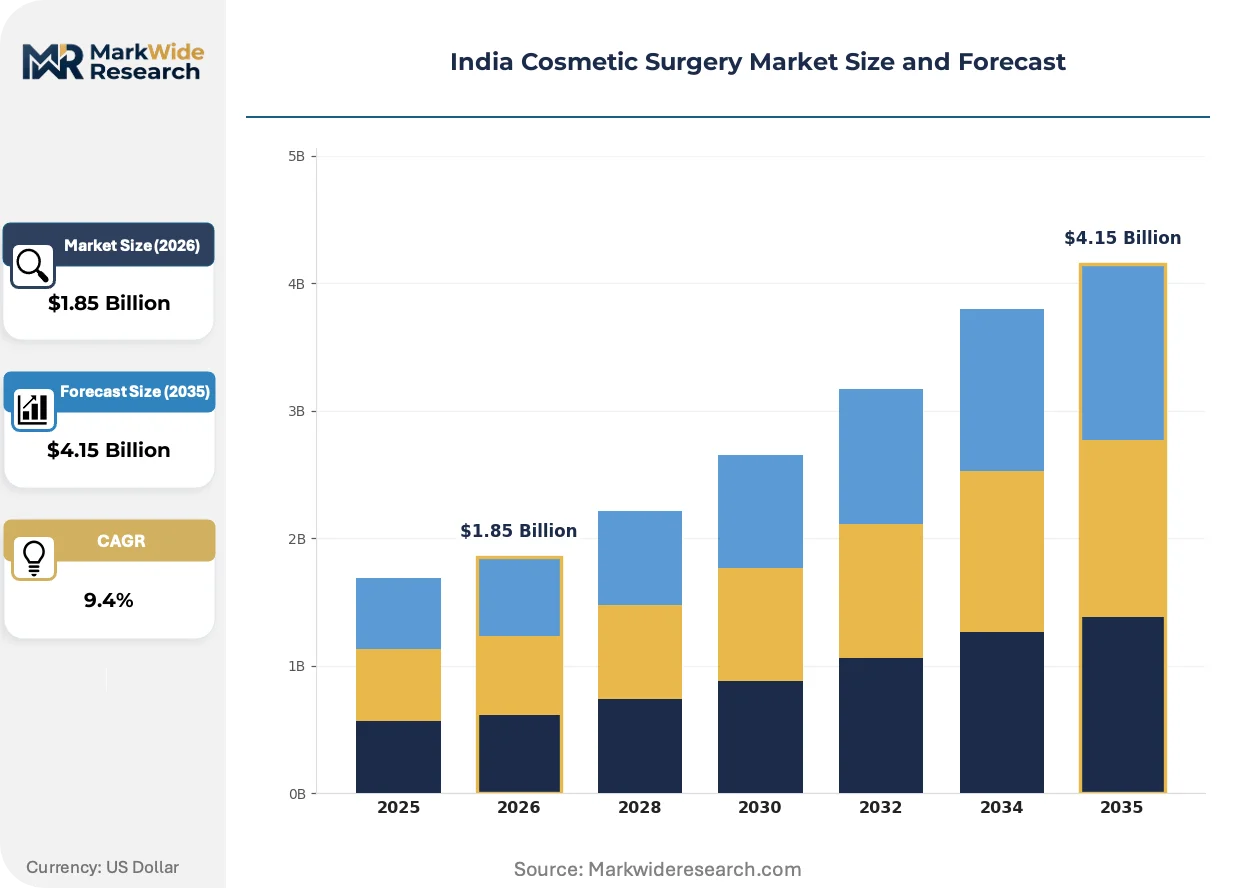
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Rhinoplasty, Liposuction, Breast Augmentation, Facelift Patient Demographics: Male, Female, Age 18-30, Age 31-50 Technology: Laser, Endoscopic, Injectables, Radiofrequency Service Type: Outpatient, Inpatient, Day Surgery, Consultation |
| Companies Covered | Manipal Hospitals, Max Super Speciality Hospital, Fortis Memorial Research Institute, Metro Hospital and Multispeciality Institute, VPS Rockland Hospital, Indraprastha Apollo Hospitals, Medanta The Medicity, CARE Hospitals, BLK-Max Super Speciality Hospital, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cosmetic Surgery Market Trends and Innovations
Digital workflow integration is transforming preoperative planning and patient communication across Indian cosmetic surgery practices, compressing consultation-to-procedure timelines while elevating outcome predictability.
Three-dimensional facial imaging and simulation software is digitizing the consultation experience for rhinoplasty and facial contouring candidates. Metro-based super-specialty chains are deploying these platforms across Bengaluru and Delhi NCR flagship centers. The technology is digitizing patient expectation management and reducing revision rates through visual alignment between surgeon and patient before incision.
CDSCO's expanding risk-based classification of aesthetic devices under the Medical Device Rules framework is tightening clinical evidence requirements for energy-based equipment imports. Manufacturers must now submit India-specific safety and performance data for laser and radiofrequency platforms. High-volume hospital chains are responding by consolidating procurement around established suppliers with existing registration portfolios.
Subscription-based aesthetic maintenance programs are displacing episodic procedure purchasing among urban millennial and Gen Z patient segments. These models bundle annual injectable schedules with priority booking and post-procedure follow-up. Maharashtra and Karnataka urban corridors exhibit the highest penetration of membership-based cosmetic care.
India Cosmetic Surgery Market Segmentation
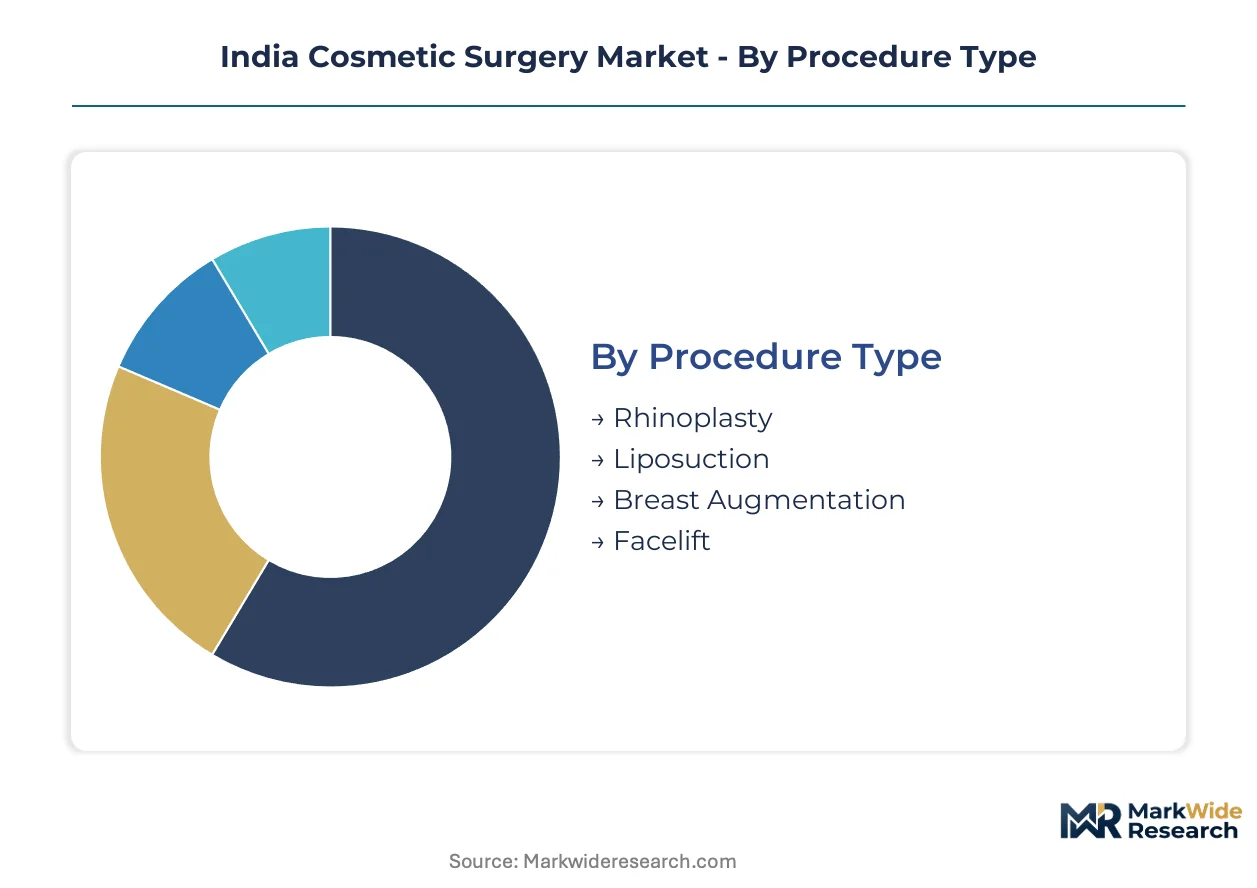
Segmentation in India's cosmetic surgery market reveals distinct demand patterns across procedure maturity, technology adoption curves, and service delivery formats. Understanding these divisions enables targeted capacity planning and technology procurement for providers navigating CDSCO regulatory pathways and urban patient concentration.
Procedure Type:
Mature surgical protocols dominate revenue concentration while emerging minimally invasive alternatives reshape patient acquisition economics.
- Rhinoplasty:Surgical reshaping of nasal bone and cartilage structures using open or closed techniques. Maharashtra and Delhi NCR super-specialty chains capture recurring revision demand from affluent patient cohorts seeking ethnic refinement or functional correction. CDSCO-registered implant portfolios differentiate premium tier providers.
- Liposuction:Fat removal via suction-assisted lipectomy or energy-assisted variants. Bengaluru and Mumbai facilities drive volume through radiofrequency-assisted platforms that reduce downtime and improve skin retraction outcomes versus traditional tumescent methods.
- Breast Augmentation:Alloplastic implant placement or autologous fat transfer for volume enhancement. Silicone gel and saline devices face import cost pressures under DGFT medical device tariff structures.
- Facelift:Rhytidectomy procedures addressing midface and neck laxity through SMAS manipulation. Slower recovery timelines limit adoption among working-age demographics compared to injectable alternatives.
Rhinoplasty retains volume leadership; radiofrequency-assisted liposuction holds the steepest expansion curve.
Patient Demographics:
Cost tier stratification separates premium self-pay segments from price-sensitive financing-dependent cohorts across urban corridors.
- Male:Gynecomastia correction and hair transplantation dominate male procedure demand, with Karnataka and Telangana clinics reporting accelerating facial contouring interest among tech sector professionals.
- Female:Body sculpting and facial rejuvenation procedures concentrate among working professionals in Delhi NCR and Mumbai, driving repeat visit economics for maintenance protocols.
- Age 18-30:Pre-career and early-career patients prioritize rhinoplasty and liposuction with parental financing support. Social media influence accelerates consultation-to-procedure compression in this bracket.
- Age 31-50:Established income patients favor combination therapies blending neurotoxins with energy-based skin tightening. Maharashtra day-surgery centers capture this recurring revenue stream through membership models.
Female patients retain volume leadership; male demographics are gaining share fastest.
Technology:
Margin concentration tracks with equipment import dependency and CDSCO registration completion timelines.
- Laser:Ablative and non-ablative platforms for skin resurfacing and hair removal. US and German suppliers dominate procurement pipelines for accredited hospital chains.
- Endoscopic:Minimally invasive visualization systems for brow lift and facial suspension procedures. Limited surgeon certification availability constrains scalable deployment outside flagship centers.
- Injectables:Neurotoxins and dermal fillers for dynamic wrinkle reduction and volume restoration. Bengaluru and Pune clinics bundle these into subscription maintenance programs with highest retention rates.
- Radiofrequency:Monopolar and bipolar energy delivery for tissue tightening and liposuction assistance. CDSCO risk-based classification is tightening clinical evidence requirements for new platform imports.
Injectables retain volume leadership; radiofrequency platforms are climbing the fastest.
Service Type:
Volume distribution reflects anesthesia protocol advances and insurance-exclusion pressures favoring shorter facility stays.
- Outpatient:Non-surgical procedures performed without sedation or with topical anesthesia. Max Super Speciality and Manipal Hospitals redirect injectable and light laser volumes into dedicated cosmetic suites.
- Inpatient:Overnight stays for complex reconstructive or combined procedures. Fortis Memorial Research Institute anchors premium inpatient capacity for NCR's high-net-worth patient base.
- Day Surgery:Single-visit surgical procedures with discharge within 12 hours. Corporate chains consolidate rhinoplasty and liposuction into these formats to optimize facility utilization.
- Consultation:Preoperative assessment and simulation services. Three-dimensional imaging platforms digitize this stage across Bengaluru flagship centers, reducing revision rates.
Day surgery retains volume leadership; outpatient services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor freight rail network underwrites Maharashtra's dominance in cosmetic surgery capacity, connecting implant import hubs at JNPT to tertiary care clusters across western India.
Maharashtra
Mumbai's super-specialty chains absorb the highest volume of rhinoplasty and body contouring procedures, driven by entertainment industry professionals and finance sector executives seeking ethnic refinement. CDSCO's import licensing framework channels silicone implants through Mumbai port facilities, creating procurement advantages for accredited centers. Pune's emerging medical corridor is capturing spillover demand from cost-conscious patients priced out of Mumbai's premium tier.
Delhi NCR
Gurgaon's corporate hospital flagships anchor premium reconstructive and aesthetic surgery for NCR's affluent patient base, with combination therapy protocols driving repeat visit economics. National Medical Commission facility accreditation standards determine market access for standalone clinics across Haryana and Uttar Pradesh satellite cities. Faridabad's day-surgery centers are consolidating outpatient aesthetics through streamlined anesthesia protocols.
Karnataka
Bengaluru's technology sector professionals are accelerating demand for minimally invasive facial contouring and hair transplantation, with super-specialty chains capturing recurring injectable maintenance visits. The state's biomedical device park policy under PLI scheme frameworks is attracting domestic manufacturing interest for sutures and cannulas. Mangaluru's coastal medical tourism corridor is expanding radiofrequency-assisted liposuction capacity for Gulf NRI patient segments.
Telangana
Hyderabad's pharmaceutical executive cohort is driving premium-tier demand for combination laser and injectable protocols, with corporate hospital chains deploying membership-based aesthetic maintenance programs. CDSCO's risk-based classification of energy-based devices is tightening clinical evidence requirements for new platform imports through the city's medical device cluster. Secunderabad's outpatient surgery centers are optimizing facility utilization through compressed consultation-to-procedure timelines.
Tamil Nadu
Chennai's medical tourism infrastructure is capturing international patient flows for complex reconstructive procedures, leveraging established accreditation relationships with Gulf healthcare payers. The state's surgical instrument manufacturing base supplies cannulas and disposables to chains across south India. Coimbatore's tier-2 market is exhibiting disposable income growth outpacing local provider density for outpatient aesthetics.
India Cosmetic Surgery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in India's cosmetic surgery market structure. The provider landscape consolidates around super-specialty hospital chains with dedicated aesthetic divisions, while standalone clinics fragment across unregulated segments. Three archetypes dominate: corporate hospital networks with technology density, mid-tier day-surgery specialists with streamlined protocols, and premium inpatient reconstructive centers. Competitive moves center on geographic expansion into tier-2 corridors and technology licensing arrangements for energy-based platforms.
Within the corporate hospital network tier, Manipal Hospitals and Max Super Speciality Hospital exemplify scale-driven platform integrators with south and north Indian geographic anchoring respectively. Fortis Memorial Research Institute occupies the premium inpatient reconstructive position through its Gurgaon flagship concentration. These entities represent the dominant competitive archetypes shaping procurement consolidation and patient acquisition economics across CDSCO-accredited facility networks.
| Leading Market Players |
|---|
| Manipal Hospitals |
| Max Super Speciality Hospital |
| Fortis Memorial Research Institute |
| Metro Hospital and Multispeciality Institute |
| VPS Rockland Hospital |
| Indraprastha Apollo Hospitals |
| Medanta The Medicity |
| CARE Hospitals |
| BLK-Max Super Speciality Hospital |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Bengaluru's radiofrequency liposuction suites is compressing procurement timelines for US and German equipment suppliers while elevating price premiums for same-day scheduling slots. CDSCO import licensing backlogs amplify this tension, forcing hospital chains to pre-commit capital for device allocation before registration completion.
Pricing Analysis
Volume-discount tiering separates corporate hospital networks from standalone clinics across Maharashtra and Karnataka. Three-tier pricing structure across premium, standard, and economy levels tracks CDSCO registration status and surgeon certification depth. Price differentiation hinges on implant origin documentation and energy-device warranty coverage. Cost compression in economy-tier rhinoplasty is intensifying because parental financing for 18-30 age cohorts faces household liquidity constraints. Corporate chains exhibit lowest price sensitivity; standalone clinics in tier-2 corridors face acute margin pressure.
Supply Chain Analysis
Tariff exposure between the United States and India dominates landed cost volatility for laser and radiofrequency platforms. Geographic supply concentration centers on the United States, Germany, and South Korea for energy-based surgical equipment. Raw material dependencies span silicone gel formulations, polymer cannulas, and precision optical components. Single-source vulnerability persists for radiofrequency generator assemblies. Distribution runs through Mumbai's JNPT port facilities to accredited hospital chains with established CDSCO import licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward corporate hospital chains as standalone clinic fragmentation accelerates consolidation into day-surgery networks across Delhi NCR and Karnataka.
For Market Incumbents: Entrench technology density advantages through exclusive licensing arrangements with US and German energy-device manufacturers before CDSCO registration windows tighten. Anchor capacity expansion in Pune and Hyderabad corridors where disposable income growth outpaces local provider density. Defensive priority rests on surgeon certification pipelines to constrain qualified practitioner supply for rival chains. For New Entrants and Emerging Players: Tier-2 city outpatient aesthetics in Coimbatore and Mangaluru represent the most penetrable entry point given demand-supply asymmetry. Combination therapy protocols blending injectables with fractional laser resurfacing offer service differentiation without capital-intensive equipment procurement. Go-to-market angle should emphasize subscription-based maintenance programs with highest retention rates among 31-50 age demographics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among super-specialty chains with membership-based aesthetic maintenance programs. Long-term viability over a multi-year horizon favors platforms with CDSCO-registered device portfolios and NMC-accredited facility networks. Acquisition target archetype: mid-tier day-surgery specialists with streamlined anesthesia protocols in underpenetrated state corridors. Signal to monitor: CDSCO risk-based classification shifts that elevate clinical evidence requirements for new energy-platform imports.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Fast-Track | Accelerated import licensing for radiofrequency platforms compresses deployment timelines for hospital chains. |
| Surgeon Certification Pipeline | Formal fellowship partnerships with medical colleges constrain qualified practitioner supply for rival expansion. |
| Tier-2 City Day-Surgery Expansion | Pune and Hyderabad facility rollouts capture disposable income growth outpacing local provider density. |
| Combination Therapy Bundling | Injectable-neurotoxin and fractional-laser convergence elevates per-patient revenue and retention rates. |
| Domestic Manufacturing Alignment | PLI scheme positioning for sutures and cannulas reduces import dependency and currency exposure. |
Research Methodology
Desk research of CDSCO registration databases, NMC facility accreditation records, and hospital procurement disclosures preceded structured interviews with cosmetic surgeons, biomedical equipment procurement managers, day-surgery center operations heads, and PLI scheme implementation officers. Secondary validation drew from DGFT medical device tariff schedules, state biomedical device park policy documents, and corporate hospital chain annual disclosures. Bottom-up procedure volume estimates and top-down market sizing triangulated across these sources.
Assumption sets held CDSCO risk-based classification timelines and NMC advertising guideline enforcement constant across the projection horizon while varying urban disposable income growth and medical tourism recovery patterns. Segmentation dimensions modeled encompassed procedure type, patient demographic cohort, technology platform, and service delivery format. CAGRs derived from procedure volume trajectories and average revenue per procedure across accredited facility networks. Industry-specific forecast inputs included energy-device import lead times and surgeon certification completion rates.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates and Gulf NRI remittance flows would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and urban millennial demand persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
UK Cosmetic Surgery Market