
 Candida Vaginitis Rapid Testing Market | 2026-2036
Candida Vaginitis Rapid Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Candida Vaginitis Rapid Testing Market Outlook
The EU In Vitro Diagnostic Regulation (IVDR) is realigning compliance burdens for rapid testing manufacturers entering European markets. Bio-Rad Laboratories leverages its molecular diagnostics heritage to sustain competitive positioning across PCR-based platforms. Quest Diagnostics anchors a dominant share of laboratory service channels in North America, while bioMérieux SA differentiates through specialized fungal pathogen detection expertise.
Candida vaginitis rapid testing encompasses diagnostic platforms that detect Candida species from vaginal specimens within minutes to hours, typically employing immunoassay strips with sensitivity thresholds of 10³ to 10⁴ colony-forming units per milliliter or nucleic acid amplification methods targeting species-specific ribosomal RNA sequences. These tools serve primary clinical purposes of distinguishing candidiasis from bacterial vaginosis and trichomoniasis to guide targeted antifungal therapy and reduce empirical prescription. Test kits and consumables command the largest revenue pools given recurring purchase requirements, while lateral flow technology occupies the broadest installed base due to minimal equipment needs and CLIA waiver eligibility. PCR-based assays represent the fastest-expanding technology segment as laboratories prioritize species-level identification and antimicrobial resistance profiling.
FDA 510(k) clearance and CLIA waiver status shape product design and commercial access for US manufacturers, while IVDR conformity assessment in Europe extends timelines and documentation requirements for notified body engagement. ISO 13485 quality management certification remains mandatory for supply to regulated markets across all geographies. Stakeholders must monitor evolving reimbursement codes for molecular versus non-molecular platforms and calibrate R&D portfolios toward multiplex detection capabilities that address polymicrobial vaginitis presentations.
Market Dynamics
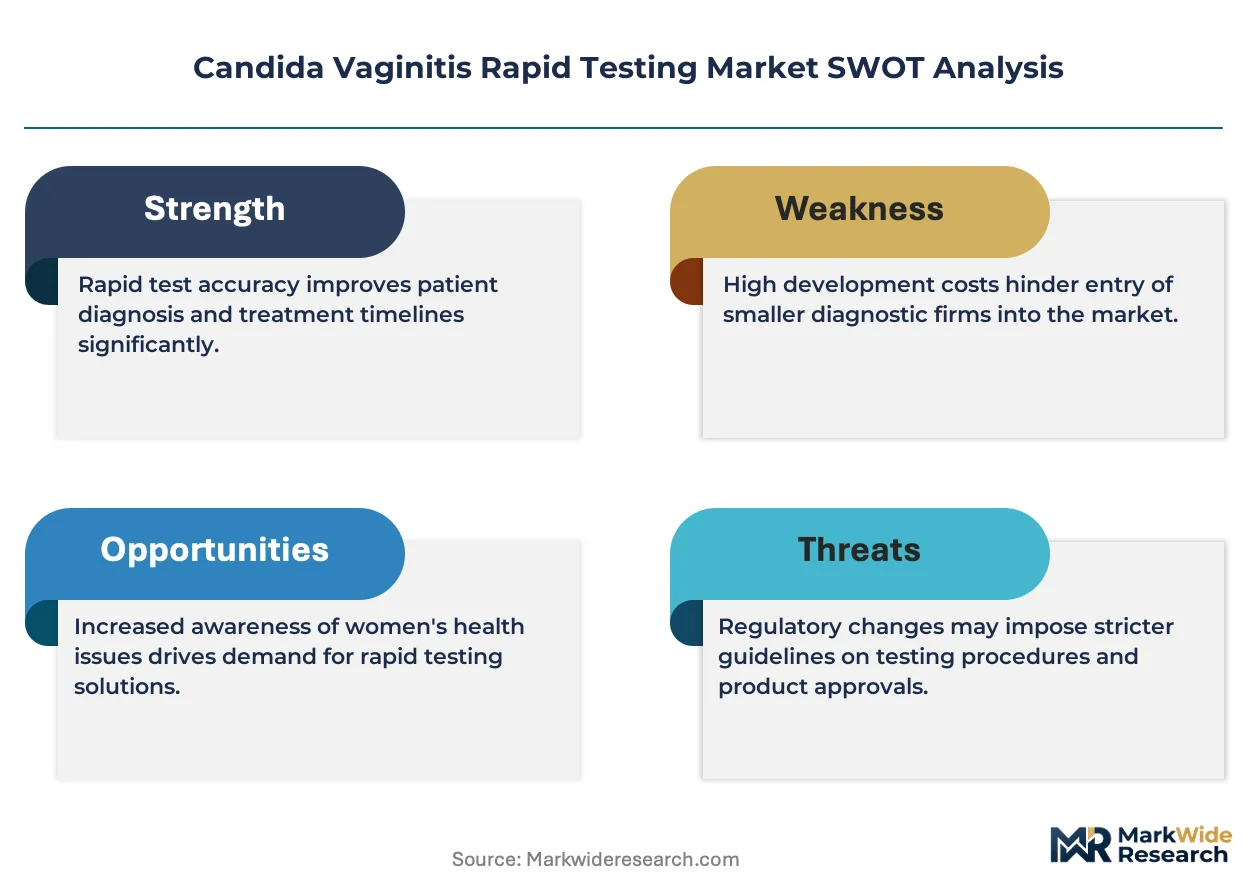
CLIA-waiver eligibility and IVDR conformity assessment are bifurcating product development pipelines, forcing manufacturers to engineer parallel assay architectures that satisfy divergent regulatory thresholds while preserving manufacturing economies.
Growth Catalysts
- CLIA-Waiver Expansion:FDA pathways for waived complex testing broaden point-of-care deployment in urgent care clinics and retail health settings, reducing laboratory dependency for routine screening.
- Antimicrobial Stewardship Mandates:Hospital accreditation standards in Germany and Japan now require species-level identification before antifungal prescription, accelerating molecular platform procurement.
- Multiplex Assay Convergence:Combined Candida-bacterial-trichomonas detection panels are consolidating diagnostic workflows, replacing serial testing with single-specimen analysis.
Market Restraints
- IVDR Documentation Burden:European notified body engagement timelines now extend 18-24 months for Class C in vitro devices, compressing commercial windows for new entrants.
- Fluorophore Supply Concentration:PCR detection chemistry relies on three Asian suppliers for critical dye intermediates, exposing manufacturers to input volatility and qualification delays.
- Lateral Flow Sensitivity Ceiling:Immunoassay platforms cannot reliably detect sub-10³ CFU/mL loads, forcing empirical treatment in early-stage infections and eroding clinical confidence.
Strategic Opportunities
- Home Collection Integration:Telehealth platforms in the United States are contracting for mail-in vaginal specimen kits with at-home stability validation, opening direct-to-patient channels.
- Resistance Gene Profiling:Azole resistance marker detection (ERG11, CDR1) represents unmet clinical need as fluconazole failure rates climb in immunocompromised populations.
- Indian Diagnostic Expansion:Ayushman Bharat health infrastructure investments are equipping 150,000 health and wellness centers with rapid testing capability, creating volume anchor demand.
Industry Challenges
- Molecular Biology Talent Scarcity:Assay development for ribosomal RNA target optimization requires hybrid skill sets spanning bioinformatics and clinical microbiology that command premium compensation.
- Legacy LIS Integration:Hospital laboratory information systems operate on HL7 v2.x architectures that resist direct PCR instrument data streaming, necessitating costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candida Vaginitis Rapid Testing Market |
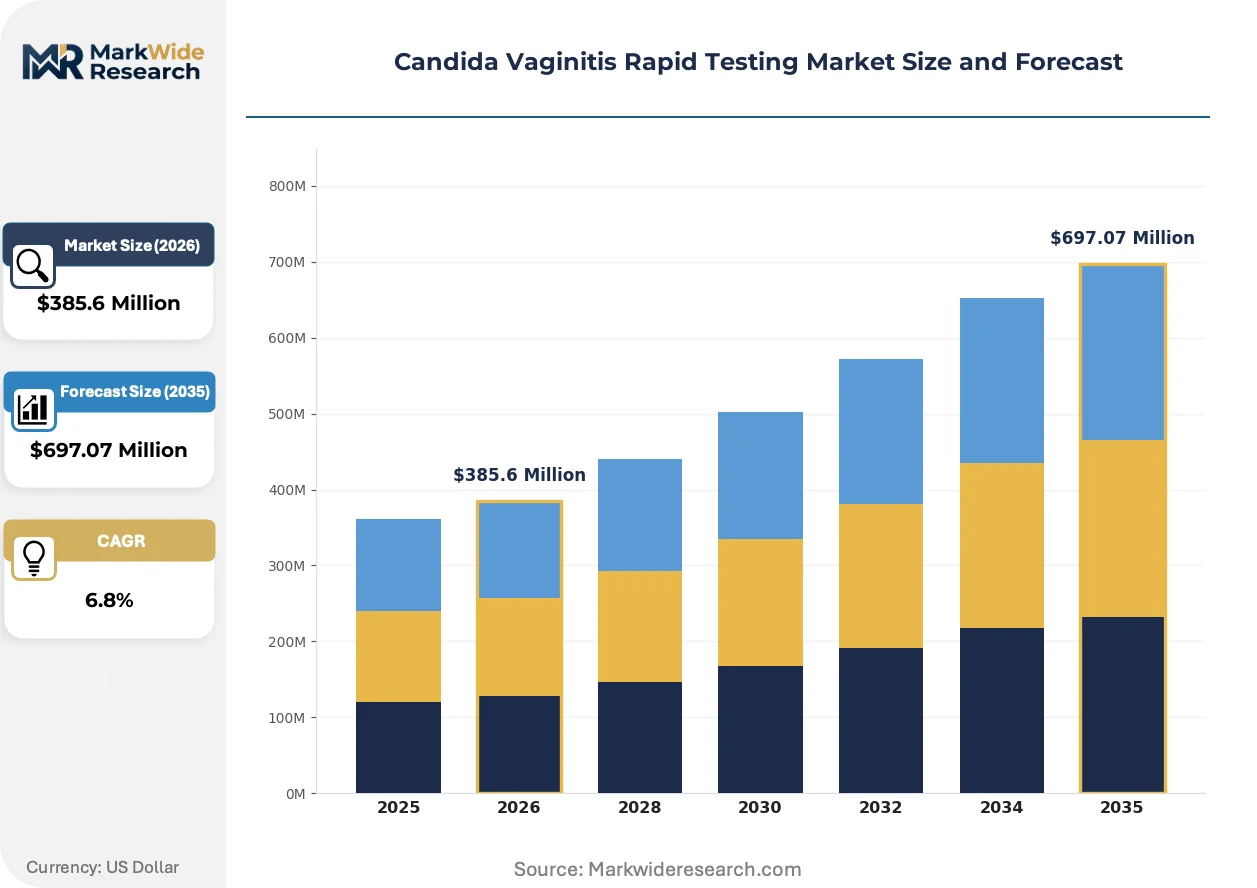
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Diagnostic Tools, Consumables, Assays Delivery Mode: Point-of-Care, Laboratory-Based, Home Testing, Mobile Units End User: Clinics, Hospitals, Laboratories, Home Users Technology: Immunoassays, PCR, Lateral Flow, ELISA |
| Companies Covered | Bio-Rad Laboratories, Quest Diagnostics, Abbott Laboratories, bioMérieux SA, Becton Dickinson, Thermo Fisher Scientific, Hologic, Inc., Savyon Diagnostics Ltd, Quidel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candida Vaginitis Rapid Testing Market Strategic Shifts
Isothermal amplification methods and smartphone-connected readers are collapsing the infrastructure requirements for molecular diagnosis, redrawing competitive boundaries between centralized laboratories and distributed care settings.
Loop-mediated isothermal amplification (LAMP) technology is decentralizing Candida detection by eliminating thermal cycler dependency. Urgent care chains in Texas and Florida are adopting battery-powered LAMP devices that return species identification within 30 minutes. This capability is compressing referral volumes to hospital microbiology departments and capturing margin previously allocated to laboratory service fees.
EU IVDR Article 10 general safety and performance requirements are mandating clinical evidence standards that exceed predecessor IVD Directive thresholds. Manufacturers must now submit prospective performance studies with 300+ specimen matrices, doubling regulatory preparation costs. Smaller assay developers are responding through notified body consortium arrangements that distribute documentation burdens across peer organizations.
Specimen collection preferences are rotating toward patient-administered vaginal swabs that bypass pelvic examination requirements. Retail pharmacy clinics in the United States are displacing traditional gynecology referrals for uncomplicated presentations, capturing diagnostic and prescription revenue in single visits. This channel shift is most visible in metropolitan markets where 24-hour pharmacy access outstrips primary care appointment availability.
Candida Vaginitis Rapid Testing Market Segmentation
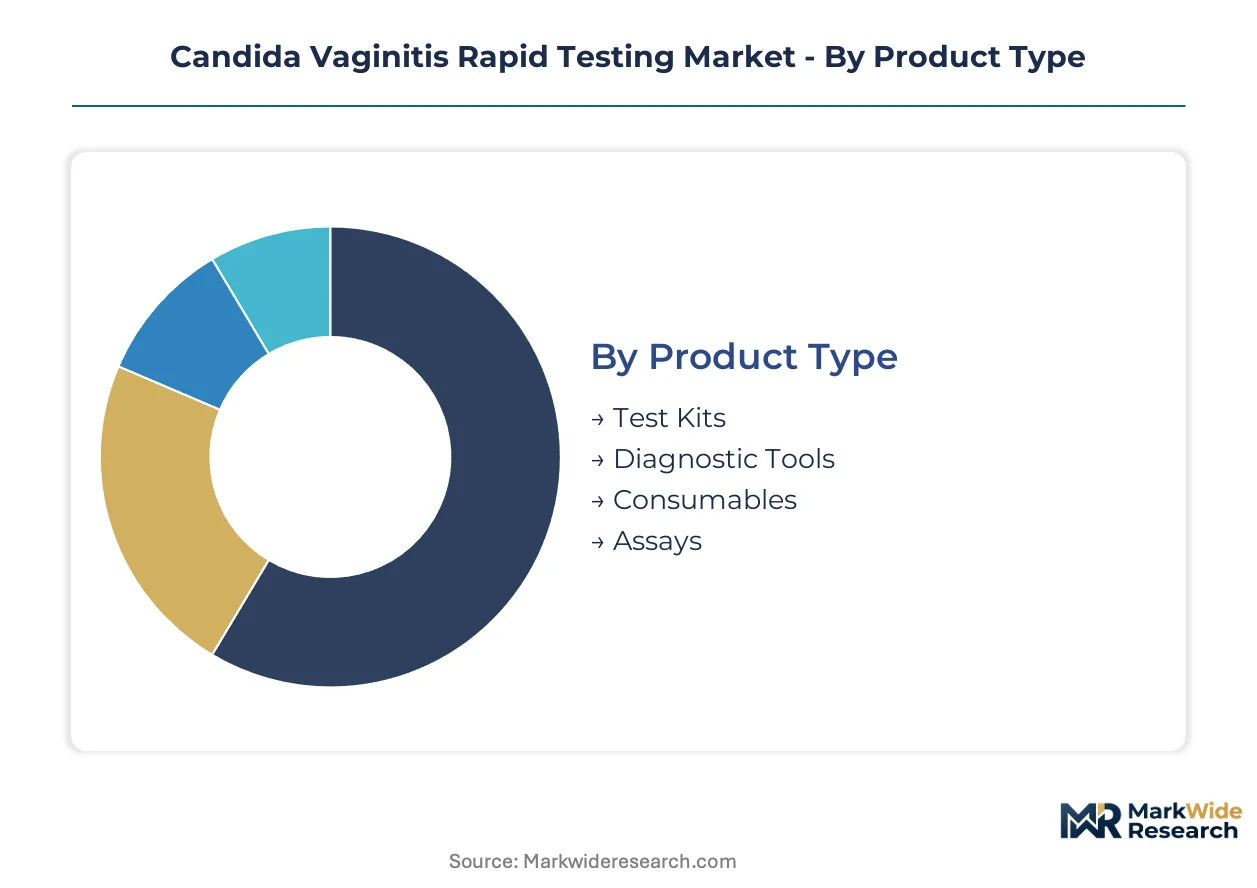
Candida vaginitis rapid testing segments fragment across capital requirements, regulatory pathways, and care setting infrastructure. Manufacturers must align product architectures with specific customer procurement capabilities and reimbursement frameworks.
Product Type:
Capital intensity varies sharply across product categories, with molecular assay platforms requiring substantial upfront R&D and manufacturing investment compared to consumable strips.
- Test Kits:Disposable cartridge-based systems integrate specimen collection, reagent delivery, and result interpretation in sealed units. Demand clusters in urgent care networks across Texas and Florida where CLIA-waived status enables non-laboratory staff operation.
- Diagnostic Tools:Benchtop analyzers and handheld readers constitute the fixed-asset layer of testing infrastructure. German hospital procurement is prioritizing multiplex-capable instruments that consolidate Candida, bacterial vaginosis, and trichomonas detection workflows.
- Consumables:Swabs, transport media, and reagent refills generate recurring revenue streams with minimal capital barriers to customer adoption.
- Assays:Species-specific probe sets and primer panels for ribosomal RNA targets command premium pricing in reference laboratory channels.
Most installed capacity flows through consumables and test kits. Expansion is steepest in diagnostic tools as laboratories upgrade to multiplex molecular platforms.
Delivery Mode:
Customer acquisition economics diverge by channel, with point-of-care deployment requiring field service infrastructure while home testing demands direct-to-consumer logistics and telehealth integration.
- Point-of-Care:CLIA-waived devices in urgent care and retail clinics compress time-to-result to under 30 minutes. Japanese regulatory pathways for pharmacy-based testing are accelerating channel development.
- Laboratory-Based:Centralized PCR and ELISA processing maintains dominant specimen volume through reimbursement advantages for complex molecular profiling.
- Home Testing:Mail-in specimen stability validation and telehealth prescription integration are opening direct patient access in United States metropolitan markets.
- Mobile Units:Battery-powered LAMP devices and van-based screening programs extend testing to underserved rural populations and temporary health campaigns.
Laboratory-based channels retain the largest installed base. Home testing is climbing the fastest as telehealth platforms contract for integrated diagnostic-prescription workflows.
End User:
Purchasing authority and budget cycles differ substantially across care settings, with hospitals consolidating procurement through group purchasing organizations while clinics operate on fragmented individual purchasing decisions.
- Clinics:Primary care and gynecology practices drive point-of-care adoption through CLIA-waived lateral flow and LAMP devices that eliminate referral dependencies.
- Hospitals:Microbiology departments anchor demand for species-level identification and antifungal resistance profiling through PCR-based platforms.
- Laboratories:Commercial reference laboratories and hospital-affiliated labs process high specimen volumes with automated ELISA and molecular systems.
- Home Users:Direct-to-patient channels are emerging through retail pharmacy partnerships and telehealth-integrated mail-in services.
Laboratories and hospitals command the majority of current procurement. Clinic-based point-of-care deployment is gaining share fastest as CLIA-waiver expansion reduces regulatory barriers.
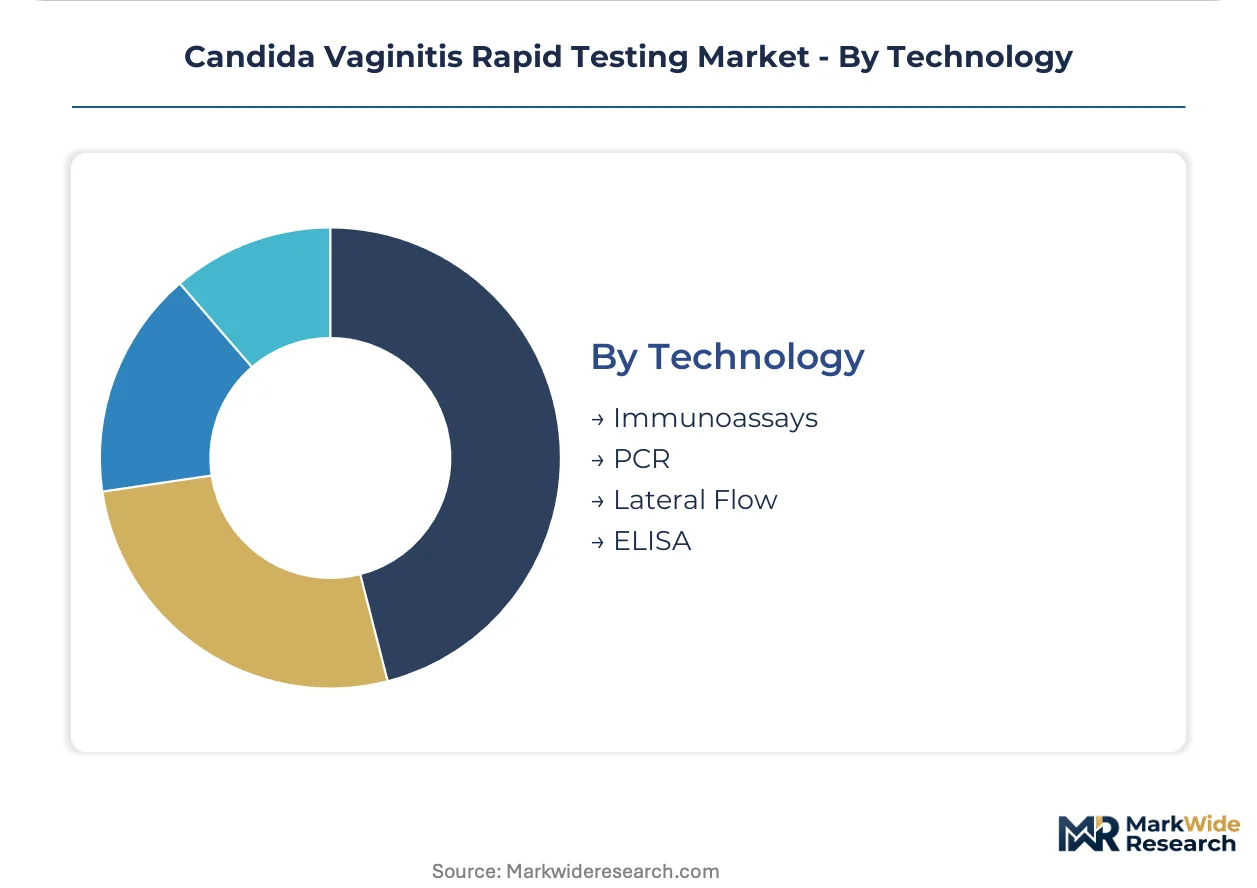
Technology:
Technical sophistication determines manufacturing complexity, with nucleic acid amplification requiring cleanroom production and fluorophore supply chain management versus simpler antibody-based strip production.
- Immunoassays:Antibody-based detection of Candida cell wall mannan or enolase antigens delivers results in 10-15 minutes without equipment. Sensitivity floors at 10³ CFU/mL limit early-stage detection.
- PCR:Thermal cycler-based amplification of species-specific ribosomal RNA sequences enables detection below 10² CFU/mL with simultaneous resistance marker profiling. German and Japanese stewardship mandates are accelerating platform procurement.
- Lateral Flow:Visual readout strips dominate the lowest-cost segment with minimal training requirements and stable room-temperature storage.
- ELISA:Enzyme-linked immunosorbent assays retain niche application in high-throughput laboratory environments where batch processing economies apply.
Lateral flow and immunoassay platforms represent the broadest installed base. PCR technology is expanding most quickly as antimicrobial stewardship requirements drive species-level identification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Candida vaginitis rapid testing industry traces its commercial scale to the United States, where CLIA-waiver pathways and point-of-care reimbursement frameworks first created viable markets for decentralized molecular diagnostics.
United States
Retail pharmacy clinics and urgent care chains in Texas and Florida are displacing traditional laboratory referrals through CLIA-waived LAMP devices. FDA 510(k) clearance timelines and telehealth-integrated mail-in specimen services are reshaping channel economics. The Dallas-Fort Worth metro anchors the highest concentration of point-of-care deployment contracts.
Germany
Hospital microbiology departments in Bavaria and North Rhine-Westphalia are procuring multiplex PCR platforms under mandatory antimicrobial stewardship protocols. IVDR conformity assessment through notified bodies extends commercialization timelines for new entrants. The Munich cluster concentrates reference laboratory capacity for species-level resistance profiling.
Japan
Pharmacy-based testing regulations from the Ministry of Health, Labour and Welfare are accelerating point-of-care channel development in Tokyo and Osaka. PMDA approval pathways favor rapid molecular platforms with documented sensitivity thresholds. The Kansai region hosts the densest installed base of automated specimen processing systems.
India
Ayushman Bharat health infrastructure investments are equipping 150,000 health and wellness centers with rapid testing capability across Maharashtra and Karnataka. CDSCO regulatory harmonization with IVD standards is streamlining import pathways for multinational assay manufacturers. The Hyderabad-Deccan corridor is emerging as a contract manufacturing hub for lateral flow components.
United Kingdom
NHS England procurement frameworks are consolidating diagnostic service contracts toward centralized laboratory networks in London and the Midlands. MHRA post-Brexit regulatory autonomy is diverging from EU IVDR timelines for domestic manufacturers. The Cambridge-Oxford arc concentrates venture-backed assay development startups targeting resistance gene detection.
Candida Vaginitis Rapid Testing Market Competitive Environment
Capital-heavy diagnostic platform manufacturers compete with asset-light assay developers for channel access and reimbursement positioning. The vendor base fragments across three tiers: multinational conglomerates with integrated laboratory service arms, specialized molecular diagnostics firms, and regional strip-test producers. Two strategic archetypes dominate competitive maneuvering: technology licensors seeking royalty-bearing partnerships with hospital procurement groups, and vertical integrators capturing margin through captive reagent supply. Consolidation pressure intensifies as CLIA-waiver eligibility and IVDR documentation burdens raise fixed-cost thresholds for sustainable participation.
Among the multinational tier, Bio-Rad Laboratories, Quest Diagnostics, and bioMérieux SA occupy positions that exemplify divergent strategic orientations toward the market. Bio-Rad Laboratories represents the molecular heritage archetype with PCR-based platform legacies. Quest Diagnostics anchors the laboratory service channel dominance model. bioMérieux SA exemplifies specialized pathogen detection expertise. These three entities collectively illustrate how geographic origin, corporate structure, and historical positioning shape competitive options without dictating specific tactical commitments.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Quest Diagnostics |
| Abbott Laboratories |
| bioMérieux SA |
| Becton Dickinson |
| Thermo Fisher Scientific |
| Hologic, Inc. |
| Savyon Diagnostics Ltd |
| Quidel Corporation |
| Others |
Value Chain & Pricing Dynamics
Fluorophore dye intermediate pricing indices from Asian chemical exchanges cascade through PCR assay manufacturing into three-tier pricing stratification across premium molecular platforms, standard immunoassay kits, and economy lateral flow strips. CLIA-waiver eligibility and IVDR conformity documentation costs concentrate margin compression at the premium tier while volume procurement by German hospital networks anchors pricing floors.
Pricing Analysis
Premium-mid-economy pricing differentiation separates multiplex PCR systems with resistance profiling capability from single-target immunoassays and visual-read lateral flow devices. Quality grade tied to FDA 510(k) clearance tier and ISO 13485 certification status drives price spreads exceeding manufacturing cost differentials. Pricing pressure stems from IVDR documentation burdens extending commercialization timelines and compressing return windows for new molecular entrants. Retail pharmacy clinics in Texas and Florida exhibit highest price sensitivity, while Japanese hospital microbiology departments prioritize sensitivity specifications over unit cost.
Supply Chain Analysis
Direct distribution to diagnostic laboratories and urgent care networks handles institutional procurement, while retail pharmacy and telehealth-integrated channels manage patient-facing volumes. Manufacturing concentration in the United States, Germany, and Japan supplies regulated markets with ISO-certified production, while India and China anchor contract manufacturing for lateral flow components. Critical dependencies include fluorophore dye intermediates from three Asian suppliers, specialized PCR reagents, and medical-grade plastics for cartridge molding. Single-source vulnerability in fluorophore supply exposes manufacturers to qualification delays and input volatility. Distribution runs through GPO contracts for hospital systems, direct sales for reference laboratories, and wholesale medical distributors for point-of-care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Candida vaginitis rapid testing market functions as a stable compounder anchored by antimicrobial stewardship mandates that institutionalize species-level identification requirements across German and Japanese hospital accreditation standards.
For Market Incumbents: To counter IVDR documentation burden escalation compressing commercial windows, consolidate notified body consortium arrangements to distribute regulatory preparation costs across peer organizations. Deepen backward integration into fluorophore dye chemistry to reduce Asian supplier dependency and stabilize input cost structures. Prioritize multiplex assay R&D targeting combined Candida-bacterial-trichomonas panels that consolidate diagnostic workflows and capture margin from serial testing displacement. For New Entrants and Emerging Players: Capture home testing channel expansion through telehealth-integrated mail-in specimen services in United States metropolitan markets where 24-hour pharmacy access outstrips primary care appointment availability. Target Indian diagnostic expansion under Ayushman Bharat infrastructure investments equipping 150,000 health and wellness centers with rapid testing capability. Pursue battery-powered LAMP device development for urgent care deployment, leveraging isothermal amplification to bypass thermal cycler infrastructure requirements and CLIA complexity barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized molecular diagnostics firms possessing ribosomal RNA assay development expertise and established notified body relationships for IVDR conformity assessment. Long-term viability over the projection horizon favors platforms with multiplex detection capabilities and resistance gene profiling pipelines addressing fluconazole failure in immunocompromised populations. Monitor PMDA regulatory pathway accelerations for pharmacy-based testing in Japan as inflection indicator for point-of-care channel maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Assay Development | Consolidates Candida, bacterial vaginosis, and trichomonas detection into single-specimen workflows for German hospital accreditation compliance. |
| CLIA-Waiver Pathway Navigation | Unlocks urgent care and retail pharmacy deployment in Texas and Florida without laboratory staff requirements. |
| Resistance Gene Profiling Pipeline | Addresses azole resistance marker detection for immunocompromised populations with rising fluconazole failure rates. |
| Home Collection Integration | Enables telehealth-integrated mail-in specimen services bypassing pelvic examination requirements in United States metropolitan markets. |
| Notified Body Consortium Arrangement | Distributes IVDR documentation burdens across peer organizations to compress 18-24 month conformity assessment timelines. |
Study Parameters
Multiple input streams — structured interviews with diagnostic platform manufacturers, regulatory affairs specialists at notified bodies, and hospital laboratory procurement managers — were reconciled against FDA 510(k) clearance databases, IVDR conformity assessment records, and GPO contract filings. Secondary validation drew from CMS reimbursement code updates, PMDA approval pathway documentation, and antimicrobial stewardship mandate records from German and Japanese health ministries. Bottom-up demand modeling across test kit, diagnostic tool, consumable, and assay categories was triangulated against top-down market sizing from installed base estimates and replacement cycle analysis.
Historical volume trajectories were cross-referenced against panel input from assay developers and clinical microbiologists to establish growth rate boundaries across the projection horizon. Segmentation modeling incorporated product type, delivery mode, end user, and technology dimensions with specific attention to CLIA-waiver status tiers and molecular versus non-molecular platform distinctions. CAGR derivation rested on specimen volume growth in point-of-care versus laboratory channels, reimbursement code expansion for multiplex detection, and antimicrobial stewardship mandate adoption curves across target geographies.
Regulatory timeline delays, fluorophore supply disruptions, and lateral flow sensitivity limitations are the dominant revision risks to base case assumptions. Forecasts reflect documented IVDR conformity assessment durations, CLIA-waiver expansion trajectories, and telehealth platform integration rates without assuming step-change technology adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Efficacy Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Urine Sediment Testing Market
Testing Services
Redox Meter Market
Testing Services
Breath Biopsy Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
Asia-Pacific Newborn Screening Market