
 Global Mastopexy Market | 2026-2036
Global Mastopexy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mastopexy Market Foresight
A shortage of board-certified plastic surgeons is unwinding capacity constraints across key metropolitan clusters. Allergan leverages its established implant portfolio to sustain premium positioning in North American surgical suites. Polytech anchors European supply through specialized silicone texturing technologies. Johnson & Johnson competes across the full procedural ecosystem from sutures to wound closure systems.
Mastopexy denotes surgical breast elevation through tissue rearrangement, skin excision, and nipple-areolar complex repositioning, typically employing general anesthesia with operative durations of two to four hours. The procedure restores projection and contour for patients experiencing ptosis from aging, gravity, pregnancy, or substantial weight fluctuation. Traditional mastopexy dominates procedural volume due to its versatility across ptosis grades, while circumareolar techniques capture growing interest among younger patients seeking minimal scarring. Facility type segmentation reveals private clinics capturing the highest margin pools through concierge pricing and reduced overhead structures.
The US FDA enforces rigorous premarket approval pathways for breast implants, while the EU Medical Device Regulation mandates enhanced clinical follow-up and traceability systems. Brazil's ANVISA imposes comparable vigilance requirements that shape product registration timelines and post-market surveillance obligations. Stakeholders must monitor evolving reimbursement classifications for aesthetic versus reconstructive indications across national health frameworks.
Market Dynamics
Board-certified plastic surgeon shortages are tightening capacity across metropolitan surgical clusters, forcing facilities to extend booking timelines and prioritize higher-margin procedures. This supply compression is reshaping competitive positioning among ambulatory surgery centers and hospital-based practices.
Growth Catalysts
- Post-pregnancy restoration protocols:Rising clinical acceptance of mastopexy as a reconstructive rather than purely aesthetic intervention is expanding insurance preauthorization pathways in several national health frameworks.
- MDR traceability mandates:The EU Medical Device Regulation's enhanced clinical follow-up requirements are accelerating adoption of implant registry systems that improve long-term outcome data and patient confidence.
- Seoul-Busan corridor concentration:South Korea's domestic aesthetic surgery infrastructure is capturing regional demand through integrated consultation-to-recovery service models.
Market Restraints
- Silicone polymer cost volatility:Raw material fluctuations for medical-grade silicone are compressing implant manufacturer margins and pressuring downstream pricing.
- Surgeon supply concentration:Fellowship-trained aesthetic specialists cluster in São Paulo, Los Angeles, and Dubai, leaving secondary markets underserved.
- FDA surveillance friction:Tightened silicone implant post-market study obligations are extending product lifecycle costs and deterring new market entrants.
Strategic Opportunities
- Mexico City medical tourism:Proximity to US patient populations and competitive facility pricing are drawing cross-border surgical volume.
- Minimally invasive tissue suspension:Convergence of absorbable mesh technology with endoscopic approaches is opening same-day discharge protocols.
- Telemedicine consultation channels:Virtual preoperative assessment platforms are reducing geographic barriers to specialist access in underserved interior regions.
Industry Challenges
- Microsurgical flap reconstruction certification:Extended training timelines for advanced autologous techniques are constraining service line expansion.
- Legacy EMR integration:Proprietary implant tracking systems face interoperability barriers with hospital enterprise software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mastopexy Market |
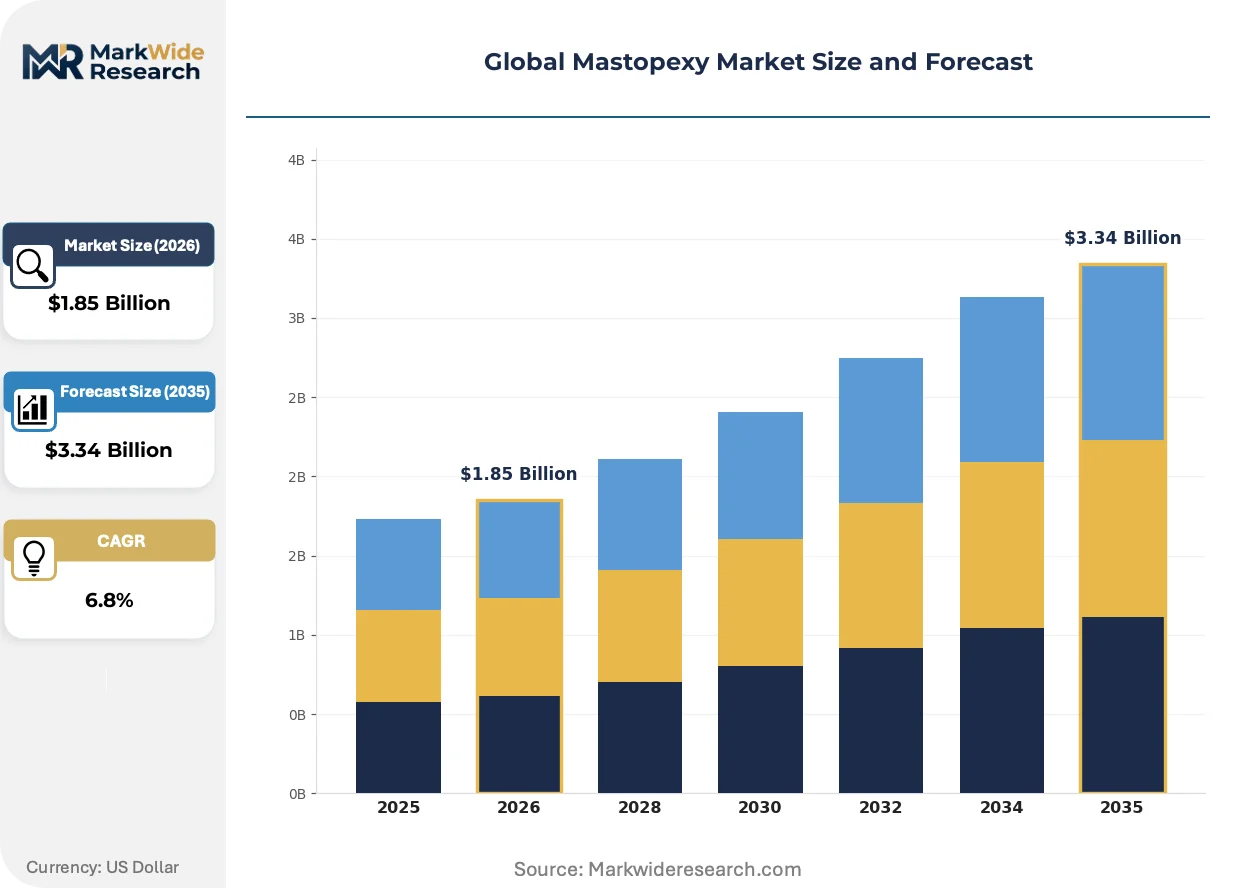
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Traditional Mastopexy, Vertical Mastopexy, Circumareolar Mastopexy, Inverted-T Mastopexy, Crescent Mastopexy Patient Age Group: 18-30 Years, 31-45 Years, 46-60 Years, Above 60 Years Facility Type: Private Clinics, Specialty Surgery Centers, Academic Medical Centers, Ambulatory Surgical Facilities Payment Mode: Out-of-Pocket, Private Insurance, Health Savings Account, Medical Tourism, Employer-Sponsored Plans |
| Companies Covered | Polytech, Cynosure, Allergan, Syneron Medical, SOLTA Medical, Sientra, Johnson & Johnson, Galderma, Integra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mastopexy Market Shifts & Advancements
Material science advances and regulatory data infrastructure are converging to reshape procedural safety profiles and patient selection criteria. These developments are compressing recovery timelines while elevating long-term outcome transparency.
Absorbable synthetic mesh scaffolding is supplanting traditional dermal autografts in select ptosis grades. Younger patient cohorts in urban Brazilian and South Korean markets are driving adoption of these resorbable alternatives. The shift is enabling shorter operative durations and reducing donor-site morbidity, though long-term capsular response data remains under collection.
ANVISA's 2023 vigilance requirements for textured implant surfaces are forcing manufacturers to revalidate surface topography classifications. Brazilian registration timelines have extended by eight to fourteen months for novel texturing protocols. Premium implant portfolios are absorbing compliance costs through concentrated São Paulo and Rio de Janeiro distribution networks.
Patients are consolidating surgical decisions through social media-validated surgeon selection rather than traditional referral pathways. Instagram and TikTok visual portfolios are displacing word-of-mouth recommendations among millennial and Gen Z demographics. This channel shift is most pronounced in Los Angeles, Miami, and Seoul aesthetic surgery markets.
Global Mastopexy Market Segmentation
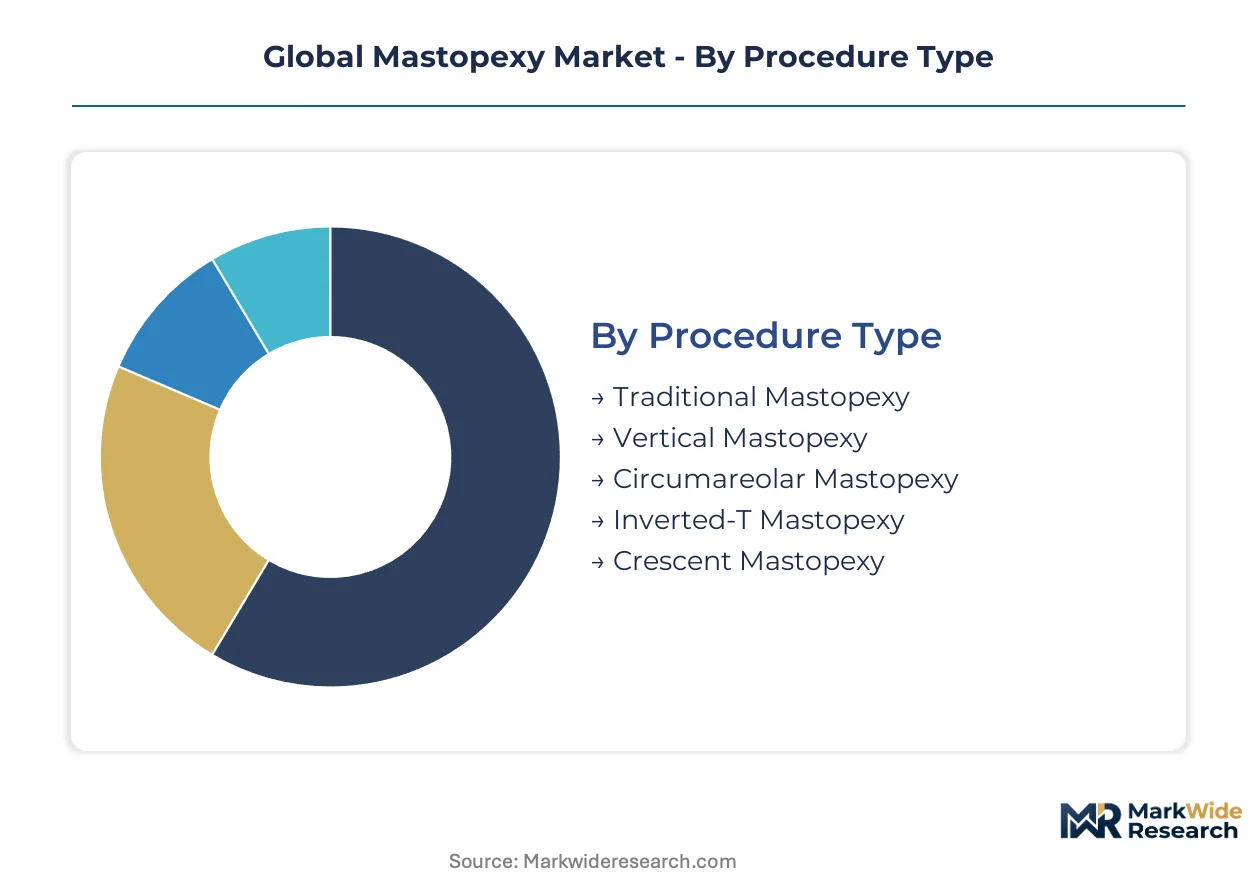
Procedure selection in mastopexy hinges on ptosis severity grading, scar tolerance, and implant combination requirements. Facility choice reflects patient willingness to trade institutional oversight for scheduling flexibility and pricing discretion. Payment pathways increasingly bifurcate between domestic out-of-pocket concentration and cross-border medical tourism corridors.
Procedure Type:
FDA premarket approval pathways differentiate implant-inclusive from autologous-only techniques, shaping surgeon training investments and facility credentialing requirements.
- Traditional Mastopexy:Combines circumvertical incision with horizontal inframammary extension for comprehensive tissue repositioning across severe ptosis grades. Demand concentrates in São Paulo and Los Angeles surgical clusters where aging patient demographics prioritize contour restoration over scar minimization. The technique accommodates simultaneous implant placement under FDA-mandated surveillance protocols.
- Circumareolar Mastopexy:Limits incision to periareolar circumference for mild ptosis correction with concealed scarring. Seoul and Rio de Janeiro clinics report expanding adoption among millennial patients seeking discrete aesthetic intervention. The approach excludes simultaneous textured implant use under ANVISA's 2023 surface topography revalidation requirements.
- Vertical Mastopexy:Eliminates horizontal component for moderate ptosis with lollipop scar pattern.
- Inverted-T Mastopexy:Retains full anchor incision for maximum lift amplitude in massive weight loss cases.
- Crescent Mastopexy:Employs upper periareolar crescent excision for nipple-areolar complex elevation without full circumference incision.
Established volume favors Traditional Mastopexy; emerging adoption favors Circumareolar Mastopexy.
Patient Age Group:
Cost tier stratification aligns with life-stage financial capacity and procedural complexity tolerance.
- 31-45 Years:Post-pregnancy restoration protocols dominate this cohort, with combined mastopexy-augmentation procedures capturing premium pricing in Dubai and Miami markets. The segment drives demand for absorbable mesh scaffolding that reduces operative duration and enables faster return to employment.
- 46-60 Years:Autologous tissue preference increases alongside implant surveillance fatigue, particularly among patients with prior silicone exposure requiring MRI compliance under FDA guidelines. Seoul academic medical centers report rising microsurgical flap consultation rates in this demographic.
- 18-30 Years:Social media-validated surgeon selection dominates decision pathways.
- Above 60 Years:Reconstructive indication preauthorization expands through Medicare Advantage plan coverage variations.
Volume concentration sits with 31-45 Years; steepest expansion trajectory belongs to 18-30 Years.
Facility Type:
Geographic supply concentration in metropolitan surgical clusters shapes patient access patterns and pricing power distribution.
- Private Clinics:Concierge pricing models and reduced overhead structures enable margin capture through bundled consultation-recovery packages. Los Angeles and São Paulo private facilities concentrate board-certified plastic surgeon supply, extending booking timelines that filter price-sensitive demand.
- Specialty Surgery Centers:Accreditation standards from AAAASF and AAAHC drive capital investment in anesthesia infrastructure and emergency preparedness. Mexican border facilities leverage these certifications to attract cross-border volume from Texas and California patient populations.
- Academic Medical Centers:Fellowship training obligations subsidize complex autologous reconstruction availability.
- Ambulatory Surgical Facilities:Same-day discharge protocols align with absorbable mesh adoption trends.
Margin pools concentrate in Private Clinics; fastest volume growth occurs in Specialty Surgery Centers.
Payment Mode:
Customer type differentiation separates domestic elective consumption from internationally mobile surgical tourism.
- Out-of-Pocket:Direct price transparency enables procedure bundling with postoperative care packages in Brazilian and South Korean urban markets. Patients in this channel demonstrate highest willingness to absorb ANVISA compliance cost pass-through for premium implant portfolios.
- Medical Tourism:Mexico City and Seoul corridors capture US patient volume through competitive facility pricing and shortened scheduling intervals. Integrated consultation-to-recovery service models reduce travel burden and complication management friction.
- Private Insurance:Reconstructive indication preauthorization pathways expand in select national health frameworks.
- Health Savings Account:Tax-advantaged accumulation aligns with planned elective procedure timelines.
- Employer-Sponsored Plans:Cosmetic surgery riders remain rare outside executive benefit tiers.
Revenue concentration favors Out-of-Pocket; cross-border flow expansion favors Medical Tourism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA surveillance protocols shape procedural safety standards that cascade through developed aesthetic surgery markets. Brazil's ANVISA and South Korea's MFDS impose parallel vigilance requirements that structure regional competitive dynamics. Metropolitan surgical clusters in São Paulo, Seoul, and Los Angeles concentrate board-certified capacity and absorb compliance cost pass-through.
United States
Post-pregnancy restoration protocols drive demand among the 31-45 year demographic seeking combined mastopexy-augmentation procedures. FDA's tightened silicone implant surveillance standards extend product lifecycle costs and elevate procedural safety protocols. Los Angeles and Miami surgical clusters concentrate premium private clinic capacity with extended booking timelines filtering price-sensitive demand.
Brazil
Domestic aesthetic surgery expansion and medical tourism corridors concentrate demand through São Paulo and Rio de Janeiro facilities. ANVISA's 2023 vigilance requirements for textured implant surfaces force manufacturers to revalidate surface topography classifications, extending registration timelines by eight to fourteen months. São Paulo private clinics absorb compliance costs through concentrated distribution networks serving premium implant portfolios.
South Korea
The Seoul-Busan corridor captures regional demand through integrated consultation-to-recovery service models targeting millennial and Gen Z demographics. MFDS implant registry requirements align with EU MDR traceability mandates, accelerating adoption of long-term outcome data systems. Seoul academic medical centers report rising microsurgical flap consultation rates among patients exhibiting implant surveillance fatigue.
Mexico
Proximity to US patient populations and competitive facility pricing draw cross-border surgical volume through Mexico City medical tourism infrastructure. AAAASF and AAAHC accreditation standards drive capital investment in anesthesia infrastructure at specialty surgery centers. Northern border facilities leverage these certifications to attract Texas and California patient populations seeking shortened scheduling intervals.
Germany
EU Medical Device Regulation's enhanced clinical follow-up requirements accelerate adoption of implant registry systems improving patient confidence. Polytech anchors European supply through specialized silicone texturing technologies manufactured under MDR compliance frameworks. German metropolitan clusters concentrate reconstructive indication preauthorization pathways expanding through statutory health insurance framework variations.
Global Mastopexy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the mastopexy market structure. Allergan and Johnson & Johnson occupy positions across the full procedural ecosystem from implants through wound closure systems. Polytech anchors European supply through specialized manufacturing capabilities. The competitive terrain rewards three archetypes: implant portfolio specialists, full-procedure ecosystem integrators, and absorbable mesh technology developers. M&A activity concentrates around mesh scaffolding capabilities and geographic expansion into medical tourism corridors.
Within the implant portfolio specialist tier, Allergan exemplifies premium positioning sustained through established silicone portfolios under FDA surveillance protocols. Polytech occupies a position as the European anchor through specialized texturing technologies compliant with MDR traceability mandates. Johnson & Johnson represents the full-procedure ecosystem archetype competing across sutures, wound closure systems, and implant adjacencies. These three entities illustrate how regulatory compliance capabilities and geographic concentration determine competitive positioning in capacity-constrained metropolitan surgical clusters.
| Leading Market Players |
|---|
| Polytech |
| Cynosure |
| Allergan |
| Syneron Medical |
| SOLTA Medical |
| Sientra |
| Johnson & Johnson |
| Galderma |
| Integra |
| Others |
Supply & Pricing Matrix
Eighteen-month ANVISA revalidation timelines for textured implant surfaces compress manufacturer margins while São Paulo private clinics capture pricing premiums through surgeon scarcity. This lead-time extension concentrates cost pass-through capacity in metropolitan surgical clusters where board-certified plastic surgeon shortages filter price-sensitive demand toward secondary markets.
Pricing Analysis
Los Angeles-to-Mexico City facility pricing spreads reach threefold multiples for comparable mastopexy procedures, with cross-border medical tourism corridors capturing volume from Texas and California patient populations. Three-tier pricing structure across premium concierge clinics, accredited specialty surgery centers, and economy-tier ambulatory facilities differentiates on surgeon certification grade and implant portfolio tier. Cost compression in economy tiers intensifies because silicone polymer feedstock volatility feeds through medical-grade implant manufacturing. Out-of-pocket patients in São Paulo and Seoul demonstrate lowest price sensitivity, while HSA-dependent cohorts in US interior regions exhibit highest elasticity.
Supply Chain Analysis
Germany and the United States anchor medical-grade silicone production for implant manufacturing, with specialized texturing capabilities concentrated in European MDR-compliant facilities. Raw material dependencies center on platinum-cured silicone elastomers, barrier membrane substrates, and resorbable polymer precursors for mesh scaffolding. Single-source vulnerability runs through concentrated texturing technology licensors facing extended Brazilian registration timelines. Distribution runs through manufacturer-direct hospital contracts in developed markets and concentrated distributor networks in medical tourism corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-surgical tissue tightening modalities threaten surgical mastopexy volume among mild ptosis cohorts, forcing incumbents to defend procedural relevance through outcome durability differentiation.
For Market Incumbents: Compound regulatory compliance capabilities into competitive moats by accelerating MDR-aligned implant registry deployment ahead of EU enforcement waves. Deepen backward integration into resorbable mesh polymer production to capture margin pools shifting from permanent implants. Defend against endoscopic tissue suspension substitutes by embedding long-term capsular response data into surgeon training protocols.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission pathways opens European market entry ahead of MDR transition completion. Target Mexico City and Seoul corridor infrastructure gaps with absorbable mesh distribution partnerships bypassing incumbent implant portfolios. Capture telemedicine consultation platform white space in US interior regions underserved by fellowship-trained aesthetic specialists.
For Investors and Strategic Acquirers: Long-term, this sits as a capacity-constrained specialist consolidation play because surgeon supply inelasticity protects pricing power across metropolitan clusters. Acquisition profiles favor absorbable mesh technology developers with ANVISA pre-submission dossiers and established São Paulo distributor relationships. Watch FDA silicone implant post-market study obligation modifications as volume inflection signal for premium implant portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR-Aligned Implant Registry Deployment | EU traceability mandates accelerate patient confidence and long-term outcome data capture. |
| Absorbable Mesh Manufacturing Scale-Up | Resorbable polymer capacity expansion captures demand shifting from permanent silicone portfolios. |
| Telemedicine Consultation Platform Launch | Virtual preoperative assessment reduces geographic barriers in surgeon-underserved interior regions. |
| ANVISA Fast-Track Registration Pathway | Brazilian regulatory pre-validation compresses fourteen-month texturing revalidation timelines. |
| Cross-Border Facility Certification Upgrade | AAAASF accreditation attracts US patient volume through Mexico City medical tourism infrastructure. |
Research Methodology
Cross-validation between plastic surgeon interview panels and ANVISA registration database analysis anchors the qualitative findings on Brazilian market structure. Primary fieldwork encompassed hospital purchasing committee representatives, biomedical engineers at academic medical centers, GPO contracts managers, and private clinic operations directors across São Paulo, Seoul, Los Angeles, and Mexico City clusters. Secondary validation drew from FDA premarket approval filings, EU MDR notified body guidance documents, MFDS implant registry disclosures, and customs trade data on medical-grade silicone imports. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data.
Sensitivity analysis on surgeon supply elasticity and silicone polymer cost pass-through assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include procedure type, patient age cohort, facility accreditation tier, and payment mode bifurcation between domestic out-of-pocket and medical tourism channels. CAGRs derive from installed base dynamics of board-certified plastic surgeons and procedural volume intensity per metropolitan cluster. Forecast inputs incorporate ANVISA registration timeline distributions and MDR traceability system adoption curves.
Underlying assumptions cover sustained medical tourism corridor expansion and stable platinum-cured silicone feedstock availability, with deviation risk concentrated in FDA surveillance obligation modifications and resorbable mesh long-term safety data publication. Recalibration cycles align with material shifts in regulatory revalidation timelines and social media channel influence on surgeon selection patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market