
 Calcium Ammonium Nitrate Market | 2026-2036
Calcium Ammonium Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Ammonium Nitrate Market Analysis
Multi-source procurement for ammonium nitrate feedstock is expanding across European fertilizer manufacturers. Yara International ASA leverages its integrated ammonia and nitric acid network to sustain cost advantages in Nordic supply zones. EuroChem Group anchors its position through captive phosphate and nitrogen assets in Russia and Belgium. Grupa Azoty S.A. competes on sulfur-efficient formulations tailored to Polish and Central European soil profiles.
Calcium ammonium nitrate is a nitrogenous fertilizer produced by neutralizing nitric acid with calcium carbonate or dolomite, yielding a product containing approximately 27 percent nitrogen by weight with added calcium for soil structure improvement. Its primary industrial purpose is to deliver water-soluble nitrogen with reduced volatility and lower soil acidification compared to straight ammonium nitrate, making it suitable for top-dressing and fertigation systems. Granular CAN dominates volume flows due to superior handling characteristics and compatibility with mechanized spreaders across broadacre farming. The horticulture end-use segment is gaining share as protected cultivation in Spain and the Netherlands demands precision nitrogen delivery with minimal chloride content.
REACH registration requirements and the EU F-Gas Regulation govern nitrogen compound handling and emissions profiling across the European production base. ECHA classification protocols for oxidizing substances directly shape packaging standards and transport modal choices for cross-border CAN shipments. The EPA oversees analogous hazard communication and environmental release thresholds for U.S. import and storage facilities. Stakeholders must monitor evolving carbon border adjustment mechanisms and national fertilizer subsidy reforms that could redirect trade flows between Black Sea exporters and Atlantic buyers.
Market Dynamics
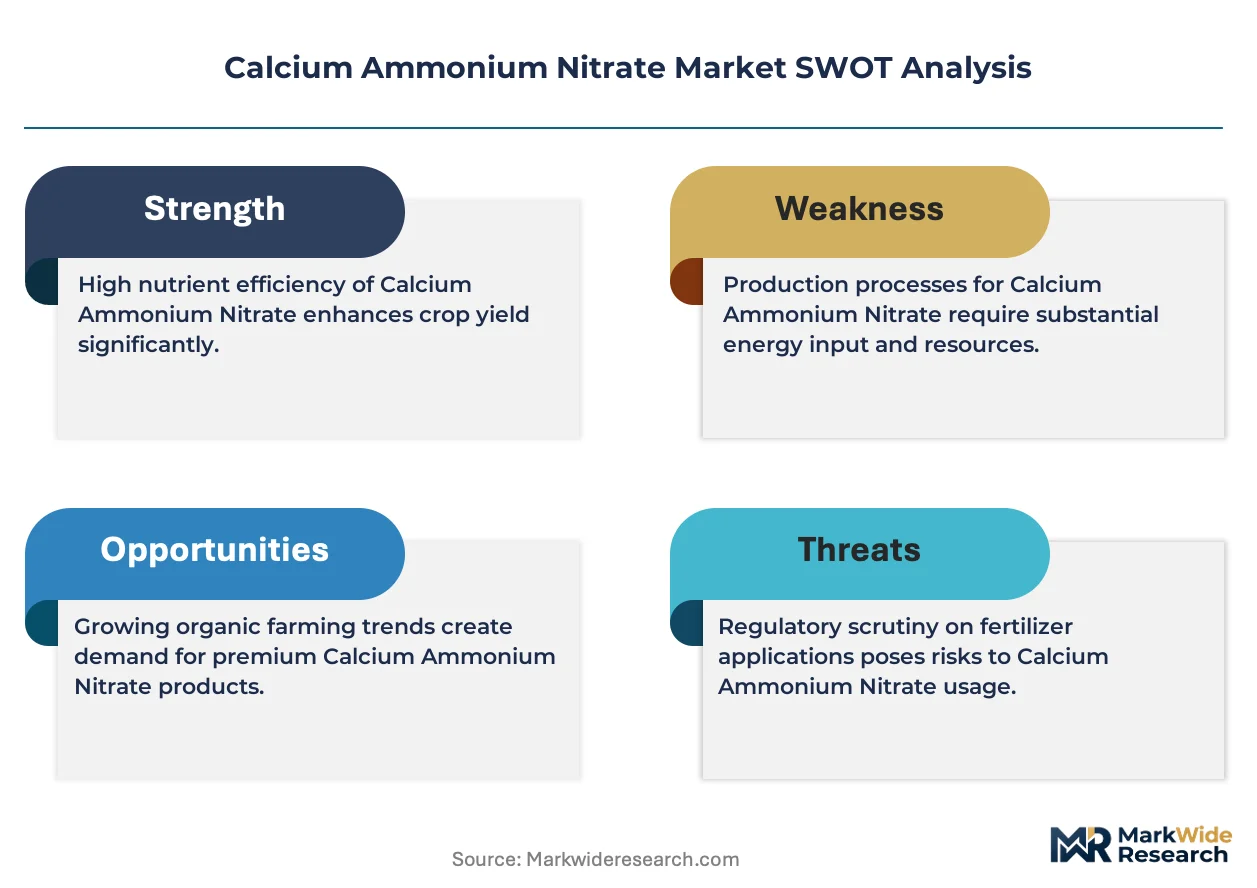
EU F-Gas Regulation enforcement is compressing nitrogen fertilizer production margins while redirecting capital toward emission-abatement retrofits across nitric acid plants serving CAN feedstock supply.
Growth Catalysts
- Soybean-corn rotation expansion:Brazilian and Argentine farmers are expanding CAN application rates in double-cropping systems to manage nitrogen volatility during wet-season top-dressing windows.
- REACH registration alignment:Harmonized ECHA classification protocols for oxidizing substances are streamlining cross-border CAN shipments between EU production hubs and Eastern European grain belts.
- Fertigation system penetration:Protected cultivation operators in Spain and the Netherlands are adopting water-soluble CAN formulations compatible with precision drip-irrigation infrastructure.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings directly compress nitric acid production economics at European CAN manufacturing sites.
- Black Sea supply concentration:Captive nitrogen and phosphate assets in Russia create asymmetric feedstock access for integrated producers versus merchant buyers.
- Urea substitution pressure:Lower-cost straight nitrogen fertilizers displace CAN in price-sensitive broadacre applications where calcium benefits are undervalued.
Strategic Opportunities
- Polish soil-profile specialization:Sulfur-efficient CAN formulations tailored to Central European acidic soils offer premium positioning against generic imports.
- Carbon border adjustment preparation:EU CBAM implementation timelines create first-mover advantage for producers with verified low-emission nitric acid production.
- Horticulture channel development:Direct supply relationships with Dutch greenhouse cooperatives bypass traditional distributor markups for high-purity granular grades.
Industry Challenges
- Nitric acid plant retrofit execution:Catalyst replacement and abatement system installation require extended downtime coordination with seasonal demand peaks.
- Multimodal logistics certification:ECHA oxidizing substance packaging standards demand specialized container fleets and handler training across Baltic and North Sea ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Ammonium Nitrate Market |
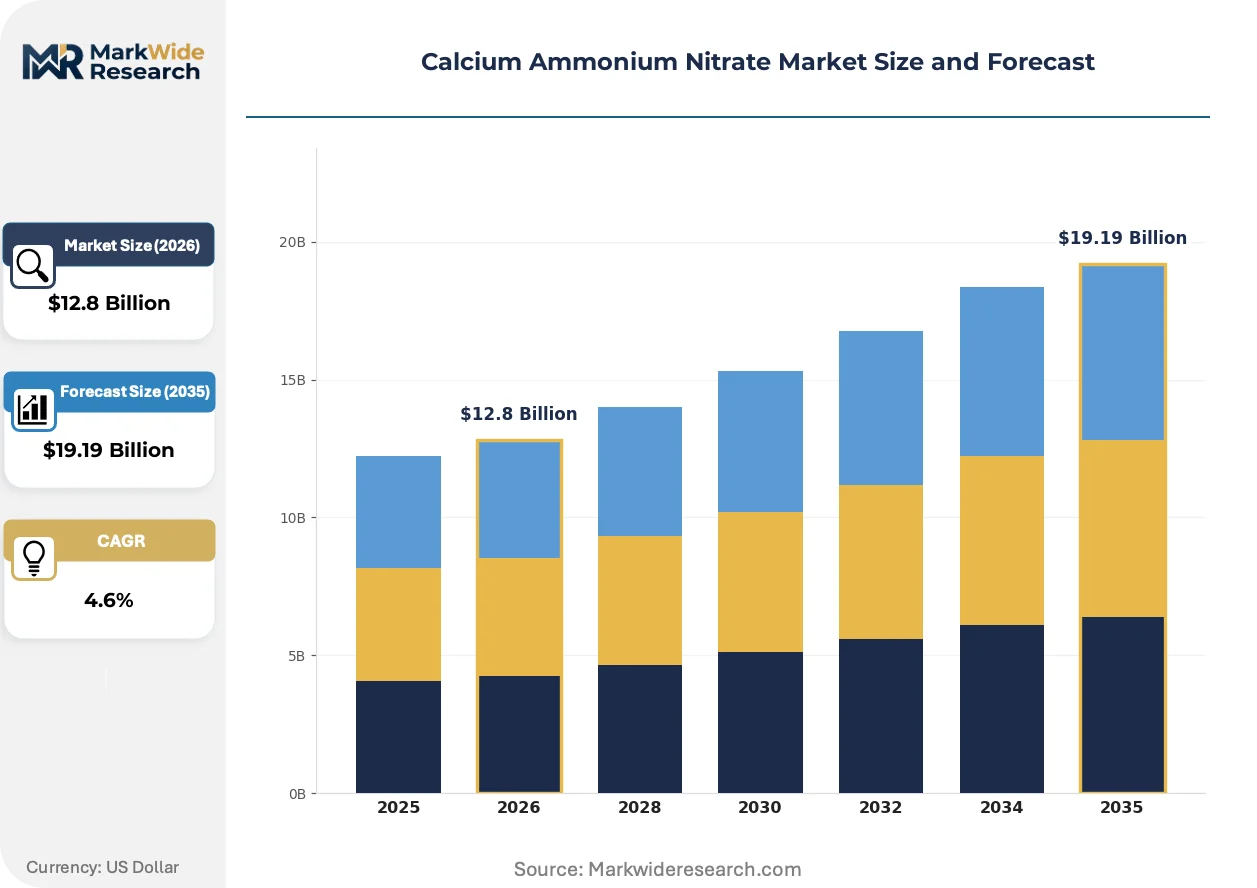
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Pellet, Powder, Crystalline End Use Industry: Agriculture, Horticulture, Forestry, Landscaping Application: Fertilizer, Soil Conditioner, Agricultural Chemicals, Plant Nutrition Packaging Type: Bags, Bulk, Drums, Containers |
| Companies Covered | Yara International ASA, EuroChem Group, Achema AB, CF Industries Holdings Inc., Uralchem JSC, Grupa Azoty S.A., Acron Group, HELM AG, Fertiberia S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Ammonium Nitrate Market Emerging Trajectories
Automation of production and application systems is compressing labor intensity while tightening nitrogen-use efficiency standards across European and South American farming operations.
Sensor-guided spreader technology is automating variable-rate CAN application in Brazilian soybean operations. Large-scale cooperatives in Mato Grosso are retrofitting existing equipment with GPS-enabled rate controllers. This automation is compressing over-application waste while satisfying financier requirements for precision agriculture documentation.
EU F-Gas Regulation phase-down schedules are forcing nitric acid plant operators to replace high-global-warming-potential abatement refrigerants. German and French facilities face accelerated capital deployment timelines to maintain operating permits. Granular CAN producers with integrated ammonia networks are absorbing retrofit costs more readily than merchant nitric acid buyers.
Greenhouse operators in the Netherlands are consolidating procurement through grower-owned purchasing cooperatives. These entities negotiate direct supply contracts with nitrogen compound manufacturers, displacing traditional agricultural distributor relationships. This channel compression is most advanced in the Westland cluster, where glasshouse density justifies dedicated bulk liquid CAN delivery infrastructure.
Calcium Ammonium Nitrate Market Segmentation
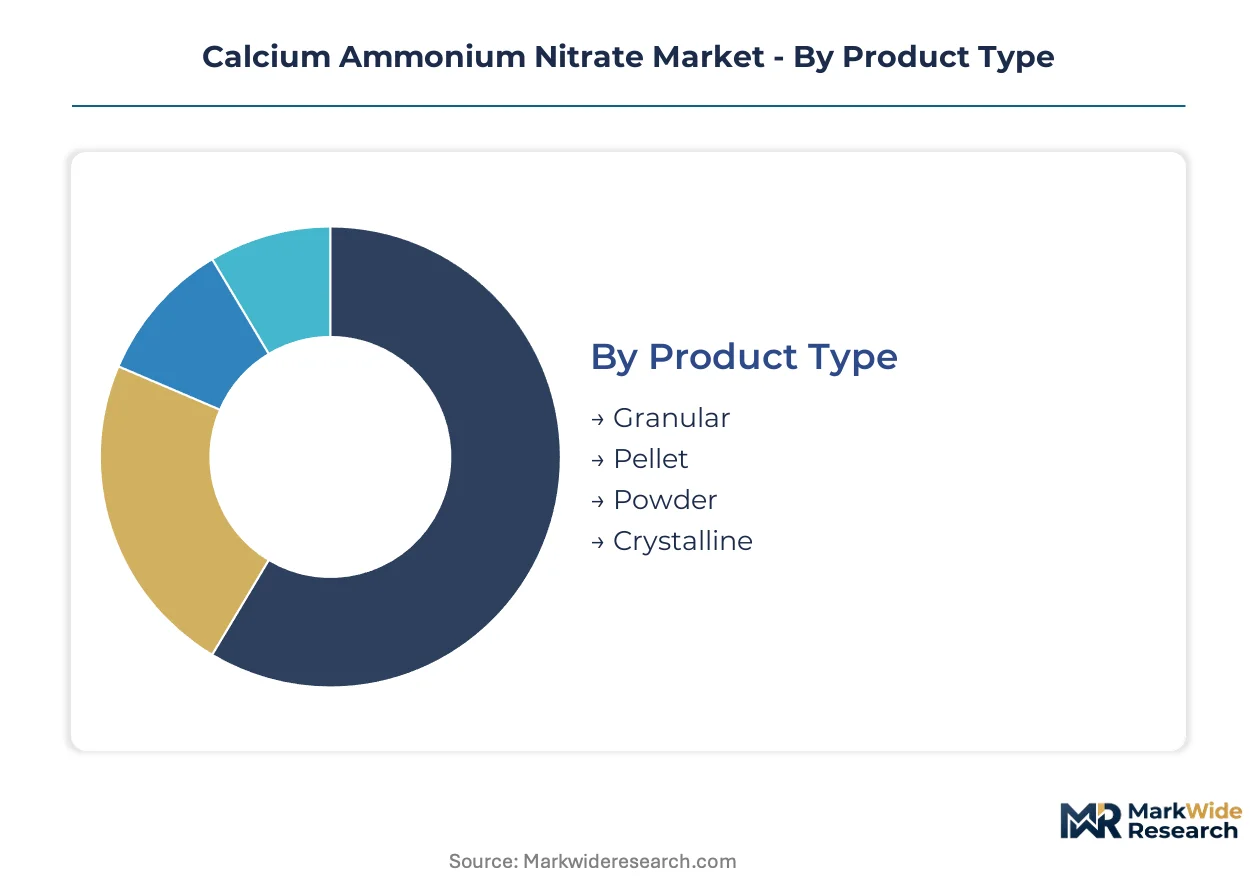
Calcium ammonium nitrate formulations diverge sharply across handling requirements and nutrient delivery precision. Product morphology dictates compatibility with mechanized spreading, fertigation infrastructure, and protected cultivation systems. End-use segmentation reveals how nitrogen-calcium delivery priorities shift between broadacre grain operations and intensive horticulture.
Product Type:
Granular and pellet formats dominate standalone mechanical application, while powder and crystalline grades embed into compound blending and liquid suspension systems.
- Granular:Spherical particles sized 2-4mm deliver uniform spread patterns across Brazilian soybean fields. Mato Grosso cooperatives specify this grade for GPS-guided variable-rate top-dressing. The format commands volume leadership in Black Sea corridor exports serving Eastern European grain belts.
- Pellet:Compressed cylindrical forms reduce dust generation during pneumatic conveying. Dutch greenhouse operators in Westland cluster specify pelletized CAN for automated batching in closed-loop irrigation. The morphology suits high-frequency application cycles in precision horticulture.
- Powder:Fine-milled material integrates into compound NPK granulation at Belgian blending facilities.
- Crystalline:High-purity prills dissolve rapidly for stock solution preparation in Spanish drip-fertigation networks.
Volume placements concentrate in Granular; the faster expansion belongs to Pellet.
End Use Industry:
Cost tier segmentation separates commodity nitrogen buyers from premium soil-structure-conscious operators.
- Agriculture:Broadacre cereal and oilseed producers apply CAN as a basal or top-dressing nitrogen source. Polish and Ukrainian wheat growers prioritize the calcium component for acidic soil remediation. The segment absorbs bulk pricing volatility through forward purchasing agreements.
- Horticulture:Protected cultivation in Almeria and the Netherlands demands chloride-free nitrogen with precise calcium dosing. Spanish greenhouse cooperatives negotiate direct supply contracts bypassing distributor markups. The segment pays formulation premiums for soluble grades compatible with drip infrastructure.
- Forestry:Plantation managers in Nordic regions apply CAN during establishment phases on nutrient-poor podzols.
- Landscaping:Turf maintenance contractors in German urban centers specify low-burn formulations for ornamental applications.
Revenue concentration sits with Agriculture; Horticulture climbs the fastest on per-tonne value realization.
Application:
Application purpose determines margin structure, with straight fertilizer use competing on cost and soil amendment functions commanding technical premiums.
- Fertilizer:Primary nitrogen delivery for crop yield optimization dominates tonnage flows. Argentine corn-soy rotations rely on CAN for wet-season nitrogen stability where urea volatilization risks escalate. The application faces persistent substitution pressure from lower-cost straight nitrogen sources.
- Soil Conditioner:Calcium delivery for pH management and structural improvement in acidic profiles. Polish farmers apply CAN specifically for sulfur-deficient loams where gypsum alternatives prove uneconomical. The application captures premium positioning where soil testing drives prescription agriculture.
- Agricultural Chemicals:Intermediate feedstock for compound fertilizer manufacturing at integrated nitrogen-phosphate complexes.
- Plant Nutrition:Specialty formulations for high-value crop segments with micronutrient co-delivery requirements.
Tonnage leadership belongs to Fertilizer; Soil Conditioner gains share fastest on agronomic advisory penetration.
Packaging Type:
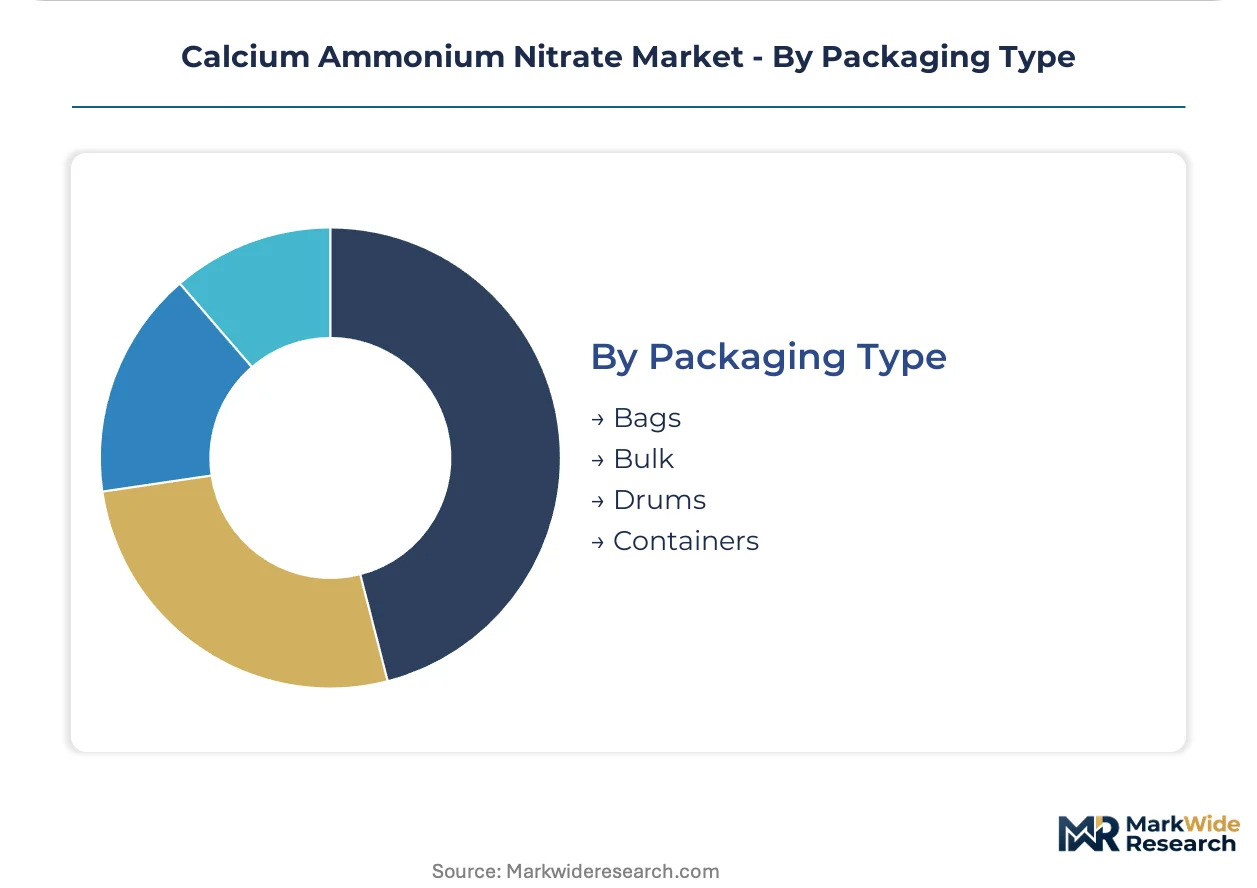
Customer type and procurement scale dictate packaging selection, from grower cooperative bulk handling to distributor-mediated bagged goods.
- Bulk:Unpacked material flows via pneumatic discharge into cooperative storage silos. Large-scale farming operations in Brazil's Cerrado region specify bulk delivery to minimize handling labor and packaging waste. The format requires dedicated logistics infrastructure and on-farm storage investment.
- Bags:25-50kg woven polypropylene units serve smallholder and distributor channel requirements. French agricultural supply cooperatives maintain bagged inventory for fragmented customer bases lacking bulk handling capacity. The format carries higher per-tonne logistics costs but enables market access breadth.
- Drums:Steel containment for liquid CAN concentrates in industrial processing applications.
- Containers:Intermediate bulk units for intra-European multimodal shipments under ECHA oxidizing substance protocols.
Volume concentrates in Bulk; Containers expand most quickly on cross-border trade formalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas deposits in western Siberia and the North Sea anchor nitrogen fertilizer production economics across the Calcium Ammonium Nitrate Market. Feedstock proximity shapes manufacturing placement and trade flow directionality between producing basins and consuming agricultural zones.
Germany
Domestic wheat and sugar beet cultivation sustains steady CAN consumption in the North German Plain. The EU F-Gas Regulation mandates nitric acid plant retrofits that compress operating margins at Ludwigshafen and Brunsbüttel chemical complexes. Rhineland-Palatinate fertilizer cooperatives are negotiating long-term supply contracts with integrated producers to secure winter top-dressing volumes.
Brazil
Soybean-corn double-cropping in Mato Grosso and Goiás drives wet-season nitrogen demand where urea volatilization risks escalate. ANVISA oversees agricultural chemical registration timelines that affect import clearance for specialty CAN formulations. The Cerrado agricultural frontier around Rondonópolis is expanding mechanized spreader fleets compatible with granular product specifications.
Poland
Acidic loam soils in Greater Poland and Silesia generate calcium-specific demand for pH remediation alongside nitrogen delivery. National fertilizer efficiency programs subsidize precision application equipment that favors CAN over straight ammonium nitrate. The Puławy nitrogen complex anchors domestic supply capacity serving Central European grain cooperatives.
Netherlands
Greenhouse horticulture in Westland and North Holland demands chloride-free nitrogen with precise calcium dosing for hydroponic systems. REACH registration requirements govern cross-border shipments from Belgian blending facilities into Dutch distribution networks. Rotterdam port infrastructure handles bulk CAN imports destined for cooperative storage silos across the Randstad cluster.
Argentina
Corn-soy rotations in Buenos Aires and Córdoba provinces rely on CAN for nitrogen stability during humid growing seasons. National agricultural ministry guidelines promote reduced-emission fertilizers that align with CAN's lower volatilization profile. The Rosario grain hub coordinates import logistics for nitrogen products arriving via Paraná River barge networks.
Calcium Ammonium Nitrate Market Vendor Landscape
Capacity expansion dominates the current landscape as producers retrofit nitric acid plants to meet tightening emission standards. The vendor base clusters around integrated nitrogen-phosphate complexes and regional blending specialists serving distinct soil-profile requirements. Three archetypes define competitive positioning: captive feedstock operators with ammonia-nitric acid integration, regional formulators tailoring sulfur-efficient blends, and merchant traders arbitraging Black Sea supply into Atlantic markets. Geographic expansion and portfolio diversification toward horticulture-grade formulations represent the dominant competitive moves.
Among Nordic integrated producers, Yara International ASA occupies a position exemplifying captive ammonia network advantages. EuroChem Group anchors the resource-backed archetype through nitrogen and phosphate asset control spanning multiple jurisdictions. Grupa Azoty S.A. represents the regional specialization tier with formulation development calibrated to Central European agronomic conditions.
| Leading Market Players |
|---|
| Yara International ASA |
| EuroChem Group |
| Achema AB |
| CF Industries Holdings Inc. |
| Uralchem JSC |
| Grupa Azoty S.A. |
| Acron Group |
| HELM AG |
| Fertiberia S.A. |
| Others |
Supply Flow & Price Mechanics
Natural gas feedstock costs cascade through nitric acid production economics into three-tier pricing structure across premium, standard, and economy levels for calcium ammonium nitrate. Ammonia contract volatility at Ludwigshafen and Brunsbüttel complexes feeds directly into granular product premiums, while Black Sea corridor supply anchors economy-tier spot pricing for Eastern European grain cooperatives.
Pricing Analysis
Service bundling separates horticulture-grade pellet formulations with technical agronomy support from unbundled bulk granular shipments to broadacre cooperatives. Price differentiation hinges on REACH certification tier and volume scale, with Dutch greenhouse buyers paying premiums for chloride-free soluble grades. Pricing pressure stems from urea substitution in Brazilian soybean operations where calcium benefits command limited recognition. Smallholder distributors through French agricultural supply cooperatives exhibit highest price sensitivity; integrated Mato Grosso farming operations show lowest.
Supply Chain Analysis
Direct-to-cooperative channels handle hyperscale buyer demand across Brazil's Cerrado region, bypassing traditional distributor markups. Supply concentrates in Russia, Belgium, and Poland, with captive ammonia-nitric acid integration at Puławy and Ludwigshafen complexes. Feedstock draws from western Siberian natural gas deposits, North Sea offshore fields, and Polish coal-bed methane. Single-source vulnerability runs through Black Sea nitrogen asset concentration amid EU F-Gas Regulation compliance timelines. Distribution runs through Rotterdam bulk handling, Paraná River barge networks, and Baltic Sea specialized container fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium ammonium nitrate market positioning is consolidating around upstream ammonia-nitric acid integration and downstream horticulture channel control. Players with captive feedstock and direct greenhouse cooperative relationships are capturing margin expansion unavailable to merchant buyers.
For Market Incumbents: Extend backward integration into ammonia production to insulate margins from natural gas volatility at European manufacturing sites. Lock in long-term offtake agreements with Dutch Westland cluster cooperatives before channel compression displaces traditional distributor relationships. Urea substitution pressure in Brazilian broadacre applications demands sulfur-efficient formulation investment to defend premium positioning. For New Entrants and Emerging Players: Begin with Polish acidic soil remediation segments where calcium-specific demand outpaces generic nitrogen supply. Target Spanish Almeria greenhouse cooperatives seeking direct manufacturer relationships for chloride-free soluble grades. Lead with precision application equipment bundling to bypass established distributor infrastructure. For Investors and Strategic Acquirers: EU F-Gas Regulation nitric acid plant retrofit completion timelines are the leading indicator that integrated producers will consolidate merchant-dependent competitors. Five-to-ten-year viability favors asset-heavy nitrogen-phosphate complexes with verified low-emission production and established Baltic-North Sea logistics corridors. Acquisition focus: regional formulators with sulfur-efficient blend capabilities and direct horticulture channel access. Watch for CBAM implementation acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive natural gas feedstock at western Siberian fields insulates margin from spot volatility. |
| Long-term Supply Agreement | Dedicated contracts with Dutch Westland greenhouse cooperatives bypass distributor markups. |
| Green Manufacturing Transition | Low-emission nitric acid retrofit at German complexes secures EU F-Gas Regulation compliance. |
| Capacity Expansion | Puławy nitrogen complex additions serve Central European sulfur-deficient soil demand. |
| Joint Venture | Brazilian Cerrado partnerships deploy precision spreader fleets with granular CAN bundling. |
Methodological Framework
Trade statistics from Eurostat, customs declarations from Brazil's MDIC, and nitrogen industry association reports formed the secondary backbone for this analysis. Primary interviews with nitric acid plant managers, procurement leads at Mato Grosso farming cooperatives, Dutch greenhouse cooperative technical directors, and Polish fertilizer distribution channel partners validated production cost structures and demand patterns. Bottom-up volume modeling across granular, pellet, powder, and crystalline product tiers triangulated against top-down nitrogen consumption forecasts.
Bottom-up segment sizing by product morphology, end-use industry, application purpose, and packaging format fed into analytical lens aggregation across the projection horizon. CAGRs derived from historical trade flow trajectories and capacity expansion announcements. Forecast inputs incorporated EU F-Gas Regulation retrofit timelines, ANVISA registration clearance patterns, and Brazilian soybean-corn rotation expansion rates.
Underlying measurement precision varies by segment; horticulture-grade pellet and crystalline formulations carry tighter precision than bulk granular commodity flows. Forecasts reflect assumptions around natural gas price normalization, Black Sea corridor logistics stability, and carbon border adjustment mechanism implementation scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Africa Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
China Organic Fertilizers Market