
 Vietnam Fertilizers Market | 2026-2036
Vietnam Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Fertilizers Market Analytics
China's urea capacity expansion is tilting regional trade flows and pressuring Vietnamese producers to defend margins through cost discipline. PetroVietnam Fertilizer and Chemicals Corporation JSC leverages its integrated ammonia-to-urea complex at Ca Mau to sustain feedstock cost advantages against imported alternatives. Binh Dien Fertilizer JSC anchors distribution through provincial dealer networks in the Mekong Delta, while Baconco Company Limited differentiates via specialized water-soluble formulations for high-value horticulture.
Vietnam fertilizers comprise nitrogenous, phosphatic, and potassic compounds formulated to replenish soil macronutrients, with urea typically containing 46% nitrogen by weight and NPK grades manufactured through steam granulation or bulk blending to achieve specified N-P-K ratios. The product type landscape sees urea dominating volume due to rice cultivation dependency, while NPK blends capture expanding share as precision agriculture protocols advance and farmers substitute single-nutrient applications. Delivery mode segmentation reveals granular formats leading in field crop applications, whereas liquid formulations gain traction in greenhouse horticulture and fertigation systems where nutrient uniformity commands premium pricing.
Vietnam's Ministry of Agriculture and Rural Development enforces fertilizer quality standards through registration and inspection protocols, while the General Department of Customs coordinates import licensing to prevent substandard product entry. BIS-equivalent national standards mandate labeled nutrient content verification, shaping manufacturer compliance costs and distributor sourcing decisions. Stakeholders must monitor evolving biofertilizer policy frameworks and carbon accounting requirements that could redirect R&D investment toward microbial inoculants and slow-release formulations.
Market Dynamics
China's urea capacity expansion is flooding regional markets with low-cost nitrogenous supply, compressing Vietnamese producer margins and forcing domestic manufacturers toward feedstock integration and specialty formulation differentiation to survive price-driven commodity competition.
Growth Catalysts
- Balanced Nutrition Mandates:Vietnam's Ministry of Agriculture and Rural Development promotes NPK substitution protocols in rice-intensive provinces, accelerating blend adoption over single-nutrient applications.
- Ca Mau Gas Field Integration:Captive ammonia feedstock from offshore gas fields insulates integrated producers from international urea price volatility.
- Greenhouse Horticulture Expansion:Da Lat and Lam Dong provinces drive water-soluble and fertigation-grade fertilizer consumption for year-round vegetable and flower exports.
Market Restraints
- Natural Gas Price Volatility:Non-integrated urea manufacturers face margin erosion when global LNG benchmarks spike, as gas constitutes the majority of ammonia production cost.
- Import Concentration Risk:Vietnamese distributors rely heavily on Chinese and Middle Eastern potash suppliers, exposing the market to shipping disruption and currency fluctuation.
- Slow-Release Formulation Cost Premium:Polymer-coated and sulfur-coated urea products carry 40-60% price premiums over conventional grades, limiting smallholder farmer adoption.
Strategic Opportunities
- Central Highlands Underpenetration:Coffee and pepper cultivation in Dak Lak and Gia Lai provinces remains underserved by precision agriculture input providers.
- Biofertilizer Regulatory Tailwind:Draft circulars from the Ministry of Agriculture signal future registration fast-tracks for microbial inoculant products containing azotobacter and phosphate-solubilizing bacteria.
- Digital Platform Distribution:Provincial cooperative networks and agri-fintech platforms enable direct manufacturer-to-farmer sales, bypassing traditional dealer markups.
Industry Challenges
- Soil Testing Capacity Shortage:Vietnam's agricultural extension system lacks sufficient trained agronomists and laboratory infrastructure to support widespread precision fertilization recommendations.
- Quality Certification Backlogs:Ministry of Agriculture registration queues for new fertilizer formulations extend 12-18 months, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Fertilizers Market |
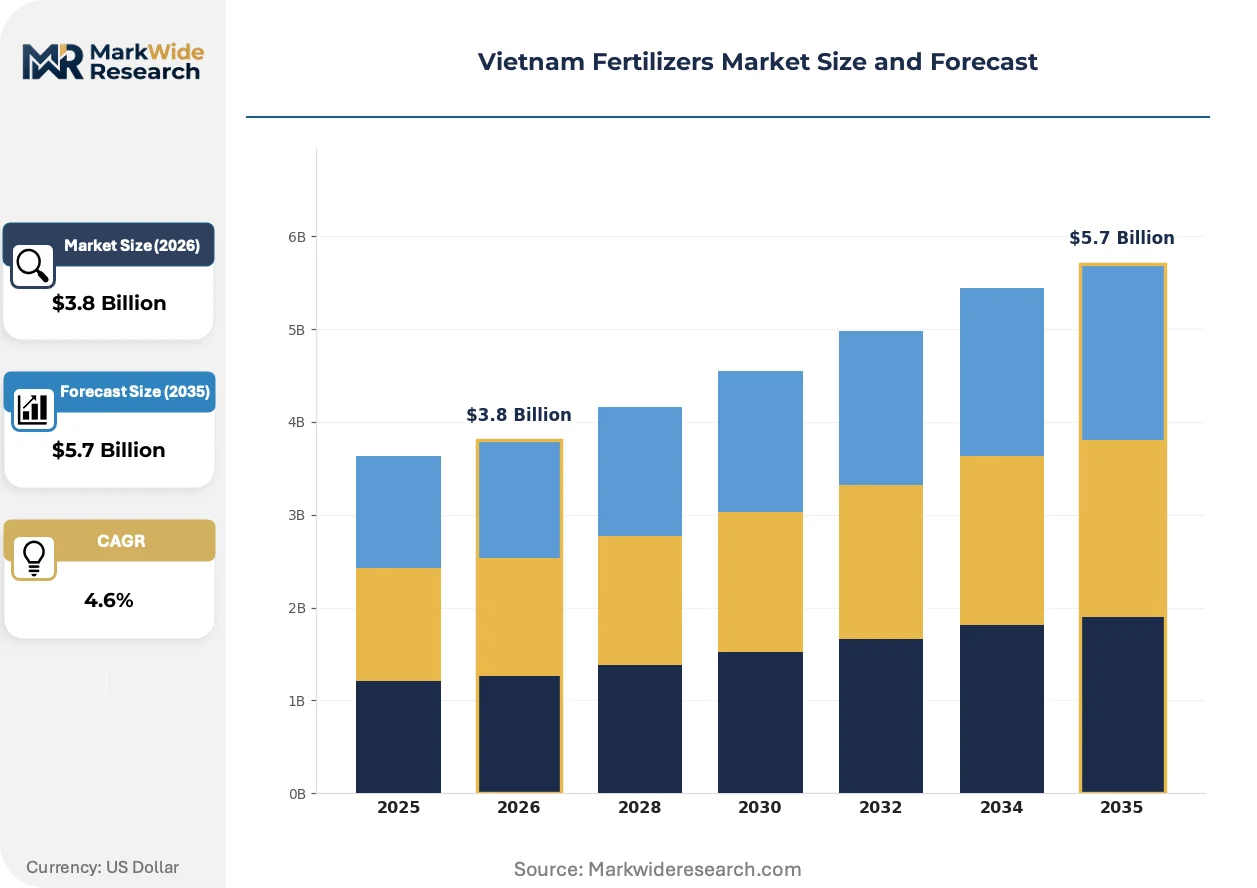
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, NPK, Potassium End Use Industry: Agriculture, Horticulture, Landscaping, Turf Management Delivery Mode: Bulk, Granular, Liquid, Powder Application: Soil Fertility, Crop Yield Enhancement, Nutrient Supply, Plant Health |
| Companies Covered | PetroVietnam Fertilizer and Chemicals Corporation JSC, Binh Dien Fertilizer JSC, Agricultural Products and Materials Joint Stock Company, Baconco Company Limited, Southern Fertilizer Joint Stock Company, Vietnam National Chemical Group, PetroVietnam Cau Mau Fertilizer Company, Grupa Azoty, ICL Group Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Fertilizers Market Evolving Landscape
Formulation chemistry and application technology are converging to reduce nutrient runoff and labor intensity, reshaping how Vietnamese farmers manage soil fertility across fragmented smallholdings.
Controlled-release nitrogen technology is migrating from conventional urea prills to polymer-coated and sulfur-coated formulations that synchronize nutrient availability with crop uptake curves. Mekong Delta rice cooperatives are piloting these products to reduce application frequency from three times per season to one. This migration from bulk-blended toward precision-delivery chemistry is compressing commodity urea volumes while expanding premium-grade market share.
Vietnam's Ministry of Agriculture and Rural Development tightened inspection protocols for imported fertilizer quality certification in 2023, mandating third-party laboratory verification of labeled N-P-K content before customs clearance. This regulatory friction has blocked numerous substandard shipments from unregistered Chinese suppliers. Distributors are responding by consolidating sourcing relationships with pre-approved multinational and ASEAN-registered manufacturers.
Farmer purchasing behavior is fragmenting across generational lines, with younger growers in the Red River Delta bypassing provincial dealers to source inputs through Zalo-integrated e-commerce platforms and cooperative bulk-buying groups. These digital channels offer price transparency and credit terms previously controlled by dealer networks. The shift is most pronounced in Bac Ninh and Hung Yen provinces, where vegetable farmers coordinate timed purchases to secure volume discounts.
Vietnam Fertilizers Market Segmentation
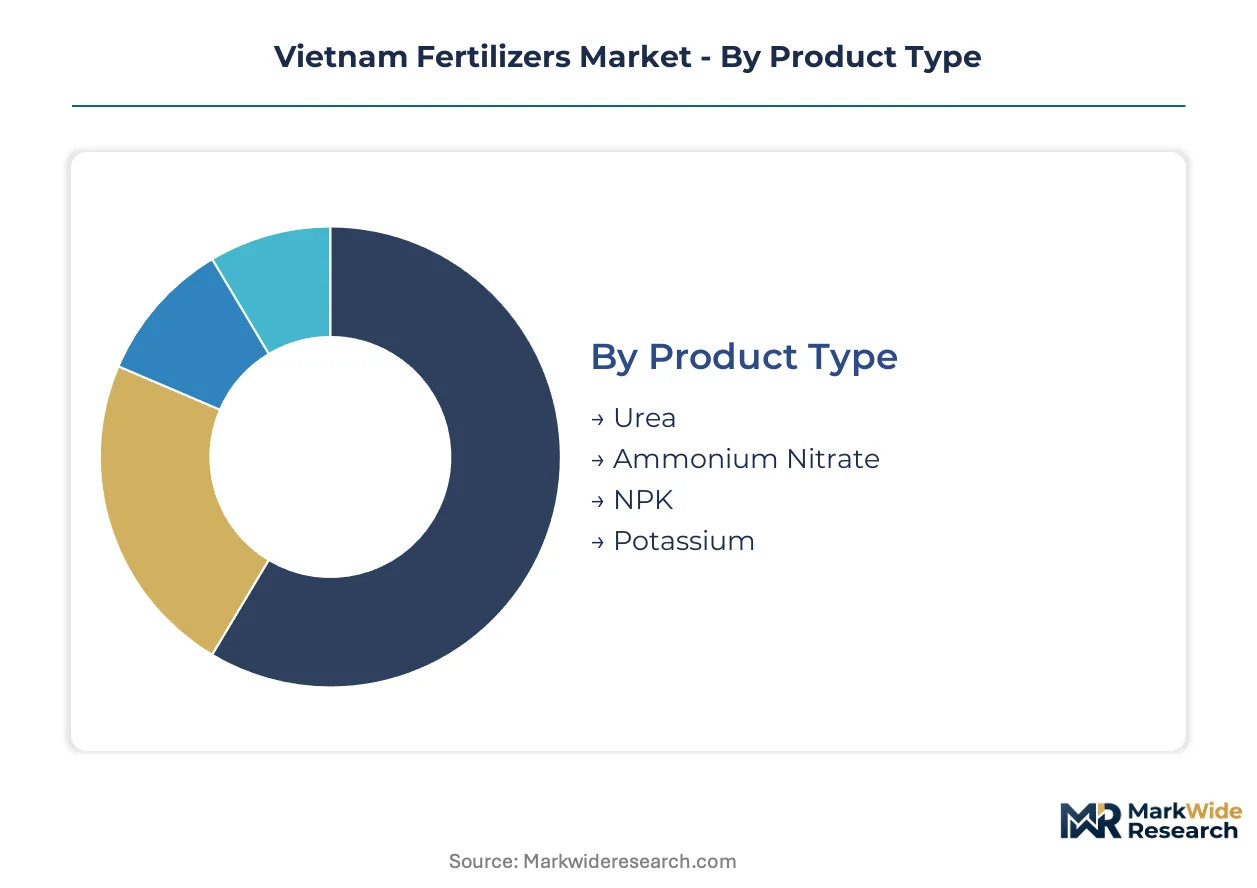
Segmentation in Vietnam's fertilizer market reflects divergent agronomic requirements across rice monoculture, export horticulture, and precision greenhouse operations. Each dimension—product chemistry, end-use intensity, physical form, and application objective—shapes procurement patterns and margin structures differently across the Mekong Delta, Red River Delta, and Central Highlands.
Product Type:
Use-case spectrum spans subsistence rice farming through high-value cash crop export operations, with chemistry selection driven by crop nutrient uptake curves and soil test results.
- Urea:Contains 46% nitrogen by weight in prilled or granular form, manufactured via ammonia synthesis from natural gas feedstock. Mekong Delta rice cooperatives absorb the largest volumes, though three-application-per-season protocols face pressure from controlled-release alternatives.
- NPK:Compound or blended formulations delivering specified nitrogen-phosphorus-potassium ratios through steam granulation or bulk blending. Adoption accelerates in intensive vegetable zones of Hung Yen and Bac Ninh where balanced nutrition mandates replace single-nutrient basals.
- Ammonium Nitrate:High-nitrogen source with rapid soil solubility, deployed primarily in industrial plantation settings with mechanized application infrastructure.
- Potassium:Muriate or sulfate forms addressing K-deficient ferralitic soils in coffee and pepper regions of Dak Lak and Gia Lai provinces.
Established volume favors urea; emerging adoption favors NPK blends.
End Use Industry:
Margin structure varies sharply across customer types, from price-sensitive smallholders to premium-seeking export-oriented greenhouse operators.
- Agriculture:Field crop production encompassing rice, maize, and cassava across delta and midland provinces. The Ministry of Agriculture's balanced nutrition protocols are redirecting traditional urea basals toward compound formulations in intensive zones.
- Horticulture:Protected cultivation of vegetables, flowers, and fruits for domestic and export markets. Da Lat and Lam Dong operations drive water-soluble and fertigation-grade demand with exacting nutrient uniformity requirements.
- Landscaping:Urban green space maintenance and roadside vegetation management in Ho Chi Minh City and Hanoi metropolitan corridors.
- Turf Management:Golf course and sports field maintenance concentrated in resort zones of Danang, Phu Quoc, and suburban Hanoi.
Volume concentration sits with agriculture; margin expansion concentrates in horticulture.
Delivery Mode:
Physical form selection tracks mechanization levels, irrigation infrastructure, and labor cost trajectories across farming systems.
- Granular:Free-flowing prills or pellets suited to broadcast spreaders and mechanical planters. Dominates rice cultivation in Mekong Delta provinces where farmer cooperatives coordinate bulk purchases.
- Liquid:Solution or suspension formulations for fertigation and foliar application. Greenhouse clusters in Lam Dong and protected vegetable zones of the Red River Delta absorb expanding volumes as drip irrigation penetration deepens.
- Bulk:Unpackaged loose material for large-scale plantation and cooperative procurement, minimizing packaging cost but requiring on-site storage infrastructure.
- Powder:Fine-ground materials for specific industrial compounding or specialty foliar applications with limited penetration in mainstream agriculture.
Granular formats anchor field crop economics; liquid formulations are climbing the fastest in protected cultivation.
Application:
Functional objective shapes product specification, with soil correction, yield maximization, and plant protection each demanding distinct nutrient timing and placement strategies.
- Soil Fertility:Long-term macronutrient replenishment and pH correction in degraded delta soils subject to intensive double-cropping regimes.
- Crop Yield Enhancement:Targeted interventions during critical growth stages—tillering in rice, flowering in coffee—requiring precise NPK timing.
- Nutrient Supply:Maintenance fertilization matching crop removal rates, the baseline function for most commercial fertilizer transactions.
- Plant Health:Secondary and micronutrient applications addressing specific deficiency symptoms in high-value export crops.
Yield enhancement commands premium pricing; soil fertility maintenance represents the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's fertilizer consumption patterns diverge sharply across its three dominant agricultural belts, with the Mekong Delta favoring volume-driven nitrogenous inputs while the Red River Delta and Central Highlands pursue precision-grade formulations for export-oriented cash crops.
Mekong Delta
Rice cooperatives in An Giang and Can Tho provinces absorb the largest urea volumes nationwide, driven by triple-cropping intensity on alluvial soils. The Ministry of Agriculture's balanced nutrition protocols are redirecting traditional basals toward NPK blends in intensive zones. PetroVietnam Cau Mau Fertilizer Company anchors supply through its integrated ammonia complex at the southern tip of the delta.
Red River Delta
Vegetable farming in Bac Ninh and Hung Yen provinces drives premium-grade compound fertilizer demand for year-round cultivation on peri-urban plots. Provincial agricultural departments enforce soil testing mandates that accelerate precision agriculture adoption. Digital purchasing platforms are fragmenting traditional dealer networks as younger farmers coordinate bulk-buying groups via Zalo-integrated channels.
Central Highlands
Coffee and pepper cultivation in Dak Lak and Gia Lai provinces remains underserved by precision input providers despite expanding plantation scale. Ferralitic soils exhibit chronic potassium deficiency that muriate of potash applications address. The region's distance from coastal manufacturing centers elevates logistics costs and extends distributor lead times.
Southeast Region
Ho Chi Minh City metropolitan demand concentrates in landscaping and turf management for golf resort maintenance in Dong Nai and Ba Ria-Vung Tau provinces. Containerized liquid formulations serve greenhouse clusters supplying year-round vegetable exports. Customs clearance at Cat Lai port shapes inventory planning for imported specialty grades.
North Central Coast
Thanh Hoa and Nghe An provinces bridge rice monoculture and emerging aquaculture feed operations with divergent nutrient requirements. Coastal salinity intrusion degrades soil quality and elevates sulfur-coated urea interest among salt-affected paddy operators. Provincial extension services lack laboratory capacity to support widespread precision fertilization recommendations.
Vietnam Fertilizers Market Competitive Landscape
Capability concentration sits with integrated petrochemical players; scale advantage sits with provincial distribution specialists. The Vietnamese fertilizer sector structures around three tiers: state-linked energy conglomerates with captive feedstock, regional blending and distribution houses with deep provincial dealer networks, and multinational traders supplying imported specialty grades. Consolidation pressure is accelerating as Chinese urea exports compress domestic manufacturer margins and force portfolio diversification toward controlled-release and water-soluble formulations.
Within the integrated domestic tier, PetroVietnam Fertilizer and Chemicals Corporation JSC and PetroVietnam Cau Mau Fertilizer Company exemplify feedstock-backed competitive positioning through their ammonia-to-urea complexes. Among regional distribution specialists, Binh Dien Fertilizer JSC occupies a position anchored in Mekong Delta dealer networks, while Baconco Company Limited represents the specialty formulation vector targeting high-value horticulture segments. Grupa Azoty and ICL Group Ltd serve as reference points for European import supply serving premium-grade demand in protected cultivation zones.
| Leading Market Players |
|---|
| PetroVietnam Fertilizer and Chemicals Corporation JSC |
| Binh Dien Fertilizer JSC |
| Agricultural Products and Materials Joint Stock Company |
| Baconco Company Limited |
| Southern Fertilizer Joint Stock Company |
| Vietnam National Chemical Group |
| PetroVietnam Cau Mau Fertilizer Company |
| Grupa Azoty |
| ICL Group Ltd |
| Others |
Value Network & Pricing Analysis
Chinese urea export surges determine both pricing tier spreads and supply chain configuration across Vietnamese fertilizer markets. PetroVietnam's integrated Ca Mau complex captures feedstock cost advantages that insulate domestic producers from import price volatility, while non-integrated manufacturers absorb margin compression through distributor markups or formulation differentiation.
Pricing Analysis
Coastal import gateways command 8-12% premiums over inland Mekong Delta delivery points due to logistics differentials. Three-tier pricing structure across premium, standard, and economy levels separates polymer-coated controlled-release grades from conventional urea prills and bulk-blended NPK compounds. Cost compression in commodity nitrogen is intensifying because Chinese capacity expansion floods regional spot markets. Smallholder rice cooperatives exhibit highest price sensitivity, whereas greenhouse horticulture operators in Lam Dong prioritize nutrient uniformity over unit cost.
Supply Chain Analysis
Vietnam's Ministry of Agriculture registration requirements function as de facto export controls on unregistered Chinese suppliers, blocking substandard shipments at Cat Lai and Hai Phong ports. Domestic manufacturing draws from offshore gas fields at Ca Mau, while potash imports rest on Canadian and Belarusian mining concentration. Single-source vulnerability concentrates in Middle Eastern ammonia supply chains exposed to Red Sea shipping disruption. Distribution runs through provincial dealer networks in the Mekong Delta and cooperative bulk-buying platforms in the Red River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures around regulatory entrenchment: Ministry of Agriculture quality certification creates switching costs that lock distributors into pre-approved supplier relationships. Incumbents who secured registration early command persistent sourcing advantages.
For Market Incumbents: Insulate margin structures through captive ammonia feedstock integration at southern gas fields rather than merchant market exposure. Accelerate controlled-release and water-soluble formulation portfolios to escape commodity urea price cycles. Defend dealer network loyalty in An Giang and Can Tho provinces against digital platform disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in Central Highlands coffee and pepper precision agriculture, where ferralitic soil potassium deficiency remains underserved by existing distributors. Target Da Lat greenhouse clusters with fertigation-grade liquid formulations bypassing granular commodity competition. Partner with provincial agricultural cooperatives for soil testing service bundling that creates differentiated entry paths.
For Investors and Strategic Acquirers: Draft biofertilizer circulars from the Ministry of Agriculture reshape the acquisition landscape toward microbial inoculant capability. Five-to-ten-year viability favors integrated petrochemical players with gas field concessions over pure-play blenders. Watch for registration queue acceleration signals that would unlock formulation innovation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Captive gas field access at Ca Mau insulates PetroVietnam from international urea price volatility. |
| Controlled-Release Formulation Expansion | Polymer-coated urea products capture premium pricing from Mekong Delta rice cooperatives reducing application frequency. |
| Digital Platform Distribution Buildout | Zalo-integrated cooperative purchasing in Bac Ninh and Hung Yen bypasses traditional dealer markups. |
| Biofertilizer Registration Fast-Track Positioning | Microbial inoculant pre-approval aligns with Ministry of Agriculture draft circulars on azotobacter products. |
| Central Highlands Logistics Infrastructure | Dak Lak and Gia Lai distribution hubs address potassium deficiency in coffee plantations with shortened lead times. |
Research Methodology
Operator-level perspectives from fertilizer plant managers, provincial dealer network heads, agricultural cooperative procurement officers, and Ministry of Agriculture registration officials anchored the qualitative base. Secondary validation drew from customs import records, General Department of Taxation filings, PetroVietnam production disclosures, and provincial agricultural extension reports. Bottom-up volume estimates from crop-specific application rates triangulated against top-down trade flow analysis.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases without year-specific anchoring. Segmentation modeling spanned product chemistry tiers, end-use crop categories, physical delivery modes, and regional consumption clusters. CAGRs derived from historical trade elasticity analysis and projected crop area intensities. Forecast inputs incorporated natural gas price trajectory assumptions and Ministry of Agriculture balanced nutrition mandate implementation pacing.
Sensitivities concentrate around Chinese urea export tax policy shifts and Mekong Delta triple-cropping intensity adjustments. Forecasts reflect documented assumptions on registration queue durations and cooperative digital adoption curves. Material shifts in Ministry of Agriculture biofertilizer regulatory timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
India Urea Market
Fertilizers
Europe Fertilizers Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market