
 United States Specialty Fertilizer Market | 2026-2036
United States Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Specialty Fertilizer Market Analytics
The Corn Belt is fragmenting as domestic production capacity for enhanced-efficiency fertilizers expands across multiple state clusters. CF Industries Holdings leverages its nitrogen manufacturing infrastructure to sustain cost advantages in urea-based specialties. The Mosaic Company anchors phosphate-derived product lines through integrated mining and processing operations. Nutrien Ltd. competes via direct-to-farm distribution networks that bypass traditional wholesale channels.
United States specialty fertilizers are formulated products containing one or more plant nutrients in concentrations adjusted for specific crop requirements, often incorporating polymer coatings or nitrification inhibitors to control nutrient release rates. These formulations serve commercial agriculture by reducing leaching losses and enabling split-application strategies that align with plant phenological stages. Controlled-release formulations command premium positioning due to their labor-saving attributes and environmental compliance benefits, while liquid specialties gain traction in fertigation systems across high-value fruit and vegetable operations. Granular products retain volume dominance in row-crop applications where broadcast equipment predominates.
The EPA regulates nutrient discharge under the Clean Water Act, compelling manufacturers toward formulations with reduced runoff potential. USDA conservation programs incentivize enhanced-efficiency product use through cost-share arrangements. State-level fertilizer application restrictions in the Chesapeake Bay watershed and Florida's sensitive watersheds further constrain conventional product viability. Stakeholders must track evolving 4R Nutrient Stewardship adoption metrics and state-level phosphorus indexing requirements to anticipate demand shifts toward certified low-loss formulations.
Market Dynamics
Precision agriculture operators are consolidating acreage under management, concentrating demand for enhanced-efficiency formulations that align variable-rate application with real-time soil sensor data. This structural concentration favors suppliers capable of technical service integration at the farm-gate level.
Growth Catalysts
- USDA Conservation Stewardship Program:Cost-share arrangements for enhanced-efficiency products accelerate farmer conversion from conventional blends, particularly in the Chesapeake Bay watershed where phosphorus indexing requirements tighten.
- Fertigation infrastructure expansion:High-value fruit and vegetable operations in California's Central Valley retrofit irrigation systems for liquid specialty delivery, creating pull-through for soluble and suspension formulations.
- 4R Nutrient Stewardship adoption:Voluntary frameworks endorsed by agricultural retailers drive certified low-loss product specifications into procurement contracts across the Corn Belt.
Market Restraints
- Natural gas price volatility:Urea-based specialty production faces margin compression when Henry Hub benchmarks spike, construring domestic nitrogen manufacturing economics.
- Phosphate rock import dependence:Concentrated Moroccan and Saudi supply for P2O5 feedstock exposes domestic blenders to shipping cost surges and geopolitical supply interruptions.
- Polymer coating cost premiums:Controlled-release formulations require specialized resin inputs whose prices track petrochemical indices, limiting price competitiveness against uncoated alternatives.
Strategic Opportunities
- Florida sensitive watershed mandates:State-level application restrictions on conventional phosphorus products create guaranteed demand displacement toward enhanced-efficiency alternatives in citrus and sugarcane districts.
- Biological-starter fertilizer convergence:Microbial inoculant integration with liquid specialty blends opens new efficacy claims for suppliers targeting organic transition acreage.
- Direct-to-farm channel development:Bypassing wholesale cooperatives via proprietary agronomy platforms captures margin and locks in multi-season supply agreements with large-scale operators.
Industry Challenges
- Certified crop adviser shortage:Technical sales roles requiring soil science credentials and precision agriculture fluency face recruitment bottlenecks, constraining farmer-facing advisory capacity.
- Legacy equipment incompatibility:Controlled-release granular products with irregular particle sizing jam pneumatic applicators calibrated for conventional prills, forcing capital expenditure on retrofit or replacement.
- State-by-state registration fragmentation:Product approval timelines vary across departments of agriculture, delaying commercial launches and complicating national formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Specialty Fertilizer Market |
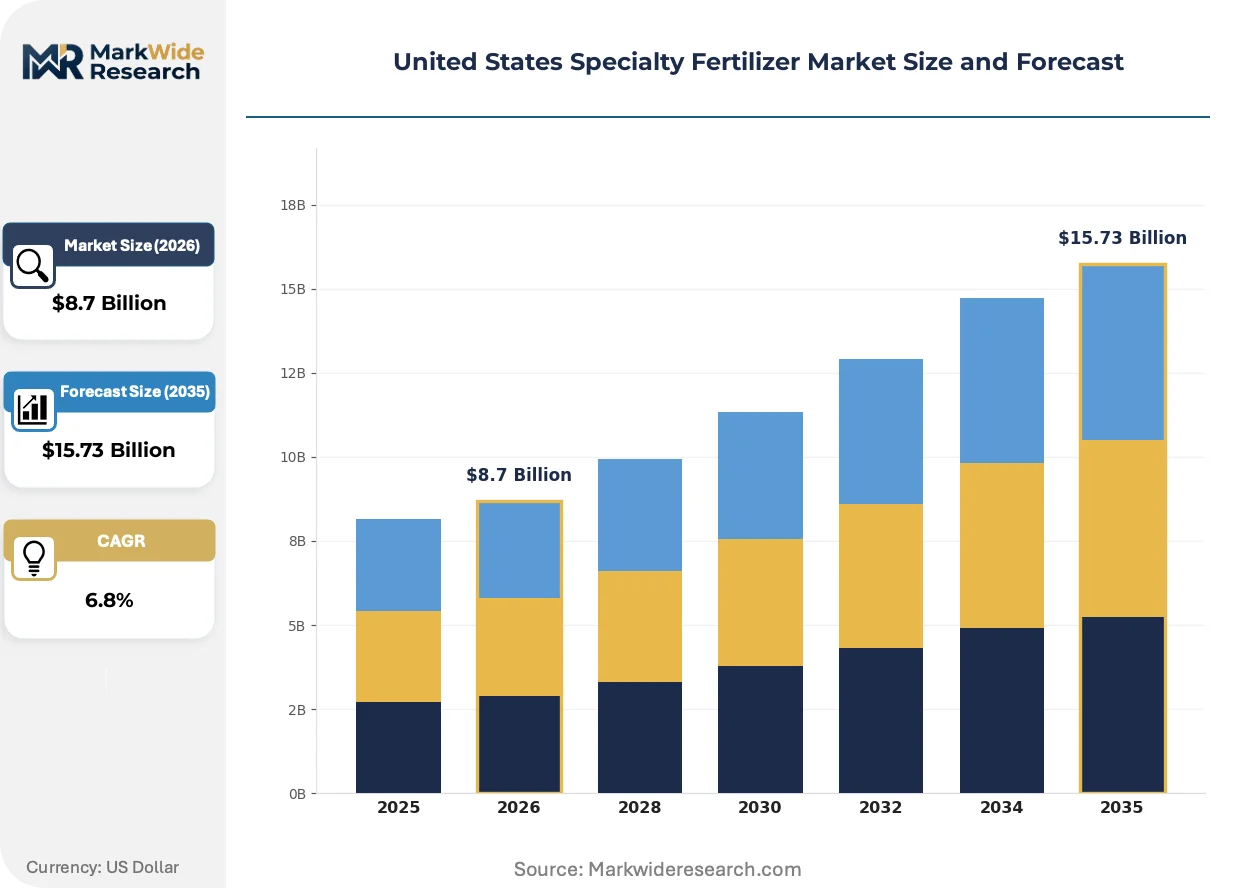
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Controlled-Release, Soluble End Use: Agriculture, Horticulture, Turf & Ornamentals, Landscaping Distribution Channel: Wholesale, Retail, Direct Sales, Online Ingredient Source: Organic, Inorganic, Bio-based, Synthetic |
| Companies Covered | CF Industries Holdings, Inc., The Mosaic Company, The Andersons Inc., Wilbur-Ellis Company LLC, Yara International ASA, ICL Group Ltd, Nutrien Ltd., K+S Aktiengesellschaft, Koch Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Specialty Fertilizer Market Evolving Landscape
Digital soil mapping and variable-rate application hardware are compressing the feedback loop between nutrient application and crop response, forcing formulation suppliers to embed sensor compatibility into product development roadmaps.
Polymer-coated controlled-release fertilizers are virtualizing the traditional split-application calendar by synchronizing nitrogen availability with maize phenological stages through temperature-responsive membrane degradation. Large-scale corn operators in Iowa and Illinois adopt these formulations to reduce sidedress labor requirements. The technology is virtualizing seasonal demand patterns that previously concentrated purchasing and application services into narrow weather windows.
EPA's evolving nutrient discharge guidelines under the Clean Water Act are compelling manufacturers toward formulations with documented reduced runoff potential. Industrial consequence includes accelerated R&D spending on nitrification inhibitor combinations and slow-release urea variants. Specialty crop regions facing total maximum daily load restrictions, particularly in the Chesapeake Bay watershed and Florida's Everglades Agricultural Area, respond by specifying certified low-loss products in procurement contracts.
Consolidation among agricultural retailers is compressing the distribution tier, with cooperative buying groups and multi-state operators demanding volume-based pricing and exclusive formulation access. Independent dealers lose share to integrated agronomy platforms that bundle seed, crop protection, and fertility into single-season packages. This channel restructuring concentrates most visibly in the Midwest, where three retail cooperatives now control substantial fertilizer throughput across Nebraska, Iowa, and Indiana.
United States Specialty Fertilizer Market Segmentation
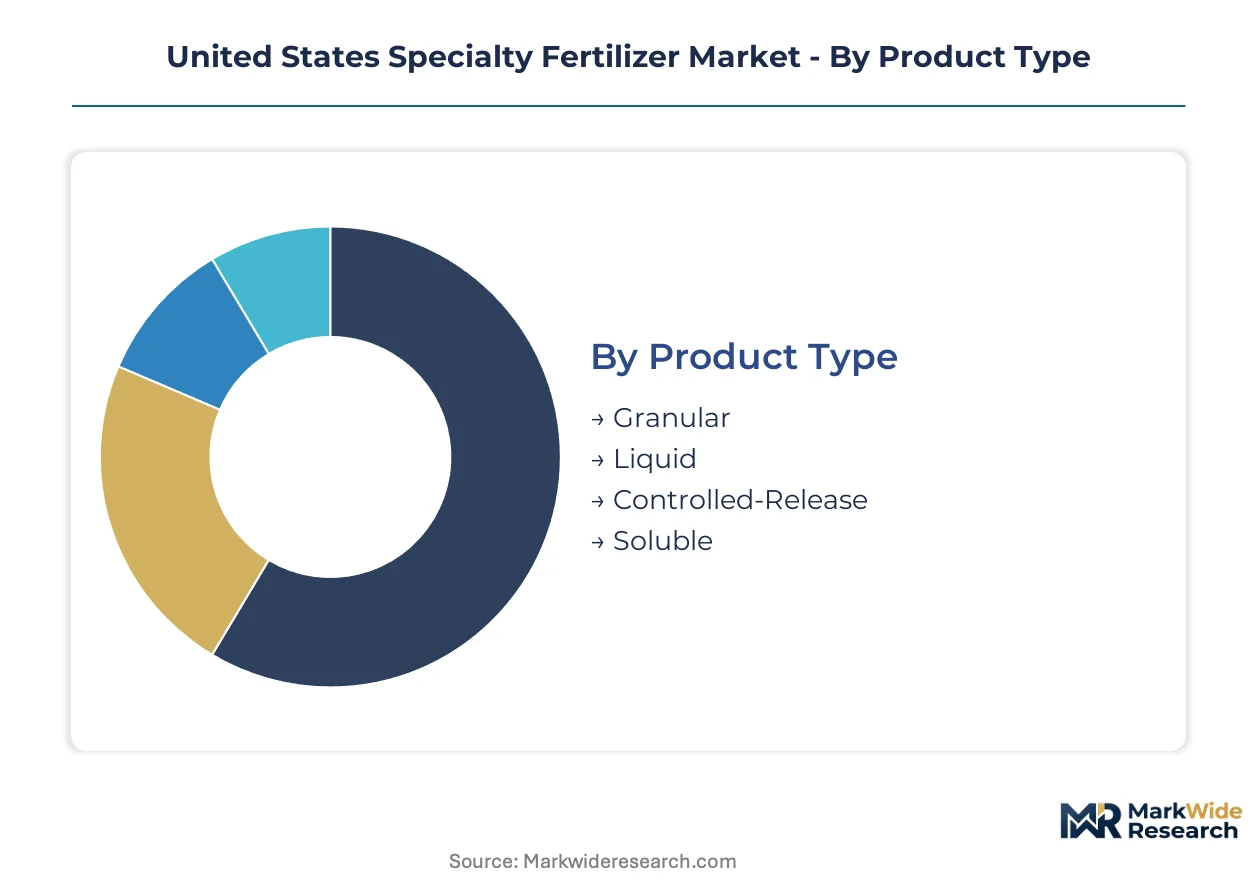
Segmentation reveals how formulation physics, application equipment, and regulatory pressure intersect to create distinct competitive arenas. Each dimension carries different margin profiles and capital requirements, reshaping supplier priorities across the Corn Belt and California's Central Valley.
Product Type:
Cycle times vary sharply: liquid formulations turn inventory weekly during growing season, while controlled-release products sit in distributor warehouses across multiple quarters awaiting pre-plant procurement windows.
- Granular:Conventional prilled or compacted products designed for broadcast spreader compatibility. Iowa and Illinois corn operators specify these for pre-plant nitrogen application where equipment fleets remain calibrated for uniform particle sizing. Volume concentration here reflects legacy capital investment in pneumatic applicators across the Midwest.
- Liquid:Suspension or solution formulations pumped directly through fertigation infrastructure. California Central Valley almond and pistachio growers retrofit irrigation systems for these products, pulling demand toward soluble concentrates that bypass mechanical application entirely. Labor savings and precision placement drive conversion from dry alternatives.
- Controlled-Release:Polymer-coated or sulfur-coated granules synchronizing nutrient availability with crop phenology. Temperature-responsive membrane degradation extends the effective application window for maize producers seeking to eliminate sidedress passes.
- Soluble:Highly refined crystalline products dissolving completely for drip or micro-sprinkler delivery. Greenhouse tomato operations in Florida and Arizona specify these for hydroponic systems where precipitate formation risks emitter clogging.
Granular dominates installed base. Controlled-release is where expansion concentrates.
End Use:
Margin tiers separate commodity row-crop applications from high-value specialty systems where formulation premiums absorb input cost volatility.
- Agriculture:Broadacre field crop production encompassing corn, soybean, wheat, and cotton systems. Nebraska and Kansas operators purchase enhanced-efficiency nitrogen for variable-rate application aligned with yield monitor data, with USDA cost-share programs accelerating conversion from conventional blends.
- Horticulture:Protected cultivation of vegetables, fruits, and nursery stock under greenhouse or high-tunnel structures. California strawberry producers demand liquid specialties compatible with drip tape injection, where leaching restrictions under state agricultural water quality programs constrain conventional product selection.
- Turf & Ornamentals:Golf course, sports field, and commercial landscape maintenance. Florida golf superintendents face municipal fertilizer blackout ordinances that specify controlled-release formulations with documented reduced runoff potential during summer nitrogen application bans.
- Landscaping:Residential and commercial ornamental planting, erosion control, and revegetation projects. Texas Hill Country developers specify slow-release products for post-construction stabilization where irrigation infrastructure remains absent during establishment periods.
Agriculture captures volume concentration. Horticulture is climbing the fastest.
Distribution Channel:
Channel economics fragment between high-touch agronomy services and transactional volume plays, with digital platforms inserting new intermediaries.
- Wholesale:Bulk transfer to agricultural cooperatives and independent dealers maintaining regional storage and blending capacity. CHS and Growmark networks across the Upper Midwest consolidate procurement for member-owners, extracting volume discounts from manufacturers.
- Retail:Farm supply stores and garden centers serving smallholder and hobbyist segments. Tractor Supply Company locations in rural exurbs stock bagged soluble products for vegetable gardeners, with seasonal demand peaking during spring planting windows.
- Direct Sales:Manufacturer-to-farm contracts bypassing wholesale markups. Nutrien's proprietary agronomists lock multi-season agreements with Iowa and Illinois operators exceeding 5,000 acres, bundling fertility with seed and crop protection procurement.
- Online:E-commerce platforms aggregating specialty products for direct shipment. Amazon Business and specialized agricultural marketplaces gain traction among hobby farmers and remote operations outside dealer service territories, though bulk liquid delivery remains impractical through parcel networks.
Wholesale retains throughput dominance. Direct sales is gaining share fastest.
Ingredient Source:
Certification requirements and carbon accounting frameworks are restructuring procurement specifications across organic transition acreage and conventional operations alike.
- Organic:Naturally derived materials meeting USDA National Organic Program standards for certified production. California organic vegetable growers source fish emulsion and composted poultry litter derivatives, with input approval timelines constraining rapid scale-up.
- Inorganic:Mined or synthetically processed mineral nutrients without organic certification. Phosphate rock from Florida and Idaho deposits feeds domestic acidulation plants, though Moroccan import dependence persists for high-purity feedstock.
- Bio-based:Agricultural waste streams and microbial fermentation products substituting for conventional synthesis. Corn stover and manure digestate processing in Iowa and Minnesota yields slow-release nitrogen formulations eligible for renewable fuel credit stacking.
- Synthetic:Industally manufactured urea, ammonium nitrate, and processed phosphates via Haber-Bosch and wet acid routes. CF Industries' Louisiana and Iowa nitrogen complexes supply this category, with Henry Hub price exposure compressing margins during natural gas spikes.
Synthetic commands volume leadership. Bio-based is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic nitrogen manufacturing clusters in Louisiana and Iowa supply feedstock for urea-based specialties, while phosphate processing concentrates in Florida and Idaho. This supply-side geography shapes regional formulation capabilities and distribution economics across the contiguous United States.
California
Almond and pistachio growers in the Central Valley drive liquid specialty demand through fertigation retrofit programs. State agricultural water quality regulations constrain conventional nitrogen application in sensitive groundwater basins. Fresno and Kern counties host blending facilities supplying soluble concentrates for drip tape injection systems.
Midwest Corn Belt
Iowa and Illinois corn operators purchase controlled-release formulations to eliminate sidedress labor passes during narrow weather windows. USDA Conservation Stewardship Program cost-shares accelerate conversion from conventional blends in the Chesapeake Bay watershed extension. Manufacturing infrastructure clusters near CF Industries' nitrogen complexes in Iowa and Illinois.
Florida
Citrus and sugarcane districts face state-level phosphorus application restrictions in the Everglades Agricultural Area and surrounding sensitive watersheds. Municipal fertilizer blackout ordinances specify controlled-release formulations with documented reduced runoff potential. Lake Okeechobee basin operations drive certified low-loss product procurement.
Texas
Cotton producers in the High Plains adopt enhanced-efficiency nitrogen for variable-rate application aligned with yield monitor data. State water conservation initiatives incentivize precision irrigation integration with liquid specialty delivery. Lubbock and Plainview serve as distribution hubs for Panhandle row-crop operations.
Pacific Northwest
Washington potato and apple growers specify soluble specialties compatible with center-pivot and drip systems. State nutrient management regulations in the Yakima River basin constrain conventional product selection. Processing vegetable operations in the Columbia Basin pull demand for fertigation-compatible formulations.
United States Specialty Fertilizer Market Competitive Landscape
Integrated nitrogen manufacturers and diversified agricultural input suppliers split the market between feedstock control and distribution proximity. Three archetypes dominate: domestic nitrogen producers with captive ammonia supply, phosphate miners with integrated acidulation capacity, and retail-integrated platforms bundling fertility with seed and crop protection. Capacity expansion in polymer coating technology and direct-to-farm channel development represent the dominant competitive moves reshaping positioning.
Within the integrated manufacturing tier, CF Industries Holdings and The Mosaic Company exemplify feedstock-anchored strategies, while Nutrien Ltd. occupies a position spanning both production and direct distribution. These three entities represent the structural poles around which mid-scale blenders and regional cooperatives organize their supply relationships.
| Leading Market Players |
|---|
| CF Industries Holdings, Inc. |
| The Mosaic Company |
| The Andersons Inc. |
| Wilbur-Ellis Company LLC |
| Yara International ASA |
| ICL Group Ltd |
| Nutrien Ltd. |
| K+S Aktiengesellschaft |
| Koch Industries Inc. |
| Others |
Value Network & Pricing Analysis
Mississippi River barge freight corridors shape cost dynamics across the Corn Belt, concentrating supply leverage with nitrogen manufacturers near Louisiana production hubs while forcing inland blenders to absorb differential logistics costs that propagate downstream as regional price tiers.
Pricing Analysis
EPA Clean Water Act discharge guidelines dictate the pricing tier structure across the United States specialty fertilizer market, separating certified low-loss formulations at premium positioning from conventional uncoated products competing on commodity economics. Three-tier pricing stratifies across enhanced-efficiency premium, standard polymer-coated, and economy uncoated levels, with USDA Conservation Stewardship Program eligibility driving tier selection. Cost compression in synthetic nitrogen runs through Henry Hub volatility exposure, tightening margins for urea-based specialty producers. Large-scale precision agriculture operators exhibit lowest price sensitivity due to labor savings and yield optimization calculus, while smallholder retail purchasers through farm supply channels face acute budget constraints.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor working capital structures for agricultural cooperatives purchasing bulk nitrogen feedstock, compressing cash conversion cycles for domestic blenders. Manufacturing concentration clusters in Louisiana and Iowa for ammonia-based inputs, Florida and Idaho for phosphate processing, with Moroccan and Saudi Arabian import dependence for high-purity P2O5 feedstock. Raw material dependencies center on natural gas for Haber-Bosch synthesis, phosphate rock for acidulation, and petrochemical-derived polymers for controlled-release coatings. Tariff exposure on Moroccan phosphate concentrates constitutes the dominant structural risk, threatening margin stability for domestic blenders. Distribution runs through wholesale cooperative networks consolidating regional procurement, with direct-to-farm contracts gaining share among operators exceeding 5,000 acres.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States specialty fertilizer market rewards technical agronomy capabilities that remain scarce across the certified crop adviser pipeline, constraining farmer-facing advisory capacity and creating differentiation premiums for suppliers investing in soil science credentialing infrastructure.
For Market Incumbents: Pre-empt biological-starter fertilizer convergence by acquiring microbial inoculant technology platforms before organic transition acreage locks into competing supply agreements. Defend margin position through captive polymer coating capacity additions in Iowa and Illinois, neutralizing resin cost volatility that compresses controlled-release formulation economics. Channel control via proprietary agronomy platforms bundling seed, crop protection, and fertility procurement represents the critical defensive lever against retail cooperative consolidation.
For New Entrants and Emerging Players: Florida's sensitive watershed mandates present the most penetrable regulatory-driven demand displacement, with citrus and sugarcane districts requiring certified low-loss phosphorus alternatives under Everglades Agricultural Area restrictions. Target biological-starter convergence for organic transition acreage in California's Central Valley, where input approval timelines constrain incumbent rapid response. Direct-to-farm digital platforms bypassing wholesale markups offer the clearest go-to-market angle for technical entrants lacking cooperative distribution relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural input conglomerates seeking to divest non-core fertilizer blending assets amid channel restructuring pressures. Long-term viability hinges on backward integration into nitrogen manufacturing or phosphate mining, insulating margin compression from feedstock volatility. Vertically integrated mid-scale blenders with proprietary polymer coating technology and direct-to-farm channel presence represent priority acquisition archetypes. Monitor 4R Nutrient Stewardship adoption metrics across the Chesapeake Bay watershed as the signal indicating accelerated demand shift toward certified low-loss formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrogen Manufacturing | Captive ammonia supply from Louisiana production complexes insulates margin compression from Henry Hub volatility exposure. |
| Polymer Coating Capacity Expansion | In-house resin application technology reduces petrochemical index tracking and accelerates controlled-release product development cycles. |
| Direct-to-Farm Channel Development | Proprietary agronomist networks bypass wholesale cooperative markups and lock multi-season supply agreements with large-scale operators. |
| Biological-Starter Fertilizer Convergence | Microbial inoculant integration with liquid specialties opens efficacy claims for organic transition acreage in California and Florida. |
| Certified Low-Loss Formulation Investment | EPA discharge guideline alignment positions products for procurement contracts in Chesapeake Bay and Everglades watershed restrictions. |
Research Methodology
The analysis maps controlled-release, liquid, granular, and soluble formulation sub-sectors, each validated through agronomists at precision agriculture operations, procurement leads at agricultural cooperatives, plant managers at nitrogen manufacturing complexes, and regulatory affairs specialists tracking EPA discharge guideline evolution. Primary interview intelligence triangulates against secondary sources including USDA Conservation Stewardship Program enrollment data, EPA Clean Water Act enforcement records, state-level phosphorus indexing requirements, and SEC 10-K filings from integrated nitrogen manufacturers. Bottom-up demand modeling across crop-specific application rates reconciles with top-down feedstock capacity assessments from Louisiana and Iowa production clusters.
Analytical assumptions hold natural gas pricing within historical volatility bands and regulatory enforcement intensity at observed levels across the projection horizon. Segmentation dimensions modeled include formulation physics, end-use crop system, distribution channel structure, and ingredient source certification status. CAGRs derive from compound growth trajectory analysis across volume and value outputs, with industry-specific inputs incorporating variable-rate adoption rates, fertigation infrastructure deployment, and 4R Nutrient Stewardship penetration metrics.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by retail cooperatives or disruptive biological-input specialists would shift competitive dynamics and demand trajectories. Macroeconomic deviation in agricultural commodity prices, regulatory acceleration of watershed discharge restrictions, or breakthrough controlled-release membrane technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
China Organic Fertilizers Market