
 Mineral Fertilizers Market | 2026-2036
Mineral Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Fertilizers Market Outlook
Skilled agronomist labor is collapsing across Black Sea extraction corridors, tightening operational uptime at potash and phosphate complexes. Yara International leverages integrated ammonia networks to sustain European nitrogen supply security. Nutrien Ltd anchors North American distribution through controlled retail channels. PhosAgro dominates apatite concentrate output from Murmansk, competing on ore grade rather than freight arbitrage.
Mineral fertilizers are inorganic nutrient formulations manufactured through Haber-Bosch ammonia synthesis, phosphate rock acidulation, or potash evaporation and beneficiation, typically specified by N-P-K macronutrient ratios and water solubility percentages for soil or foliar delivery. Their primary purpose is to replenish soil nutrient stocks at scale for commercial crop production systems. Urea commands the largest volume share among nitrogen products due to its high nitrogen density and liquid adaptability. Potassium chloride from Saskatchewan and Belarusian mines supplies the bulk of global K2O demand for fruit and vegetable quality traits. Granular fertilizer grades capture premium positioning in mechanized broadcasting systems across Brazilian soybean operations.
EPA water quality standards in the United States restrict phosphorus runoff from Corn Belt applications, reshaping formulation and buffer zone requirements. REACH and the EU Green Deal in Europe are pressing for carbon footprint disclosure across ammonia supply chains, conditioning market access for import-dependent blenders. India's CEA-linked fertilizer subsidy mechanism distorts urea pricing relative to potash and phosphate, skewing soil nutrient balance. Stakeholders must monitor how EU carbon border adjustments and evolving Green Deal fertilizer benchmarks alter competitive access for Russian and Middle Eastern producers.
Market Dynamics
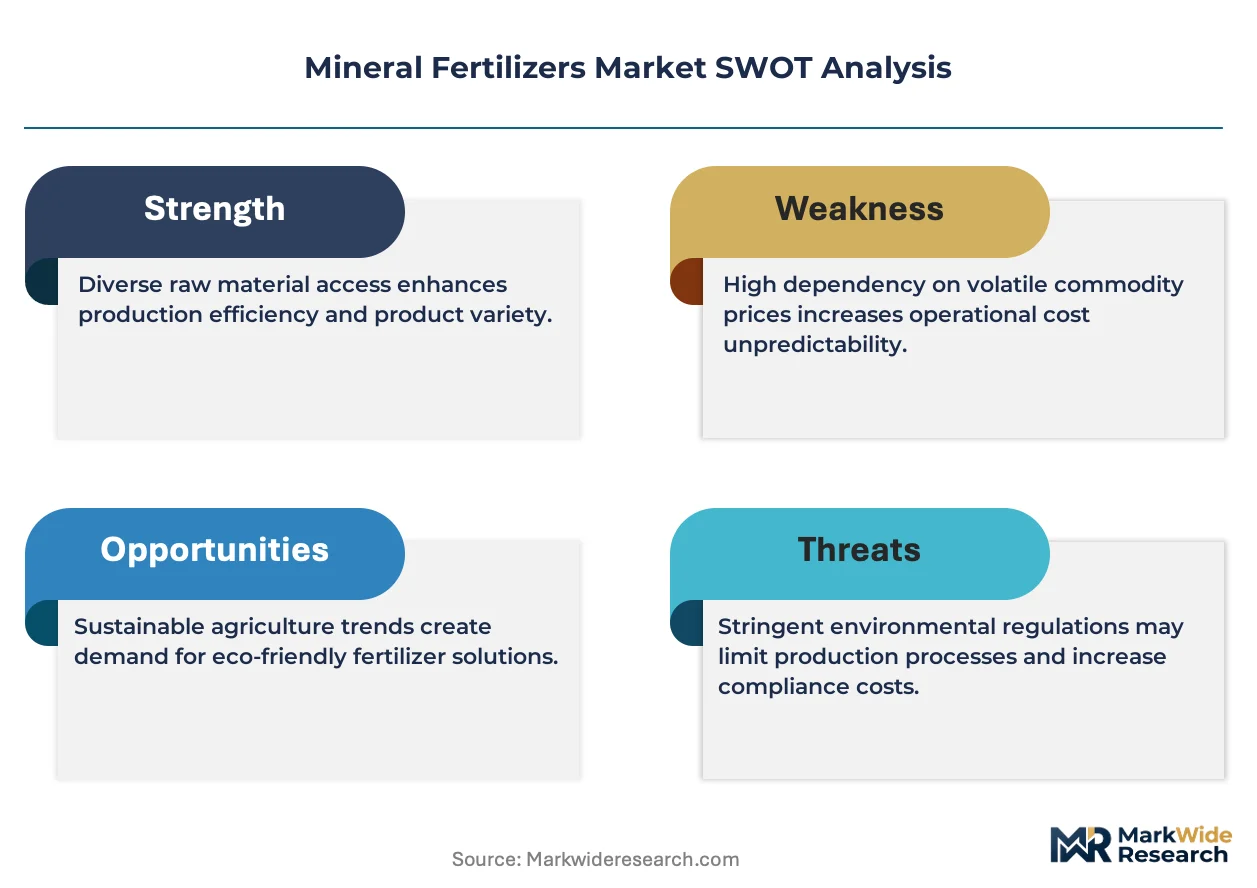
Carbon border adjustments and ammonia supply chain disclosure mandates are restructuring competitive access for import-dependent blenders, forcing capital reallocation toward low-carbon production assets.
Growth Catalysts
- India's CEA-linked subsidy mechanism:Subsidized urea distribution in wheat-belt states sustains volume demand while precision agriculture pilots expand micronutrient adoption.
- Brazilian specialty soybean protein premiums:Micronutrient blend expansion by specialty crop growers raises protein content thresholds, pulling customized N-P-K formulations.
- Controlled-release coating technologies:Polymer-coated urea reduces nitrogen volatilization losses, improving nutrient use efficiency in mechanized broadcasting systems.
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis depends on natural gas pricing, exposing nitrogen producers to input cost swings at European and Middle Eastern complexes.
- Belarusian potash supply concentration:Sanctions-disrupted rail corridors through Lithuania constrain K2O availability for Southeast Asian vegetable producers.
- EPA phosphorus runoff restrictions:Water quality standards in US Corn Belt states mandate buffer zones and formulation changes, raising compliance costs for phosphate blenders.
Strategic Opportunities
- Sub-Saharan Africa soil nutrient deficit:Underpenetrated smallholder markets in Nigeria and Kenya present volume expansion potential for packaged fertilizer blends.
- EU Green Deal carbon footprint labeling:Mandatory disclosure across ammonia supply chains creates first-mover advantage for low-carbon certification holders.
- Foliar application drone systems:UAV-based micronutrient delivery converges with precision agriculture, opening channel innovation for specialty nutrient suppliers.
Industry Challenges
- Agronomist labor scarcity:Skilled technical talent collapse across Black Sea extraction corridors tightens operational uptime at potash and phosphate beneficiation facilities.
- REACH registration timelines:Extended substance evaluation periods for novel fertilizer additives delay product commercialization and revenue recognition.
- Legacy blending equipment retrofit costs:Controlled-release formulation shifts require capital-intensive coating line upgrades at regional distribution terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Fertilizers Market |
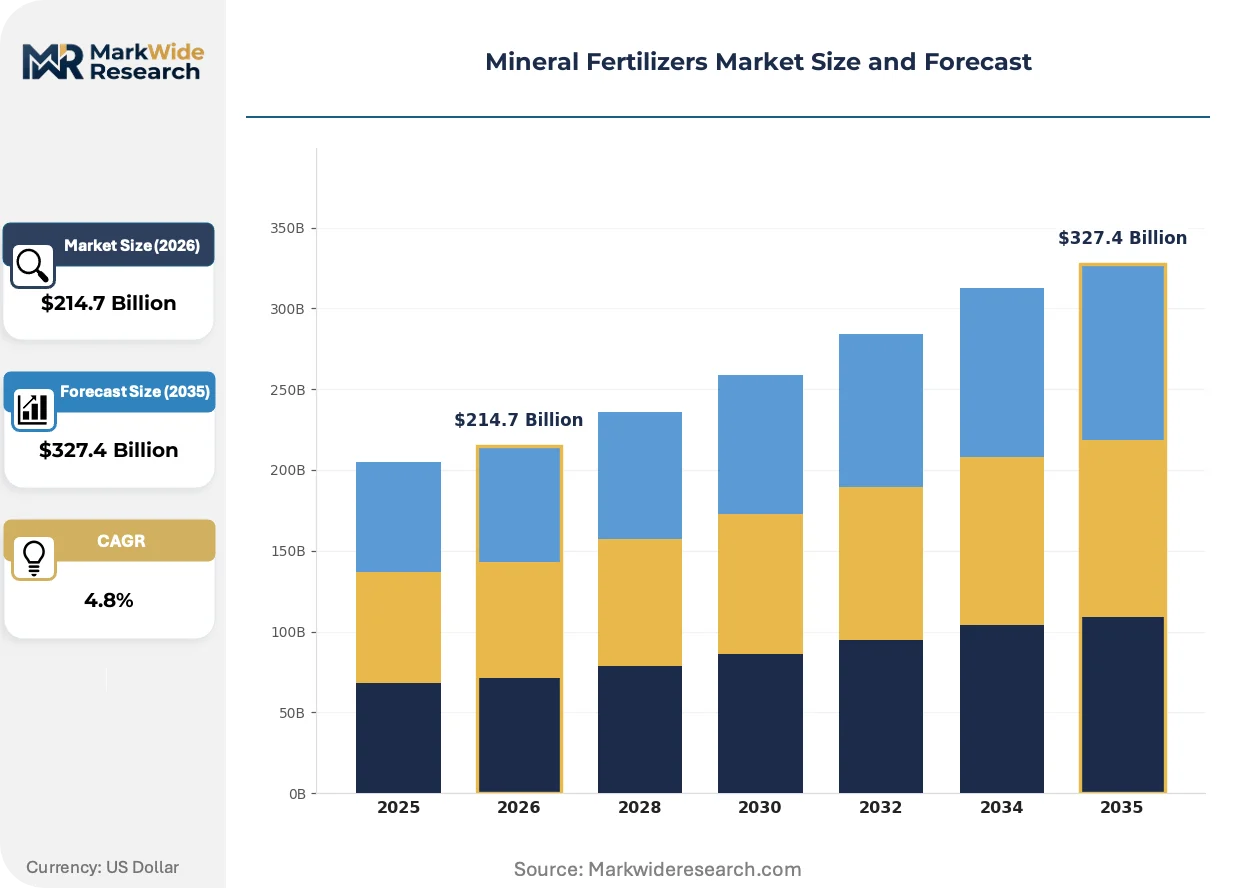
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $327.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Potassium Chloride, MAP Grade: High Analysis, Standard Grade, Liquid Fertilizers, Granular Fertilizers Application: Cereals, Fruits, Vegetables, Cash Crops End User: Agriculture, Horticulture, Commercial Growers, Home Gardens |
| Companies Covered | The Mosaic Company, Uralkali, Yara International, PhosAgro, ICL Group, Nutrien Ltd, EuroChem Group, K+S, CF Industries Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Fertilizers Market Strategic Shifts
Digital nutrient mapping and variable-rate application systems are compressing the gap between blanket fertilization and site-specific crop management, redrawing equipment and formulation requirements simultaneously.
Polymer-sulfur coated urea is bifurcating the nitrogen product hierarchy. The technology releases nitrogen in sync with crop uptake curves, reducing leaching losses. Large-scale corn operations in Iowa and Illinois are adopting it at accelerating rates despite 15-20% price premiums over conventional prilled urea. This bifurcation is squeezing commodity urea margins while rewarding formulation specialists with coating capabilities and agronomic support infrastructure.
REACH and the EU Green Deal are pressing for full carbon footprint disclosure across ammonia supply chains. The regulation conditions market access for import-dependent blenders in Germany, France, and Poland. Nitrogen producers with integrated renewable hydrogen pilots or access to low-carbon natural gas certificates are securing preferential offtake terms from sustainability-committing cooperatives.
Cooperative procurement consolidation is compressing distributor margins across North American corn-soy rotations. Large grower cooperatives in Minnesota and Nebraska are negotiating direct supply agreements with ammonia producers, bypassing traditional retail channels. This disintermediation is most visible in regions with strong cooperative infrastructure and transparent price benchmarking through USDA reporting services.
Mineral Fertilizers Market Segmentation
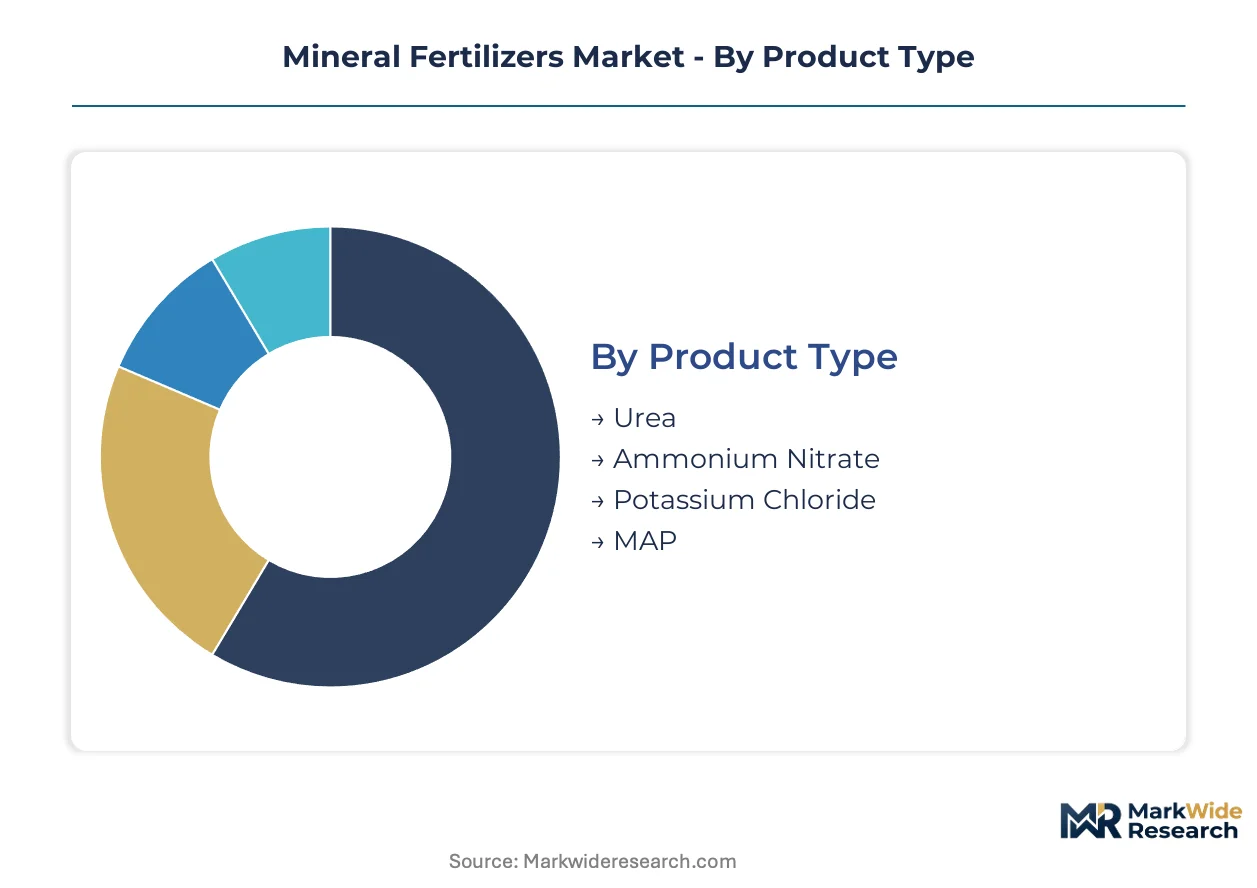
Mineral fertilizer segmentation determines formulation specifications, distribution channel economics, and regulatory compliance pathways. Product chemistry and physical grade dictate application equipment compatibility and nutrient release kinetics across divergent cropping systems.
Product Type:
REACH substance evaluation timelines and EPA water quality mandates differentiate registration burdens across nitrogen and phosphate chemistries, reshaping competitive positioning for import-dependent blenders.
- Urea:Synthesized through Haber-Bosch ammonia reaction with carbon dioxide, yielding 46% nitrogen density in prilled or granular form. Corn-soy rotations across Iowa and Illinois concentrate demand where polymer-coated variants command 15-20% price premiums for volatilization control. Urea handles the majority of throughput; MAP is the fastest mover on share.
- Ammonium Nitrate:Double-salt crystalline product combining ammonia and nitric acid, delivering immediate nitrogen availability with lower volatilization risk than urea. European wheat producers under EU Green Deal carbon disclosure requirements favor it for split-application programs despite stricter storage security protocols.
- Potassium Chloride:Mined from Saskatchewan evaporite deposits or Belarusian rail corridors, supplying K2O for fruit quality and drought resistance.
- MAP:Monoammonium phosphate granules with 11-52-0 N-P-K ratio, acidulated from Florida or Moroccan phosphate rock.
Granular MAP climbs fastest in commercial horticulture; urea retains volume dominance in mechanized row-crop broadcasting.
Grade:
Cost tier differentiation separates premium coating technologies from commodity bulk products, with liquid adaptability capturing specialty vegetable premiums.
- High Analysis:Concentrated nutrient formulations exceeding 40% total macronutrient density, typically urea-based or compound NPK blends. Brazilian soybean operations in Mato Grosso and Pará concentrate procurement where protein content premiums justify micronutrient-fortified custom blends.
- Standard Grade:Conventional prilled or granular products with 20-35% nutrient density, distributed through cooperative networks across Minnesota and Nebraska.
- Liquid Fertilizers:Ammonium polyphosphate or urea-ammonium nitrate solutions for fertigation and foliar delivery.
- Granular Fertilizers:Sized prills for mechanized spreader compatibility, dominating Corn Belt application windows.
Granular grades dominate equipment-installed base; liquid formulations expand most quickly in drip-irrigated vegetable districts.
Application:
End-use crop value per hectare determines formulation sophistication, with cash crops justifying precision agriculture investments unavailable in cereal systems.
- Cereals:Wheat, rice, and corn production systems consuming bulk nitrogen for biomass accumulation. India's wheat-belt states of Punjab and Haryana concentrate subsidized urea distribution where CEA-linked pricing mechanisms distort soil nutrient balance toward nitrogen overuse.
- Fruits:Tree and vine crops requiring potassium-intensive programs for sugar accumulation and shelf-life extension.
- Vegetables:High-value row crops with micronutrient sensitivity and foliar feeding protocols.
- Cash Crops:Cotton, sugarcane, and oilseeds with specialized NPK ratios and sulfur supplementation.
Cereals absorb the largest absolute tonnage; vegetables generate the steepest margin expansion trajectory per nutrient unit applied.
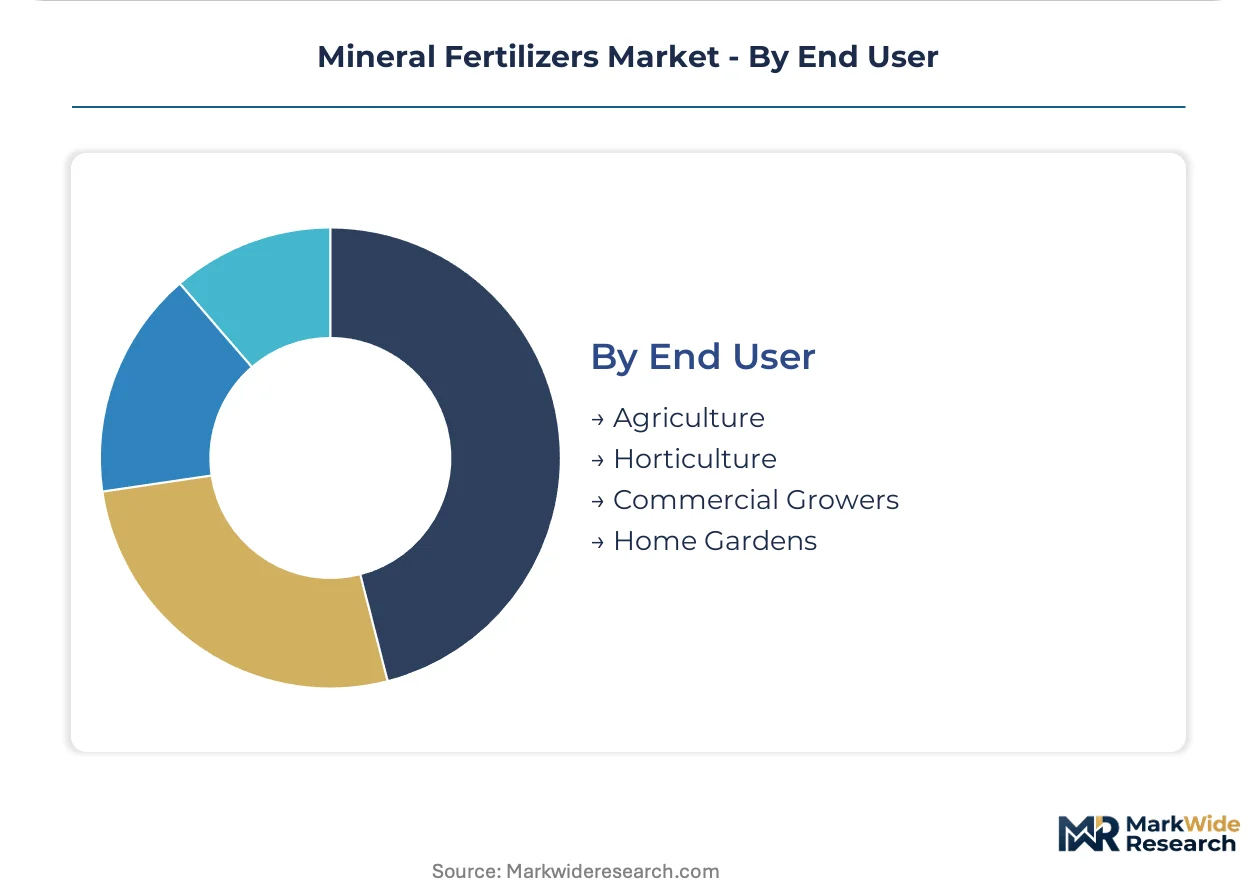
End User:
Customer scale dictates procurement channel structure, with commercial growers bypassing retail through direct ammonia offtake agreements.
- Agriculture:Broad-acre row-crop and smallholder systems representing baseline volume demand. Nigerian and Kenyan smallholders present underpenetrated expansion potential where packaged blend distribution remains sparse.
- Horticulture:Protected cultivation and nursery operations requiring soluble specialty formulations.
- Commercial Growers:Large-scale operations with cooperative procurement consolidation compressing distributor margins.
- Home Gardens:Consumer-packaged retail products with convenience-oriented sizing and application guidance.
Agriculture commands the volume base; commercial growers are gaining share fastest through disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA-linked subsidy mechanisms in India anchor volume demand across the wheat-belt states, while REACH carbon disclosure mandates in Europe and EPA water quality standards in the United States reshape formulation requirements and competitive access for import-dependent blenders.
United States
Corn-soy rotations across Iowa and Illinois concentrate urea and MAP procurement where polymer-coated variants command price premiums for volatilization control. EPA phosphorus runoff restrictions mandate buffer zones and formulation changes across Corn Belt states, raising compliance costs for phosphate blenders. Large grower cooperatives in Minnesota and Nebraska negotiate direct ammonia offtake agreements, bypassing traditional retail channels.
Brazil
Specialty soybean operations in Mato Grosso and Pará drive micronutrient blend expansion to capture protein content premiums from export markets. ANVISA-style fertilizer quality protocols tighten registration thresholds for imported formulations. Mechanized broadcasting systems across the Cerrado cluster favor granular grades with coating technologies for nutrient use efficiency.
China
NMPA-style fertilizer registration reforms tighten product quality thresholds and consolidate domestic production capacity. Dual carbon goals press ammonia producers toward renewable hydrogen pilots and low-carbon natural gas sourcing. Yangtze River Delta blending terminals face margin compression as state distribution networks standardize pricing.
India
Punjab and Haryana wheat-belt states absorb subsidized urea distribution under CEA-linked mechanisms that distort soil nutrient balance toward nitrogen overuse. Precision agriculture pilots expand micronutrient adoption among commercial growers seeking yield optimization. Gujarat and Maharashtra fertilizer terminals handle the bulk of imported potash and phosphate for domestic formulation.
Germany
EU Green Deal carbon footprint disclosure mandates condition market access for nitrogen importers across the Rhine corridor blending network. REACH substance evaluation timelines delay novel additive commercialization. Lower Saxony and North Rhine-Westphalia host the largest ammonia import terminals serving continental cooperative procurement consolidation.
Mineral Fertilizers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around ammonia network control and apatite concentrate grade advantages. The upper tier commands distribution infrastructure and captive raw material positions, while mid-scale blenders compete on formulation customization and agronomic service intensity. Strategic archetypes span integrated ammonia-to-nitrogen producers, phosphate rock miners with acidulation capacity, and potash extractors with rail-linked export corridors. Dominant competitive moves include cooperative procurement consolidation bypassing retail channels and controlled-release coating technology licensing to defend margin positions.
Among integrated nitrogen producers, Yara International and CF Industries Holdings occupy positions anchored by ammonia network density and European supply security mandates. Nutrien Ltd represents the vertically integrated agribusiness archetype with retail channel control across North American corn-soy rotations. PhosAgro exemplifies the phosphate concentrate specialist competing on Murmansk ore grade rather than freight arbitrage, while Uralkali and K+S sit within the potash extraction tier constrained by sanctions-disrupted rail corridors and evaporite deposit quality differentiation.
| Leading Market Players |
|---|
| The Mosaic Company |
| Uralkali |
| Yara International |
| PhosAgro |
| ICL Group |
| Nutrien Ltd |
| EuroChem Group |
| K+S |
| CF Industries Holdings |
| Others |
Value Chain & Pricing Dynamics
Polymer-coated urea substitution for conventional prilled grades simultaneously redistributes production geography toward coating-capable blending terminals and compresses price premiums for commodity nitrogen across Iowa and Illinois corn-soy rotations. This input substitution dynamic concentrates margin capture with formulation specialists while eroding pricing power at bulk urea importers lacking coating infrastructure.
Pricing Analysis
Geographic price spreads between Saskatchewan potash railheads and Southeast Asian discharge ports widen when Belarusian sanctions disrupt Lithuanian corridor access, amplifying volatility for K2O-dependent vegetable producers. Contract-based long-term offtake agreements dominate nitrogen procurement, with price differentiation driven by carbon certification tier under EU Green Deal mandates and volume scale in cooperative procurement consolidation. Pricing pressure intensifies from cooperative disintermediation bypassing traditional retail channels, compressing distributor margins most severely in Minnesota and Nebraska where USDA price benchmarking enables transparent direct negotiations.
Supply Chain Analysis
Russia and Belarus anchor global potash extraction through rail-linked export corridors feeding Murmansk and Baltic Sea terminals, while Canada and China concentrate phosphate rock acidulation and ammonia synthesis capacity respectively. Raw material dependencies center on natural gas feedstock for Haber-Bosch ammonia production, phosphate rock from Florida and Moroccan deposits, and potash evaporite extraction. Single-source vulnerability concentrates in Belarusian rail corridors where sanctions exposure constrains K2O availability. Distribution runs through cooperative procurement networks across North American corn-soy rotations and state-subsidized distribution mechanisms in Indian wheat-belt states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative procurement consolidation across Minnesota and Nebraska, fragmenting traditional retail channel economics and forcing supply-side repositioning.
For Market Incumbents: Consolidate ammonia network control through backward integration into low-carbon hydrogen pilots and captive coating technology licensing to defend margin positions against cooperative disintermediation. Secure preferential offtake terms from sustainability-committing cooperatives by investing in EU Green Deal carbon certification infrastructure before REACH disclosure mandates harden competitive access barriers. For New Entrants and Emerging Players: EU Green Deal carbon footprint certification fast-track positions low-carbon ammonia importers for preferential access across German and Polish blending networks underserved by incumbent high-carbon producers. Target Nigerian and Kenyan smallholder packaged blend distribution where agronomic service intensity remains sparse and volume expansion potential concentrates in underpenetrated soil nutrient deficit regions. Pursue foliar application drone system partnerships as precision agriculture convergence creates channel innovation entry points. For Investors and Strategic Acquirers: REACH substance evaluation timeline extensions and EU carbon border adjustment implementation reshape the acquisition landscape toward low-carbon certification holders and coating-capable formulation specialists with agronomic support infrastructure. Long-term viability favors integrated ammonia-to-nitrogen producers with renewable hydrogen pilots and phosphate rock miners with acidulation capacity in low-regulatory-cost jurisdictions. Monitor Belarusian rail corridor sanction durability as the primary inflection signal for potash supply concentration risk and K2O pricing volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Hydrogen | Secures ammonia feedstock cost stability under EU Green Deal carbon disclosure mandates. |
| Controlled-Release Coating Technology Licensing | Captures premium positioning in Iowa and Illinois corn-soy rotations demanding volatilization control. |
| Cooperative Procurement Partnership | Bypasses retail margin compression through direct ammonia offtake agreements in Minnesota and Nebraska. |
| Sub-Saharan Africa Distribution Buildout | Addresses Nigerian and Kenyan soil nutrient deficits through packaged blend agronomic service intensity. |
| EU Carbon Certification Program | Conditions market access for import-dependent German and Polish blenders under REACH evaluation timelines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ammonia plant managers, cooperative procurement leads, fertilizer distribution channel partners, and technical agronomists across Black Sea extraction corridors and North American corn-soy rotations. Secondary validation drew from customs and trade data, SEC 10-K filings of listed nitrogen producers, EIA natural gas pricing benchmarks, and EU ETS carbon market disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic demand drivers across the analysis window.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product chemistry tier, physical grade specification, end-use crop value per hectare, and customer scale archetype from smallholder to commercial grower. CAGRs were derived through regression analysis of historical volume trajectories against input cost elasticity and regulatory compliance burden evolution. Industry-specific forecast inputs incorporated natural gas feedstock volatility patterns and REACH substance evaluation timeline uncertainty.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and stable Indian CEA-linked subsidy mechanisms; material deviation in Belarusian rail corridor access or cooperative procurement consolidation velocity would warrant model refresh. Recalibration cycles align with material shifts in carbon border adjustment enforcement and precision agriculture technology penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Global Complex Fertilizers Market