
 Sulphur Coated Urea Market | 2026-2036
Sulphur Coated Urea Market Size, Share, and Industry Trends Forecast 2026-2036
Sulphur Coated Urea Market Outlook
Buyer concentration among agricultural cooperatives is decoupling from historical distributor dependency across North American grain belts. Koch Industries Inc. leverages its integrated sulphur supply chain to sustain cost advantages in coated urea production. Yara International ASA anchors its position through deep agronomic service relationships with European farming syndicates. Nutrien Ltd. dominates wholesale distribution infrastructure across the Canadian prairies and US Midwest corridors.
Sulphur coated urea consists of granular or prilled urea cores enveloped in elemental sulphur layers, typically comprising 10-30% sulphur by weight, with secondary sealants controlling nitrogen release over 6-12 week cycles. The product serves commercial agriculture by synchronizing nutrient availability with crop uptake patterns, reducing leaching losses in intensive cultivation systems. Granule formulations lead volume share due to compatibility with existing spreader equipment, while tablet variants capture premium positioning in high-value horticulture segments. Agricultural stores remain the dominant distribution channel, though distributor consolidation is reshaping margin capture across the value chain.
EPA nutrient management guidelines and the EU Nitrates Directive constrain application rates in sensitive watersheds, elevating demand for precision-release alternatives. BIS fertilizer quality standards in India and China's GB standards for slow-release products govern import specifications and domestic manufacturing compliance. Stakeholders must monitor evolving carbon accounting methodologies for agricultural inputs, as lifecycle emissions metrics increasingly influence procurement decisions by sustainability-focused agricultural companies.
Market Dynamics
Precision agriculture adoption among large-scale farming cooperatives is decoupling nutrient procurement from traditional distributor networks, forcing coated urea suppliers to build direct agronomic service capabilities or lose volume to integrated farm input platforms.
Growth Catalysts
- Brazil's Cerrado Expansion:Soybean cultivation intensification in Mato Grosso and Goiás states sustains demand for controlled-release formulations that match nutrient release to extended crop uptake windows.
- EU F-Gas Regulation:Nitrogen emission caps under the EU Green Deal framework elevate demand for precision-release alternatives that reduce ammonia volatilization in intensive arable systems.
- Tablet Formulation Innovation:Secondary sealant advances in horticultural-grade products command premium positioning in high-value protected cropping operations across Mediterranean greenhouse clusters.
Market Restraints
- Elemental Sulphur Price Volatility:Refinery byproduct supply fluctuations and sulphuric acid demand competition from battery manufacturing compress coating cost margins unpredictably.
- Granule Equipment Lock-In:Compatibility requirements with existing pneumatic spreader infrastructure limit rapid format switching despite superior release-profile alternatives.
- Conventional Urea Substitution:Unsubsidized price premiums of 15-40% above standard prilled urea restrict uptake in price-sensitive smallholder segments across South Asian rice belts.
Strategic Opportunities
- Carbon Accounting Integration:Lifecycle emissions methodologies for agricultural inputs create procurement preference shifts among sustainability-focused European farming syndicates seeking Scope 3 reductions.
- Direct-to-Farm Platforms:Bypassing consolidated agricultural store networks through cooperative purchasing aggregators captures margin previously captured by distributor intermediaries.
- Sub-Saharan Underpenetration:Low controlled-release fertilizer adoption in Nigerian and Kenyan commercial maize operations offers first-mover positioning ahead of input subsidy program reforms.
Industry Challenges
- Release-Rate Calibration Complexity:Matching sulphur layer thickness and sealant composition to specific soil temperature and moisture regimes requires specialized agronomic support capabilities most distributors lack.
- Multi-Jurisdiction Compliance Burden:Simultaneous adherence to EPA nutrient management guidelines, EU Nitrates Directive specifications, and BIS fertilizer quality standards fragments product formulation and labeling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulphur Coated Urea Market |
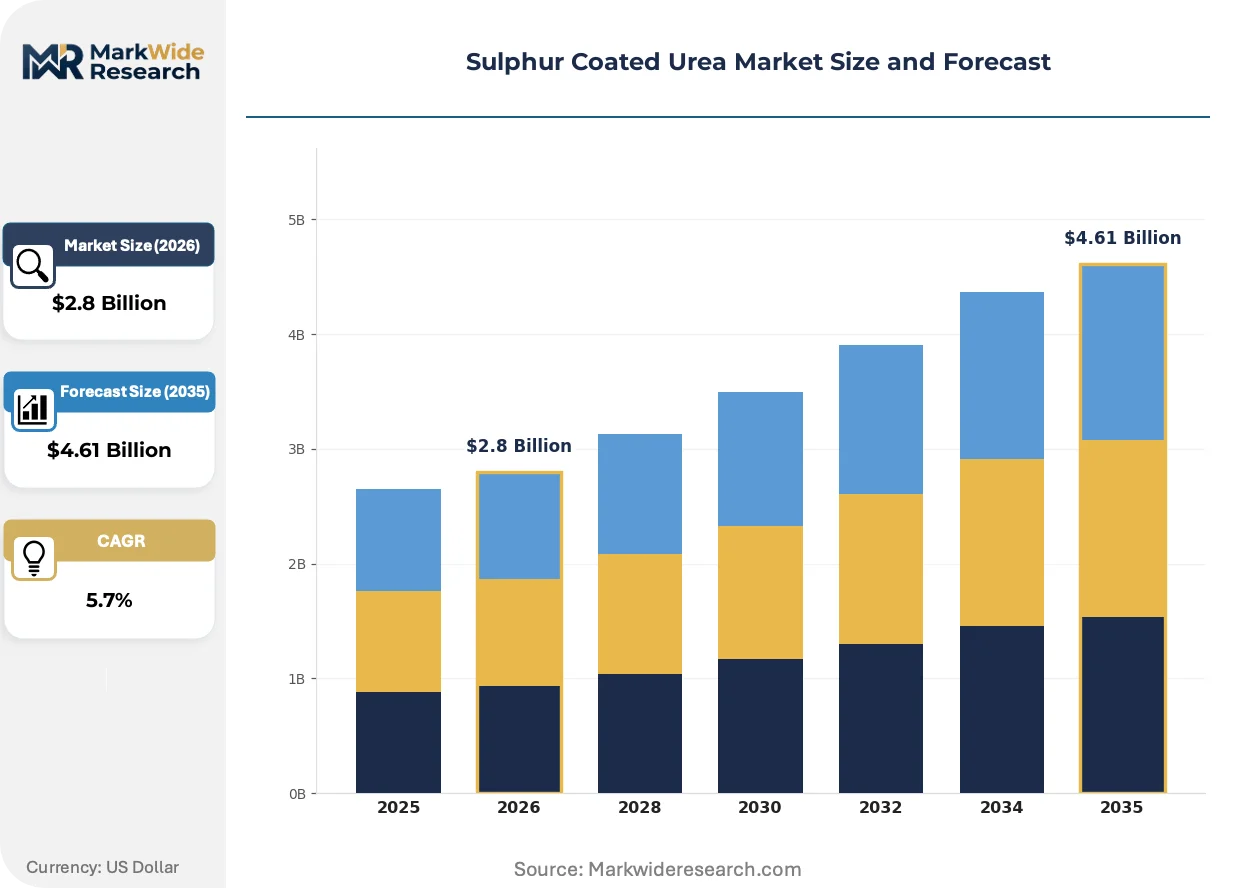
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Prills, Tablets, Coated Urea Application: Agriculture, Gardening, Turf Management, Horticulture Distribution Channel: Online Retail, Agricultural Stores, Distributors, Wholesalers End User: Farmers, Agricultural Companies, Landscaping Firms, Greenhouses |
| Companies Covered | Israel Chemicals Ltd., Haifa Chemicals Ltd, Agrium Inc., Koch Industries Inc., J. R. Simplot Company, Yara International ASA, Andersons Inc., Nutrien Ltd., Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulphur Coated Urea Market Strategic Shifts
Coating technology convergence with digital agriculture platforms is redefining how nutrient release profiles are specified, monitored, and validated across commercial farming operations.
Polymer-sulphur hybrid coating systems are decentralizing nitrogen management authority from agronomists to on-farm sensor networks. Large-scale Midwest grain operations deploy soil moisture probes and canopy sensors to trigger supplemental feeding decisions independent of fixed calendar schedules. This shift compresses the value capture window for traditional extension services while elevating demand for coatings with adjustable release curves.
The EU Nitrates Directive revision process is tightening permissible application windows in nitrate-vulnerable zones. German and Dutch arable producers face compressed autumn spreading permissions that elevate demand for products capable of safe early-season placement without leaching risk. Formulators respond with sulphur layer modifications that delay initial nitrogen availability until soil temperatures cross biological activation thresholds.
Cooperative purchasing consolidation is displacing independent agricultural store networks across North American grain belts. Large farming syndicates in Iowa and Illinois negotiate direct supply agreements with coating manufacturers, extracting volume discounts and custom formulation services previously reserved for distributor tier-one accounts. This channel compression forces remaining independents into specialty horticulture niches or exit.
Sulphur Coated Urea Market Segmentation
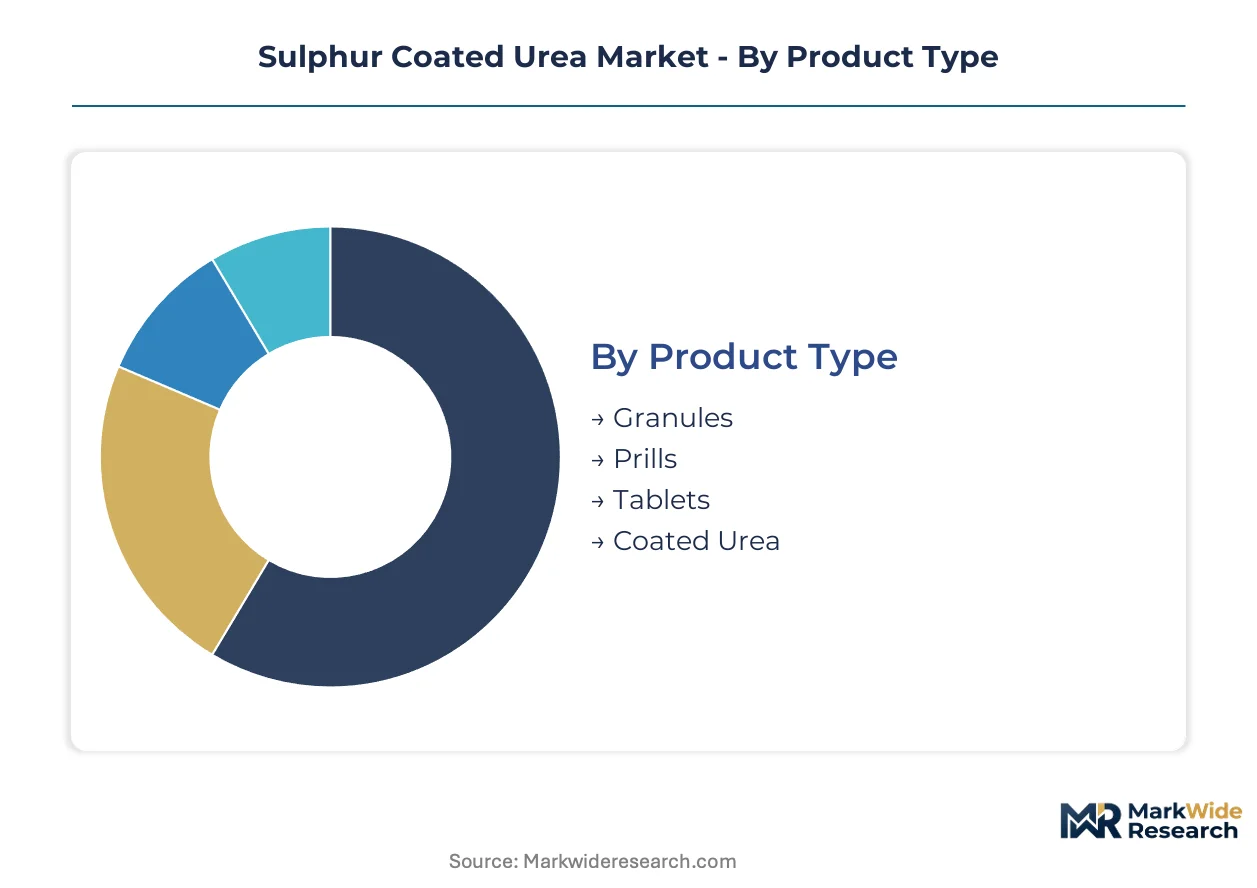
Sulphur coated urea producers face divergent technical requirements across agricultural versus horticultural applications, forcing formulation trade-offs between release precision and manufacturing scale. Segmentation discipline determines which coating specifications justify dedicated production lines versus flexible batch configurations.
Product Type:
Coating thickness specifications concentrate production economics in formats compatible with existing fertilizer handling infrastructure.
- Granules:Granular urea cores receive sulphur layers through rotary drum coating, producing free-flowing particles that meter accurately through pneumatic spreaders. Demand clusters in Iowa and Illinois grain operations where cooperative purchasing agreements specify granule compatibility with existing equipment fleets. Equipment lock-in effects protect this segment against format substitution despite superior release alternatives.
- Tablets:Compressed urea cores with precision sulphur encapsulation enable exact placement in protected cropping systems. Mediterranean greenhouse clusters in Spain and Italy absorb volume for high-value vegetable production where nutrient timing directly correlates with harvest quality premiums. Secondary sealant advances command pricing power in horticultural channels.
- Prills:Spherical prilled cores offer intermediate surface-area-to-volume ratios for moderate-release applications in broadacre cereals.
- Coated Urea:Polymer-sulphur hybrid systems represent the technology frontier for adjustable release curves in precision agriculture deployments.
Granules absorb the bulk of installed capacity; tablets are expanding most quickly.
Application:
Application-specific nitrogen timing requirements fragment demand across calendar-driven versus sensor-triggered feeding regimes.
- Agriculture:Commercial row-crop operations in Brazil's Mato Grosso state deploy controlled-release formulations to match nutrient availability with extended soybean uptake windows. The EU Nitrates Directive constrains autumn application timing, elevating demand for products capable of safe early-season placement without leaching risk.
- Horticulture:Protected cropping operations require exact nutrient synchronization with generative growth phases in tomato and pepper production. German and Dutch greenhouse clusters under tightening nitrogen emission caps drive specification of sulphur layer modifications that delay initial availability until soil temperatures cross biological activation thresholds.
- Gardening:Consumer lawn and garden segments prioritize convenience over precision, accepting broader release windows for reduced application frequency.
- Turf Management:Golf course and sports field maintenance demands uniform greening without surge growth, favoring predictable 8-12 week release profiles.
Agriculture commands the dominant revenue share; horticulture is climbing the fastest.
Distribution Channel:
Channel structure determines margin capture between manufacturers and end-users through tiered service intensity.
- Agricultural Stores:Independent and cooperative retail networks remain the dominant physical channel across North American grain belts, though consolidation compresses intermediary margins. Staff agronomic advice justifies price premiums in regions where cooperative purchasing has not yet displaced traditional distributor relationships.
- Distributors:Wholesale distributors aggregate volume across dispersed farming operations, capturing economies in logistics and credit extension. Nutrien Ltd. dominates this tier across Canadian prairies and US Midwest corridors through integrated supply chain control.
- Online Retail:E-commerce platforms gain traction in horticultural inputs where small-batch requirements and technical documentation favor digital specification.
- Wholesalers:Volume merchants serve price-sensitive commodity purchasers with limited formulation customization.
Agricultural stores retain the largest transaction volume; online retail is gaining share fastest.
End User:
End-user scale and technical sophistication segment service requirements from standardized commodity supply to custom formulation partnerships.
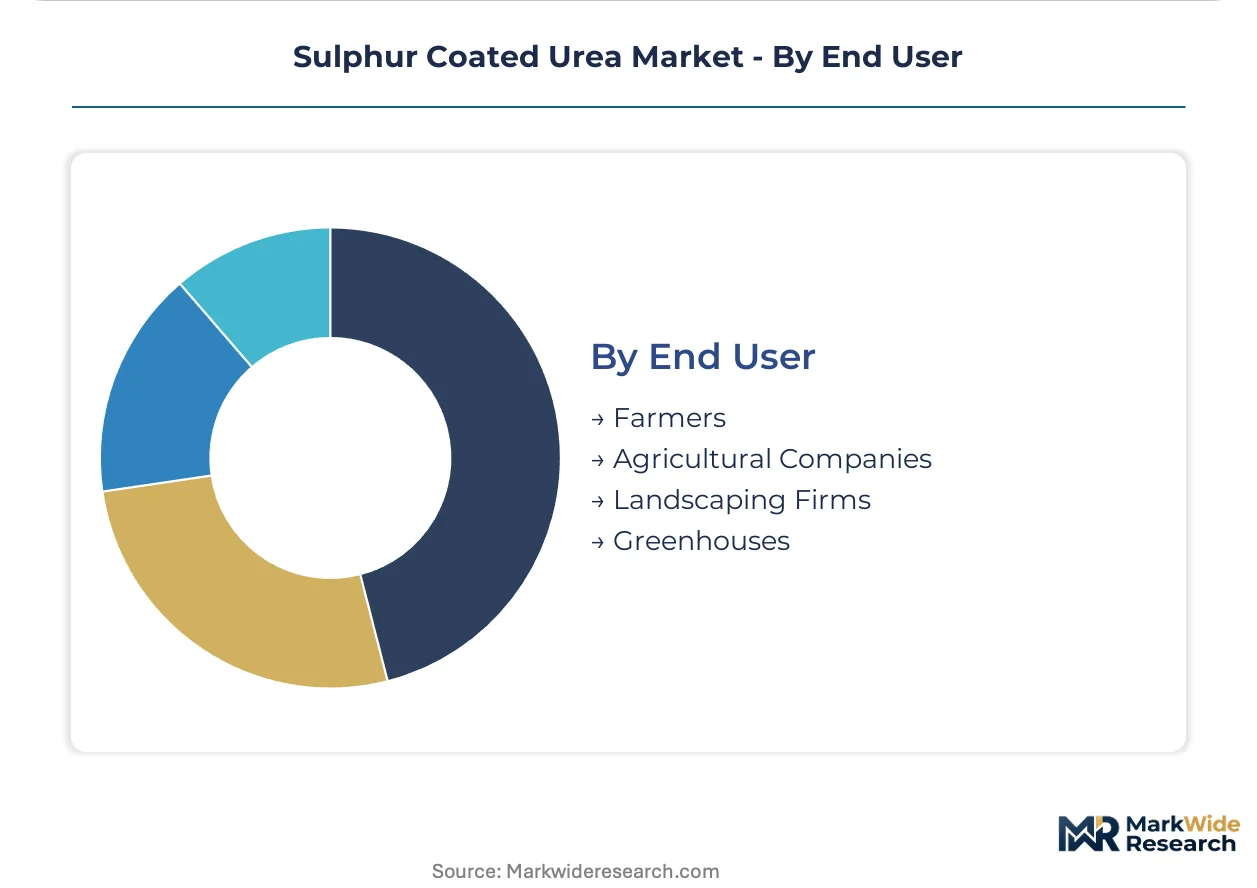
- Farmers:Large-scale farming cooperatives in Goiás state negotiate direct supply agreements with coating manufacturers, extracting volume discounts and custom formulation services. This procurement shift bypasses consolidated agricultural store networks and forces remaining independents into specialty niches or exit.
- Agricultural Companies:Corporate farming operations deploy soil moisture probes and canopy sensors to trigger supplemental feeding decisions, elevating demand for coatings with adjustable release curves compatible with digital agriculture platforms.
- Greenhouses:Controlled-environment producers require precise nutrient timing correlation with artificial lighting and climate control schedules.
- Landscaping Firms:Commercial maintenance contractors prioritize labor efficiency through reduced application frequency in municipal and corporate grounds.
Farmers represent the largest addressable base; agricultural companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for sulphur coated urea clusters in agricultural export corridors where intensive cultivation meets tightening environmental regulations. Brazil, the United States, Germany, India, and China anchor volume consumption through distinct combinations of crop intensity, cooperative purchasing power, and nitrogen emission controls.
Brazil
Soybean expansion across Mato Grosso and Goiás states sustains demand for controlled-release formulations matching extended crop uptake windows. ANVISA fertilizer quality standards govern import specifications and domestic manufacturing compliance. The Cerrado region absorbs premium volumes as large farming cooperatives negotiate direct supply agreements with coating manufacturers.
United States
Midwest grain operations in Iowa and Illinois deploy precision agriculture platforms that elevate demand for adjustable-release coating systems. EPA nutrient management guidelines constrain application rates in sensitive watersheds, favoring precision-release alternatives. Cooperative purchasing consolidation across the Corn Belt displaces traditional agricultural store networks.
Germany
Arable producers face compressed autumn spreading permissions under EU Nitrates Directive revisions in nitrate-vulnerable zones. The EU F-Gas Regulation and Green Deal frameworks tighten nitrogen emission standards for fertilizer applications. German and Dutch greenhouse clusters drive specification of sulphur layer modifications that delay initial nitrogen availability until soil temperatures cross biological activation thresholds.
India
Rice belt intensification in Punjab and Haryana generates demand for leaching-reduction formulations, though price-sensitive smallholder segments limit unsubsidized uptake. BIS fertilizer quality standards govern import specifications and domestic manufacturing compliance. The Indo-Gangetic Plain remains underpenetrated for controlled-release products relative to cultivation intensity.
China
Domestic production capacity expansion targets self-sufficiency in slow-release fertilizer categories under national food security frameworks. GB standards for slow-release products govern manufacturing compliance and import specifications. The Yangtze River Delta concentrates demand from high-value horticulture operations requiring exact nutrient synchronization.
Sulphur Coated Urea Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue polymer-sulphur hybrid coating systems. The market structure consolidates around integrated agrochemical conglomerates with captive sulphur supply chains and regional distributors with deep agronomic service relationships. Three archetypes dominate: upstream-integrated petrochemical operators, cooperative-aligned wholesale distributors, and specialty coating technology licensors. Competitive moves concentrate on backward integration into elemental sulphur sourcing and direct-to-farm platform development bypassing intermediary tiers.
Among integrated petrochemical operators, Koch Industries Inc. exemplifies upstream-integrated positioning through sulphur supply chain control. Yara International ASA anchors the European tier through agronomic service relationships with farming syndicates. Nutrien Ltd. occupies wholesale distribution dominance across North American prairie corridors. These three represent distinct strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Israel Chemicals Ltd. |
| Haifa Chemicals Ltd |
| Agrium Inc. |
| Koch Industries Inc. |
| J. R. Simplot Company |
| Yara International ASA |
| Andersons Inc. |
| Nutrien Ltd. |
| Syngenta AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap coating specialists in the US Midwest and European agrarian belts anchor pricing discipline through captive sulphur sourcing relationships and cooperative-aligned volume commitments. Their ownership structure insulates margin targets from quarterly earnings pressure, enabling long-term contract pricing that stabilizes input cost pass-through to Brazilian and North American grain cooperatives.
Pricing Analysis
Volume-margins split sharply between granule commodity tiers and precision tablet formulations. Three-tier pricing structure across premium, standard, and economy levels reflects coating thickness precision and secondary sealant sophistication. Cost compression in standard granule tiers is intensifying because refinery byproduct sulphur supply fluctuates with battery manufacturing demand competition. Smallholder rice cultivators in South Asia exhibit acute price sensitivity, while Mediterranean greenhouse operators absorb premium positioning for exact nutrient synchronization.
Supply Chain Analysis
Direct-to-farm cooperative channels handle hyperscale buyer demand across Iowa, Illinois, and Mato Grosso grain belts, bypassing traditional agricultural store intermediaries. Elemental sulphur feedstock draws from US Gulf Coast refineries, Canadian oil sands processing, and Middle Eastern sour crude operations. Single-source vulnerability concentrates in pneumatic spreader equipment compatibility requirements that lock granule format dominance despite superior release alternatives. Distribution runs through Nutrien Ltd.'s integrated prairie infrastructure and Koch Industries' captive sulphur pipeline networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and Green Deal nitrogen emission frameworks erect a cost-of-compliance barrier that favors incumbents with established agronomic service capabilities and certified formulation portfolios. New entrants face capital-intensive coating technology validation requirements before accessing European farming syndicate procurement channels.
For Market Incumbents: Hedge against conventional urea substitution pressure by deepening backward integration into elemental sulphur sourcing and deploying direct-to-farm digital platforms that bypass consolidating agricultural store networks. Capture margin compression defense through custom formulation partnerships with large-scale Brazilian cooperatives. For New Entrants and Emerging Players: Begin with underpenetrated Sub-Saharan commercial maize operations in Nigeria and Kenya ahead of input subsidy program reforms. Target horticultural tablet segments in Mediterranean greenhouse clusters where secondary sealant advances command pricing power absent commodity granule equipment lock-in. For Investors and Strategic Acquirers: Cooperative purchasing consolidation across North American grain belts is the leading indicator that channel compression will accelerate margin capture by upstream-integrated coating manufacturers. Prioritize acquisition targets with captive sulphur supply chains and established EPA nutrient management guideline compliance portfolios. Watch for Brazilian ANVISA fertilizer quality standard enforcement shifts as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elemental Sulphur | Koch Industries' captive supply chain sustains cost advantages against refinery byproduct volatility. |
| Direct-to-Farm Platform Development | Nutrien Ltd. bypasses agricultural store consolidation through cooperative purchasing aggregator partnerships. |
| Polymer-Sulphur Hybrid Coating R&D | Yara International ASA anchors European positioning through adjustable release curve innovation. |
| Sub-Saharan Market Entry | First-mover positioning in Nigerian maize operations captures subsidy reform upside ahead of incumbent response. |
| Carbon Accounting Certification | Lifecycle emissions methodology compliance unlocks sustainability-focused European farming syndicate procurement preference. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this sulphur coated urea market assessment. Primary interviews with coating plant managers, agricultural cooperative procurement leads, distributor channel partners, and technical R&D directors at major formulators were cross-referenced against EPA nutrient management guidelines, EU Nitrates Directive specifications, BIS fertilizer quality standards, and Brazilian ANVISA compliance databases. Bottom-up volume triangulation across granule, tablet, and prill production lines was reconciled with top-down fertilizer consumption forecasts from national agricultural ministries.
Data-stream reconciliation across the analysis window employed simultaneous modeling of product type segmentation, application-specific nitrogen timing requirements, distribution channel margin capture, and end-user scale sophistication. CAGRs were derived from weighted regression of historical consumption patterns against soybean expansion trajectories in Brazil's Cerrado, EU emission cap enforcement intensity, and cooperative purchasing consolidation velocity across North American grain belts. Sulphur layer thickness specifications and sealant composition advances were tracked as technology frontier inputs.
Underlying measurement precision varies by segment; horticultural tablet formulations and polymer-sulphur hybrid systems carry tighter precision than commodity granule volumes given concentrated greenhouse cluster demand concentration. Forecasts reflect assumptions regarding EPA watershed constraint enforcement continuity, EU Green Deal nitrogen emission standard implementation pace, and elemental sulphur refinery byproduct supply stability. Periodic stress-testing of base assumptions against battery manufacturing demand competition and input subsidy program reform timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Nano Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Soil Conditioners Market
Fertilizers
India Micronutrient Fertilizer Market