
 India Specialty Fertilizer Market | 2026-2036
India Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
India Specialty Fertilizer Market Foresight
Precision delivery technology is fragmenting conventional bulk fertilizer application models across Indian agriculture. Coromandel International Ltd anchors its position through backward integration into phosphoric acid and sulfuric acid production. ICL Group Ltd differentiates via controlled-release and water-soluble product portfolios calibrated for tropical soil conditions. Yara International ASA extends its digital farming platform to Indian contract farmers, combining sensor data with customized micronutrient prescriptions.
India specialty fertilizers comprise value-added formulations including biofertilizers, micronutrients, organic fertilizers, and controlled-release fertilizers designed for targeted nutrient delivery with enhanced use efficiency. These products typically incorporate polymer coatings, chelation complexes, or microbial consortia to synchronize nutrient release with crop phenological stages, primarily serving commercial agriculture and export-oriented horticulture. Controlled-release fertilizers command premium positioning due to technical barriers in coating chemistry and the scarcity of domestic polymer supply. Micronutrients represent the fastest-expanding category as zinc, boron, and iron deficiencies become recognized yield constraints in intensively cultivated belts.
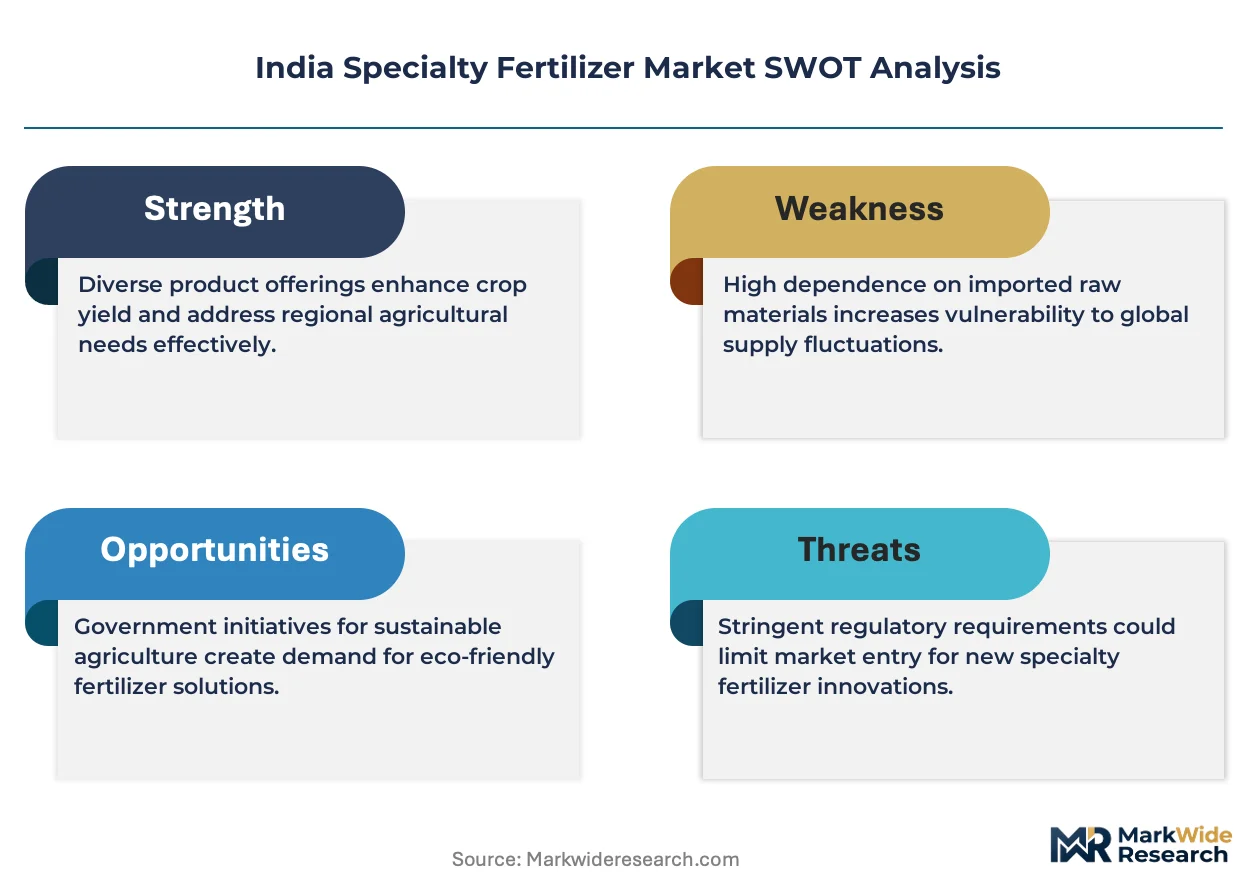
BIS certification requirements and the Fertiliser Control Order under the Ministry of Agriculture shape product registration timelines and quality enforcement across state markets. The PLI scheme for agrochemical manufacturing and nutrient-based subsidy mechanisms administered by the Department of Fertilisers are redirecting investment toward coated urea and fortified formulations. Stakeholders must monitor subsidy allocation shifts between conventional and specialty grades while building technical service capabilities to support farmer adoption of precision application protocols.
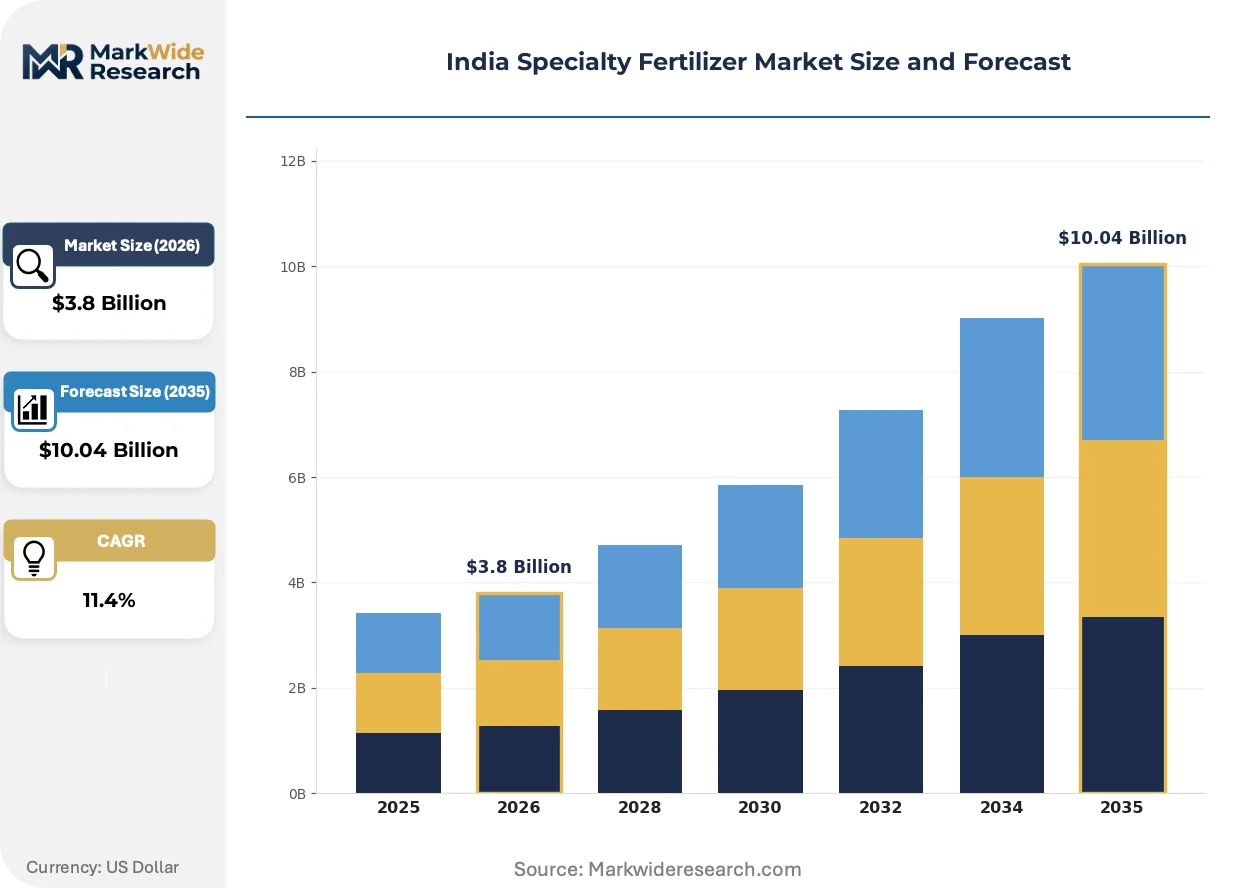
Market Dynamics
The PLI scheme for agrochemical manufacturing is redirecting domestic capital from commodity urea toward coated and slow-release formulations, compressing the historical subsidy advantage of bulk fertilizers and forcing technical service investments across the value chain.
Growth Catalysts
- Nutrient-Based Subsidy reform:The Department of Fertilisers is recalibrating support toward fortified and specialty grades, reducing the price gap against conventional urea and accelerating farmer switching in Maharashtra and Gujarat.
- Drip irrigation infrastructure:Micro-irrigation networks across western and southern state clusters create compatible delivery systems for water-soluble and controlled-release products, locking in precision application protocols.
- Zinc deficiency recognition:Soil health card programs and extension services are identifying micronutrient gaps in intensively cultivated belts, pulling demand for chelated zinc and boron formulations.
Market Restraints
- Domestic polymer supply scarcity:Controlled-release fertilizer coating chemistry depends on imported polyurethane and polyolefin resins, exposing margins to petrochemical price volatility and forex fluctuations.
- BIS certification timelines:The Bureau of Indian Standards product registration process extends commercialization cycles for new formulations, delaying revenue recognition against R&D investments.
- Commodity urea substitution:Heavily subsidized conventional nitrogen remains the default choice for price-sensitive smallholders in eastern and central state clusters.
Strategic Opportunities
- Export-oriented horticulture:Grape, pomegranate, and mango value chains in Nashik and Sangli districts require residue-compliant micronutrient programs for European and Middle Eastern market access.
- Contract farming digitization:Agri-input platforms are integrating specialty fertilizer prescriptions with sensor data, creating bundled service revenue streams beyond product margins.
- Organic fertilizer convergence:Microbial consortia and biofertilizer categories align with FSSAI organic certification demand and state-level organic farming missions in Karnataka and Sikkim.
Industry Challenges
- Soil science talent scarcity:Agronomists capable of translating soil test data into customized micronutrient prescriptions are concentrated in public extension services, constraining private sector technical service scaling.
- Application equipment fragmentation:Fertigation system compatibility varies across drip emitter specifications, forcing manufacturers to maintain multiple formulation grades and dilution protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Specialty Fertilizer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofertilizers, Micronutrients, Organic Fertilizers, Controlled-Release Fertilizers End User: Agriculture, Horticulture, Landscaping, Forestry Distribution Channel: Retail Stores, Online Stores, Agricultural Cooperatives, Direct Sales Application: Field Crops, Vegetable Crops, Fruit Crops, Ornamental Plants |
| Companies Covered | Indian Farmers Fertiliser Cooperative Limited, ICL Group Ltd, Coromandel International Ltd, Haifa Group, Yara International ASA, Chambal Fertilisers & Chemicals Ltd, Mangalore Chemicals & Fertilizers Ltd, Fertilisers and Chemicals Travancore Ltd, Deepak Fertilisers & Petrochemicals Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Specialty Fertilizer Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are converging around precision agriculture infrastructure, with coating technologies and digital prescription platforms compressing the gap between laboratory nutrient design and field-level application accuracy.
Sulfur-coated urea and polymer-encapsulated nitrogen are migrating from experimental station trials to commercial sugarcane and banana operations in Tamil Nadu and Uttar Pradesh. Large horticulture estates and cooperative processing units are adopting these products to synchronize nutrient release with critical growth stages. The technology is migrating from premium export crops toward domestic food grain value chains as input costs and labor availability tighten.
The Fertiliser Control Order under the Ministry of Agriculture is tightening quality enforcement and traceability requirements for micronutrient and organic categories. Manufacturers must now maintain batch-level documentation and third-party testing protocols, extending compliance costs toward smaller regional blenders. Specialty grade importers and domestic formulators are responding by consolidating testing partnerships and pre-certifying formulations for multiple state markets.
Farmer procurement of specialty inputs is fragmenting across agri-input platforms, cooperative societies, and direct contract arrangements with processors. Traditional dealer networks in Punjab and Haryana are losing share to digitized channels offering soil-test-linked recommendations and credit bundling. The shift is most visible in Karnataka and Telangana, where startup-backed platforms have achieved critical density in vegetable and flower cultivation belts.
India Specialty Fertilizer Market Segmentation
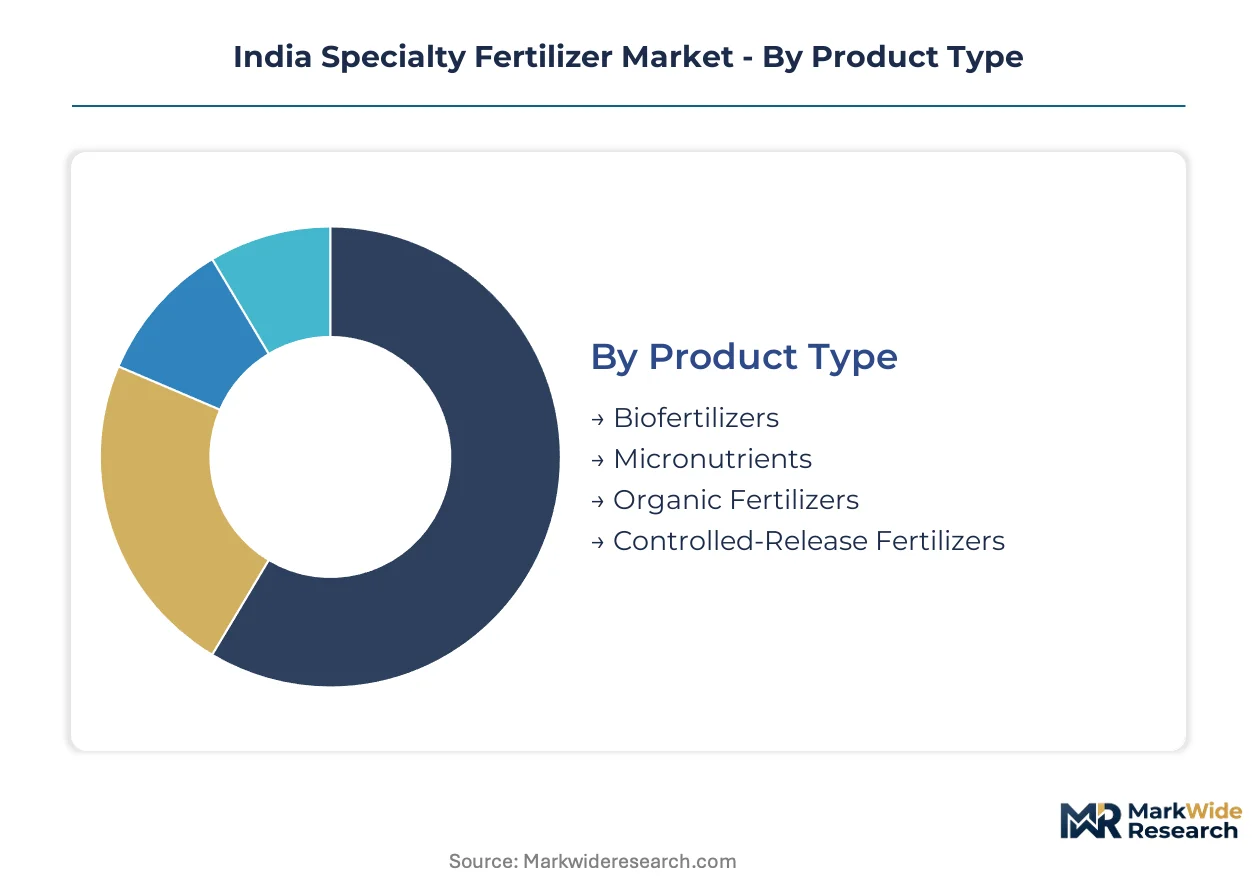
Specialty fertilizer segmentation in India reflects the tension between established bulk nutrient categories and precision agriculture's emerging requirements. Product portfolios must balance commodity-grade scale against formulation complexity that commands premium positioning.
Product Type:
Mature bulk nitrogen formulations coexist with emerging precision delivery technologies across India's fertilizer landscape.
- Controlled-Release Fertilizers:Polymer-coated and sulfur-encapsulated formulations synchronize nutrient release with crop phenological stages. Maharashtra and Gujarat horticulture belts drive demand as drip irrigation infrastructure achieves compatible density for precision application protocols.
- Micronutrients:Chelated zinc, boron, and iron formulations address documented deficiencies in intensively cultivated belts. Soil health card programs in Punjab and Haryana are pulling demand for targeted correction of yield-constraining nutrient gaps.
- Biofertilizers:Microbial consortia containing nitrogen-fixing and phosphate-solubilizing bacteria align with FSSAI organic certification requirements and state-level organic farming missions.
- Organic Fertilizers:Compost-based and vermicompost formulations serve Karnataka and Sikkim organic certification value chains with residue-compliant nutrient programs.
Controlled-release formulations handle the majority of throughput; micronutrients are climbing the fastest on share expansion.
End User:
Customer concentration varies sharply between volume-driven agricultural commodity producers and margin-focused horticulture operators.
- Agriculture:Field crop producers in wheat-rice belts of Punjab and Haryana represent the foundational demand base for fortified and coated urea applications under nutrient-based subsidy reform.
- Horticulture:Grape, pomegranate, and mango value chains in Nashik and Sangli districts require residue-compliant micronutrient programs for European and Middle Eastern export market access. Contract farming digitization in Karnataka and Telangana is integrating specialty prescriptions with sensor data platforms.
- Landscaping:Urban green infrastructure projects in Delhi NCR and Bengaluru metro regions create demand for slow-release formulations in turf and ornamental maintenance.
- Forestry:Plantation timber and agroforestry initiatives in Madhya Pradesh and Chhattisgarh utilize targeted nutrient delivery for establishment-phase biomass accumulation.
Agriculture absorbs the dominant volume share; horticulture demonstrates the steepest margin expansion trajectory.
Distribution Channel:
Channel evolution reflects the fragmentation of farmer procurement behavior across traditional and digitized touchpoints.
- Agricultural Cooperatives:State-level cooperative federations in Maharashtra and Gujarat maintain procurement leverage for bulk specialty formulations, particularly in sugarcane and cotton processing catchments.
- Online Stores:Agri-input platforms in Karnataka and Telangana have achieved critical density in vegetable and flower belts, bundling soil-test-linked recommendations with credit facilities.
- Retail Stores:Traditional dealer networks in Punjab and Haryana are losing share to digitized channels but retain loyalty among smallholder rice-wheat producers.
- Direct Sales:Large horticulture estates and cooperative processing units in Tamil Nadu and Uttar Pradesh negotiate direct manufacturer relationships for customized controlled-release programs.
Agricultural cooperatives move the largest tonnage; online platforms are gaining share fastest among commercial growers.
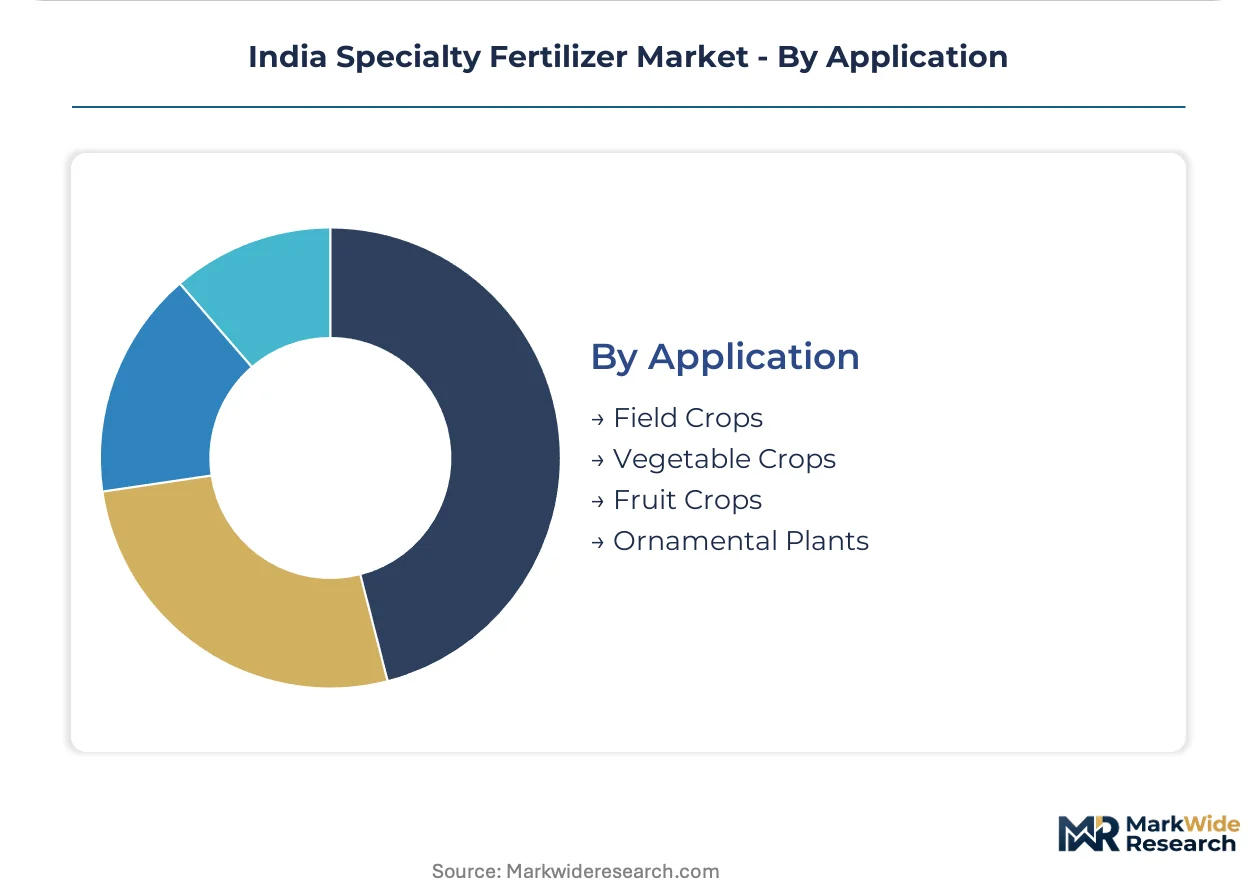
Application:
Application segmentation tracks the migration of precision nutrient technology from premium export crops toward domestic food grain value chains.
- Fruit Crops:Banana and mango operations in Tamil Nadu and Uttar Pradesh are adopting sulfur-coated urea to synchronize nutrient release with critical growth stages and flowering induction.
- Vegetable Crops:Protected cultivation and precision greenhouse operations in Nashik and Bengaluru require water-soluble and foliar micronutrient protocols calibrated for high-frequency fertigation cycles.
- Field Crops:Sugarcane and cotton in Maharashtra and Gujarat represent the migration path for controlled-release technology from experimental stations to commercial scale.
- Ornamental Plants:Floriculture export units in Karnataka and Telangana utilize chelated micronutrient programs meeting phytosanitary requirements for European market access.
Field crops dominate absolute volume; fruit crops show the most rapid technology adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers in Maharashtra and Gujarat drive premium specialty fertilizer procurement, while Punjab and Haryana field crop producers respond to nutrient-based subsidy recalibration. Karnataka and Telangana digitized platforms are compressing traditional dealer networks.
Maharashtra
Grape and pomegranate export zones in Nashik and Sangli districts demand residue-compliant micronutrient programs for European market access. The state agricultural department's micro-irrigation expansion scheme has achieved critical drip infrastructure density compatible with water-soluble formulations. Cooperative sugarcane processing units in western Maharashtra negotiate direct controlled-release supply contracts with manufacturers.
Gujarat
Cotton and groundnut value chains in Saurashtra and North Gujarat pull fortified and coated urea applications under nutrient-based subsidy reform. The state's horticulture mission promotes protected cultivation infrastructure requiring precision fertigation protocols. Anand and Vadodara industrial corridors host polymer coating technology partnerships addressing domestic resin supply constraints.
Karnataka
Startup-backed agri-input platforms in Bengaluru and Mysuru vegetable belts have achieved critical density, bundling soil-test-linked specialty prescriptions with credit facilities. The state organic farming mission in Kodagu and Chikkamagaluru aligns microbial consortia demand with FSSAI certification requirements. Floriculture export units around Bengaluru utilize chelated micronutrient programs meeting phytosanitary standards.
Punjab
Wheat-rice belt producers respond to soil health card programs identifying zinc and boron deficiencies in intensively cultivated districts. The Department of Fertilisers' subsidy recalibration reduces price gaps against conventional urea in Ludhiana and Amritsar procurement zones. Traditional dealer networks retain loyalty among smallholder producers despite digitized channel encroachment.
Tamil Nadu
Banana operations in Tiruchirappalli and Coimbatore districts adopt sulfur-coated urea to synchronize nutrient release with flowering induction stages. The state's precision agriculture initiative promotes sensor-integrated fertigation systems compatible with controlled-release products. Large horticulture estates in the Cauvery delta negotiate customized manufacturer relationships bypassing cooperative channels.
India Specialty Fertilizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement touchpoints. The market structure shows moderate consolidation around cooperative federations and integrated chemical manufacturers, with regional blenders occupying fragmented niches. Three archetypes dominate: backward-integrated phosphate producers, imported specialty technology licensors, and platform-integrated digital service providers. Competitive moves center on coating chemistry partnerships and soil-testing service bundling.
Among domestic cooperative and private manufacturers, Indian Farmers Fertiliser Cooperative Limited, Coromandel International Ltd, and Chambal Fertilisers & Chemicals Ltd occupy positions spanning commodity scale and value-added formulation capabilities. ICL Group Ltd and Yara International ASA exemplify technology-licensing archetypes importing controlled-release and water-soluble expertise calibrated for tropical conditions. Deepak Fertilisers & Petrochemicals Corporation Ltd and Mangalore Chemicals & Fertilizers Ltd represent regional chemical manufacturers diversifying into micronutrient and fortified grades.
| Leading Market Players |
|---|
| Indian Farmers Fertiliser Cooperative Limited |
| ICL Group Ltd |
| Coromandel International Ltd |
| Haifa Group |
| Yara International ASA |
| Chambal Fertilisers & Chemicals Ltd |
| Mangalore Chemicals & Fertilizers Ltd |
| Fertilisers and Chemicals Travancore Ltd |
| Deepak Fertilisers & Petrochemicals Corporation Ltd |
| Others |
Supply & Pricing Matrix
Polymer resin import dependence from China, South Korea, and the Middle East anchors margin compression risks for domestic controlled-release formulators serving Maharashtra and Gujarat horticulture belts. Coating chemistry inputs represent the dominant cost stack, concentrating pricing power with petrochemical suppliers and forcing downstream manufacturers to absorb forex volatility or pass through via indexed contracts.
Pricing Analysis
Cost-plus contracts with quarterly indexation to Singapore naphtha benchmarks dominate procurement between coating resin suppliers and domestic formulators. Three-tier pricing structure across premium controlled-release, standard fortified grades, and economy bulk urea reflects certification complexity and drip irrigation compatibility. Pricing pressure stems from nutrient-based subsidy recalibration narrowing conventional urea gaps. Smallholder rice-wheat producers in Punjab and Haryana exhibit highest price sensitivity; export-oriented grape and pomegranate estates in Nashik demonstrate lowest.
Supply Chain Analysis
Upstream feedstock sourcing for sulfur-coated urea draws from domestic refinery byproduct streams and imported elemental sulfur from Canada and the Middle East. Polyurethane and polyolefin coating resins hinge on petrochemical imports from China, South Korea, and Saudi Arabia. Single-source vulnerability concentrates in specialty polymer grades lacking domestic production. Distribution runs through state cooperative federations in Maharashtra and Gujarat, agri-input platforms in Karnataka and Telangana, and direct manufacturer relationships with large horticulture estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agronomists capable of translating soil health card data into customized micronutrient prescriptions remain concentrated in public extension services, constraining private sector technical service scaling and creating acquisition premiums for talent-rich regional blenders.
For Market Incumbents: Build technical service moats through captive agronomist training programs and soil-testing laboratory networks. Coromandel International Ltd's backward integration into phosphoric acid production demonstrates upstream margin defense against commodity urea substitution pressure. Prioritize coating chemistry partnerships with Anand and Vadodara industrial corridor polymer suppliers to reduce import exposure. For New Entrants and Emerging Players: Karnataka and Telangana digitized agri-input platforms represent the most penetrable entry point for microbial consortia and biofertilizer categories aligned with FSSAI organic certification demand. Kodagu and Chikkamagaluru organic farming missions offer white-space anchor contracts. Pursue bundling strategies integrating soil-test-linked prescriptions with credit facilities through platform partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-release coating capacity as domestic polymer supply scarcity forces integrated manufacturing investments. Regional micronutrient blenders with BIS pre-certified formulations and established testing partnerships offer viable acquisition profiles. Monitor PLI scheme agrochemical manufacturing disbursement velocity as inflection indicator for specialty grade capital redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphoric Acid | Coromandel International Ltd's captive sulfuric acid production insulates margin against import volatility. |
| Coating Chemistry Partnership | Anand polymer suppliers address domestic resin scarcity constraining controlled-release formulation scale. |
| Soil-Testing Laboratory Network | Extension service capabilities differentiate prescriptions for zinc-deficient Punjab wheat-rice belts. |
| Platform Credit Bundling | Karnataka agri-input startups integrate specialty fertilizer procurement with working capital facilities. |
| BIS Pre-Certification Investment | Batch-level documentation capabilities compress commercialization timelines for new micronutrient grades. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Fertiliser Control Order amendments, Department of Fertilisers subsidy allocation records, and BIS certification databases. Agronomists at state agricultural universities, procurement managers at Maharashtra cooperative federations, coating chemistry specialists at Vadodara industrial partnerships, and horticulture estate managers in Nashik and Sangli districts provided qualitative inputs. Customs trade data on polymer resin imports, SEC filings of listed fertilizer manufacturers, and state micro-irrigation scheme deployment statistics furnished secondary validation. Bottom-up acreage estimates and top-down subsidy flow analysis were cross-referenced for triangulation.
Forecast inputs span product type segmentation across controlled-release, micronutrient, biofertilizer, and organic categories; end-use splits between agriculture, horticulture, landscaping, and forestry; and distribution channel evolution across cooperatives, online platforms, retail stores, and direct sales. CAGRs were derived from slope analysis of subsidy recalibration trajectories and drip irrigation infrastructure deployment curves. Nutrient-based subsidy reform pace and PLI scheme agrochemical manufacturing uptake served as scenario-weighting variables across the projection horizon.
Stress conditions across polymer resin import cost bands, BIS certification timeline extensions, and commodity urea subsidy retention were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding drip irrigation density thresholds and farmer switching elasticity. Cross-checking against state agricultural department micro-irrigation deployment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
GCC Fertilizer Market