
 High-Brix Fruit Quality Enhancement Fertilizer Market | 2026-2036
High-Brix Fruit Quality Enhancement Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
High-Brix Fruit Quality Enhancement Fertilizer Market Insights
China's Shandong Province is reconfiguring regional supply chains for high-Brix fertilizers through expanded blending facilities and controlled-environment agriculture clusters. Yara International leverages its integrated nitrate production network to dominate premium micronutrient delivery systems across East Asian fruit belts. Haifa Group specializes in fully-soluble potassium sources tailored to drip-fertigation protocols in Mediterranean citrus operations. ICL Group anchors its position through captive phosphate reserves and customized chelation technologies for stone fruit producers.
High-Brix fruit quality enhancement fertilizers are formulated inputs designed to elevate soluble solids content—measured in degrees Brix—through targeted delivery of potassium, boron, and trace elements during reproductive growth phases, typically applied via foliar spray or fertigation at concentrations calibrated to cultivar-specific accumulation curves. Their primary commercial purpose is to meet stringent procurement standards from fresh-export and processing channels where sweetness thresholds determine grade premiums and contract eligibility. Micronutrient fertilizers and chelated formulations command the deepest margin pools due to technical barriers in stability and uptake efficiency, while organic amino acids and bio-stimulants represent the fastest-expanding categories as residue-conscious retailers in Europe and Japan impose input restriction protocols. Application segmentation tilts toward grape cultivation and berry production, where per-hectare input values justify precision nutrition investments and sensory quality directly links to varietal pricing tiers.
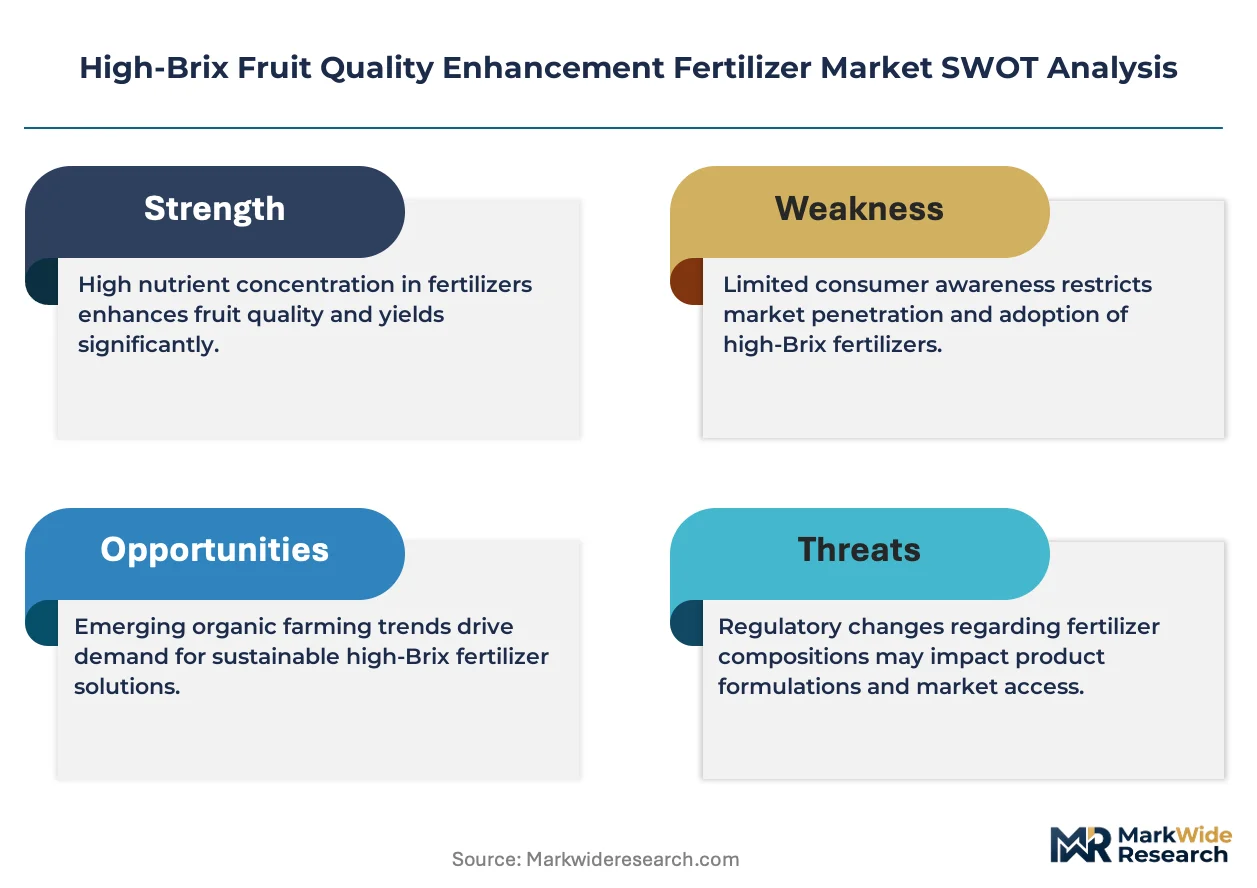
The EU F-Gas Regulation and REACH chemical authorization framework constrain ammonia and nitrous oxide-intensive production pathways, compelling reformulation toward stabilized urea and organic-mineral hybrids. China's Ministry of Ecology and Environment enforces dual carbon goals that tighten energy benchmarks for fertilizer synthesis, while Japan's METI promotes JIS-standardized efficiency metrics for protected horticulture inputs. Stakeholders must monitor divergence between EU Green Deal compliance requirements and emerging Asian carbon accounting rules, as certification asymmetries threaten cross-border product registrations and procurement contract eligibility.
Market Dynamics
The EU F-Gas Regulation and China's dual carbon goals are forcing simultaneous reformulation of ammonia-intensive production pathways, compressing legacy synthesis margins while opening premium positions for stabilized urea and organic-mineral hybrid suppliers.
Growth Catalysts
- Japan's METI Efficiency Standards:JIS-standardized metrics for protected horticulture inputs accelerate precision fertigation adoption among Shizuoka strawberry and Yamanashi grape producers seeking export-grade Brix certification.
- Controlled-Environment Agriculture Clusters:China's Shandong Province expands dedicated blending facilities serving cherry and strawberry operations under film-greenhouse intensification programs.
- Residue Restriction Protocols:European and Japanese retailers impose input restriction mandates that pull amino acid bio-stimulants and chelated micronutrients into premium procurement tiers.
Market Restraints
- Natural Gas Feedstock Volatility:Ammonia synthesis remains tethered to natural gas price swings, exposing nitrate-based fertilizer margins to energy market shocks without hedging mechanisms.
- Phosphate Rock Concentration:Captive phosphate reserves concentrate among integrated mining-chemical conglomerates, limiting independent formulator access to primary phosphorus sources.
- REACH Authorization Friction:ECHA's chemical authorization framework delays novel chelation agent registrations, freezing European market entry for experimental micronutrient carriers.
Strategic Opportunities
- India's Protected Cultivation Expansion:National horticulture missions in Maharashtra and Karnataka underpenetrate high-Brix inputs, creating first-mover positioning for drip-fertigation specialists.
- Carbon Border Adjustment Mechanisms:EU Green Deal compliance requirements generate certification premiums for low-emission fertilizer producers serving Dutch and Spanish export-oriented fruit cooperatives.
- Sensor-Fertigation Convergence:Integration of soil-moisture sensing with variable-rate injection equipment enables real-time Brix optimization protocols in Israeli and Australian desert agriculture.
Industry Challenges
- Formulation Chemistry Expertise Gap:Chelate stability engineering and cultivar-specific accumulation curve calibration require specialized agronomic-chemical hybrid skill sets scarce in regional distribution networks.
- Dual Certification Timelines:Concurrent EU organic certification and national residue-limit approvals extend product launch cycles by 18-24 months for bio-stimulant entrants.
- Legacy Fertigation Infrastructure Retrofit Costs:Converting flood-irrigated orchards to drip systems demands capital-intensive emitter and filtration installations that strain smallholder financing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Brix Fruit Quality Enhancement Fertilizer Market |
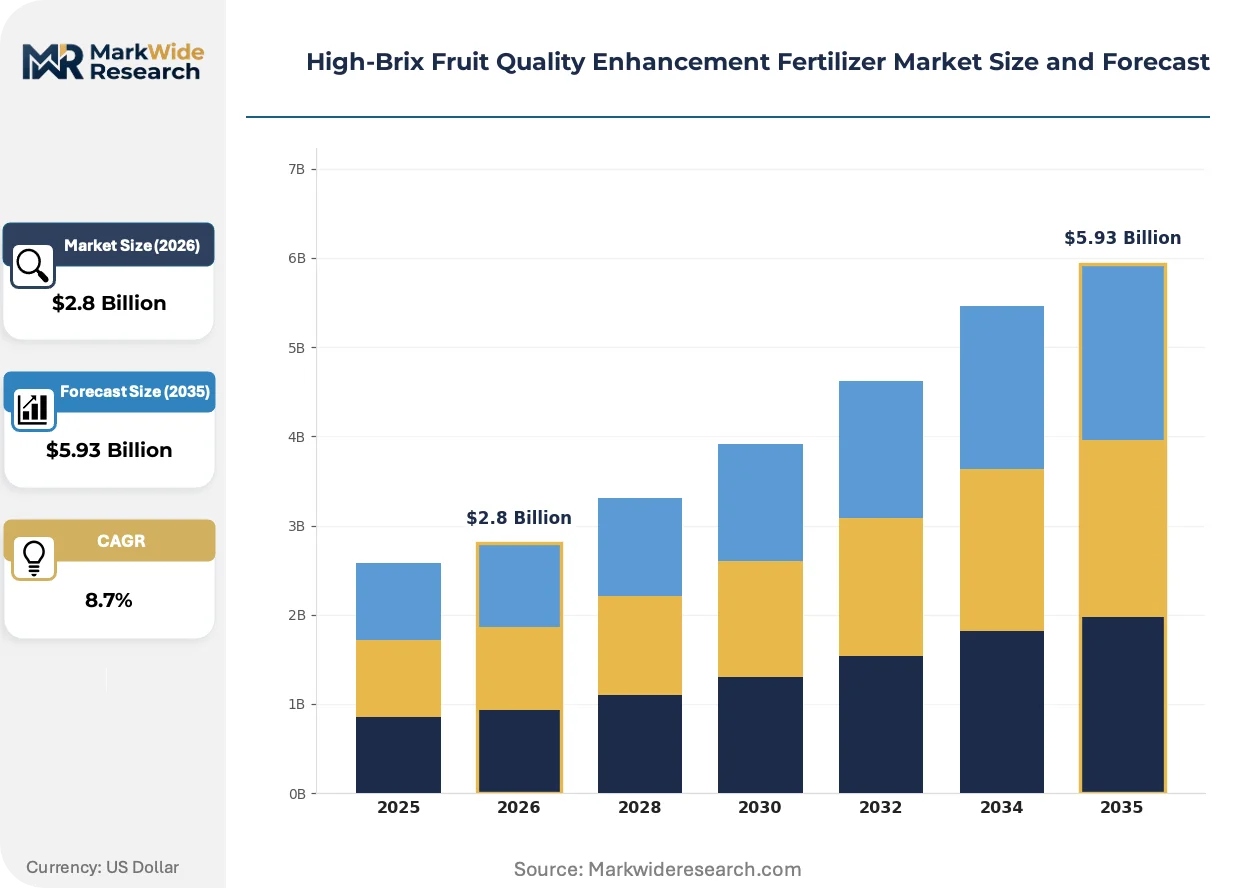
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micronutrient Fertilizers, Organic Amino Acids, Humic Substances, Chelated Fertilizers, Bio-Stimulants Application: Grape Cultivation, Citrus Farming, Apple Orchards, Berry Production, Tropical Fruit Growing Crop Stage: Pre-Bloom, Fruit Set, Ripening, Post-Harvest Distribution Channel: Agri Retail Outlets, Online Marketplaces, Cooperative Stores, Direct Sales, Agricultural Wholesalers |
| Companies Covered | Yara International, Haifa Group, ICL Group, COMPO EXPERT, SQM, K+S, Syngenta Biologicals, Fertinagro Biotech, Uralchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Brix Fruit Quality Enhancement Fertilizer Market Trends and Innovations
Precision delivery technologies and residue-conscious input protocols are restructuring competitive advantage around real-time agronomic data integration rather than bulk commodity scale.
Controlled-release potassium nitrate formulations with polymer-coated granules are collapsing the distinction between single-application basal dressing and multi-split fertigation protocols. Mediterranean citrus cooperatives in Spain and Italy adopt these materials to reduce labor costs during peak flowering windows. The technology is collapsing seasonal input application schedules into compressed pre-bloom interventions that match mechanized harvesting logistics.
REACH chemical authorization and the EU F-Gas Regulation jointly restrict ammonia-based nitrogen production pathways. Manufacturers reformulate toward stabilized urea and organic-mineral hybrids to maintain European market access. Specialty micronutrient blenders in the Netherlands and Belgium redirect R&D expenditure toward low-emission synthesis verification to secure retailer procurement contracts.
Fresh-export channels in Japan and South Korea now mandate third-party Brix certification with chain-of-custody documentation. Procurement teams at Tokyo and Seoul wholesale markets reject uncertified lots regardless of visual grade. This behavioral shift concentrates supplier relationships among integrated formulators offering bundled testing and input packages rather than standalone fertilizer transactions.
High-Brix Fruit Quality Enhancement Fertilizer Market Segmentation
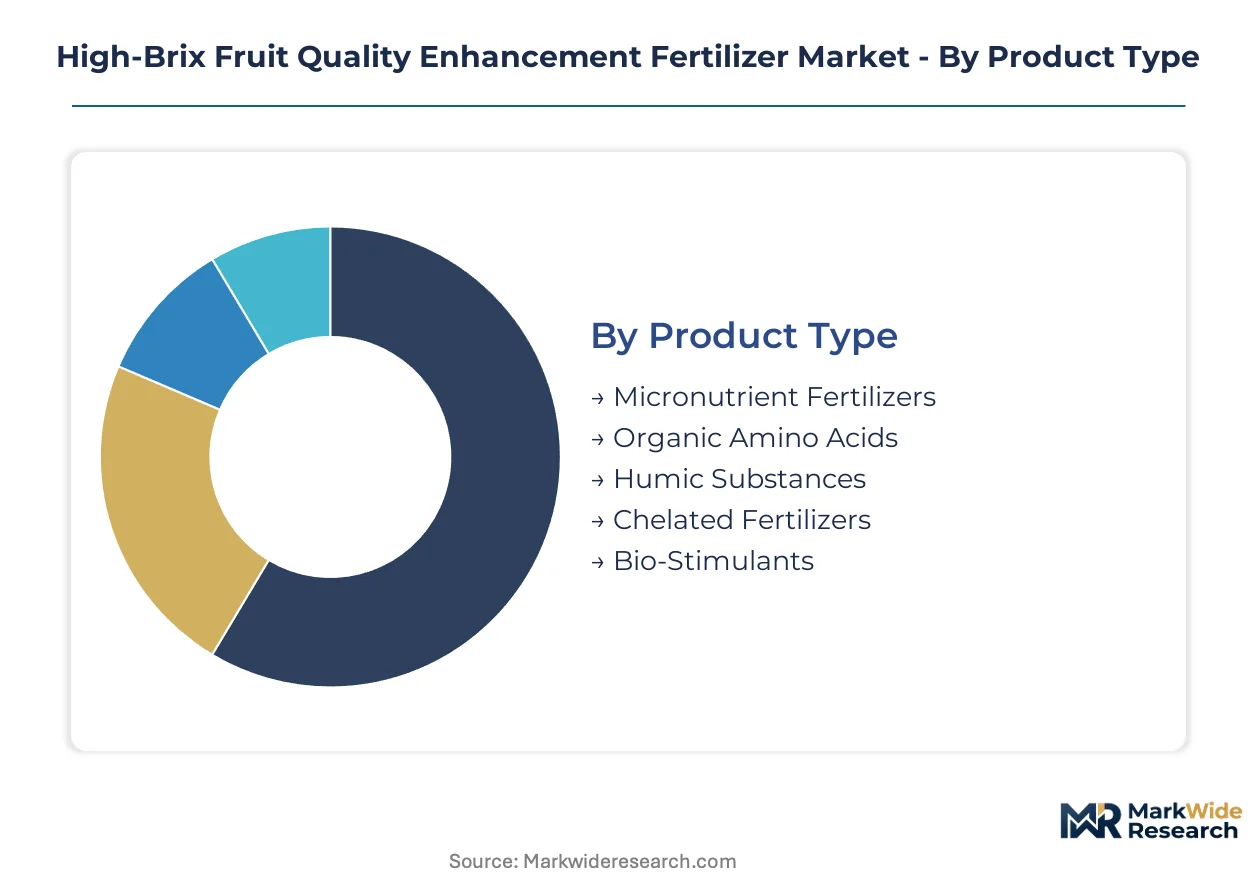
High-Brix fertilizer markets fragment sharply across product chemistry and crop specificity. Procurement patterns diverge between commodity-scale orchards and precision-driven protected cultivation operations. Understanding these fault lines clarifies where formulation premiums materialize versus where bulk pricing dominates.
Product Type:
Cost tier stratification separates commodity macronutrient blends from precision micronutrient systems commanding formulation premiums.
- Micronutrient Fertilizers:These inputs deliver boron, zinc, and manganese in soluble forms calibrated to cultivar-specific accumulation curves. Japan's METI efficiency standards pull these materials into Shizuoka strawberry operations seeking export-grade Brix certification.
- Chelated Fertilizers:Organic ligand-bound metal ions resist soil fixation and improve foliar uptake efficiency. Mediterranean citrus cooperatives in Spain adopt these for drip-fertigation protocols where water quality variability threatens nutrient availability.
- Organic Amino Acids:Protein-derived biostimulants enhance stress tolerance and sugar translocation.
- Humic Substances:Soil organic matter extracts improve cation exchange capacity and root zone buffering.
- Bio-Stimulants:Microbial and seaweed-derived formulations accelerate metabolic pathways during ripening phases.
Micronutrient fertilizers command the established base. The steepest expansion runs through bio-stimulants.
Application:
Application segmentation tracks where per-hectare input values justify precision nutrition investments and sensory quality directly links to varietal pricing tiers.
- Grape Cultivation:Table grape operations in Yamanashi Prefecture and California's Central Valley deploy intensive foliar programs during veraison. Procurement teams at Tokyo wholesale markets mandate third-party Brix certification with chain-of-custody documentation.
- Berry Production:Protected strawberry cultivation in China's Shandong Province drives fertigation adoption under film-greenhouse intensification programs. Dual carbon enforcement from China's MEE tightens energy benchmarks for synthesis inputs serving these clusters.
- Citrus Farming:Mediterranean cooperatives mechanize harvesting logistics around compressed pre-bloom intervention schedules.
- Apple Orchards:Washington State and Himachal Pradesh operations focus on color development and storage sugar retention.
- Tropical Fruit Growing:Mango and lychee producers in Maharashtra and Karnataka underpenetrate high-Brix inputs.
Grape cultivation anchors revenue concentration. Berry production is climbing the fastest.
Crop Stage:
Timing protocols determine whether inputs integrate into basal soil applications or shift toward precision foliar interventions.
- Ripening:Sugar accumulation phases demand potassium-dominant formulations with controlled-release nitrogen avoidance. Polymer-coated potassium nitrate granules collapse multi-split schedules into single pre-bloom interventions matching mechanized logistics.
- Fruit Set:Cell division windows require balanced micronutrient availability without vegetative growth stimulation.
- Pre-Bloom:Flower bud differentiation stages establish yield potential and initial sugar sink capacity.
- Post-Harvest:Reserve carbohydrate replenishment in perennial systems influences subsequent season performance.
Ripening-stage inputs capture premium pricing. Fruit set applications are gaining share fastest.
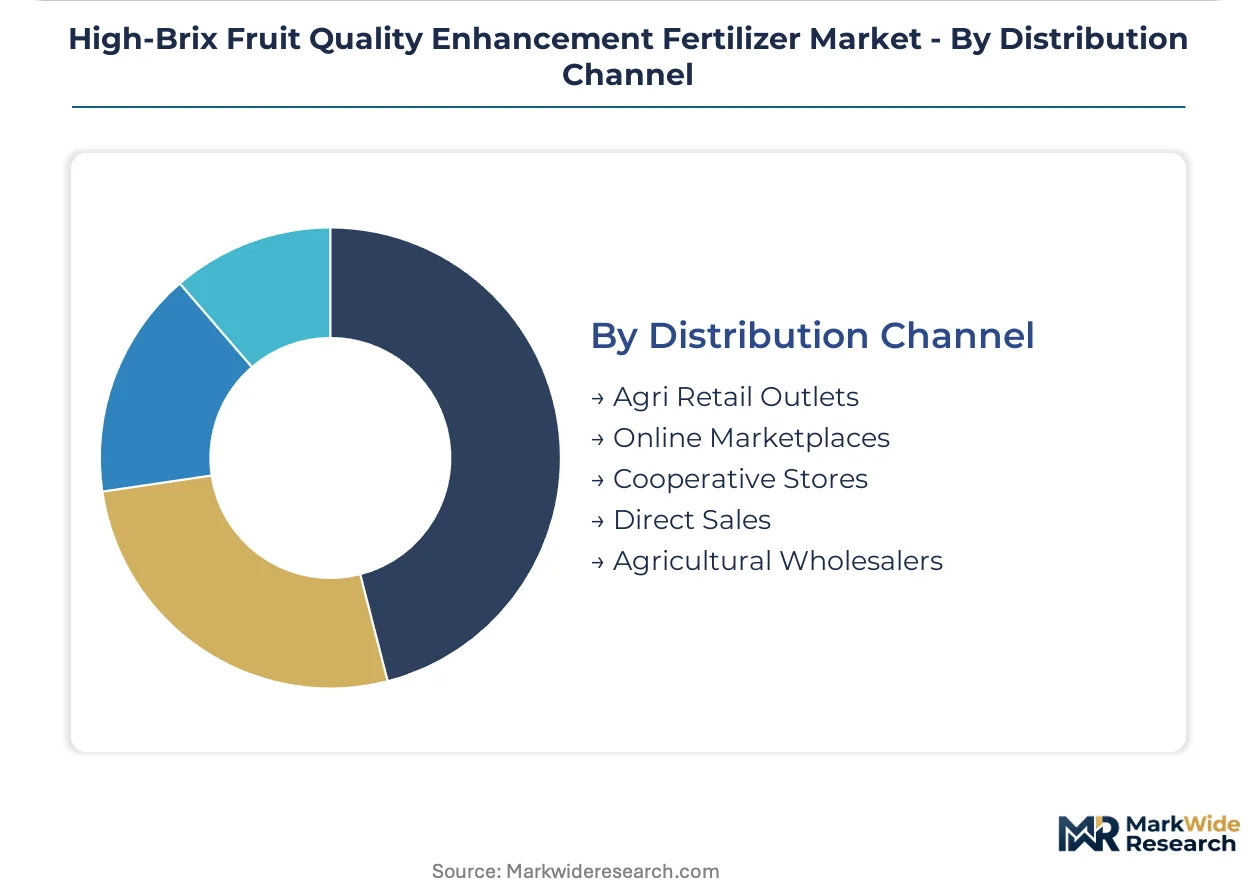
Distribution Channel:
Channel structure reflects capital intensity of customer relationships and technical service requirements.
- Direct Sales:Integrated formulators bundle testing protocols and input packages for Japanese and South Korean fresh-export channels. Procurement teams reject uncertified lots regardless of visual grade.
- Agri Retail Outlets:Independent stores serve smallholder citrus and apple operations with standardized blends.
- Agricultural Wholesalers:Volume distributors aggregate demand across commodity-scale orchards.
- Cooperative Stores:Member-owned outlets dominate Spanish and Italian citrus cooperative procurement.
- Online Marketplaces:Digital platforms penetrate price-transparent commodity segments.
Direct sales command margin premiums. Online marketplaces are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Japanese growers prioritize export-certification inputs, European operators reformulate around emissions compliance, and Chinese clusters scale protected-cultivation intensification.
China
Shandong Province drives demand through film-greenhouse cherry and strawberry operations. The Ministry of Ecology and Environment enforces dual carbon goals tightening energy benchmarks for fertilizer synthesis. Qingdao and Yantai host expanded blending facilities serving controlled-environment agriculture clusters under provincial intensification programs.
Japan
Yamanashi grape and Shizuoka strawberry producers seek METI-standardized efficiency metrics for export-grade Brix certification. METI promotes JIS-standardized protocols for protected horticulture inputs. Tokyo wholesale market procurement teams mandate third-party certification with chain-of-custody documentation, rejecting uncertified lots regardless of visual grade.
Spain
Mediterranean citrus cooperatives adopt compressed pre-bloom intervention schedules matching mechanized harvesting logistics. The EU F-Gas Regulation and REACH framework restrict ammonia-intensive production pathways. Valencia and Murcia host reformulation activity toward stabilized urea and organic-mineral hybrids to maintain retailer procurement contracts.
Netherlands
Specialty micronutrient blenders redirect R&D expenditure toward low-emission synthesis verification. ECHA's chemical authorization framework delays novel chelation agent registrations. The Dutch-Belgian border region concentrates expertise in chelate stability engineering for drip-fertigation protocols serving export-oriented fruit cooperatives.
India
Maharashtra and Karnataka underpenetrate high-Brix inputs despite national horticulture mission expansion. BIS standards govern fertilizer quality specifications. Nashik grape belts and Bengaluru strawberry clusters present first-mover positioning for drip-fertigation specialists targeting protected cultivation growth.
High-Brix Fruit Quality Enhancement Fertilizer Market Competitive Landscape
Capability concentration sits with integrated nitrate and phosphate producers; scale advantage sits with regional blenders serving commodity orchards. The structure tilts toward tiered specialization rather than consolidation. Three archetypes dominate: captive-reserve miners, fully-soluble formulation specialists, and bio-stimulant innovators. M&A activity targets micronutrient technology access, while capacity expansion concentrates in Chinese blending corridors.
Among European-integrated chemical conglomerates, Yara International and ICL Group exemplify the captive-reserve archetype through upstream control over nitrate and phosphate supply chains. Haifa Group occupies a position within the fully-soluble specialization tier. These three anchors represent divergent strategic postures: mineral integration versus precision formulation versus regional blending scale.
| Leading Market Players |
|---|
| Yara International |
| Haifa Group |
| ICL Group |
| COMPO EXPERT |
| SQM |
| K+S |
| Syngenta Biologicals |
| Fertinagro Biotech |
| Uralchem |
| Others |
Pricing and Supply Chain Analysis
Captive phosphate reserves in Morocco and Jordan concentrate upstream phosphorus supply, directing margin pools toward integrated mining-chemical conglomerates with in-house chelation capabilities while independent formulators absorb feedstock volatility through contract pass-through clauses.
Pricing Analysis
Long-term offtake agreements dominate procurement between Japanese fresh-export cooperatives and integrated formulators, locking in volume commitments against spot-market ammonium nitrate volatility. Three-tier pricing structure across premium chelated micronutrients, standard soluble blends, and economy bulk NPK separates certification-grade exporters from domestic-channel suppliers. Cost compression in stabilized urea formulations is intensifying because EU F-Gas Regulation compliance adds synthesis verification overhead. Smallholder citrus operators in Mediterranean cooperatives exhibit highest price sensitivity, while Tokyo wholesale market procurement teams prioritize chain-of-custody documentation over unit cost.
Supply Chain Analysis
Natural gas feedstock draws from Qatar, Russia, and the United States anchors ammonia synthesis pathways for nitrate-based fertilizers serving East Asian fruit belts. Potassium chloride sources from Belarus and Canada, phosphate rock from Morocco, and boron from Turkey constitute critical input dependencies. Single-source vulnerability concentrates in Moroccan phosphate rock exports subject to export quota fluctuations. Distribution runs through cooperative-owned outlets in Spanish and Italian citrus regions, direct sales teams for Japanese export-certification channels, and agri-retail networks for Chinese Shandong greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against biological bio-stimulant alternatives that bypass synthetic fertilizer regulatory exposure while capturing residue-conscious retailer procurement mandates.
For Market Incumbents: Entrench backward integration into captive nitrate production networks to defend margin position against natural gas feedstock volatility. Secure dual organic-mineral certification under EU Green Deal and Japan's JIS standards to preempt bio-stimulant substitution in premium export channels. Capacity expansion in Qingdao and Yantai blending corridors locks in Shandong Province greenhouse cluster demand. For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra grape belts and Karnataka strawberry clusters where national horticulture mission expansion underpenetrates high-Brix precision inputs. Target drip-fertigation retrofit financing partnerships with regional agricultural banks to overcome smallholder capital constraints. Lead with sensor-integrated variable-rate injection equipment bundled with cultivar-specific accumulation curve protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chelated micronutrient synthesis as REACH authorization timelines extend R&D amortization periods. Acquisition targets with validated low-emission production pathways and existing EU retailer procurement contracts offer defensive positioning through regulatory compliance premiums. Monitor divergence between EU carbon border adjustment implementation and Asian carbon accounting standardization as inflection signal for cross-border product registration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Phosphate Reserves | Secures primary phosphorus access against Moroccan export quota volatility for integrated formulators. |
| Dual Certification Investment | Accelerates EU organic and JIS-standardized approval timelines for bio-stimulant entrants targeting Japanese export channels. |
| Sensor-Fertigation Platform Development | Enables real-time Brix optimization in Israeli and Australian desert agriculture through soil-moisture convergence. |
| Regional Blending Facility Expansion | Captures Shandong Province greenhouse cluster demand under China's dual carbon enforcement tightening synthesis benchmarks. |
| Long-term Supply Agreement Structuring | Hedges natural gas feedstock exposure for nitrate-based fertilizer margins through Qatar and US offtake contracts. |
Research Methodology
A standing panel of fertilizer plant managers, downstream fruit cooperative procurement leads, drip-fertigation equipment distributors, and technical R&D directors at chelation specialists provided ongoing calibration against customs and trade data, SEC 10-K filings, EU ECHA authorization registers, and Japanese METI efficiency standard documentation. Primary interviews with stakeholders across Moroccan phosphate mining operations, Dutch-Belgian micronutrient blenders, and Chinese Shandong greenhouse operators combined with secondary validation through bottom-up cultivation-area modeling and top-down chemical consumption triangulation.
Scenario-bracketing framed analytical approach across the analysis window, modeling low-emission synthesis adoption curves, natural gas price volatility bands, and regulatory authorization delay distributions. Segmentation dimensions included product chemistry tier, crop-specific application protocol, distribution channel structure, and regional regulatory cluster intensity. CAGRs derived from cultivation area expansion rates multiplied by per-hectare input value intensification, cross-referenced against fertilizer industry association capacity utilization disclosures and energy benchmark enforcement trajectories.
Stress conditions across ammonia feedstock price spikes, REACH authorization timeline extensions, and carbon border adjustment mechanism implementation pacing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dual carbon goal enforcement intensity in China and EU F-Gas Regulation reformulation compliance costs. Cross-checking against FAO fertilizer consumption statistics and national horticulture mission budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Russia Fertilizers Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market