
 Saudi Arabia Greenhouse Horticulture Market | 2026-2036
Saudi Arabia Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Greenhouse Horticulture Market Insights
SASO greenhouse construction certification is redrawing competitive entry barriers for controlled-environment agriculture suppliers in the Kingdom. Pure Harvest Smart Farms leverages integrated hydroponic systems to sustain year-round tomato production across its Riyadh-area facilities. Red Sea Global anchors its position through tourism-anchored agritourism complexes that merge food production with hospitality destination development. Nole Agriculture differentiates via specialized pepper cultivation protocols optimized for Saudi climatic stress conditions.
Greenhouse horticulture encompasses the cultivation of vegetables and leafy crops within structurally enclosed environments where temperature, humidity, light, and irrigation parameters are actively managed through climate control systems and soilless substrate technologies. The primary purpose centers on decoupling agricultural output from arid-zone environmental constraints to achieve predictable yields for domestic food security. Hydroponics technology leads installed capacity due to established operator familiarity and lower capital thresholds versus aeroponics systems. Tomato production occupies the dominant product category, reflecting aligned consumer dietary patterns and established wholesale distributor offtake agreements. Vertical farming represents the fastest-growing technology segment as urban proximity requirements intensify among Riyadh and Jeddah supermarket chains.
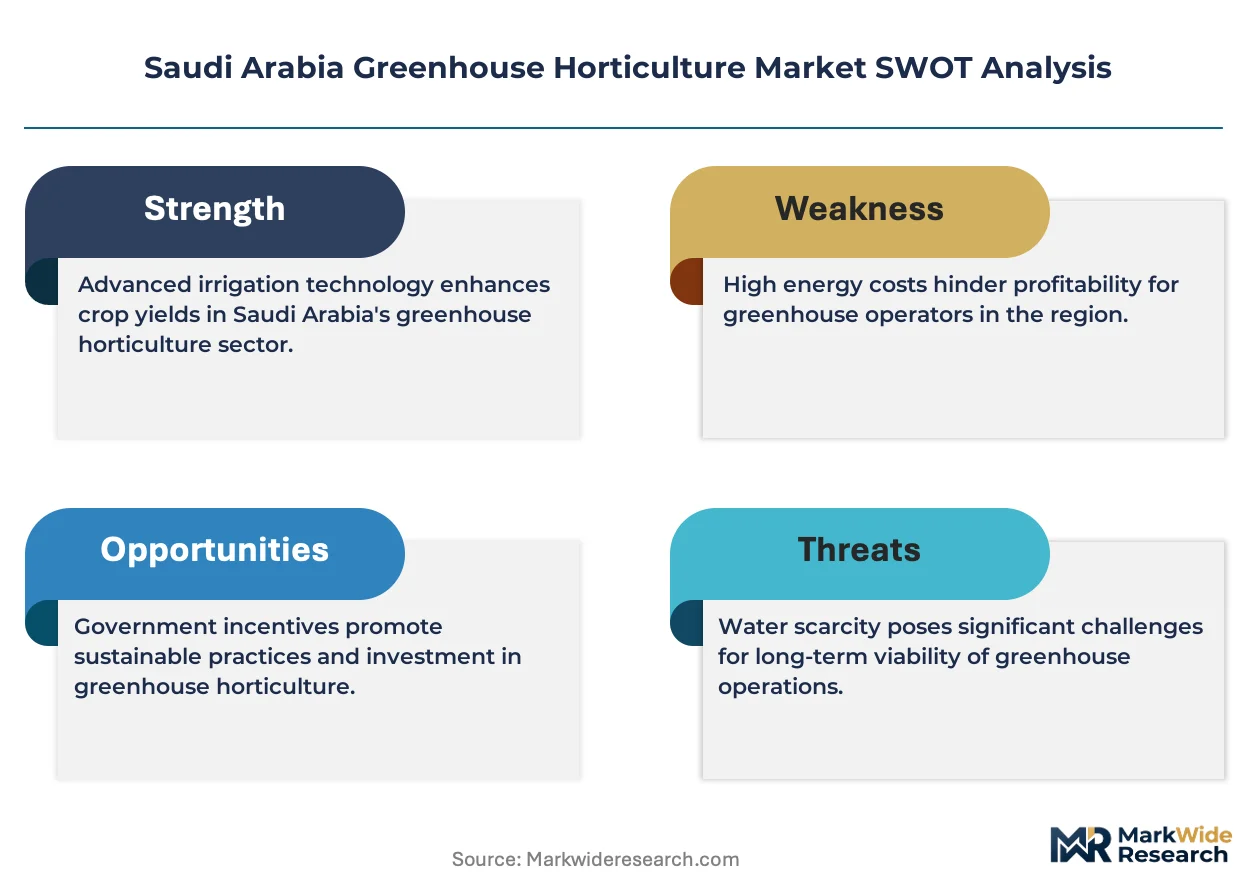
SFDA food safety mandates and SASO structural standards jointly determine which greenhouse operators qualify for domestic retail channel access, with non-compliant facilities restricted to informal farmer's markets. The Ministry of Environment, Water and Agriculture enforces water-use efficiency quotas that directly shape irrigation technology selection across Neom and Qassim developments. Stakeholders must monitor evolving subsidy eligibility tied to renewable energy integration in controlled-environment facilities.
Market Dynamics
SFDA food safety mandates and SASO structural certification requirements are compressing market access into compliant controlled-environment facilities, forcing capital reallocation toward climate-controlled infrastructure that satisfies retail channel entry standards.
Growth Catalysts
- Riyadh-Qassim corridor logistics:Just-in-time vegetable delivery networks enable supermarket chains to reduce post-harvest loss and expand local sourcing programs for fresh produce.
- SFDA import substitution protocols:Tightening food safety standards redirect procurement toward domestic greenhouse operators who achieve facility certification.
- Neom renewable energy integration:Subsidy eligibility tied to solar-powered controlled-environment agriculture attracts development capital toward sustainable irrigation systems.
Market Restraints
- Desalinated water cost volatility:Ministry of Environment water-use efficiency quotas intensify input cost pressure on hydroponic and aeroponic system operators.
- Import equipment dependency:Climate control hardware and LED grow-light systems concentrate sourcing from East Asian manufacturing clusters, exposing operators to shipping cost fluctuations.
- Aeroponics technical complexity:Higher capital thresholds and operator unfamiliarity restrict adoption versus established hydroponics infrastructure.
Strategic Opportunities
- Jeddah urban vertical farming:Proximity requirements from supermarket chains create demand for rooftop and warehouse-based controlled-environment facilities in dense coastal zones.
- Qassim pepper specialization:Climatic stress-optimized cultivation protocols enable differentiated product positioning in domestic wholesale channels.
- Agritourism convergence:Red Sea coastal development zones merge food production with hospitality infrastructure, creating dual-revenue greenhouse operations.
Industry Challenges
- Controlled-environment agriculture technician scarcity:Specialized skill requirements for climate system management and nutrient solution calibration outpace vocational training program output.
- SASO certification timeline compression:Structural and food safety compliance documentation creates facility commissioning delays that postpone revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Greenhouse Horticulture Market |
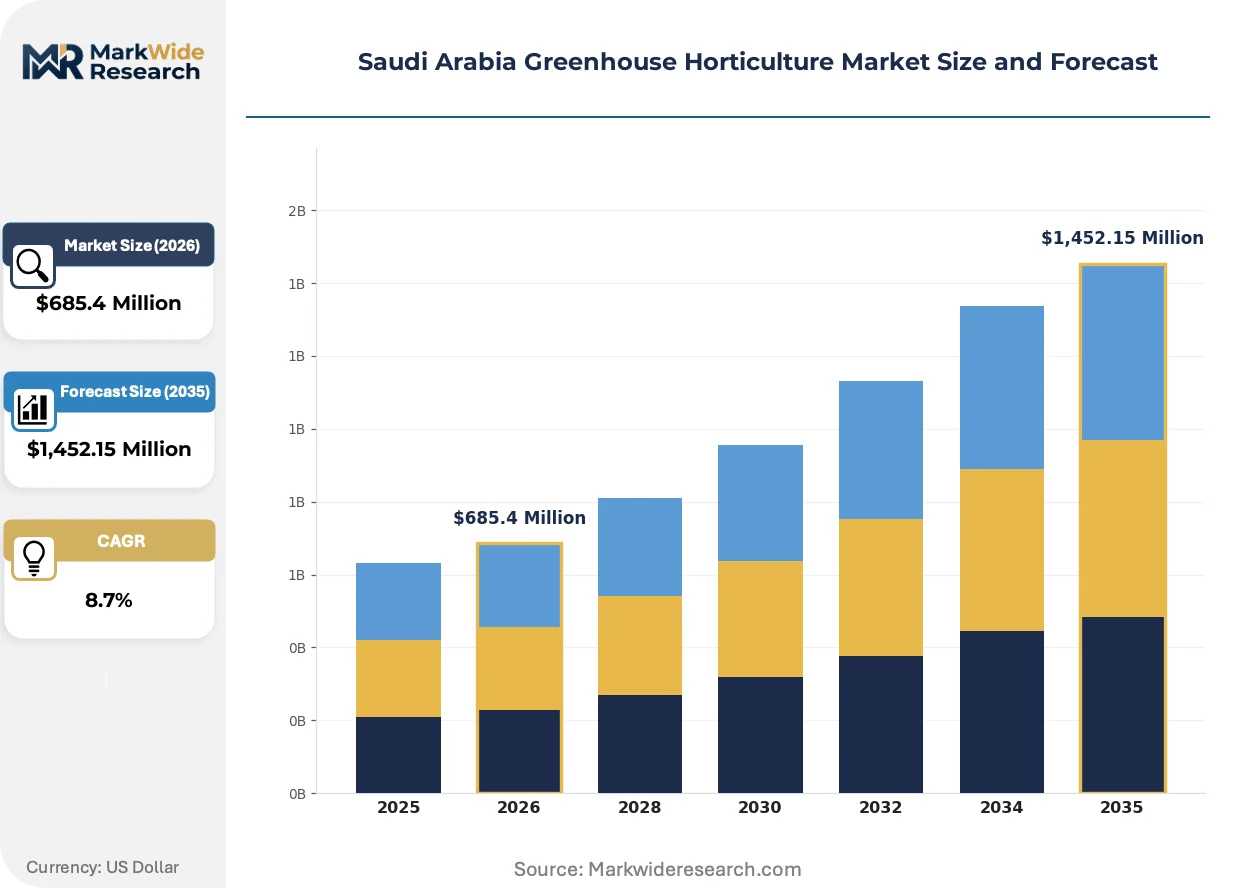
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomatoes, Peppers, Cucumbers, Lettuce Technology: Hydroponics, Aeroponics, Soil-based, Vertical Farming End User: Wholesale Distributors, Supermarkets, Restaurants, Home Gardeners Distribution Channel: Online Retail, Direct Sales, Farmer's Markets, Grocery Stores |
| Companies Covered | Pure Harvest Smart Farms, Red Sea Global, Nole Agriculture, Mowreq, Mishkat, AeroFarms, Topian, iFarm, Blue Fields Farms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Greenhouse Horticulture Market Trends and Innovations
Technology convergence between renewable energy systems and precision agriculture hardware is reconfiguring capital deployment patterns across Saudi controlled-environment facilities. Three developments are compressing operational cost structures and reshaping competitive entry requirements.
LED supplemental lighting technology is miniaturizing fixture form factors while increasing photosynthetic photon flux density. Riyadh-area tomato producers are retrofitting existing greenhouse bays with modular LED arrays that reduce HVAC load. The technology is miniaturizing climate control footprints, enabling higher-density cultivation layouts within fixed structural envelopes.
SFDA traceability mandates now require blockchain-enabled supply chain documentation for retail channel access. Greenhouse operators must deploy sensor-to-shelf tracking infrastructure that captures temperature, humidity, and handling data. Facilities in the Riyadh-Qassim corridor are prioritizing integrated farm management software to satisfy distributor audit requirements.
Supermarket procurement consolidation is compressing supplier qualification cycles. Domestic retail chains now mandate year-round volume commitments and just-in-time delivery windows that informal farmer's market channels cannot satisfy. This behavioral shift concentrates offtake agreements among SASO-certified facilities with integrated cold-chain logistics.
Saudi Arabia Greenhouse Horticulture Market Segmentation
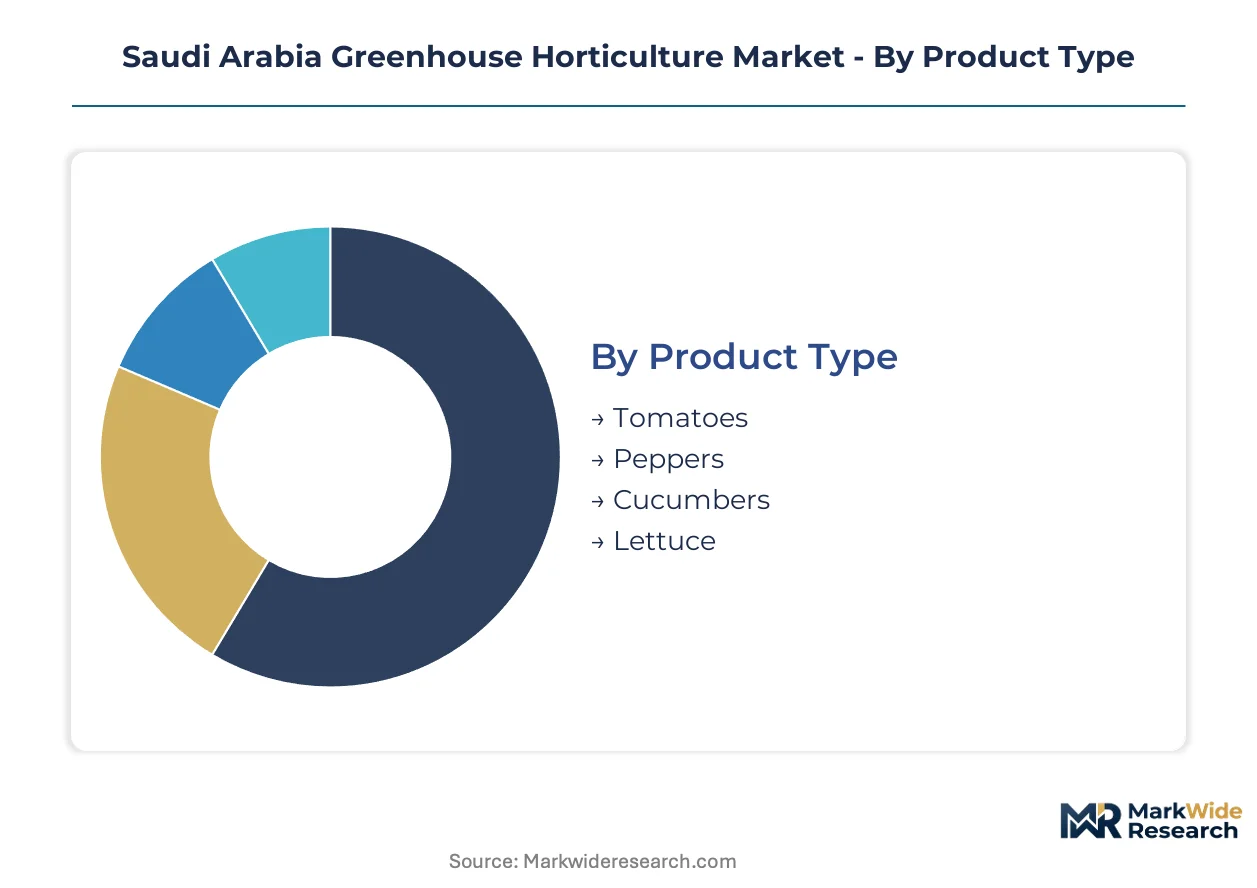
Channel access in Saudi Arabia's controlled-environment agriculture sector hinges on certification status. SFDA-compliant facilities supply supermarkets and wholesale distributors, while uncertified operators remain confined to informal channels. Technology and product choices cascade from these channel requirements.
Product Type:
Supermarket procurement concentrates on shelf-stable vegetables with established cold-chain protocols, while restaurants prioritize flavor-forward varieties with shorter harvest windows.
- Tomatoes:Vine-ripened and cherry varieties dominate Riyadh-Qassim corridor offtake agreements. Pure Harvest Smart Farms anchors year-round supply contracts with Carrefour and Tamimi through integrated hydroponic systems that satisfy just-in-time delivery windows.
- Peppers:Bell and chili cultivars require precise humidity control to prevent blossom-end rot in Saudi climatic stress conditions. Nole Agriculture specializes in stress-optimized protocols that differentiate its Qassim facility output in domestic wholesale channels.
- Cucumbers:English and Persian varieties serve restaurant prep kitchens through direct sales arrangements with Jeddah hospitality clusters.
- Lettuce:Leafy greens concentrate in vertical farming facilities near urban consumption centers, with Riyadh rooftop operations supplying same-day harvest-to-shelf programs.
Tomatoes dominate installed base. Lettuce is where expansion concentrates.
Technology:
Capital intensity and water-use efficiency quotas from the Ministry of Environment, Water and Agriculture determine technology selection across Neom and Qassim developments.
- Hydroponics:Nutrient film technique and deep water culture systems account for the majority of installed greenhouse capacity due to established operator familiarity and lower capital thresholds. Riyadh-area tomato producers favor these systems for their predictable yield profiles and compatibility with existing technician training programs.
- Aeroponics:Mist-based root delivery achieves superior water-use efficiency but demands precise pressure calibration and backup power systems. Higher technical complexity restricts adoption to Neom developments with integrated renewable energy infrastructure and specialized maintenance contracts.
- Soil-based:Traditional substrate cultivation persists in Qassim facilities serving informal farmer's market channels that bypass SASO certification requirements.
- Vertical Farming:Stacked cultivation layers with LED supplemental lighting enable urban proximity production. Jeddah supermarket chains drive demand for warehouse-based and rooftop facilities that compress harvest-to-shelf timelines.
Hydroponics anchors current capacity. Vertical farming is climbing the fastest.
End User:
Volume concentration and certification requirements split the customer base between formal retail channels and informal direct sales.
- Wholesale Distributors:Aggregators in the Riyadh-Qassim corridor consolidate output from multiple SASO-certified facilities to satisfy supermarket chain volume commitments. These intermediaries bear cold-chain logistics investment and SFDA traceability documentation burdens.
- Supermarkets:Carrefour, Tamimi, and Panda mandate year-round supply contracts with blockchain-enabled provenance tracking. Their procurement consolidation compresses supplier qualification to facilities with integrated farm management software.
- Restaurants:Jeddah and Riyadh hospitality clusters source specialty varieties through direct sales arrangements that prioritize flavor profiles over shelf stability.
- Home Gardeners:Small-scale hydroponic kit sales serve expatriate compounds and affluent residential compounds in Riyadh's northern districts.
Wholesale distributors intermediate the largest volume flows. Supermarkets are where contract terms are tightening fastest.
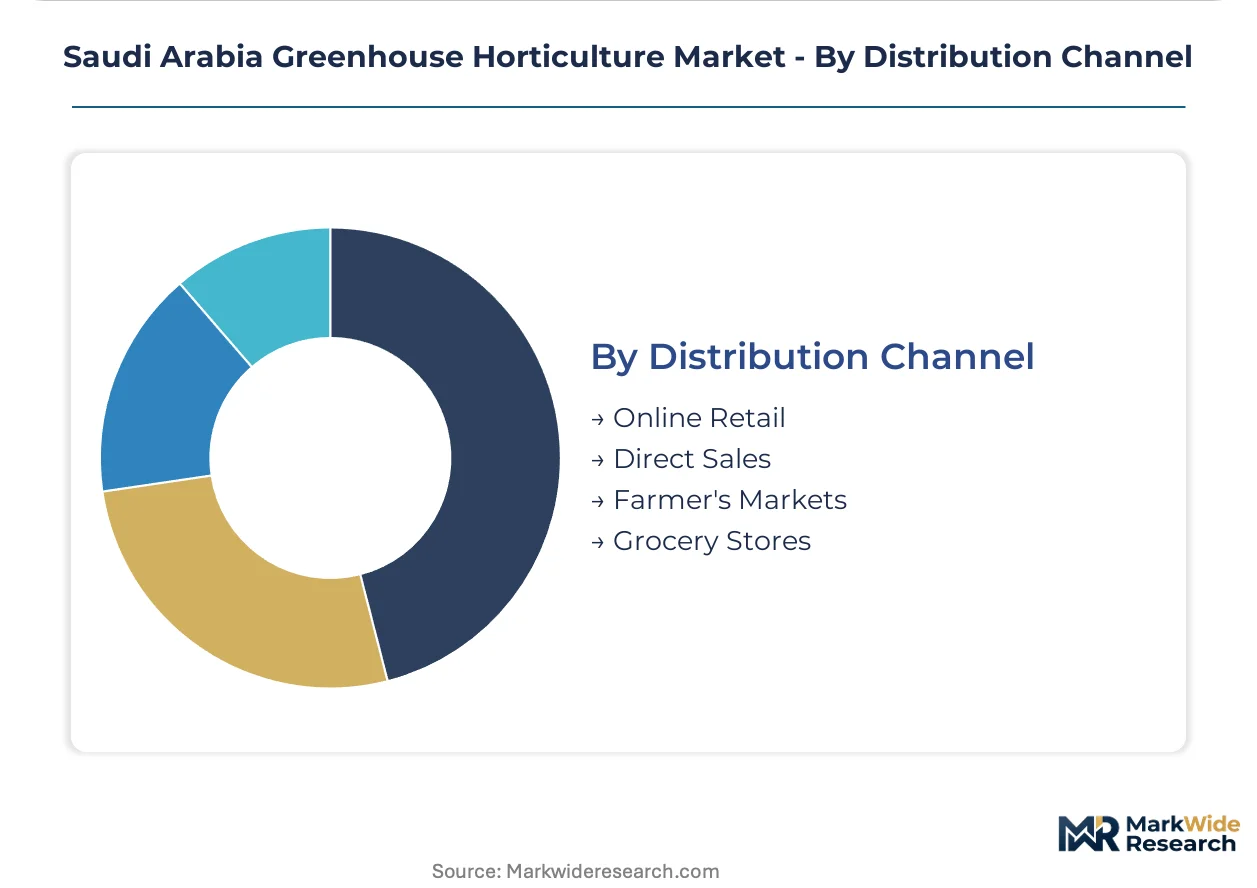
Distribution Channel:
Certification status and cold-chain capability determine channel eligibility, with SASO-compliant facilities accessing premium retail positioning.
- Online Retail:Same-day delivery platforms like Noon and Amazon.sa aggregate output from certified facilities for affluent Riyadh and Jeddah households. These channels demand individual unit packaging and temperature-controlled last-mile logistics.
- Direct Sales:Restaurant contracts and corporate catering arrangements bypass intermediary margins. Red Sea Global's agritourism complexes monetize direct-to-consumer sales as hospitality experience components.
- Farmer's Markets:Uncertified Qassim and Asir facilities serve price-sensitive consumers with seasonal output that lacks SFDA documentation. These channels absorb surplus production rejected by formal retail for cosmetic defects.
- Grocery Stores:Neighborhood bakalas and smaller supermarket formats stock limited SKUs with shorter freshness windows, sourcing through wholesale distributors rather than direct farm relationships.
Grocery stores anchor mass-market penetration. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement teams and wholesale distributors dominate buyer archetypes across Saudi Arabia's controlled-environment agriculture sector, with channel access hinging on SASO certification status and cold-chain logistics capability.
Riyadh
Capital region demand concentrates around just-in-time vegetable delivery networks serving Carrefour and Tamimi expansion programs. SFDA food safety mandates compress supplier qualification timelines for retail channel entry. Al-Kharj industrial corridor hosts Pure Harvest Smart Farms facilities that anchor year-round tomato supply contracts through integrated hydroponic systems.
Eastern Province
Dammam and Khobar hospitality clusters drive specialty pepper and lettuce procurement for restaurant prep kitchens with compressed harvest-to-plate requirements. Ministry of Environment water-use efficiency quotas shape irrigation technology selection across new developments. Jubail industrial zone proximity enables equipment servicing infrastructure for climate control hardware maintenance.
Western Region
Jeddah supermarket chains prioritize urban vertical farming proximity for same-day harvest-to-shelf programs targeting affluent coastal households. SASO structural certification requirements filter rooftop and warehouse facility eligibility for formal retail channel access. Makkah corridor logistics infrastructure supports produce distribution to hospitality venues serving religious tourism flows.
NEOM Northwest
Renewable energy integration subsidies attract development capital toward solar-powered controlled-environment agriculture in the giga-project zone. Neom's regulatory sandbox enables aeroponics pilot deployments that exceed standard Ministry water efficiency quotas elsewhere. Trojena and Oxagon clusters position greenhouse operations within tourism-anchored agritourism complexes merging food production with destination hospitality.
Qassim
Central province climatic stress conditions favor pepper specialization protocols optimized for high-temperature cultivation environments. Wholesale distributor concentration in Buraydah consolidates output from multiple SASO-certified facilities for supermarket chain volume commitments. Regional vocational training institutes struggle to match technician output demands for climate system management roles.
Saudi Arabia Greenhouse Horticulture Market Competitive Landscape
Player mix skews toward integrated facility operators with captive supply relationships to retail chains, creating a tiered structure where certification status determines channel access. Strategic archetypes include technology-integrated pure-play greenhouse operators, tourism-hospitality conglomerates with agritourism divisions, and specialized crop protocol developers. Competitive moves concentrate on SASO certification acquisition and renewable energy integration for subsidy eligibility.
Among Riyadh-based integrated operators, Pure Harvest Smart Farms exemplifies the technology-forward archetype through its hydroponic facility network. Red Sea Global occupies a position within tourism-anchored development, representing the hospitality-convergence model merging production with destination infrastructure. Nole Agriculture sits within the specialization tier, anchoring crop-specific protocol development for climatic stress conditions.
| Leading Market Players |
|---|
| Pure Harvest Smart Farms |
| Red Sea Global |
| Nole Agriculture |
| Mowreq |
| Mishkat |
| AeroFarms |
| Topian |
| iFarm |
| Blue Fields Farms |
| Others |
Pricing and Supply Chain Analysis
SFDA food safety certification gates both supply qualification and price differentiation across Saudi Arabia's controlled-environment agriculture sector, compressing retail channel access to SASO-compliant facilities that command premium positioning against uncertified operators confined to informal farmer's markets.
Pricing Analysis
Cost-plus contracts with desalinated water price indexation dominate procurement agreements between Riyadh-Qassim corridor growers and wholesale distributors. Price differentiation separates SASO-certified premium tier from standard uncertified output and economy-grade surplus channeled to farmer's markets. Pricing pressure stems from Ministry of Environment water-use efficiency quotas intensifying input cost volatility. Supermarket chains exhibit lowest price sensitivity due to year-round volume commitments, while home gardeners and informal channel buyers drive hard bargaining on small-lot purchases.
Supply Chain Analysis
Climate control hardware inventory cycles stretch 8-14 weeks for Saudi operators sourcing LED grow-light systems and precision irrigation components from East Asian manufacturing clusters. Geographic supply concentration centers on China for LED fixtures, South Korea for climate sensors, and the Netherlands for hydroponic substrate technologies. Raw material dependencies include high-purity nutrient salts, specialized polymer films, and semiconductor-grade LED chips. Single-source vulnerability concentrates in advanced aeroponics pressure systems. Distribution runs through Dammam port clearance and Riyadh-Qassim corridor cold-chain consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a regulatory-entrenchment defensive moat where SFDA certification creates switching costs that lock supermarket procurement relationships and compress supplier qualification timelines for challengers.
For Market Incumbents: Fortify captive supply relationships with Carrefour and Tamimi through blockchain-enabled traceability infrastructure that satisfies evolving SFDA mandates. Deepen backward integration into renewable energy systems to secure subsidy eligibility and insulate against desalinated water cost volatility threatening margin stability.
For New Entrants and Emerging Players: Anchor in Jeddah urban vertical farming whitespace where rooftop and warehouse facility proximity commands supermarket premium positioning absent from Riyadh-Qassim corridor saturation. Target direct-to-restaurant specialty lettuce and herb segments bypassing wholesale distributor margin extraction through same-day harvest-to-plate logistics.
For Investors and Strategic Acquirers: SASO certification timeline compression reshapes the acquisition landscape toward facilities with completed regulatory documentation rather than greenfield development risk. Long-term viability favors integrated operators with renewable energy infrastructure and established technician training pipelines. Monitor Ministry of Environment water quota tightening as the critical inflection signal for technology substitution toward aeroponics.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Unlocks Carrefour and Tamimi retail channel access with blockchain traceability infrastructure. |
| Renewable Energy Integration | Secures Ministry subsidy eligibility for solar-powered irrigation at Neom and Qassim developments. |
| Urban Vertical Farming Expansion | Captures Jeddah supermarket proximity premiums through rooftop and warehouse facility deployment. |
| Specialized Crop Protocol Development | Differentiates Qassim pepper output through climatic stress-optimized cultivation techniques. |
| Agritourism Complex Integration | Merges Red Sea Global hospitality infrastructure with dual-revenue greenhouse operations. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with greenhouse operations managers, SFDA compliance officers, supermarket procurement directors, and wholesale distributor logistics heads; and secondary validation against SASO certification registries, Ministry of Environment water quota filings, and customs import records for climate control equipment. Bottom-up facility capacity assessments triangulated against top-down supermarket offtake volume aggregation.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning technology type, product category, end-user channel, and regional cluster. CAGRs derived from trend extrapolation of installed greenhouse capacity, technology substitution patterns, and regulatory compliance diffusion curves. Forecast inputs incorporated desalinated water price trajectory assumptions and renewable energy subsidy eligibility evolution.
Material uncertainties — regulatory enforcement intensity variation, climate control equipment import disruption, and technician training program output shortfalls — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dry Onion Market
Vegetables
Fresh Mushroom Market
Vegetables
Garden Cress Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
South America Peas Market
Vegetables
Squash Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Global Mushroom Market
Vegetables
Qatar Greenhouse Market
Vegetables
Butternut Squash Market
Vegetables
Asparagus Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Dried Peas Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Garlic Market