
 Native Grass Seeds Market | 2026-2036
Native Grass Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Native Grass Seeds Market Intelligence
A capital-intensity divergence between integrated seed processors and boutique heritage collectors is redrawing competitive boundaries in native grass seed supply. Millborn Seeds Inc. leverages vertical control over conditioning and cold-storage infrastructure to sustain bulk contract fulfillment for government restoration programs. Bamert Seed Company anchors its position through geographic dominance across Texas and Oklahoma rangelands, where it competes on warm-season species breadth. Outsidepride.com, Inc. differentiates via direct-to-consumer digital channels that specialize in small-lot wildflower and grass mixes for residential pollinator gardens.
Native grass seeds comprise reproductive propagules of indigenous perennial and annual grass species, typically processed to purity standards exceeding 85 percent germination rates with minimal noxious weed contamination, then deployed to establish self-sustaining plant communities without invasive pressure. Their primary commercial purpose centers on ecological engineering applications where below-root biomass stabilizes substrates and above-ground canopy provides wildlife forage or carbon sequestration. Perennial seed types dominate volume flows due to multi-year stand persistence that reduces replanting frequency for erosion control contractors, while Tailored Blends command premium positioning where habitat restoration specifications mandate precise PLS (pure live seed) ratios for endangered species support. Green Infrastructure applications represent the fastest-expanding demand channel as municipal authorities integrate bioswale and green-roof mandates into stormwater compliance frameworks.
The USDA Natural Resources Conservation Service administers EQIP and CRP cost-share programs that directly shape seed procurement volumes and species eligibility lists across American agricultural counties. EPA stormwater regulations under the National Pollutant Discharge Elimination System compel municipal separate storm sewer system operators to incorporate vegetated best management practices, creating specification-grade demand for certified native seed sources. State departments of transportation in Iowa, Minnesota, and Wisconsin enforce roadside revegetation standards that restrict non-native cultivars, further tightening market access protocols. Stakeholders must monitor pending Farm Bill revisions that could recalibrate conservation acreage caps and redirect seed funding priorities across federal land management agencies.
Market Dynamics
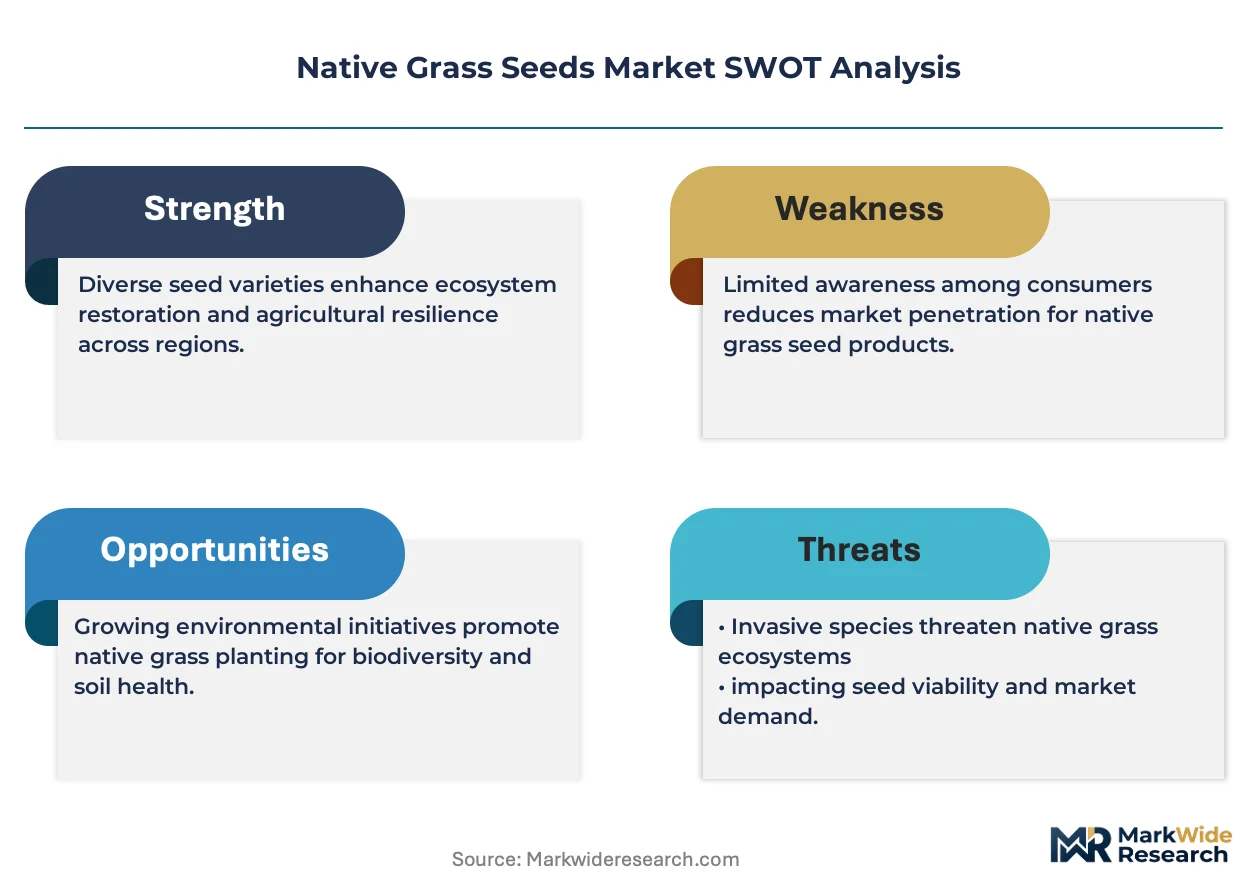
Federal conservation funding mechanics and municipal stormwater compliance mandates are restructuring demand concentration across the native grass seed supply base, privileging processors with certified cold-chain infrastructure and documented provenance trails.
Growth Catalysts
- Conservation Reserve Program (CRP) acreage retirement:USDA cost-share mechanisms sustain bulk procurement volumes across Iowa, Minnesota, and Nebraska counties, with enrollment caps directly conditioning seed mix specifications.
- EPA Clean Water Act Section 319 nonpoint source grants:Riparian buffer installation mandates in Midwest watersheds are generating specification-grade demand for certified PLS (pure live seed) ratios in government contracts.
- Green infrastructure codification:Municipal bioswale and green-roof ordinances in Chicago, Milwaukee, and Minneapolis are embedding native vegetation requirements into stormwater NPDES permits.
Market Restraints
- Seed conditioning infrastructure concentration:Cold-storage and purity-testing capacity clusters in South Dakota and Nebraska, creating geographic supply bottlenecks for East Coast restoration contractors.
- Genetic provenance restrictions:State DOT specifications in Wisconsin and Iowa mandate local ecotype sourcing, fragmenting inventory management and compressing eligible supplier pools.
- Perennial stand establishment timelines:Multi-year maturity requirements for ecological function delay contractor cash conversion cycles versus annual cover crop alternatives.
Strategic Opportunities
- Carbon credit stacking on CRP acres:Emerging protocols for soil carbon quantification create secondary revenue streams for seed providers bundling establishment services with monitoring.
- Direct-to-consumer pollinator garden channels:Residential small-lot mixes for monarch and native bee habitat represent underserved volume outside institutional procurement cycles.
- Endangered species habitat banking:US Fish and Wildlife Service mitigation credit frameworks in Texas and Oklahoma rangelands specify precise warm-season grass compositions.
Industry Challenges
- Seed certification timeline compression:AOSA (Association of Official Seed Analysts) purity and germination testing protocols create 6-12 month inventory holding periods before commercial release.
- Specialized harvesting equipment scarcity:Native grass seed strippers and flail-vacuum systems require capital deployment that smaller heritage collectors cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Grass Seeds Market |
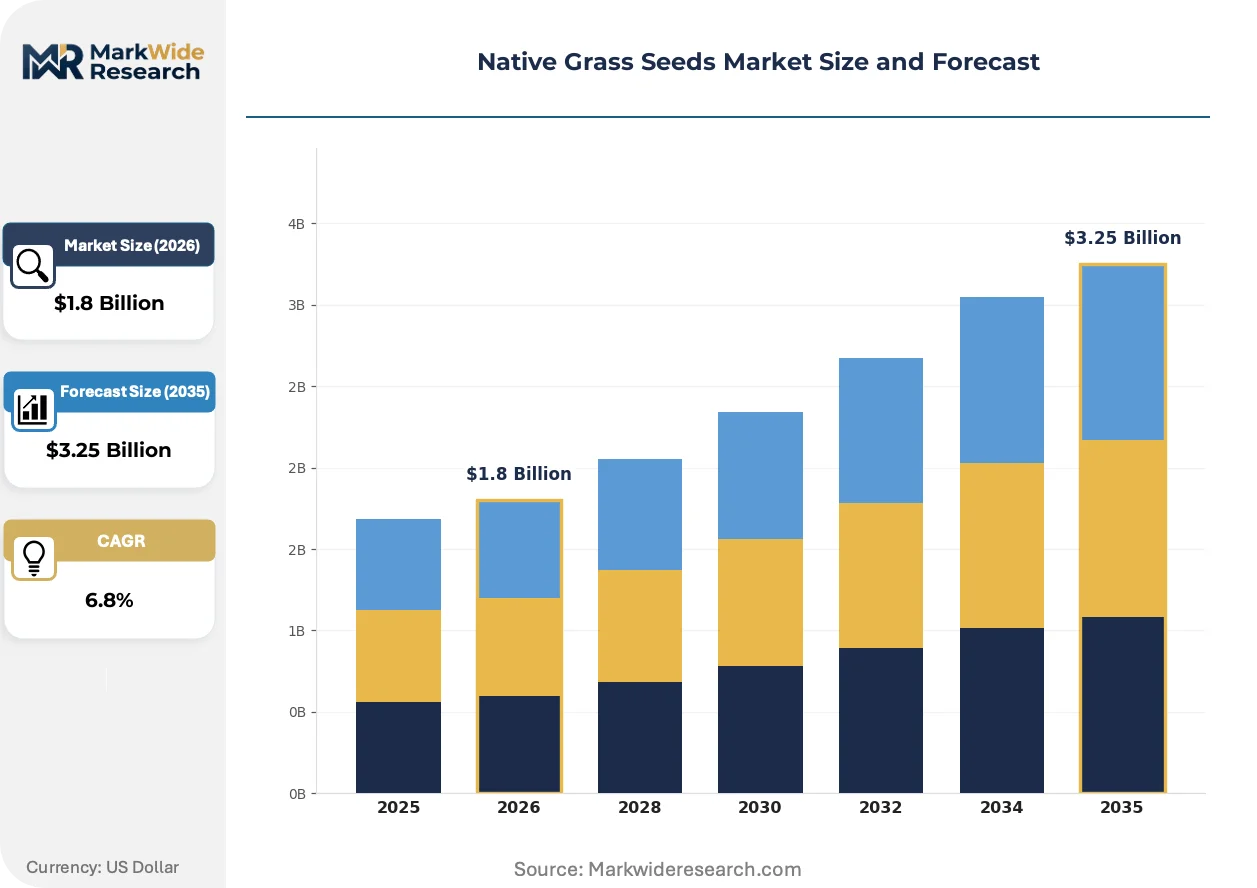
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Perennial, Annual, Biennial, Wildflower Mix, Tailored Blends Application: Soil Erosion Control, Habitat Restoration, Landscaping, Pasture Improvement, Green Infrastructure End User: Landscapers, Agricultural Producers, Conservation Groups, Municipal Authorities, Golf Courses Packaging Type: Bags, Bulk Containers, Pellets, Seed Tapes, Sachets |
| Companies Covered | Millborn Seeds Inc., Outsidepride.com, Inc., Star Seed Inc., American Meadows, Bamert Seed Company, Everwilde Farms, Inc., Hedgerow Farms, Prairie Seed Farms, Roundstone Native Seeds LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Grass Seeds Market Strategic Shifts & Innovations
Digital provenance tracking and precision seed coating chemistries are reconfiguring quality assurance workflows, while regulatory fragmentation across state DOT specifications is forcing modular product architecture.
Drone-assisted multispectral stand assessment is displacing manual germination monitoring for large-scale restoration contractors. Bureau of Land Management reclamation contractors in Wyoming and Colorado are deploying UAV-mounted NDVI sensors to verify establishment rates at 90-day intervals. This displacement compresses payment milestone verification from quarterly site visits to continuous remote sensing, altering contractor-seed supplier risk allocation in performance-based contracts.
USDA NRCS technical note revisions on native seed sourcing are tightening local ecotype definitions for EQIP-eligible projects. The revised Plant Materials Program guidelines now require seed collection radius documentation within 300 miles of installation sites. Midwest CRP enrollment counties are responding by consolidating procurement through regional seed cooperatives that can certify geographic origin.
Specification-driven procurement consolidation is compressing supplier tiers for municipal green infrastructure contracts. Stormwater engineering firms in Minneapolis and Chicago are pre-qualifying single-source seed providers for multi-year maintenance agreements. Texas and Oklahoma transportation departments are mirroring this pattern through master service agreements that bundle seed, installation, and monitoring.
Native Grass Seeds Market Segmentation
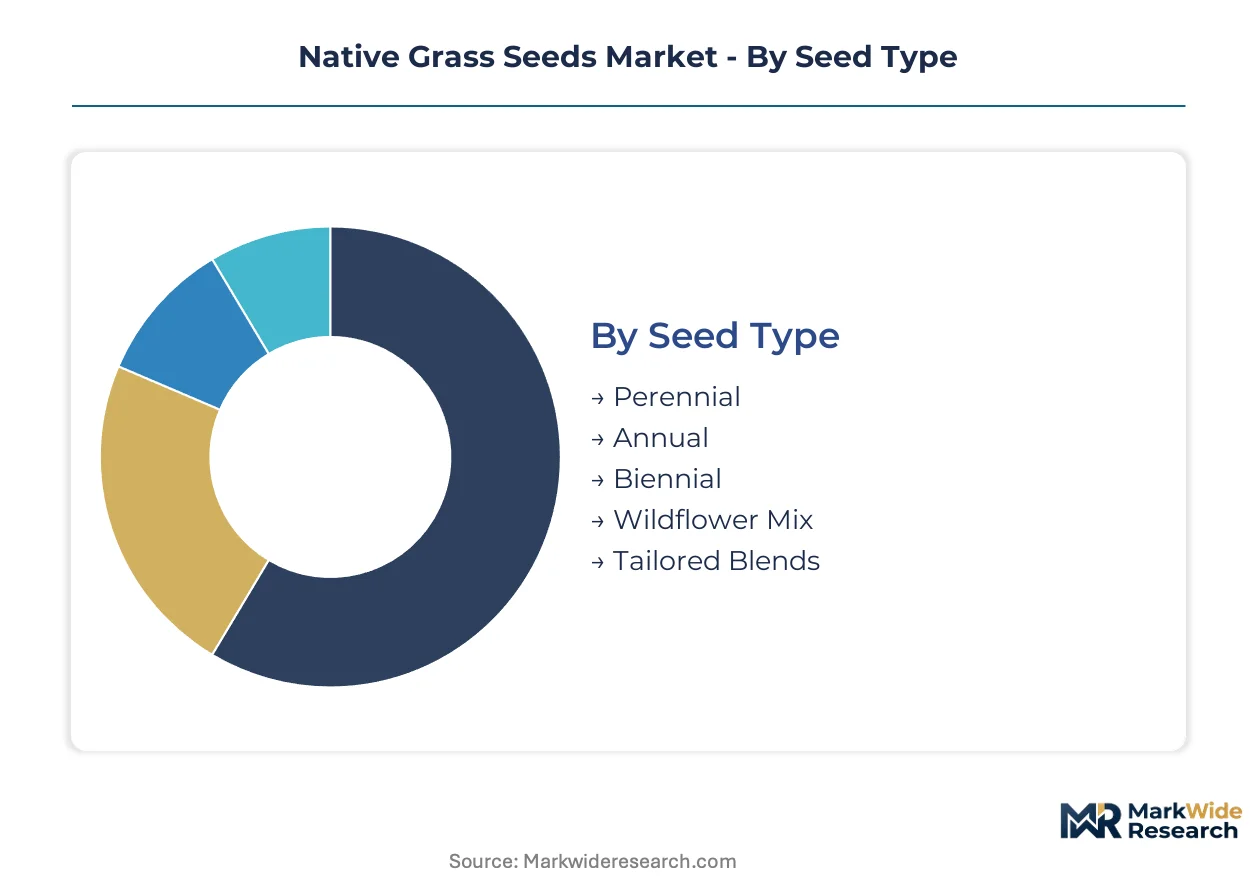
Native grass seed procurement channels fragment sharply across institutional buyers and residential consumers, with specification requirements varying by conservation program eligibility, stormwater compliance mandates, and habitat banking protocols. Segmentation discipline separates volume-driven bulk contracts from premium-priced provenance-certified lots.
Seed Type:
Substitution pressure from annual cover crops and synthetic erosion control materials concentrates most intensely on short-lived perennial varieties, while certified local ecotypes face minimal replacement risk due to regulatory lock-in.
- Perennial:Multi-year stand persistence reduces replanting frequency for erosion control contractors. Demand concentrates in Midwest Corn Belt CRP counties where USDA cost-share programs favor long-lived species over annual alternatives.
- Annual:Rapid establishment cycles appeal to emergency stabilization projects, but face displacement from cereal rye and crimson clover cover crops that offer comparable biomass at lower seed cost.
- Biennial:Intermediate persistence windows suit transitional restoration phases. Procurement volumes track disturbance-recovery timelines on pipeline corridors and mining reclamation sites.
- Wildflower Mix:Pollinator habitat specifications drive residential and municipal demand. EPA Clean Water Act Section 319 grants increasingly mandate native forb inclusion in riparian buffer seedings.
- Tailored Blends:Precise PLS ratios for endangered species support command premium positioning. US Fish and Wildlife Service mitigation credit frameworks in Texas and Oklahoma specify warm-season grass compositions that generic mixes cannot satisfy.
Perennial varieties retain volume leadership; Tailored Blends hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity erosion control from specification-grade habitat banking, with green infrastructure mandates creating a mid-tier compliance-driven channel.
- Soil Erosion Control:Highway embankments and construction sites drive bulk procurement of fast-establishing grasses. State DOT specifications in Iowa, Minnesota, and Wisconsin restrict cultivar eligibility to certified local ecotypes.
- Green Infrastructure:Municipal bioswale and green-roof ordinances in Chicago, Milwaukee, and Minneapolis embed native vegetation requirements into stormwater NPDES permits. Engineering firms pre-qualify single-source providers for multi-year maintenance agreements.
- Habitat Restoration:Endangered species mitigation banks and conservation easements demand documented provenance trails. Collection radius documentation within 300 miles of installation sites is now required for USDA NRCS EQIP eligibility.
- Landscaping:Residential pollinator gardens and corporate campus aesthetics favor small-lot wildflower and grass mixes. Direct-to-consumer digital channels capture volume outside institutional procurement cycles.
- Pasture Improvement:Warm-season native forages for rotational grazing systems compete against introduced bermudagrass and fescue. Texas and Oklahoma rangeland operators balance drought tolerance against establishment timeline constraints.
Soil Erosion Control dominates contract volume; Green Infrastructure is climbing the fastest.
End User:
Customer type concentration shapes packaging, certification, and payment term requirements, with municipal authorities imposing the most stringent pre-qualification barriers.
- Municipal Authorities:Stormwater NPDES compliance mandates specification-grade certified seed with full provenance documentation. Chicago and Minneapolis bundle seed, installation, and monitoring into master service agreements.
- Conservation Groups:Riparian buffer projects across Midwest watersheds generate demand for native grass seed mixes. EPA Clean Water Act Section 319 nonpoint source pollution grants direct funding toward vegetative stormwater management.
- Agricultural Producers:CRP acreage retirement programs in Iowa, Nebraska, and Minnesota sustain steady commercial volumes. Enrollment caps directly condition seed mix specifications and cost-share rates.
- Landscapers:Commercial and residential installation contractors favor bagged small-lot mixes with simplified establishment protocols. Regional seed cooperatives consolidate procurement to satisfy local ecotype requirements.
- Golf Courses:Native roughs and out-of-play areas balance aesthetic maintenance reduction with playability concerns. Warm-season prairie grasses compete against low-input fine fescue alternatives.
Municipal Authorities anchor specification-grade demand; Conservation Groups are gaining share fastest.
Packaging Type:
Supply concentration in South Dakota and Nebraska conditioning infrastructure dictates bulk container availability, while precision seed coating chemistries favor pellet formats for green infrastructure applications.
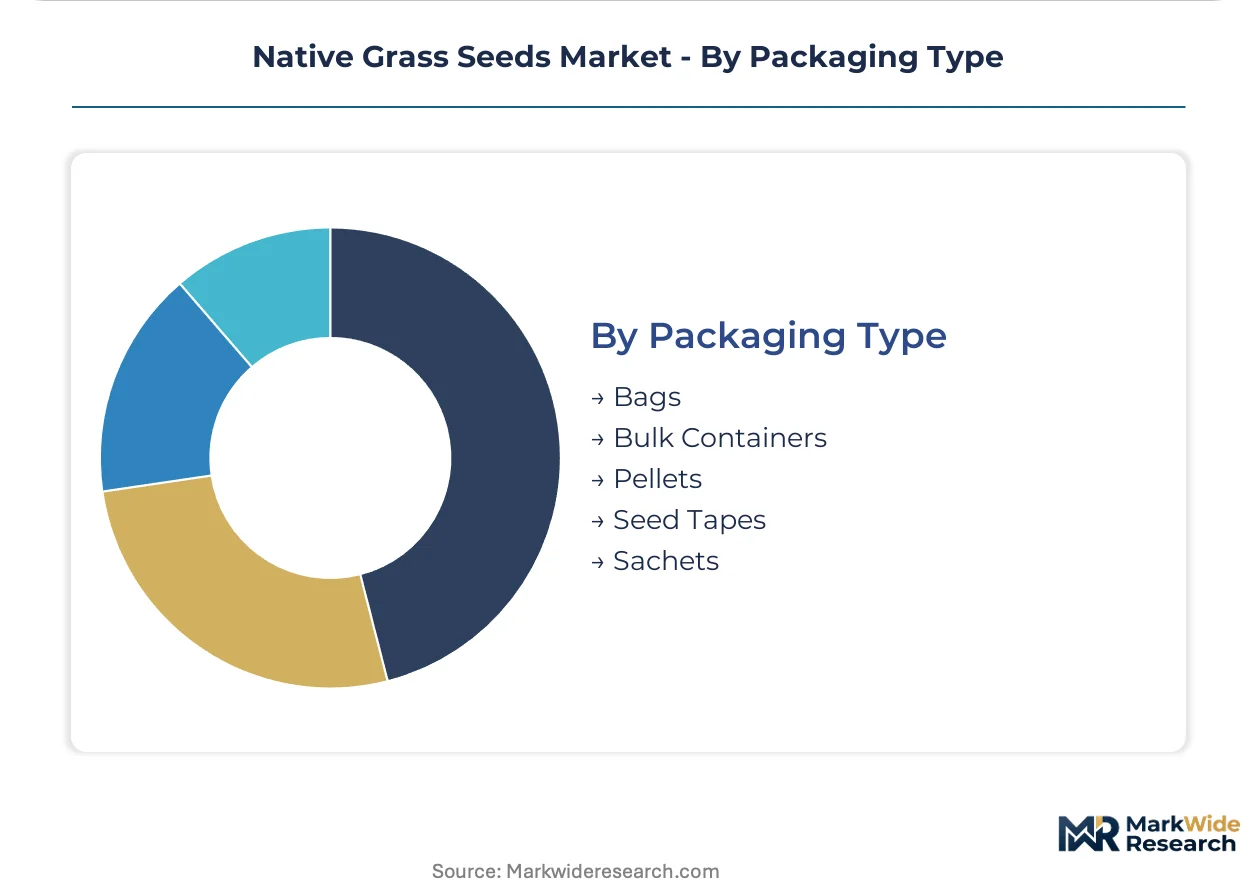
- Bulk Containers:Government restoration programs and large-scale CRP enrollments require tonnage-scale delivery with cold-chain integrity. Geographic bottlenecks disadvantage East Coast contractors.
- Pellets:Coated seed formats with integrated moisture retention and nutrient amendment suit bioswale and green-roof installations. Municipal stormwater engineering specifications increasingly mandate precision placement compatibility.
- Bags:Standard retail and commercial landscaping channels. AOSA purity and germination testing protocols create 6-12 month inventory holding periods before commercial release.
- Seed Tapes:Precision agriculture and habitat banking applications requiring uniform row spacing. US Fish and Wildlife Service mitigation sites in Texas specify establishment rate verification protocols.
- Sachets:Residential pollinator garden and small-lot wildflower channels. Direct-to-consumer digital platforms specialize in monarch and native bee habitat mixes.
Bulk Containers retain volume leadership; Pellets hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains net exporter status for native grass seed, shipping certified PLS inventory to Canadian restoration contractors while importing limited volumes of specialty warm-season ecotypes from Australian breeders. Domestic production clusters in the northern Great Plains, where conditioning infrastructure and cold-storage capacity concentrate near major CRP enrollment zones.
United States
USDA EQIP and CRP cost-share programs drive procurement volumes across Iowa, Minnesota, and Nebraska counties. EPA Clean Water Act Section 319 grants direct riparian buffer funding toward certified native seed sources. South Dakota and Nebraska host the dominant conditioning and cold-storage infrastructure clusters, creating geographic bottlenecks for East Coast contractors.
Canada
Prairie restoration initiatives and carbon sequestration projects generate import demand for certified PLS grass seed from US suppliers. Environment and Climate Change Canada wetland conservation programs specify native ecotype requirements. Ontario and Manitoba restoration contractors rely on cross-border seed cooperatives for provenance documentation.
Australia
Drought-tolerant warm-season native grasses support rangeland rehabilitation across Queensland and New South Wales. The Department of Agriculture, Water and the Environment administers Landcare and Natural Heritage Trust funding for indigenous revegetation. Seed collection networks in the Murray-Darling Basin supply local ecotypes for riparian recovery projects.
Germany
EU Green Deal biodiversity targets and national grassland conservation schemes expand demand for regional seed provenances. The Federal Agency for Nature Conservation enforces strict local ecotype sourcing for publicly funded restoration. Bavarian and Lower Saxony seed cooperatives consolidate collection networks to satisfy 300-kilometer radius requirements.
United Kingdom
Defra's Environmental Land Management scheme redirects agricultural subsidies toward habitat creation and species-rich grassland restoration. Natural England mandates local provenance seed for Sites of Special Scientific Interest and National Nature Reserve projects. English and Scottish seed enterprises build certified collection networks to meet specification-grade procurement.
Native Grass Seeds Market Key Industry Players
Concentration sits with vertically integrated processors controlling conditioning infrastructure and cold-chain logistics for government contract fulfillment. The supplier base fragments between bulk commodity handlers and boutique heritage collectors serving endangered species habitat banking. Three archetypes dominate: scale-driven seed processors with captive storage assets, geographic specialists commanding warm-season species breadth, and direct-to-consumer digital platforms capturing residential pollinator demand. Competitive moves center on regional seed cooperative consolidation and precision seed coating technology licensing for green infrastructure specifications.
Among US-based processors, Millborn Seeds Inc., Bamert Seed Company, and Outsidepride.com, Inc. occupy distinct positioning vectors. Millborn Seeds Inc. exemplifies the integrated processor archetype through vertical control over conditioning and bulk contract infrastructure. Bamert Seed Company anchors the geographic specialist tier with warm-season species concentration across Texas and Oklahoma rangelands. Outsidepride.com, Inc. represents the digital channel archetype, capturing small-lot residential demand outside institutional procurement cycles.
| Leading Market Players |
|---|
| Millborn Seeds Inc. |
| Outsidepride.com, Inc. |
| Star Seed Inc. |
| American Meadows |
| Bamert Seed Company |
| Everwilde Farms, Inc. |
| Hedgerow Farms |
| Prairie Seed Farms |
| Roundstone Native Seeds LLC |
| Others |
Cost & Logistics Intelligence
Six-to-twelve-month AOSA certification timelines compress inventory turns and amplify working capital requirements for processors lacking captive cold-storage assets, concentrating pricing power among vertically integrated handlers in South Dakota and Nebraska while squeezing margin recovery for smaller heritage collectors.
Pricing Analysis
The customization-premium spread between configured-to-order Tailored Blends and standard Perennial bulk contracts runs wide, with specification-grade PLS ratios for endangered species habitat banking commanding substantial premiums over commodity erosion control mixes. Price differentiation hinges on certification grade and provenance documentation radius, with USDA NRCS EQIP-eligible local ecotypes priced above generic cultivars. Pricing pressure stems from CRP enrollment cap uncertainty and Farm Bill revision timelines, compressing cost-share visibility. Agricultural Producers exhibit highest price sensitivity due to cost-share dependency, while Municipal Authorities show lowest sensitivity given NPDES compliance mandates.
Supply Chain Analysis
South Dakota and Nebraska anchor North American native grass seed conditioning, with captive cold-storage infrastructure and AOSA-certified testing laboratories clustering near major CRP enrollment zones in Iowa and Minnesota. Production draws from wildland collection networks across Texas and Oklahoma rangelands, plus cultivated stands in the northern Great Plains. Supply chain risk centers on single-source vulnerability: East Coast restoration contractors depend on distant Midwest conditioning capacity with no regional alternative. Distribution runs through regional seed cooperatives consolidating local ecotype procurement for state DOT specifications, supplemented by direct-to-consumer digital channels for residential pollinator mixes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across state DOT ecotype mandates and municipal green infrastructure ordinances creates multiple defendable niches for differentiated positioning, as no single processor can cost-effectively cover all provenance radius and certification requirements simultaneously.
For Market Incumbents: Compound geographic dominance through cooperative consolidation in CRP-heavy counties, securing captive collection networks within 300-mile USDA NRCS radius requirements. Invest in precision seed coating chemistries for bioswale specifications before municipal master service agreements lock in preferred providers. Defend against drone-assisted stand assessment displacing traditional germination verification by embedding remote sensing protocols into performance-based contracts. For New Entrants and Emerging Players: Differentiate on residential pollinator garden channels where Outsidepride.com, Inc. currently captures volume outside institutional procurement cycles. Target direct-to-consumer sachet formats for monarch and native bee habitat mixes, leveraging digital marketing against incumbent bulk-container focus. Penetrate through subscription-based seasonal planting programs bypassing AOSA certification delays for non-certified ornamental applications. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural cooperative seed divisions lacking capital to upgrade conditioning infrastructure for green infrastructure specifications. Long-term viability hinges on carbon credit stacking protocols maturing for CRP acreage secondary revenue streams. Watch for US Fish and Wildlife Service mitigation credit framework expansion in Texas and Oklahoma as inflection signal for warm-season grass specialist valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Seed Cooperative Consolidation | Midwest CRP counties demand provenance documentation that fragmented collectors cannot satisfy alone. |
| Precision Seed Coating Technology Licensing | Municipal bioswale specifications in Chicago and Minneapolis mandate pellet formats with moisture retention. |
| Drone-Assisted Stand Assessment Integration | Wyoming BLM contractors now require continuous NDVI verification replacing quarterly site visits. |
| Carbon Credit Stacking Service Bundling | Emerging soil carbon protocols create secondary revenue streams on established CRP acreage. |
| Direct-to-Consumer Pollinator Channel Buildout | Residential small-lot demand for monarch habitat escapes institutional procurement cycle constraints. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA NRCS program documentation, EPA Clean Water Act Section 319 grant allocations, and state DOT specification databases, with input from seed cooperative managers, erosion control contractors, municipal stormwater engineers, and AOSA-certified testing laboratory directors. Bottom-up volume estimates from county-level CRP enrollment data triangulate against top-down federal conservation funding appropriations to anchor market sizing.
Segmentation dimensions modeled span seed type, application, end user, and packaging format across the projection horizon, with particular attention to Perennial versus Tailored Blend substitution dynamics and Green Infrastructure versus Soil Erosion Control demand migration. CAGRs derive from enrollment trend extrapolation, regulatory mandate codification timelines, and municipal ordinance adoption curves, incorporating Farm Bill revision scenarios and NPDES permit expansion patterns as sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained federal conservation funding levels or accelerated state DOT local ecotype mandate adoption would require recalibration. Forecasts reflect assumptions regarding AOSA certification timeline stability and cold-storage infrastructure capacity expansion. Recalibration cycles align with material shifts in Farm Bill conservation title provisions and EPA stormwater regulatory guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Russia Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Mexico Seed Market
Seeds
Sesame Seeds Market
Seeds
Africa Vegetable Seed Market
Seeds
Global Oilseed Market
Seeds
Africa Peas Market
Seeds
Tallow Tree Seed Market
Seeds
Asparagus Seeds Market
Seeds
Field Crop Seeds Market
Seeds
Cover Crop Seed Varieties Market
Seeds
North America Vegetable Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Sri Lanka Seed Market
Seeds
Pigeon Pea Market
Seeds
Global Sorghum Seed Market