
 Polymer Coated Fertilizer Market | 2026-2036
Polymer Coated Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Coated Fertilizer Market Insights
Market Context
Modular nutrient bundling is hardening as the dominant packaging configuration, letting growers customize NPK ratios with polymer-coated base products rather than buying fixed formulations. Nutrien Ltd leverages its retail agronomy network to push private-label coated blends into North American corn belts. Yara International ASA anchors European demand through premium nitrate-based controlled-release lines. ICL Group Ltd specializes in potash-coated formulations for specialty crop segments.
Technical Definition and Segment Structure
Polymer coated fertilizer consists of conventional granular nutrients encapsulated in polymer membranes—typically polyolefins, polyurethanes, or sulfur-polymer composites—that regulate dissolution via diffusion-controlled release kinetics, primarily serving agricultural applications requiring precise nutrient timing and reduced leaching. Controlled-release formulations capture the deepest margin pools due to patent-protected coating chemistries and technical support bundling, while slow-release variants dominate volume in broadacre grain production where cost sensitivity limits uptake of advanced systems. Turf applications in golf course and municipal landscaping channels sustain premium pricing power despite smaller absolute tonnage.
Regulatory Framework and Outlook
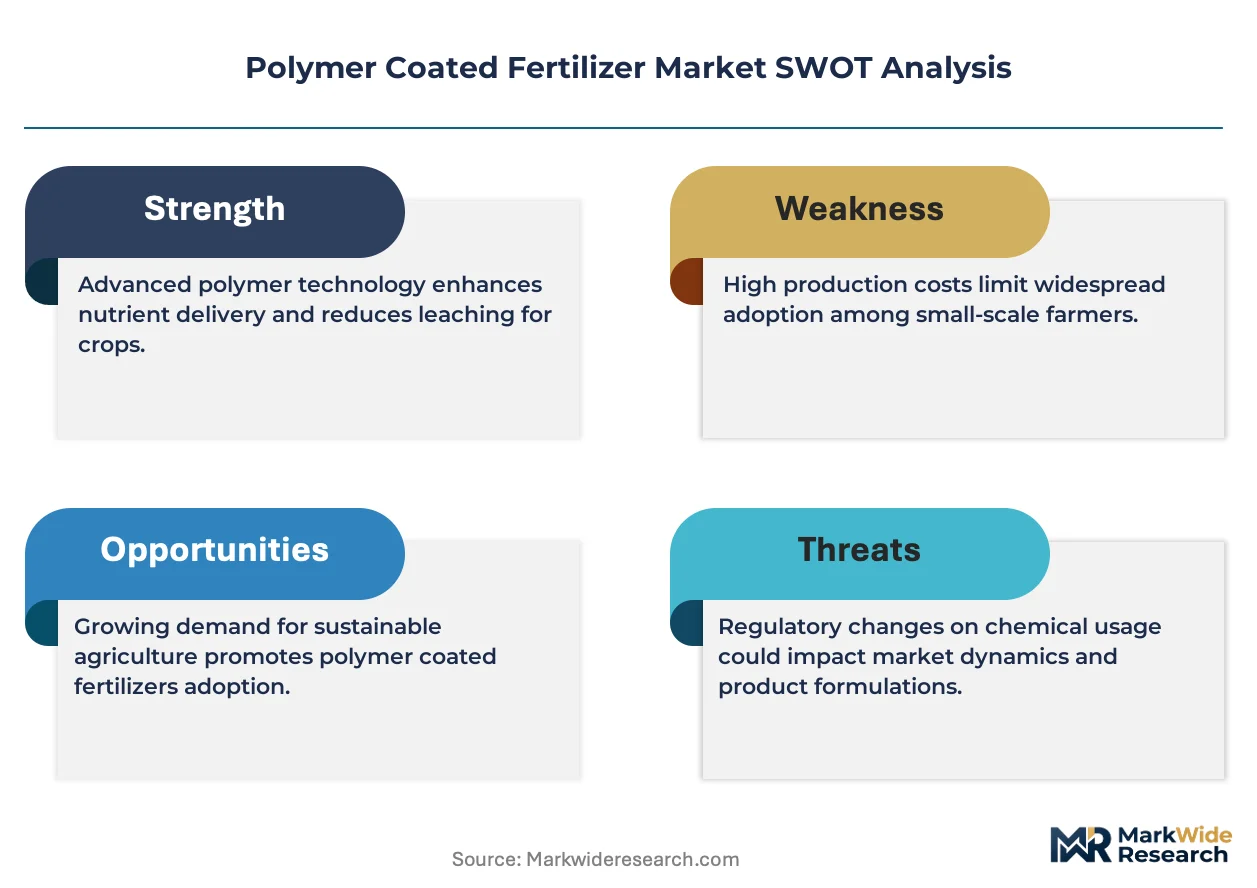
EPA water quality standards under the Clean Water Act and EU Nitrates Directive constrain conventional fertilizer runoff, directly elevating polymer-coated alternatives in watershed-sensitive zones. China's Ministry of Ecology and Environment enforces dual carbon goals that penalize high-emission nitrogen production, redirecting capacity toward efficient-release technologies. Brazil's national agricultural regulator enforces deforestation-linked sourcing rules that favor input suppliers with traceable supply chains. Stakeholders must monitor how carbon border adjustment mechanisms reshape cost competitiveness between regional coating technology hubs.
Market Dynamics
Water-use efficiency mandates across drought-prone agricultural zones are compressing adoption timelines for controlled-release formulations, forcing coating technology suppliers to prove agronomic ROI under tighter environmental constraints than conventional fertilizers face.
Growth Catalysts
- California's Central Valley regulations:Specialty crop producers face tightening irrigation allotments under state water board directives, driving demand for polymer-coated urea that reduces leaching losses and extends nutrient availability through dry spells.
- Sulfur-polymer composite coatings:Israeli and Chinese manufacturers have refined dual-layer encapsulation processes that cut per-unit polymer content by one-third while maintaining 60-90 day release profiles, narrowing the cost gap with uncoated alternatives.
- Precision agriculture integration:Variable-rate application systems in Brazil's Cerrado region pair GPS-guided spreaders with coated fertilizer databases, letting soybean operators synchronize nutrient release curves with growth-stage algorithms.
Market Restraints
- Petrochemical feedstock volatility:Polyolefin and polyurethane membrane costs track naphtha and propylene indices, exposing coating margins to energy market swings that uncoated fertilizer producers do not absorb.
- Coating technology concentration:Proprietary sulfur-polymer application equipment remains concentrated among Israeli, Chinese, and select North American engineering firms, creating equipment bottlenecks for new market entrants.
- Release kinetics variability:Soil temperature and moisture fluctuations in rain-fed grain systems degrade the predictability that justifies polymer-coated premiums, limiting penetration in non-irrigated broadacre markets.
Strategic Opportunities
- EU Green Deal agricultural pillars:Farm-to-Fork strategy nutrient-loss reduction targets create procurement preference for coated formulations in Netherlands, Denmark, and northern German watersheds with nitrate-vulnerable zone designations.
- Carbon credit monetization:Nitrous oxide emission reductions from controlled-release urea qualify for compliance and voluntary carbon markets in California's cap-and-trade system and emerging Australian agricultural protocols.
- Biostimulant-coating hybrids:Encapsulating microbial inoculants or humic acids within polymer shells alongside mineral nutrients addresses the biological-input segment seeking single-application convenience.
Industry Challenges
- Coating technician scarcity:Fluidized-bed and spouted-bed equipment operation requires specialized training unavailable through standard agricultural engineering programs, constraining production scale-up at new manufacturing sites.
- Field trial standardization gaps:Lack of harmonized protocols for demonstrating release-rate claims across soil types forces redundant testing for country-specific registrations, stretching R&D budgets and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Coated Fertilizer Market |
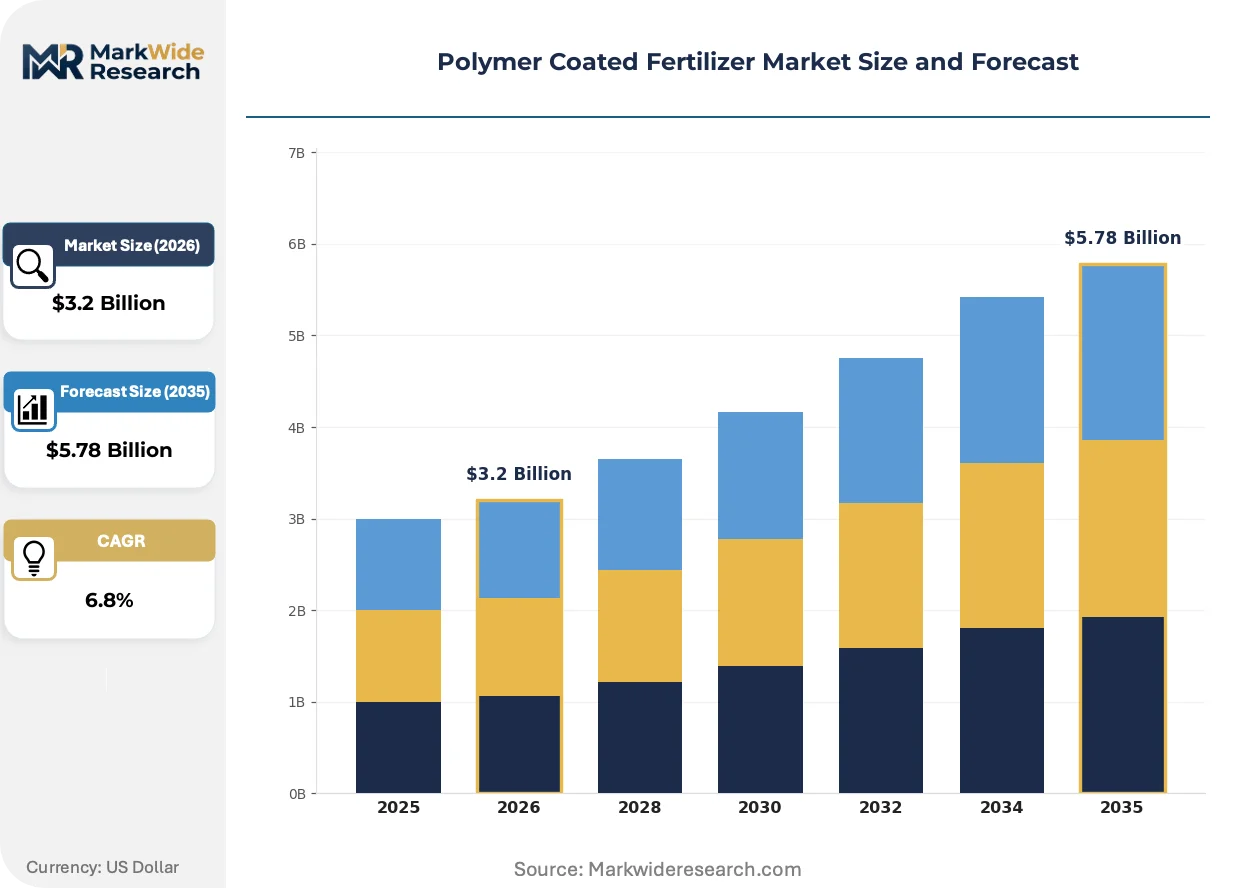
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slow-Release, Controlled-Release, Nutrient-Enriched, Blended Application: Agronomic, Turf, Ornamental, Greenhouse End Use: Agriculture, Horticulture, Landscaping, Gardening Packaging Type: Bulk Bags, Small Bags, Drums, Containers |
| Companies Covered | Nutrien Ltd, Yara International ASA, ICL Group Ltd, The Mosaic Company, Kingenta Ecological Engineering Group, Haifa Group, J.R. Simplot Company, Compo Expert GmbH, Nufarm Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Coated Fertilizer Market Trends and Innovations
Coating chemistry is migrating toward bio-based and biodegradable membrane materials as petroleum-derived polymers face scrutiny under extended producer responsibility frameworks, while digital agriculture platforms rewrite how growers evaluate nutrient efficiency claims.
Biopolymer encapsulation derived from lignin, starch, and cellulose derivatives is converging with conventional polyolefin systems in hybrid membrane designs. European specialty crop operators in greenhouse and high-value vegetable systems are piloting these materials at 15-20% price premiums. The convergence is compressing the sustainability credential gap between premium coated products and commodity alternatives, forcing incumbents to reformulate or defend positions on cost-performance metrics alone.
China's Ministry of Ecology and Environment dual carbon enforcement is redirecting nitrogen fertilizer capacity toward efficient-release technologies through emission-intensity penalties on conventional urea plants. Industrial consequence includes accelerated licensing for sulfur-coated urea expansion and restricted permits for new uncoated capacity. Domestic Chinese vegetable and fruit producers in Shandong and Yunnan provinces are absorbing this supply shift through state-backed demonstration farm programs.
Buyers in Brazil's Mato Grosso soybean belt are unbundling agronomic advisory from product supply, contracting independent precision agriculture consultancies to specify coating formulations rather than deferring to distributor recommendations. Retail agronomy channels face margin compression as procurement authority concentrates among 500+ hectare operators with in-house technical staff. This pattern is most visible in the Cerrado expansion zones where land consolidation outpaces traditional cooperative structures.
Polymer Coated Fertilizer Market Segmentation
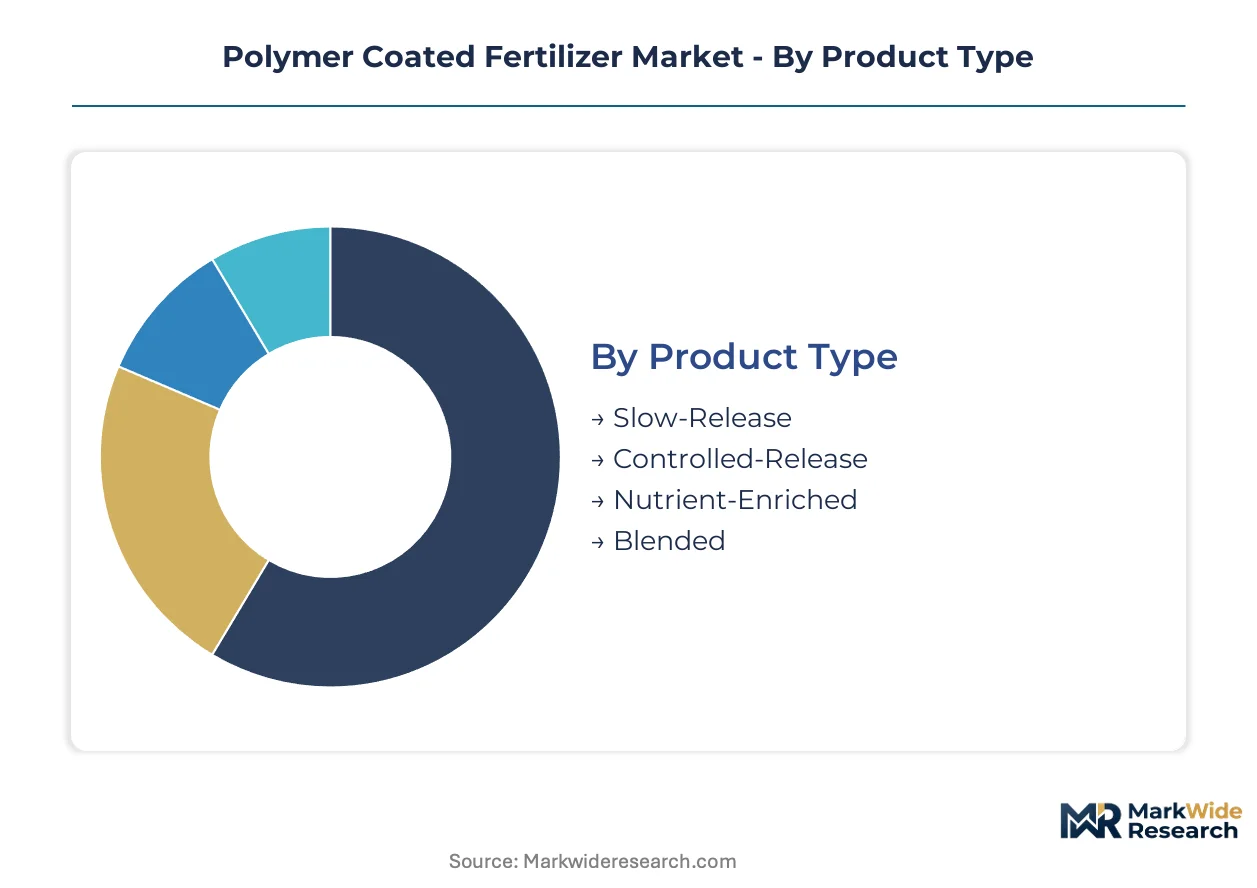
Polymer-coated fertilizer segmentation reflects divergent certification burdens across regulatory jurisdictions. Coating chemistry and release-kinetics specifications trigger distinct approval pathways under EPA, EU Nitrates Directive, and China's MEE frameworks.
Product Type:
Controlled-release formulations carry the heaviest registration burden under EPA 40 CFR Part 152 and EU REACH polymer substance notifications. Slow-release variants face lighter documentation requirements in most jurisdictions.
- Slow-Release:Sulfur-coated urea and sulfur-polymer composites dominate tonnage in Brazilian soybean operations and North American corn belts. Demand concentrates among cost-sensitive broadacre grain producers where release precision matters less than per-unit economics. Leading the category by volume: Slow-Release. Growing fastest: Controlled-Release.
- Controlled-Release:Polyolefin and polyurethane membrane systems achieve 60-120 day release curves through diffusion-controlled kinetics. Specialty crop producers in California's Central Valley and Netherlands greenhouse clusters absorb premium pricing for leaching reduction compliance.
- Nutrient-Enriched:Micronutrient-infused coatings address zinc and boron deficiencies in Indian wheat systems and Australian broadacre operations.
- Blended:Modular NPK combinations with polymer-coated base granules serve precision agriculture operators seeking customized ratios without fixed-formulation inventory.
Margin concentration follows coating sophistication: controlled-release commands premium positioning, slow-release drives volume throughput.
Application:
Application segments map directly to water-use regulation intensity and irrigation infrastructure access. Turf and greenhouse channels operate under municipal runoff ordinances and enclosed-system discharge rules that elevate coated fertilizer preference.
- Agronomic:Field crop applications span rain-fed grain systems and irrigated specialty production. Brazilian Cerrado soybean operators and California Central Valley vegetable growers represent divergent demand profiles within this segment.
- Turf:Golf course superintendents and municipal park managers sustain premium pricing power despite smaller absolute volumes. Nitrogen runoff restrictions under municipal stormwater permits in US Sun Belt states and Australian coastal jurisdictions mandate controlled-release adoption.
- Ornamental:Nursery and landscape contractors in EU urban greening programs and Chinese municipal beautification projects absorb mid-tier pricing for consistent color performance.
- Greenhouse:Soilless substrate systems in Netherlands, Spain's Almeria province, and China's Shandong province require precision nutrient delivery that polymer coatings enable.
Highest margin capture: Turf. Steepest expansion trajectory: Greenhouse.
End Use:
End-use segmentation reveals customer sophistication gradients. Professional agriculture and horticulture channels demand technical documentation and agronomic support that residential gardening segments rarely require.
- Agriculture:Commercial farming operations across Brazil, United States, and China account for dominant volume absorption. Precision agriculture adoption in Mato Grosso and variable-rate application penetration in Iowa corn systems reshape procurement patterns.
- Horticulture:High-value fruit and vegetable producers in Yunnan province, California's Salinas Valley, and Italy's Po Valley prioritize leaching reduction for water quality compliance.
- Landscaping:Commercial grounds maintenance contractors in drought-prone US Southwest states and Australian metropolitan areas specify coated formulations for reduced application labor.
- Gardening:Retail consumer channels in European home improvement stores and Chinese e-commerce platforms represent emerging volume with limited technical service requirements.
Procurement authority concentrates: Agriculture. Fastest share gain: Gardening.
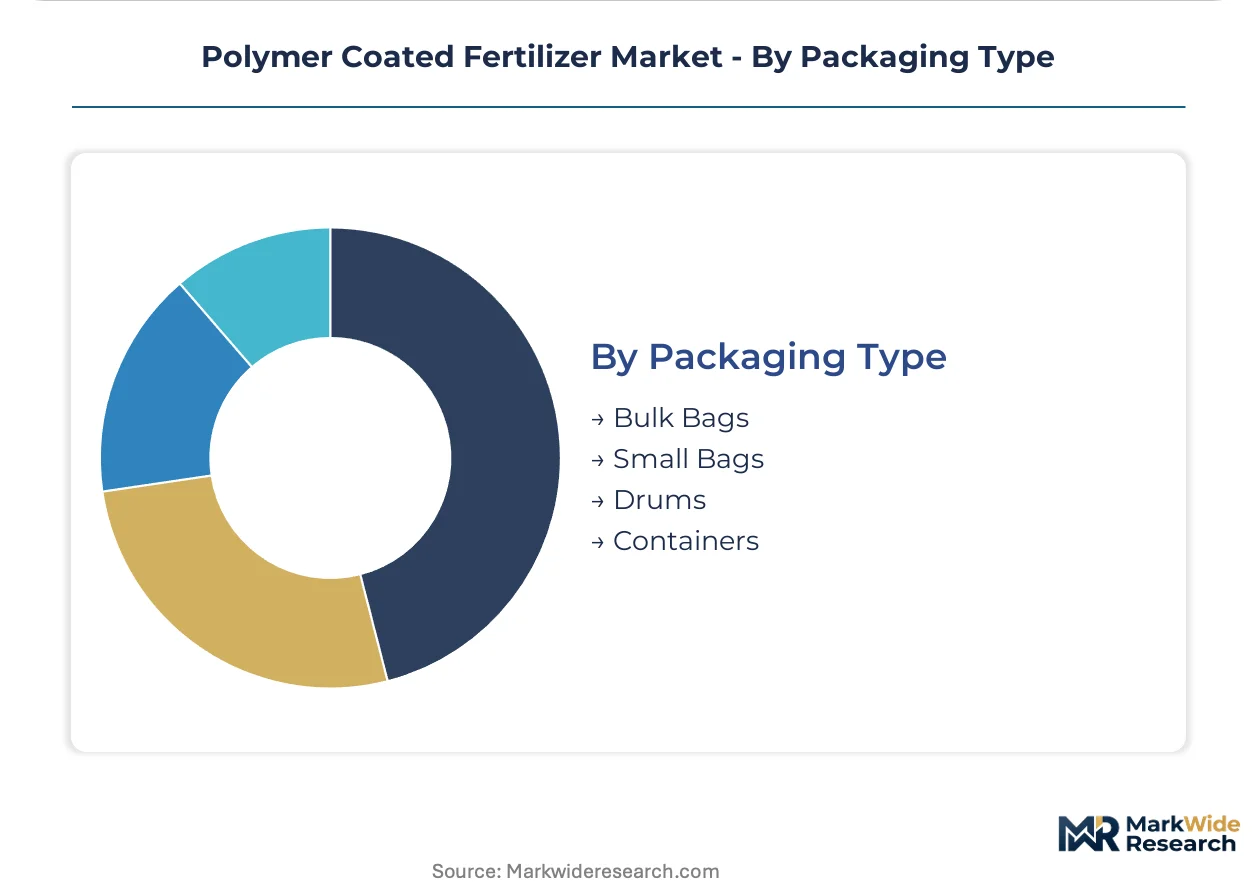
Packaging Type:
Packaging configuration reflects supply chain distance and customer scale. Bulk logistics dominate intra-regional movement while containerized formats serve export trade and smallholder access.
- Bulk Bags:One-ton and two-ton flexible intermediate bulk containers move coated urea from Chinese and Israeli manufacturing hubs to Brazilian port terminals and US Midwest distribution points.
- Small Bags:25-50 kilogram woven polypropylene units serve cooperative purchasing structures in India's Punjab and Haryana states and African smallholder aggregation programs.
- Drums:Steel and fiber containers protect moisture-sensitive specialty formulations during ocean freight to Southeast Asian horticulture markets.
- Containers:ISO tank and flexitank configurations enable liquid coating precursor shipments between petrochemical hubs and regional blending facilities.
Volume leadership: Bulk Bags. Fastest format growth: Small Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in China and Israel while consumption gravitates toward Brazil and the United States, creating transoceanic supply chains that expose coating margins to freight rate volatility and currency fluctuations.
Brazil
Mato Grosso soybean operators drive coated urea absorption through precision agriculture integration with GPS-guided variable-rate spreaders. ANVISA enforces traceable supply chain documentation under deforestation-linked sourcing rules that favor certified input suppliers. The Cerrado expansion zones around Lucas do Rio Verde witness procurement authority concentrating among 500+ hectare operators with in-house technical staff.
China
Shandong and Yunnan vegetable producers absorb supply shifts from state-backed demonstration farm programs promoting efficient-release technologies. The Ministry of Ecology and Environment penalizes high-emission nitrogen production through dual carbon enforcement, redirecting capacity toward sulfur-coated urea expansion. Domestic coating equipment manufacturing clusters in Jiangsu province supply fluidized-bed systems to regional blending facilities.
United States
California Central Valley specialty crop producers face tightening irrigation allotments under State Water Resources Control Board directives. EPA Clean Water Act runoff constraints elevate polymer-coated alternatives in watershed-sensitive zones throughout the Salinas Valley and Imperial County. Iowa corn systems integrate variable-rate application technology with coated fertilizer databases for growth-stage algorithm synchronization.
Israel
Advanced sulfur-polymer composite coating technologies originate from engineering firms with proprietary dual-layer encapsulation processes. National water-use efficiency mandates drive domestic agricultural technology export orientation toward drought-prone markets. Haifa-based equipment manufacturers supply spouted-bed application systems to international coating facilities seeking to narrow cost gaps with uncoated alternatives.
Netherlands
Greenhouse operators in Westland and Aalsmeer clusters absorb premium pricing for precision nutrient delivery in soilless substrate systems. EU Nitrates Directive nitrate-vulnerable zone designations create procurement preference for leaching-reduction formulations across northern German border watersheds. Wageningen University research partnerships accelerate biopolymer encapsulation pilot programs at 15-20% price premiums over conventional membranes.
Polymer Coated Fertilizer Market Competitive Landscape
The competitive structure tilts toward diversified agricultural input conglomerates with captive retail distribution networks. Three tiers separate premium patent-protected coating specialists from volume-driven commodity blenders and regional private-label suppliers. Consolidation pressure concentrates among Israeli and Chinese equipment-technology licensors while North American and European players defend positioning through agronomy service bundling. Dominant competitive moves include backward integration into polymer precursor production and strategic partnerships with precision agriculture platform providers.
Within the diversified-input conglomerate tier, Nutrien Ltd and Yara International ASA exemplify scale-driven positioning through retail agronomy network leverage and premium nitrate-based controlled-release lines respectively. Haifa Group anchors the specialty coating-technology vector as an Israel-based limited company representing advanced sulfur-polymer composite expertise. Kingenta Ecological Engineering Group occupies a position among Chinese ecological engineering specialists with state-backed demonstration farm program access.
| Leading Market Players |
|---|
| Nutrien Ltd |
| Yara International ASA |
| ICL Group Ltd |
| The Mosaic Company |
| Kingenta Ecological Engineering Group |
| Haifa Group |
| J.R. Simplot Company |
| Compo Expert GmbH |
| Nufarm Ltd |
| Others |
Pricing and Supply Chain Analysis
California's Central Valley irrigation allotment reductions under State Water Resources Control Board directives are forcing specialty crop producers to specify leaching-reduction formulations, compelling coating technology suppliers to absorb polymer cost volatility while defending premium positioning against uncoated alternatives.
Pricing Analysis
Margin tightening in controlled-release tiers reflects sulfur-polymer composite coating cost reductions from Israeli and Chinese equipment licensors. Three-tier pricing structure across controlled-release, slow-release, and nutrient-enriched levels stratifies by release precision and agronomic support bundling. Cost compression accelerates in slow-release segments as Brazilian soybean operators and North American corn belt buyers exercise volume-scale leverage. Turf and greenhouse applications demonstrate least price sensitivity due to municipal runoff compliance mandates.
Supply Chain Analysis
Direct-to-farm channels handle large-scale operator demand in Brazil's Mato Grosso and Iowa corn systems, while distributor networks serve cooperative purchasing structures. Manufacturing gravity centers on China and Israel, with coating equipment production clustering in Jiangsu province and Haifa engineering corridors. Raw material dependencies span naphtha-derived polyolefins, sulfur feedstocks, and polyurethane precursors. Single-source vulnerability concentrates in proprietary spouted-bed application systems controlled by Israeli and Chinese licensors. Distribution runs through bulk bag logistics for intra-regional movement and containerized formats for export trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer coated fertilizer markets function as cost-of-compliance arenas where EPA Clean Water Act runoff constraints and EU Nitrates Directive nitrate-vulnerable zone designations erect registration barriers that favor incumbents with established regulatory dossiers.
For Market Incumbents: Deepen backward integration into polymer precursor production to offset naphtha and propylene index volatility that commodity blenders do not absorb. Expand sulfur-polymer composite capacity in Israeli and Chinese manufacturing corridors before equipment bottlenecks constrain new entrant scale-up. Patent-protected coating chemistries and technical support bundling defend positioning against private-label distributors. For New Entrants and Emerging Players: E-commerce platforms serving Chinese home gardening segments and European retail consumer channels represent penetrable white-space with limited technical service requirements. Biostimulant-coating hybrids addressing microbial inoculant encapsulation demand offer differentiation angles against established mineral-nutrient incumbents. Precision agriculture consultancy partnerships bypass traditional distributor capture in Brazil's Cerrado consolidation zones. For Investors and Strategic Acquirers: The window for entry favors coating-technology licensors with proprietary dual-layer encapsulation equipment and state-backed demonstration farm program access in China. Long-term viability hinges on carbon credit monetization infrastructure for nitrous oxide emission reductions under California cap-and-trade systems and emerging Australian agricultural protocols. Watch for ANVISA deforestation-linked sourcing rule enforcement as inflection indicator for certified supply chain premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursors | Captive naphtha and propylene supply shields coating margins from petrochemical index swings. |
| Carbon Credit Monetization Infrastructure | California cap-and-trade qualification for controlled-release urea emission reductions opens compliance market revenue streams. |
| Precision Agriculture Platform Partnerships | GPS-guided variable-rate spreader integration in Brazil's Cerrado displaces traditional distributor procurement authority. |
| Biopolymer Encapsulation R&D Investment | Wageningen University partnerships accelerate lignin-derived membrane pilots at greenhouse operator price premiums. |
| Equipment Technology Licensing Expansion | Proprietary spouted-bed system exports from Israeli engineering firms capture margin pools in emerging coating hubs. |
Research Methodology
Trade databases, SEC 10-K filings from agricultural input conglomerates, and customs records formed the secondary backbone, supplemented by primary interviews with coating equipment engineers, agronomy retail network managers, specialty crop procurement leads, and regulatory affairs specialists at fertilizer registrants. Bottom-up triangulation across regional production capacity assessments and top-down validation against consumption absorption patterns in watershed-sensitive zones ensured cross-verification.
Historical trendline analysis of sulfur-coated urea and polymer-encapsulated nutrient shipments informed projection frameworks across the analysis window. Segmentation dimensions modeled include coating chemistry tier, application channel, end-use sophistication gradient, and regional regulatory cluster. CAGRs derived from supply-demand balance modeling incorporating water-use efficiency mandate adoption curves and precision agriculture penetration rates in Brazilian soybean operations.
The model holds under sustained EPA and EU Nitrates Directive enforcement intensity; deviation in carbon border adjustment mechanism implementation timelines or petrochemical feedstock price collapse would shift competitive cost positioning. Forecasts reflect documented assumptions regarding coating technology diffusion rates and irrigation infrastructure access expansion. Periodic stress-testing of base assumptions against ANVISA traceability rule enforcement and Chinese dual carbon goal acceleration is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Sulphur Coated Urea Market