
 Phosphoric Fertilizer Market | 2026-2036
Phosphoric Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphoric Fertilizer Market Analytics
Saudi Arabia is rewriting phosphate fertilizer supply dynamics through Ma'aden's massive Waad Al-Shamal mining and processing complex. The Mosaic Co. leverages its integrated Florida phosphate rock mines and Louisiana ammonia networks to sustain cost leadership across the Americas. OCP Group anchors global trade flows through its Jorf Lasfar hub, controlling export volumes into Europe and sub-Saharan Africa. EuroChem Group AG competes through its Russian and Kazakh phosphate assets, navigating sanctions complexity while maintaining output.
Phosphoric fertilizer denotes phosphate-containing compounds manufactured via the wet-process reaction of phosphate rock with sulfuric acid, yielding intermediates such as phosphoric acid that are subsequently ammoniated or combined to form finished products with specified P2O5 content, typically applied to correct phosphorus deficiency in cultivated soils. Diammonium phosphate dominates product type volumes due to its high nutrient density and compatibility with bulk blending operations, though ammonium polyphosphate is gaining traction in liquid fertilizer systems where application precision matters. On the application dimension, agricultural crops occupy the largest demand share, while horticulture commands premium pricing through specialized micronutrient co-formulations that standard commodity grades cannot match.
The EPA regulates phosphate mining under Clean Water Act permits in the United States, while REACH governs cadmium and heavy metal thresholds for fertilizer products entering the European Union, with ECHA periodically reviewing limit values that directly affect Moroccan and Russian export eligibility. India's FSSAI and CEA coordinate with the Department of Fertilizers to enforce quality standards and subsidy compliance, shaping formulation requirements for domestic manufacturers and importers alike. Stakeholders must monitor regulatory divergence on contaminant limits between jurisdictions, as compliance investments in one market may not transfer to another with stricter emerging standards.
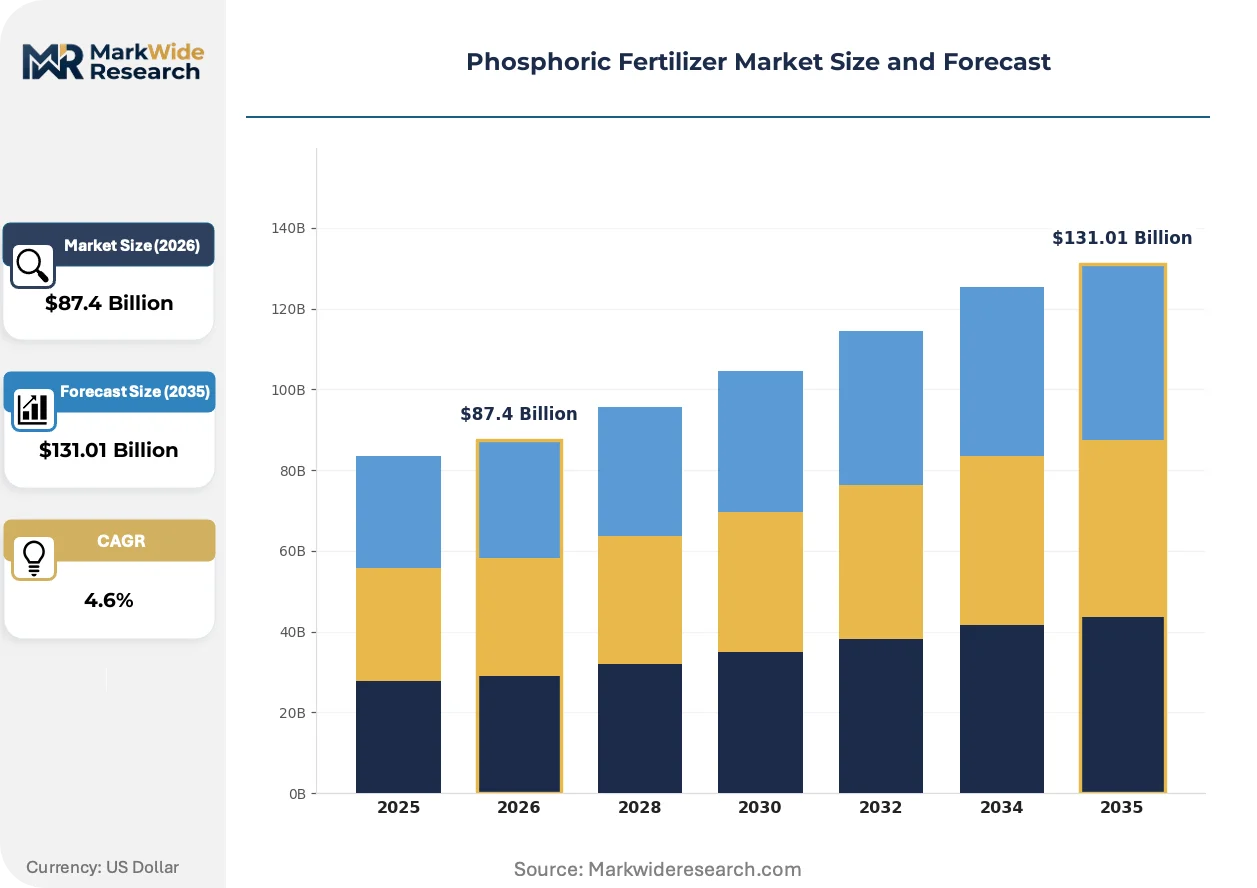
Market Dynamics
Phosphate rock supply concentration in Morocco and Saudi Arabia is reconfiguring procurement strategies for nitrogen-phosphate compound manufacturers, forcing buyers to secure long-term offtake agreements rather than spot-market sourcing.
Growth Catalysts
- Brazilian grain expansion:Soybean and corn producers in Mato Grosso and Goiás states are accelerating phosphate application rates as soil testing reveals critical phosphorus depletion across 45 million hectares of cultivated land.
- India's nutrient-based subsidy:The Department of Fertilizers recalibrated DAP and NPK support mechanisms under the NBS scheme, lowering farmer out-of-pocket costs and expanding volume offtake from domestic blenders.
- Enhanced-efficiency coating technologies:Polymer-coated phosphate granules and stabilized acid formulations are extending nutrient release windows, enabling single-application protocols that reduce labor costs for large-scale row-crop operations.
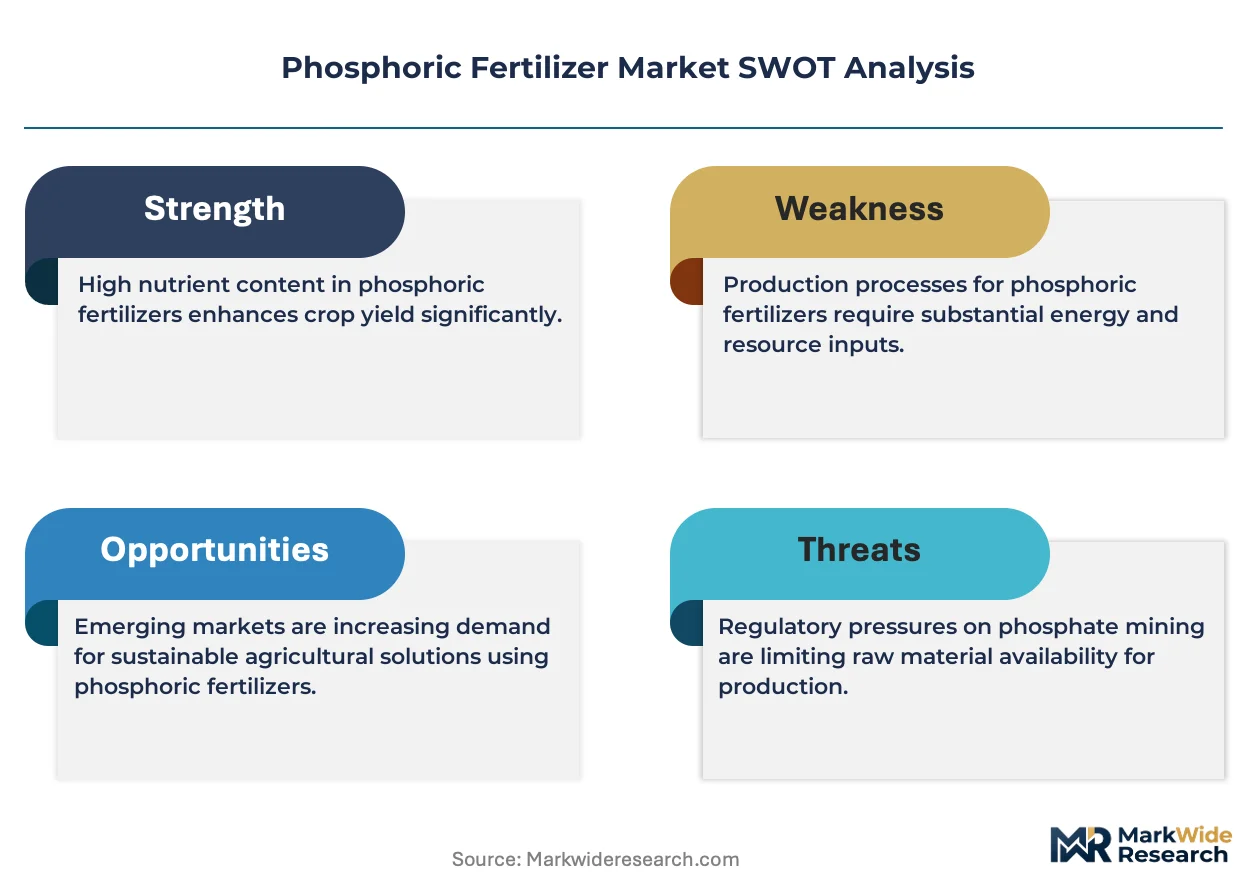
Market Restraints
- Sulfuric acid cost volatility:Wet-process phosphoric acid production consumes 2.5-3.0 tonnes of sulfuric acid per tonne of P2O5, and sulfur price spikes at Tampa and Vancouver benchmarks directly compress processor margins.
- EU cadmium thresholds:REACH and the EU Fertilizing Products Regulation are tightening heavy metal limits on phosphate rock imports, disqualifying high-cadmium Moroccan and Russian concentrates from European formulation plants.
- Rock phosphate substitution:Struvite recovery from municipal wastewater and bone meal processing are capturing niche organic fertilizer demand, particularly in Dutch and Danish horticulture markets with strict input certification requirements.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Ethiopia, Tanzania, and Nigeria maintain phosphate application rates below 15 kg P2O5 per hectare, creating volume expansion potential as national fertilizer subsidy programs scale.
- Liquid fertilizer systems:Ammonium polyphosphate and orthophosphate suspensions are displacing dry bulk blends in Brazilian sugarcane and citrus operations where fertigation infrastructure penetrates.
- Carbon border adjustment:The EU CBAM will impose embodied emissions tariffs on imported phosphate fertilizers from 2026, rewarding producers with low-carbon sulfuric acid and captive power generation.
Industry Challenges
- Process engineering talent scarcity:Wet-process phosphoric acid plant operations require specialized expertise in filtration, concentration, and fluorine recovery that retiring workforces in Florida and Morocco are not replenishing.
- Phosphogypsum stack remediation:EPA and state-level environmental regulators are mandating closure and capping of legacy gypsum impoundments, imposing billion-dollar liabilities on historical production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphoric Fertilizer Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $131.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoammonium Phosphate, Diammonium Phosphate, Superphosphate, Ammonium Polyphosphate Application: Agricultural Crops, Horticulture, Turf & Ornamentals, Fertilizer Blends Form: Granular, Powder, Liquid, Suspension Packaging Type: Bags, Bulk, Drums, Custom Packaging |
| Companies Covered | The Mosaic Co., OCP Group, EuroChem Group AG, Nutrien Ltd., Yara International ASA, CF Industries Holdings Inc., PJSC PhosAgro, Israel Chemicals Ltd., Coromandel International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphoric Fertilizer Market Evolving Landscape
Digital nutrient management platforms and precision application hardware are converging to transform how phosphate fertilizers are prescribed, distributed, and validated in the field.
Controlled-release coating technology is virtualizing traditional broadcasting methods. Polymer-encapsulated DAP and MAP granules synchronize phosphorus availability with crop uptake curves, reducing fixation losses in high-pH calcareous soils. Major row-crop operators in the US Corn Belt and Ukrainian black-soil zones are adopting these formulations at 15-20% price premiums, compressing the economic case for uncoated commodity grades.
EFSA's revision of contaminant limits under the Farm to Fork Strategy is tightening cadmium and uranium thresholds for fertilizer products entering European markets. Moroccan and Russian exporters must now certify rock phosphate sources below 60 mg Cd/kg P2O5, forcing beneficiation investments and blending strategies at Jorf Lasfar and Russian processing hubs. German and Polish blenders are responding by diversifying supply contracts toward Saudi and Jordanian rock with inherently lower heavy metal content.
Farmer buying collectives and input financing platforms are consolidating procurement decisions away from independent retail channels. Brazilian cooperatives and Indian Farmers Producer Organizations are negotiating direct manufacturer contracts, disintermediating regional distributors who previously controlled credit extension and technical advisory. This concentration is most visible in Mato Grosso and Punjab, where cooperative volumes now exceed 40% of seasonal phosphate offtake.
Phosphoric Fertilizer Market Segmentation
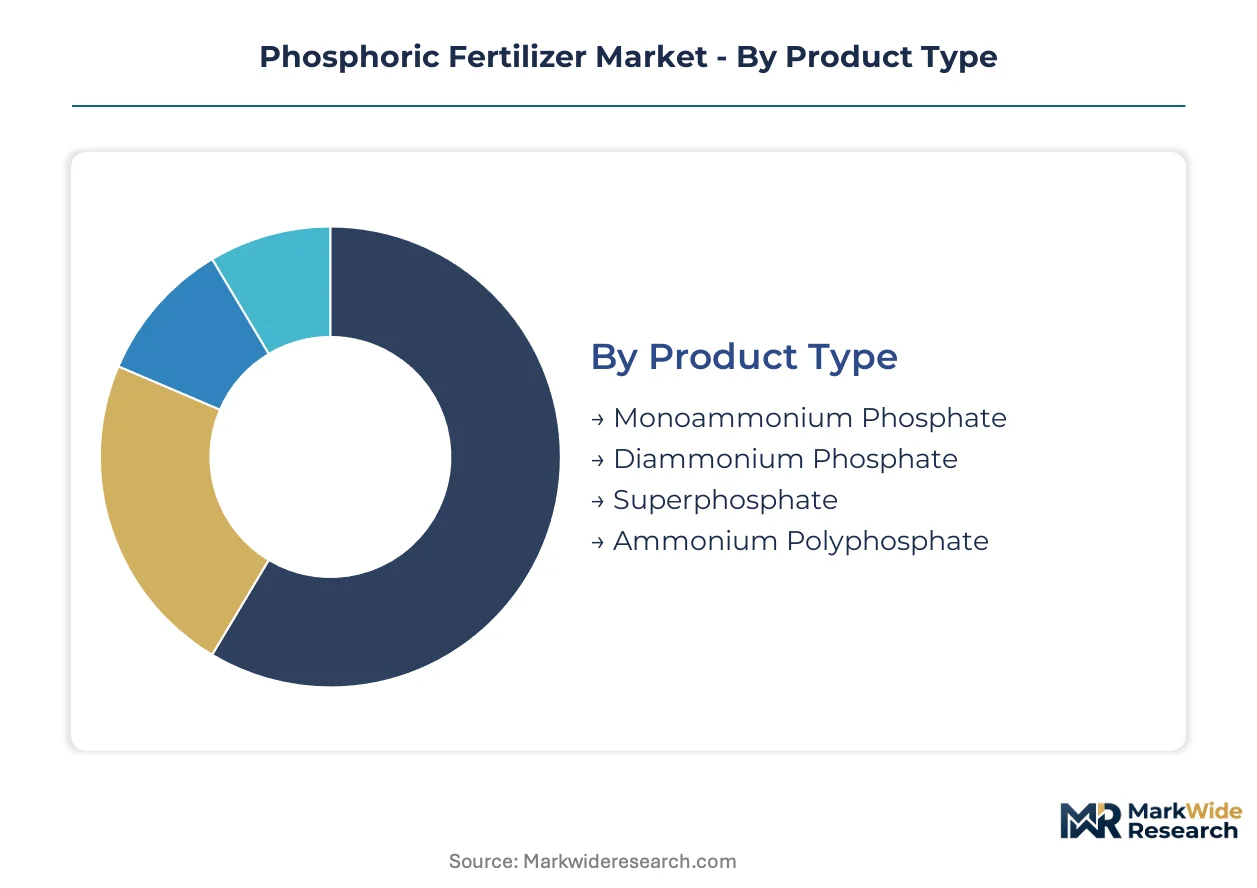
Phosphoric fertilizer segmentation reveals how product chemistry, application method, and physical form intersect to create distinct value propositions for buyers with divergent soil conditions, equipment capabilities, and crop economics. Understanding these segment boundaries enables suppliers to align formulation investments with the highest-margin demand pockets.
Product Type:
Cost tier stratification separates commodity phosphate compounds from premium stabilized formulations, with nitrogen-phosphate ratios and water solubility determining farm-gate pricing power.
- Diammonium Phosphate:This compound delivers 18% nitrogen and 46% P2O5 in a fully water-soluble crystalline structure, making it compatible with bulk blending systems worldwide. Brazilian soybean operations in Mato Grosso rely on DAP as their base phosphorus source, though sulfur price volatility at Tampa benchmarks compresses processor margins on this grade.
- Ammonium Polyphosphate:Liquid formulations contain 10-34-0 or 11-37-0 nutrient ratios with polyphosphate chains that sequester micronutrients and resist soil fixation. Florida citrus and Brazilian sugarcane fertigation systems are displacing dry bulk blends with APP suspensions where precision application infrastructure penetrates.
- Monoammonium Phosphate:Lower nitrogen content (11-52-0) suits high-pH calcareous soils where ammonia volatilization losses threaten efficiency.
- Superphosphate:Single and triple superphosphate grades serve organic-certified operations requiring non-ammoniated phosphorus sources.
Diammonium Phosphate commands the established base. The steepest expansion runs through Ammonium Polyphosphate.
Application:
Application dimension separates volume-driven commodity agriculture from premium horticulture markets where micronutrient co-formulations justify 40-60% price premiums over standard grades.
- Agricultural Crops:Row-crop operations across the US Corn Belt, Ukrainian black-soil zones, and Indian Punjab apply phosphate fertilizers at scale through broadcast spreading or precision planting equipment. India's nutrient-based subsidy scheme recalibrated DAP and NPK support mechanisms, lowering farmer out-of-pocket costs and expanding volume offtake from domestic blenders.
- Horticulture:Protected cultivation in Dutch glasshouses and Spanish Almería polytunnels demands specialized formulations with controlled-release coatings and certified low-cadmium content under EFSA's Farm to Fork Strategy thresholds. German and Polish blenders are diversifying supply contracts toward Saudi and Jordanian rock with inherently lower heavy metal content to serve this segment.
- Turf & Ornamentals:Golf course and landscape maintenance operations favor quick-dissolving granular grades for foliar and soil applications.
- Fertilizer Blends:Regional mixing facilities combine phosphate intermediates with nitrogen and potassium sources to produce customized NPK ratios for local soil conditions.
Agricultural Crops generates the volume foundation. Horticulture captures the margin expansion.
Form:
Physical form determines logistics economics and application compatibility, with liquid and suspension technologies gaining share in irrigated systems while granular retains dominance in rainfed grain regions.
- Granular:Hard, uniform prills spread evenly through pneumatic and spinner applicators, dominating Brazilian Cerrado soybean operations and US Midwest corn production where dry fertilizer infrastructure is entrenched.
- Liquid:Clear solutions and suspensions enable fertigation integration and variable-rate application through center-pivot and drip systems, expanding fastest in Florida citrus and Brazilian sugarcane zones.
- Powder:Fine-ground materials serve specialty foliar sprays and hydroponic nutrient solutions.
- Suspension:High-analysis liquid concentrates with gelling agents prevent settling during storage and transport.
Granular form holds the installed base. Liquid form is climbing the fastest.
Packaging Type:
Packaging configuration reflects customer scale and supply chain access, with bulk dominating integrated operations while bags persist in fragmented retail channels.
- Bulk:Unpackaged shipments via pneumatic trailer and railcar serve cooperative purchasing groups and large-scale farming enterprises, with Brazilian cooperatives in Mato Grosso and Indian Farmers Producer Organizations negotiating direct manufacturer contracts that disintermediate regional distributors.
- Bags:50kg woven polypropylene sacks remain standard for smallholder access through dealer networks in sub-Saharan Africa and South Asian villages where storage infrastructure is limited.
- Drums:Steel and plastic containers protect liquid formulations during long-distance transport to remote operations.
- Custom Packaging:Private-label and specialty-blend containers serve branded retail channels and organic certification requirements.
Bulk packaging dominates volume flows. Custom packaging offers the differentiation pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian grain producers apply phosphate fertilizers at substantially higher rates per hectare than Indian smallholders, creating divergent procurement patterns between volume-driven cooperative purchasing and subsidy-dependent retail distribution.
Brazil
Soybean and corn operations in Mato Grosso and Goiás states drive phosphate consumption as soil testing reveals critical phosphorus depletion across 45 million hectares. ANVISA coordinates with MAPA on fertilizer quality standards while the country's nutrient-based subsidy discussions remain under legislative review. São Paulo-based cooperatives now negotiate direct manufacturer contracts, disintermediating regional distributors who previously controlled credit extension.
India
The Department of Fertilizers recalibrated DAP and NPK support mechanisms under the NBS scheme, lowering farmer out-of-pocket costs and expanding volume offtake from domestic blenders. FSSAI and CEA enforce quality standards and subsidy compliance, shaping formulation requirements for domestic manufacturers and importers alike. Punjab's Farmers Producer Organizations concentrate seasonal purchasing power, with cooperative volumes now exceeding 40% of regional phosphate offtake.
United States
Row-crop operators across the Corn Belt apply phosphate fertilizers at scale through broadcast spreading or precision planting equipment, with polymer-coated formulations commanding 15-20% price premiums. EPA regulates phosphate mining under Clean Water Act permits while Florida state environmental regulators mandate closure and capping of legacy gypsum impoundments. The Mosaic Co. leverages integrated Florida phosphate rock mines and Louisiana ammonia networks to sustain cost leadership across the Americas.
Germany
German blenders diversify supply contracts toward Saudi and Jordanian rock with inherently lower heavy metal content to serve horticulture markets with strict input certification requirements. REACH governs cadmium and heavy metal thresholds for fertilizer products entering the European Union, with ECHA periodically reviewing limit values that directly affect Moroccan and Russian export eligibility. The Rhine-Ruhr industrial corridor hosts formulation facilities serving Dutch glasshouse and Spanish Almería polytunnel demand.
Saudi Arabia
Ma'aden's Waad Al-Shamal mining and processing complex rewrites phosphate fertilizer supply dynamics through massive capacity expansion into European and Asian markets. SFDA coordinates with the Ministry of Environment on industrial emissions standards while the country's central bank supports project financing structures. The integrated complex combines phosphate rock extraction, sulfuric acid production, and downstream fertilizer manufacturing within a single industrial zone.
Phosphoric Fertilizer Market Competitive Landscape
Capability concentration sits with integrated mining-processing complexes; scale advantage sits with distributed formulation and distribution networks. The vendor base organizes around three strategic archetypes: captive rock producers with downstream acid and fertilizer assets, nitrogen-phosphate compounders dependent on merchant rock offtake, and regional blenders serving localized soil chemistry requirements. Dominant competitive moves include securing long-term phosphate rock supply agreements and investing in enhanced-efficiency coating technologies that command farm-gate price premiums.
Within the integrated producer tier, The Mosaic Co., OCP Group, and Ma'aden exemplify the captive-resource archetype. The Mosaic Co., a US-based corporation, anchors American supply security through vertically controlled Florida mining assets. OCP Group, a Moroccan limited company, occupies a position as the Jorf Lasfar hub operator directing export volumes into Europe and sub-Saharan Africa. Ma'aden, a Saudi Arabian corporate entity, represents the emerging low-carbon production vector targeting European markets ahead of CBAM implementation.
| Leading Market Players |
|---|
| The Mosaic Co. |
| OCP Group |
| EuroChem Group AG |
| Nutrien Ltd. |
| Yara International ASA |
| CF Industries Holdings Inc. |
| PJSC PhosAgro |
| Israel Chemicals Ltd. |
| Coromandel International Ltd. |
| Others |
Value Network & Pricing Analysis
Sulfuric acid cost volatility at Tampa and Vancouver benchmarks compresses processor margins while simultaneously widening price spreads between integrated captive producers and merchant-dependent compounders, forcing buyers to lock in long-term offtake agreements rather than absorb spot-market sulfur spikes.
Pricing Analysis
Brazilian farm-gate DAP quotations run 12-18% above Indian subsidized equivalents due to freight differentials and cooperative purchasing concentration. Three-tier pricing structure across polymer-coated premium grades, standard granular compounds, and bulk commodity blends separates formulations by release-technology sophistication and micronutrient certification. Cost compression in uncoated commodity grades is intensifying because sulfur price spikes transmit directly into wet-process acid economics. Smallholder retail channels in sub-Saharan Africa exhibit acute price sensitivity, while Brazilian cooperatives and German horticulture blenders absorb premiums for cadmium-certified and enhanced-efficiency products.
Supply Chain Analysis
Merchant sulfuric acid processors in Louisiana and Florida hold contracted capacity positions serving nitrogen-phosphate compounders without captive acid assets. Phosphate rock extraction concentrates in Morocco, Saudi Arabia, and Russia, while downstream formulation spreads across Brazil, India, and the United States. Wet-process phosphoric acid production draws from phosphate rock, sulfuric acid, and ammonia inputs in fixed stoichiometric ratios. Single-source vulnerability to Moroccan rock supply exposes European blenders to REACH cadmium threshold revisions. Distribution runs through cooperative purchasing groups disintermediating regional distributors in Mato Grosso and Punjab, alongside bulk rail and pneumatic trailer networks serving integrated row-crop operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as Brazilian grain expansion and Indian subsidy recalibration restock channel inventories depleted during the sulfur price spike period.
For Market Incumbents: Entrench cost leadership through backward integration into captive sulfuric acid production and Florida phosphate rock mining assets that The Mosaic Co. leverages. Secure long-term offtake agreements with Brazilian cooperatives and Indian Farmers Producer Organizations before emerging Saudi capacity captures European CBAM-advantaged share. Invest in polymer-coating R&D to defend premium tier pricing against commodity grade erosion. For New Entrants and Emerging Players: Pursue sub-Saharan African markets where Ethiopian, Tanzanian, and Nigerian application rates sit below 15 kg P2O5 per hectare and national subsidy programs are scaling. Target liquid fertilizer systems in Brazilian sugarcane and Florida citrus zones where fertigation infrastructure penetration displaces dry bulk blends. Angle through ammonium polyphosphate suspensions with micronutrient sequestration claims that command precision-application premiums. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated mining-processing complexes with captive energy and acid assets over distributed formulation networks. Long-term viability across the projection horizon rests on securing low-carbon production positions ahead of EU CBAM implementation. Watch sulfur price volatility at Tampa benchmarks as the inflection indicator for processor margin compression and cooperative purchasing consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive acid production insulates margins from Tampa sulfur benchmark spikes. |
| Enhanced-Efficiency Coating Investment | Polymer-encapsulated granules command 15-20% premiums in US Corn Belt. |
| Long-term Supply Agreement | Brazilian cooperatives now exceed 40% of seasonal phosphate offtake. |
| Low-Carbon Production Certification | EU CBAM rewards Saudi and Jordanian rock with inherently lower emissions profiles. |
| Sub-Saharan Distribution Partnership | Ethiopia and Nigeria subsidy programs create volume expansion pathways. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC 10-K filings, and industry association reports through structured interviews with phosphate plant managers, procurement leads at downstream blenders, distribution channel partners, and technical R&D directors. Primary intelligence combines structured interviews with secondary validation through bottom-up and top-down triangulation approaches.
Forecast inputs span product chemistry tiers, application method segmentation, physical form categories, and regional production hub economics across the analysis window. CAGRs derive from demand modeling by crop acreage expansion, subsidy program calibration, and soil testing penetration rates. Sulfur price volatility and cadmium regulatory threshold revisions serve as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Indian rupee subsidy allocation cycles, or European natural gas pricing would shift the trajectory. Forecasts reflect documented assumptions on sulfur input costs, rock phosphate beneficiation yields, and cooperative purchasing consolidation velocity. Quarterly review of Tampa sulfur benchmarks, EFSA contaminant limit proceedings, and ANVISA quality standard enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Sulfur Fertilizer Market