
 Precision Viticulture Market | 2026-2036
Precision Viticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Viticulture Market Intelligence
Multi-source procurement of telemetry and imagery services is broadening as vineyard operators reduce dependence on single-platform vendors. Deere & Company leverages its established dealer network to bundle precision hardware with seasonal financing. Trimble Inc. anchors its position through tightly integrated GNSS correction services and farm management software. AGCO Corporation differentiates via open-platform architecture that accommodates third-party sensor arrays.
Precision viticulture deploys georeferenced sensing, autonomous aerial platforms, and distributed soil monitors to capture within-block variability in vine vigor, moisture, and phenolic development. Spectral indices such as NDVI derived from UAV-mounted cameras guide zonal harvesting decisions that preserve grape uniformity and winery receival efficiency. Sensor networks for irrigation management lead technology deployment because water stress directly binds to fruit chemistry and vintage value. Yield prediction applications are gaining fastest traction among high-value estate wineries that tie block-level forecasts to futures pricing and tank allocation planning.
France's ANSM and Germany's KBA do not regulate viticulture directly, but the EU Green Deal and REACH frameworks constrain agrochemical inputs that precision systems replace through targeted application. The EPA in the United States oversees drone operations under Part 107 waivers that shape how UAV vendors certify platforms for vineyard spray and survey missions. Stakeholders must weigh platform interoperability against regulatory compliance as data sovereignty rules tighten across jurisdictions and cloud-based analytics become standard.
Market Dynamics
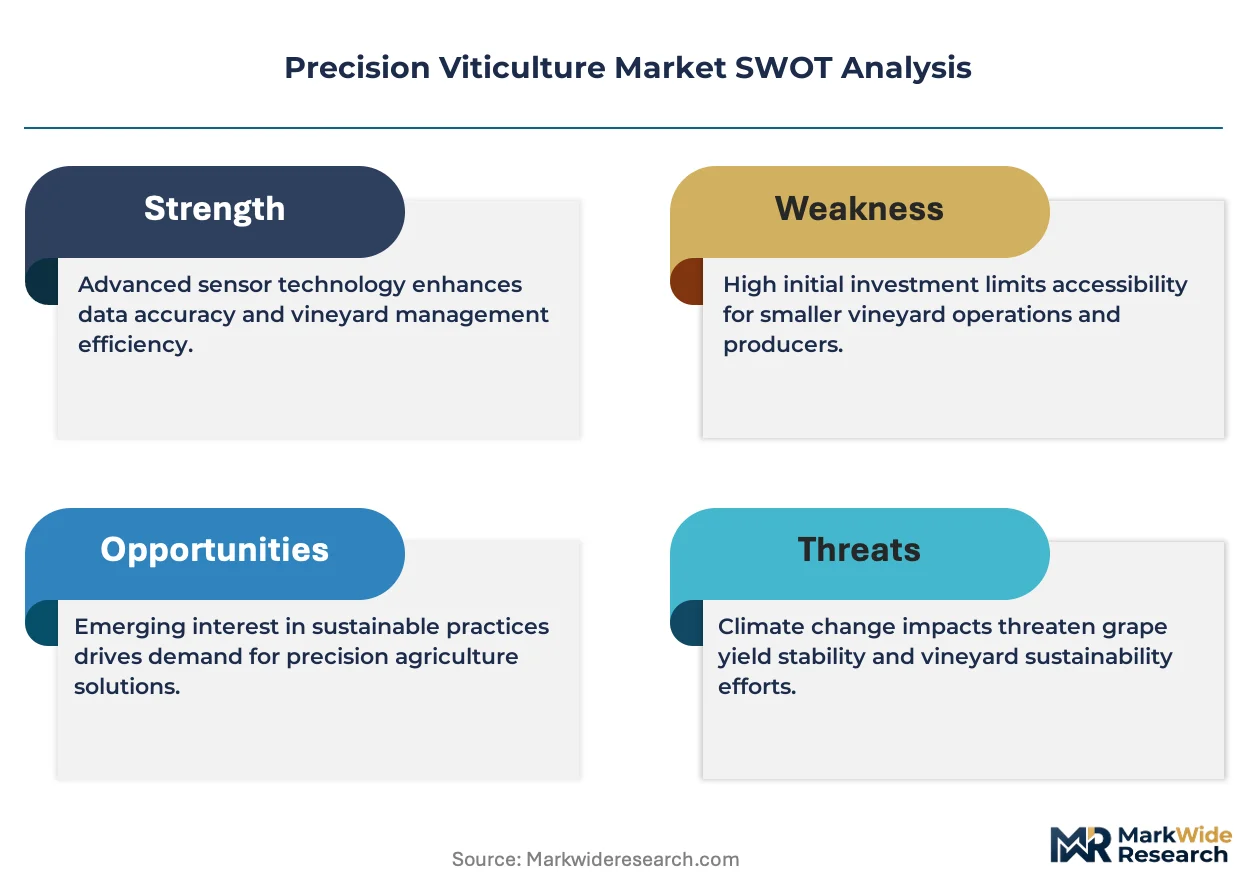
EU Green Deal pesticide reduction mandates are compressing the adoption window for variable-rate application systems, forcing vineyard operators to replace broadcast spraying with sensor-targeted interventions within a single replanting cycle.
Growth Catalysts
- REACH framework chemical restrictions:The European Chemicals Agency's tightening of approved active substances eliminates broad-spectrum options, compelling French and German growers toward precision spot-treatment hardware.
- Drought resilience infrastructure:Australian premium wine regions facing consecutive La Niña failures are prioritizing soil moisture sensor networks as insurance against vintage-quality collapse.
- Canopy management automation:Large Bordeaux and Champagne estates are deploying LiDAR-guided mechanical leaf removal to standardize grape exposure and reduce labor dependency during critical phenological windows.
Market Restraints
- Sensor hardware cost concentration:Multispectral camera modules and GNSS correction subscriptions absorb disproportionate capital from mid-scale operators in Spain and Italy.
- Copper fungicide substitution limits:Organic certification bodies restrict synthetic alternatives, capping the efficacy gains precision application can deliver against downy mildew pressure.
- Technical interoperability gaps:Proprietary data formats between irrigation telemetry platforms and winery management software force redundant manual translation at harvest planning stages.
Strategic Opportunities
- Portuguese Douro Valley penetration:Terrace vineyard topography has historically blocked mechanization, creating first-mover advantage for UAV-based spray and survey services.
- Carbon credit verification protocols:The EU's Carbon Removal Certification Framework creates monetizable pathways for precision irrigation water savings and reduced diesel tractor passes.
- Hyperspectral-phenolic fusion analytics:Convergence of airborne imaging with winery laboratory data streams enables real-time harvest scheduling tied to contract pricing structures.
Industry Challenges
- Viticultural data science talent scarcity:Estate wineries struggle to recruit personnel capable of translating NDVI maps into actionable canopy intervention protocols.
- FAA Part 107 waiver latency:United States operators face extended certification timelines for beyond-visual-line-of-sight drone missions over sprawling Central Coast vineyard blocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Viticulture Market |
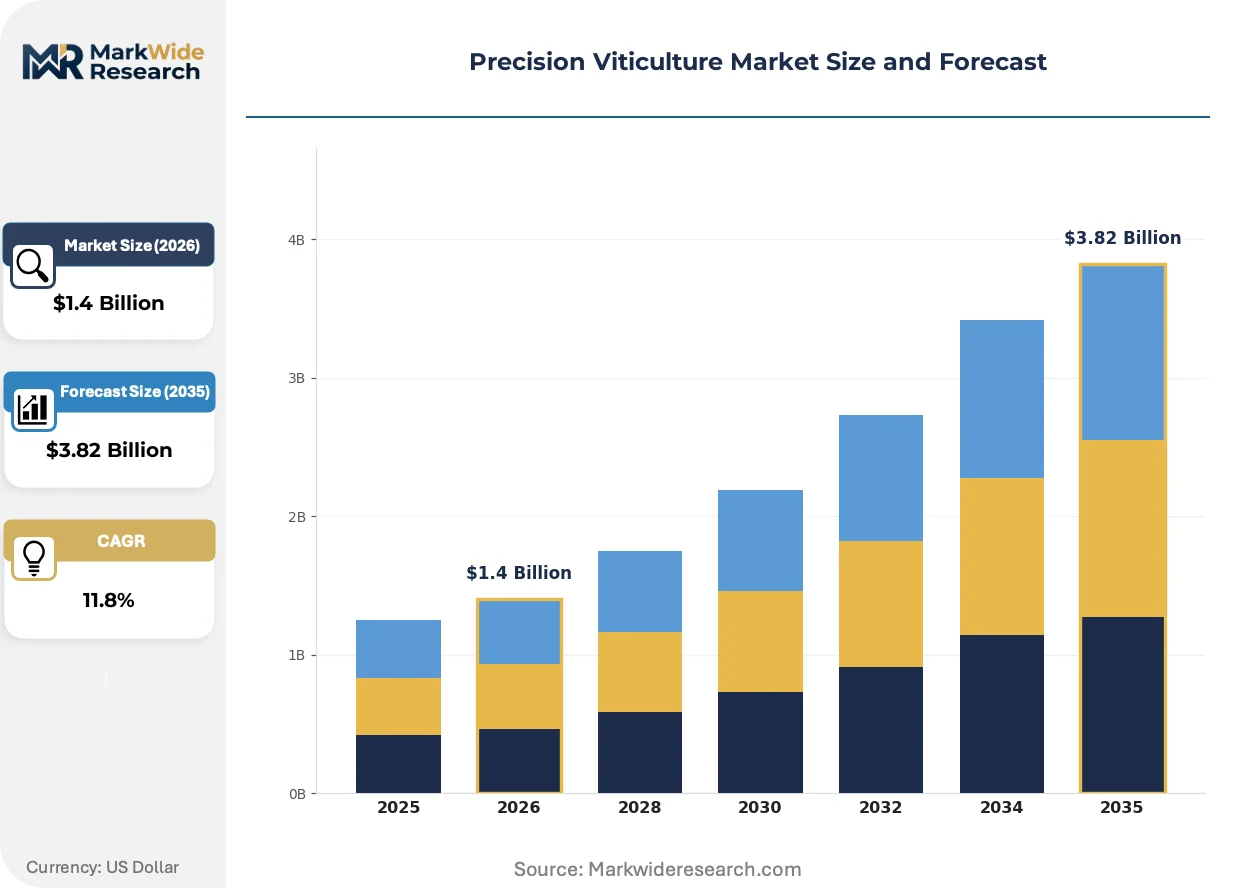
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GIS, UAVs, Sensor Networks, Mobile Applications Application: Irrigation Management, Crop Monitoring, Soil Analysis, Yield Prediction End User: Vineyards, Wineries, Agricultural Consultants, Research Institutions Service Type: Data Analytics, Consulting, Equipment Leasing, Custom Software Development |
| Companies Covered | AGCO Corporation, TeeJet Technologies, Deere & Company, Corteva Inc., Raven Industries Inc., Trimble Inc., Hexagon AB, Valmont Industries Inc., Topcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Viticulture Market Strategic Shifts & Innovations
Telemetry hardware architectures are fragmenting from integrated monoliths toward interoperable component ecosystems, enabling vineyard operators to mix sensor vendors without platform lock-in.
Hyperspectral imaging payloads are modularizing around standardized gimbal interfaces and open API data outputs. Premium Australian estates are adopting these swappable sensor heads to alternate between vegetative vigor mapping and water stress detection within single flight windows. This interoperability is compressing equipment refresh cycles and diluting vendor switching costs.
The EU AI Act's risk classification framework is reclassifying autonomous spray drones as high-risk agricultural equipment. French regulators at ANSM are coordinating with EASA to mandate algorithmic transparency logs for chemical application decision trees. Equipment vendors serving the Loire and Alsace clusters are pre-emptively engineering audit trails to satisfy forthcoming conformity assessment procedures.
Service-based telemetry procurement is displacing capital purchase models among mid-tier cooperatives in Rioja and Piedmont. Annual subscription contracts covering sensor maintenance, data processing, and agronomic interpretation are replacing outright hardware ownership. This shift is most pronounced among operators managing fragmented landholdings who prioritize operational flexibility over asset control.
Precision Viticulture Market Segmentation
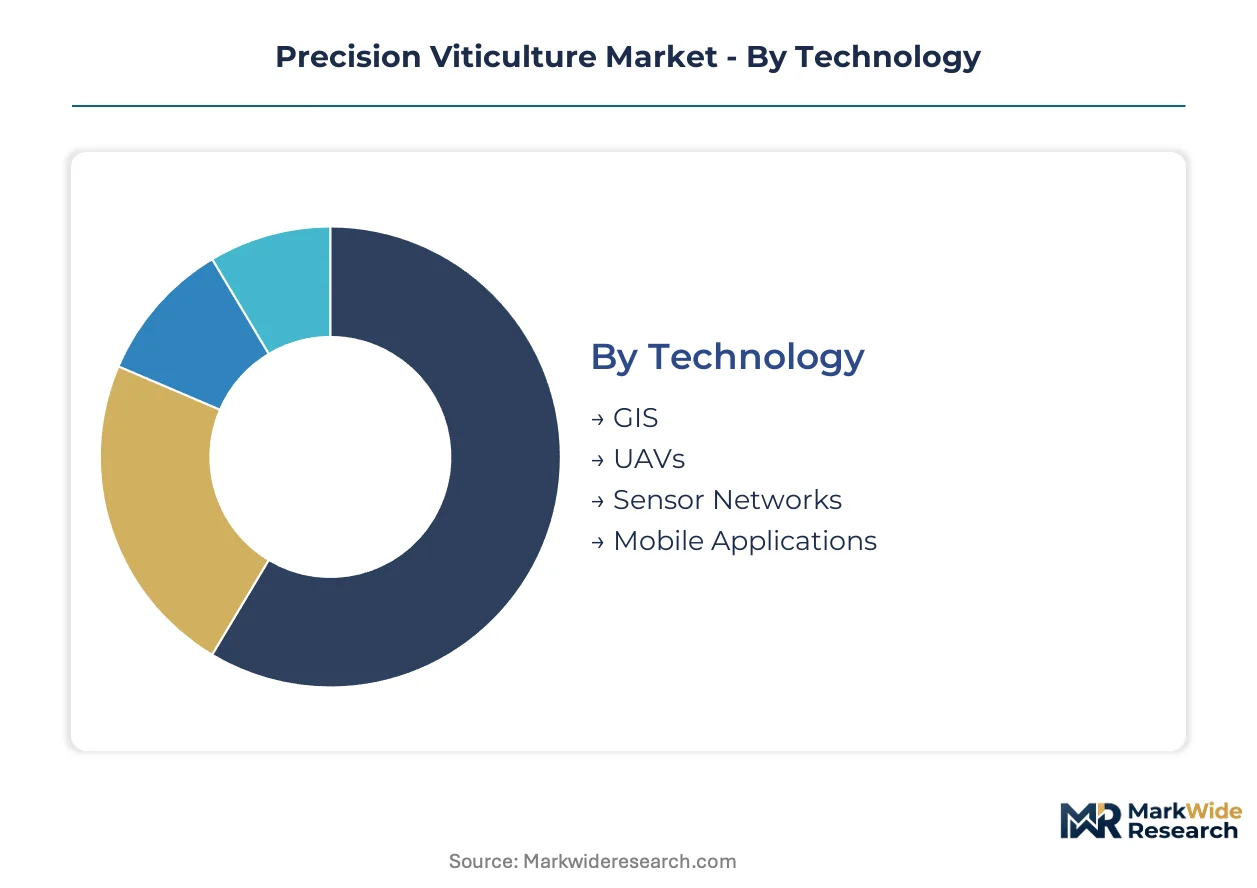
Technology deployment in precision viticulture fragments sharply across vineyard scale and capital availability. Equipment vendors configure modular architectures to capture both estate winery budgets and cooperative procurement patterns.
Technology:
Supply concentration clusters around integrated platform vendors who bundle hardware with recurring data services.
- GIS:Geospatial information systems anchor vineyard block mapping, soil zoning, and historical yield layering. Large Bordeaux and Champagne estates commission sub-meter resolution elevation models to guide drainage investments and machinery routing.
- UAVs:Unmanned aerial vehicles carry multispectral and thermal payloads for canopy vigor assessment. Australian premium regions facing consecutive drought cycles deploy UAV fleets weekly during veraison to detect water stress before fruit chemistry degrades.
- Sensor Networks:Distributed soil moisture and weather stations feed irrigation automation. Spanish Rioja cooperatives favor subscription-based sensor-as-a-service models over capital purchase.
- Mobile Applications:Smartphone-based scouting tools digitize pest observations and phenological tracking. Piedmont consultants bundle mobile apps with seasonal vineyard monitoring contracts.
Today's leader: UAVs. Tomorrow's challenger: Sensor Networks.
Application:
Cost tier separation emerges between water-stress solutions commanding premium pricing and monitoring tools facing commoditization pressure.
- Irrigation Management:Soil moisture telemetry and variable-rate drip systems dominate capital allocation. California Central Valley operators prioritize deficit irrigation scheduling to concentrate berry flavors without yield collapse.
- Crop Monitoring:NDVI mapping and disease detection algorithms guide canopy intervention timing. German Rheingau estates integrate monitoring feeds directly into winery laboratory information management systems.
- Soil Analysis:Electromagnetic conductivity mapping and grid-based sampling reveal within-block variability. Portuguese Douro Valley terrace vineyards deploy portable soil scanners where tractor access is impossible.
- Yield Prediction:Machine learning models fuse spectral indices with historical harvest data. High-value Napa Valley wineries tie block-level forecasts to futures contract pricing and tank allocation planning.
Volume concentrates in Irrigation Management. Margin expansion sits with Yield Prediction.
End User:
Customer type determines procurement modality—estates buy platforms, consultants sell outcomes, cooperatives lease flexibility.
- Vineyards:Grape-growing operations purchase sensor hardware and telemetry subscriptions. Large French commercial estates staff in-house precision viticulture technicians.
- Wineries:Vertical integrators demand harvest scheduling tools linked to receival logistics and fermentation capacity planning.
- Agricultural Consultants:Independent advisors procure multi-client sensor fleets and sell interpretation services to fragmented landholders.
- Research Institutions:Universities and extension services validate algorithms and train regional viticulturists.
Revenue pools deepest with Vineyards. Fastest expansion runs through Agricultural Consultants.
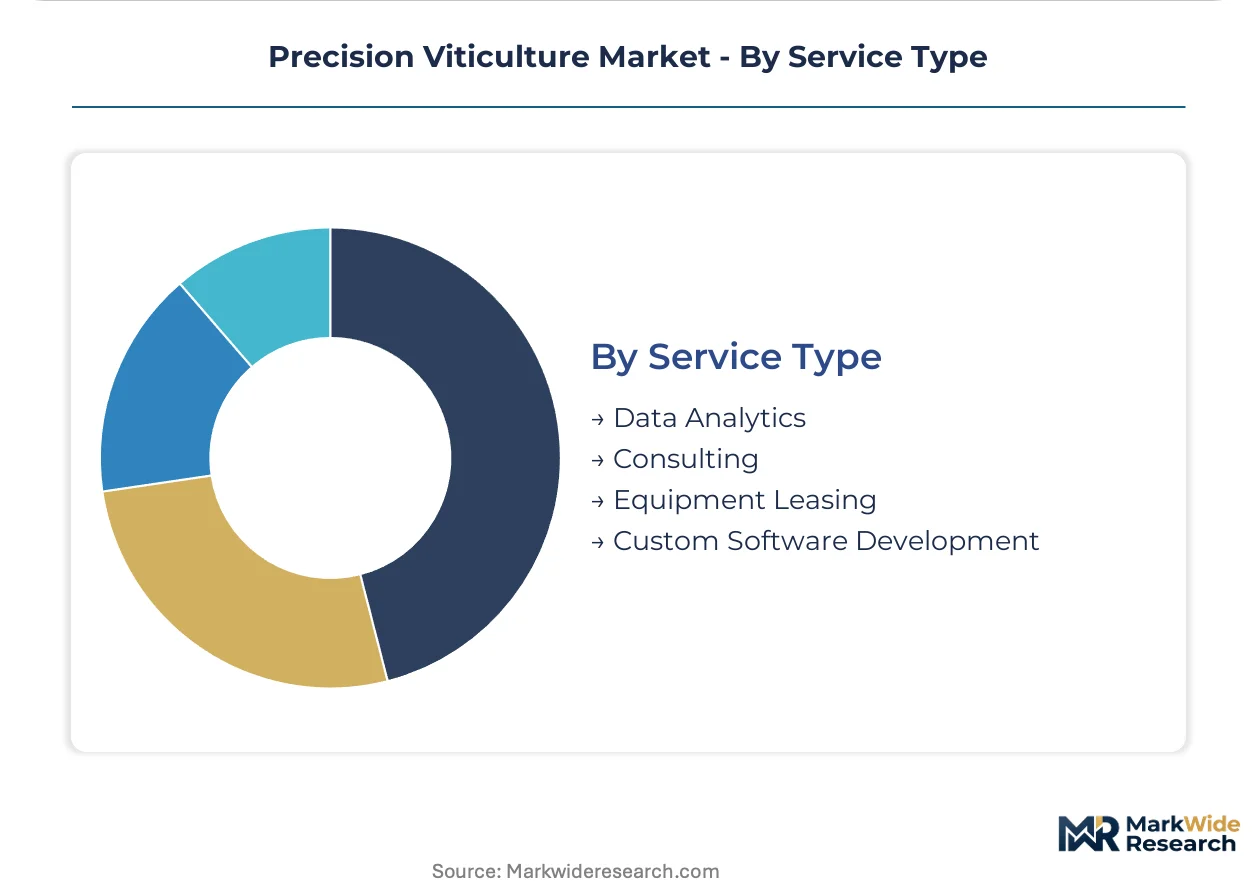
Service Type:
Maturity gradients separate established equipment leasing from nascent carbon credit verification and phenolic fusion analytics.
- Data Analytics:Cloud-based processing of spectral imagery and sensor streams generates prescription maps. Australian drought-response programs subsidize analytics adoption for mid-tier growers.
- Consulting:Agronomic interpretation bridges raw data and canopy intervention decisions. French precision viticulture consultancies face talent scarcity as estate wineries compete for the same data science skills.
- Equipment Leasing:Seasonal UAV and sensor rentals reduce capital barriers for trial adoption. Italian cooperative wineries favor leasing to preserve balance sheet flexibility.
- Custom Software Development:Bespoke integration between telemetry platforms and winery management systems. Loire Valley estates commission API development to automate harvest planning workflows.
Margin leadership belongs to Data Analytics. Steepest expansion trajectory tracks Custom Software Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping capital deployment as EU Green Deal compliance costs push some vineyard operators toward jurisdictions with lighter chemical-application oversight, while drought-risk premiums concentrate precision equipment demand in water-stressed premium wine regions.
France
ANSM coordination with EASA on drone spray certification is compressing equipment approval timelines for Bordeaux and Champagne estates pursuing canopy management automation. The EU Green Deal's Farm to Fork pesticide reduction mandates are forcing replanting-cycle adoption of variable-rate application systems. Large commercial vineyards in Champagne are expanding sensor-guided leaf removal to standardize grape exposure.
Australia
Consecutive La Niña failures have elevated drought resilience to the dominant purchasing criterion for soil moisture sensor networks across premium wine regions. The country's national agricultural regulator subsidizes telemetry adoption through drought-response programs targeting mid-tier growers. South Australian estates deploy weekly UAV flights during veraison to detect water stress before fruit chemistry degrades.
Germany
KBA vehicle standards intersect with vineyard mechanization as Rheingau estates integrate monitoring feeds directly into winery laboratory information management systems. REACH framework restrictions on approved active substances are eliminating broad-spectrum chemical options. Precision spot-treatment hardware demand concentrates in the Rheingau and Mosel clusters facing downy mildew pressure.
United States
EPA oversight of drone operations under Part 107 waivers shapes UAV vendor certification timelines for Central Coast vineyard spray and survey missions. California operators face extended beyond-visual-line-of-sight certification delays over sprawling blocks. Napa Valley wineries tie block-level yield forecasts to futures contract pricing and tank allocation planning.
Spain
Rioja cooperatives favor subscription-based sensor-as-a-service models over capital purchase to preserve balance sheet flexibility across fragmented landholdings. National agricultural extension programs validate precision viticulture algorithms for regional viticulturists. Mid-scale operators in Catalonia and Rioja absorb disproportionate capital burdens from multispectral camera modules and GNSS correction subscriptions.
Precision Viticulture Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue service-based telemetry procurement and carbon credit verification protocols. The vendor base organizes around three strategic archetypes: integrated platform vendors bundling hardware with recurring data services, open-architecture specialists accommodating third-party sensor arrays, and precision-hardware purveyors leveraging established dealer networks for seasonal financing. Dominant competitive moves include strategic partnerships between telemetry providers and winery management software developers, plus geographic expansion into terrace vineyard topography previously blocked from mechanization.
Among integrated platform vendors, Deere & Company and Trimble Inc. exemplify contrasting approaches to customer lock-in. Deere leverages its established dealer network to bundle precision hardware with seasonal financing, occupying a position centered on capital-access convenience. Trimble anchors its positioning through tightly integrated GNSS correction services and farm management software. AGCO Corporation represents the open-architecture alternative, differentiating via platform designs that accommodate third-party sensor arrays and dilute vendor switching costs.
| Leading Market Players |
|---|
| AGCO Corporation |
| TeeJet Technologies |
| Deere & Company |
| Corteva Inc. |
| Raven Industries Inc. |
| Trimble Inc. |
| Hexagon AB |
| Valmont Industries Inc. |
| Topcon Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EU Green Deal-compliant precision systems and conventional equipment bifurcates both pricing power and supply chain sourcing. Premium-tier vendors command 40-60% markups for REACH-validated variable-rate applicators, while procurement teams in France and Germany face extended lead times for sensor modules meeting EASA drone-integration standards.
Pricing Analysis
Distributor margins absorb 15-25% of multispectral camera module costs before vineyard operators see final pricing. Equipment vendors deploy three-tier pricing structure across premium, standard, and economy levels, with premium tiers bundling GNSS correction subscriptions and agronomic interpretation services. Pricing pressure stems from mid-scale Spanish and Italian operators absorbing disproportionate capital burdens from proprietary data format lock-in. Cooperatives in Rioja exhibit highest price sensitivity, while Champagne estates prioritize performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor fabs producing hyperspectral imaging sensors for UAV payloads. Component sourcing draws from Germany for precision GNSS modules, China for lithium-ion power systems, and the United States for cloud-processing infrastructure. Tariff exposure runs through escalating EU-China trade friction affecting telemetry hardware imports. Distribution runs through Deere and Trimble dealer networks in France and Australia, with direct OEM relationships dominating California Central Valley procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision viticulture market compounds regulatory-driven replacement cycles, with EU Green Deal pesticide reduction mandates forcing hardware adoption within single replanting windows.
For Market Incumbents: Deepen backward integration into hyperspectral sensor manufacturing to reduce dependence on Taiwanese semiconductor supply. Anchor market position by pre-certifying drone platforms under forthcoming EASA-EU AI Act conformity procedures before smaller competitors complete audit-trail engineering. Threat substitution looms from open-architecture entrants diluting platform lock-in.
For New Entrants and Emerging Players: Enter via service-based telemetry procurement models targeting fragmented Portuguese Douro Valley terrace vineyards historically blocked from mechanization. White-space concentration sits with carbon credit verification protocols under the EU Carbon Removal Certification Framework. Go-to-market leverage: annual subscription contracts covering sensor maintenance, data processing, and agronomic interpretation.
For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary data format fragmentation forces redundant manual translation at harvest planning stages. Long-term viability favors platforms demonstrating interoperability across irrigation telemetry and winery management software. Acquisition target archetype: precision-hardware purveyors with established seasonal financing relationships. Signal to watch: FAA Part 107 waiver approval velocity for beyond-visual-line-of-sight missions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Interoperability Investment | Open API development dilutes vendor switching costs for Australian drought-response programs. |
| EASA-EU AI Act Pre-Certification | Algorithmic transparency logs satisfy forthcoming conformity assessment procedures for French spray drones. |
| Carbon Credit Verification Protocol Development | Monetizable pathways emerge for precision irrigation water savings under EU Carbon Removal Certification Framework. |
| Sensor-as-a-Service Model Expansion | Subscription contracts preserve balance sheet flexibility for Rioja cooperative wineries. |
| Hyperspectral-Phenolic Fusion Analytics | Real-time harvest scheduling ties block-level forecasts to Napa Valley futures contract pricing. |
Research Approach
Direct dialogue with precision viticulture technicians, vineyard operations managers, agricultural consultants, and winery laboratory directors grounded qualitative findings. Secondary validation drew from EASA drone certification filings, EU Green Deal implementation progress reports, EPA Part 107 waiver databases, and Australian Bureau of Agricultural and Resource Economics drought-response program disclosures. Bottom-up equipment deployment estimates triangulated against top-down addressable vineyard hectare calculations.
Bottom-up modeling segmented the market by technology type, application intensity, and end-user procurement modality across the projection horizon. Analysts modeled GIS, UAV, sensor network, and mobile application adoption curves separately, then cross-referenced against irrigation management, crop monitoring, soil analysis, and yield prediction use-case penetration. CAGRs derived from equipment replacement cycles tied to replanting timelines and regulatory compliance deadlines. Forecast inputs included La Niña drought frequency projections and EU REACH active substance restriction schedules.
Inputs from EASA, EPA, and Australian national agricultural regulators were available through the study window; gaps in real-time carbon credit verification pricing introduce uncertainty bands around service-based revenue projections. Forecasts reflect assumptions about regulatory enforcement consistency and drought resilience infrastructure subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Soil Moisture Sensor Market