
 Charging Nitrogen Gas Systems Market | 2026-2036
Charging Nitrogen Gas Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Charging Nitrogen Gas Systems Market Analysis
A shift from outsourced gas supply contracts toward in-house nitrogen generation and charging infrastructure is realigning capital deployment across industrial facilities. Hale Hamilton leverages its heritage in high-pressure valve engineering to sustain premium positioning in defense and aerospace charging applications. Maximator GmbH anchors its presence through integrated booster-charging system architectures that reduce external dependency for German automotive clients. Hydrotechnik UK Ltd competes on portable calibration and charging unit portability, occupying niche service mobility segments where fixed infrastructure proves uneconomical.
Charging nitrogen gas systems compress and purify nitrogen for injection into hydraulic accumulators, aircraft landing gear, and industrial process vessels, typically achieving output pressures from 3,000 psi to 15,000 psi depending on accumulator specifications and aerospace tire requirements. Fixed systems dominate installed base value due to permanent integration with plant compressed air networks and higher upfront capital commitment, while portable units represent the fastest-expanding category as maintenance departments prioritize field-deployable flexibility for distributed equipment fleets. Cryogenic technology leads the technology segmentation in absolute revenue terms, though membrane separation is gaining traction in mid-pressure manufacturing applications where energy efficiency outweighs ultra-high purity demands.
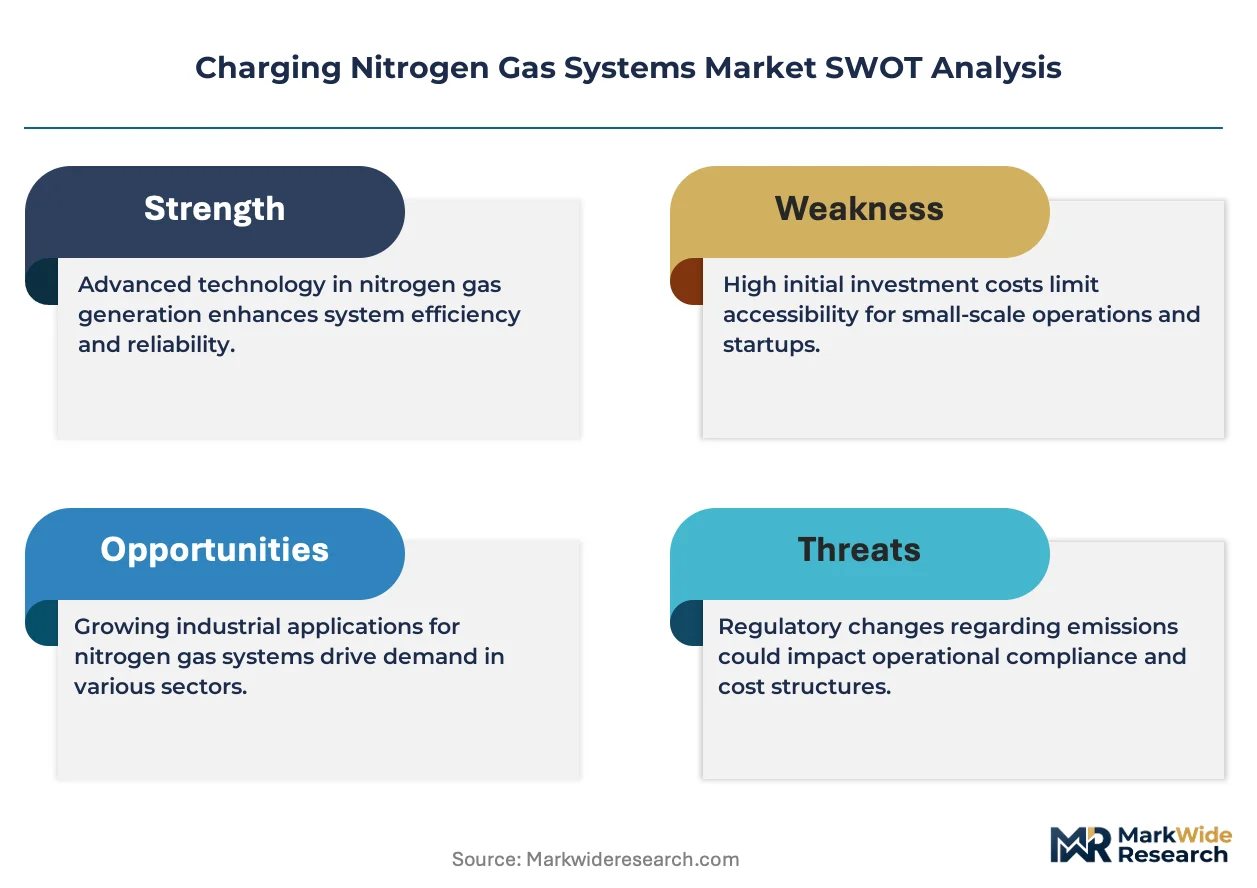
OSHA breathing air standards and FAA maintenance documentation requirements shape product certification pathways for systems serving commercial aviation ground support. The EU F-Gas Regulation and REACH chemical safety protocols constrain refrigerant and lubricant selections in nitrogen generation equipment sold across European member states. Stakeholders must monitor evolving EPA stationary source emissions guidelines and ISO 8573 air purity class specifications as these frameworks increasingly influence procurement specifications and aftermarket service obligations.
Market Dynamics
The transition from bulk nitrogen delivery contracts to on-site generation and charging infrastructure is compressing operational expenditure timelines while elevating capital intensity requirements across industrial facilities. This structural shift is redistributing value capture from gas distributors toward equipment manufacturers and system integrators.
Growth Catalysts
- EU F-Gas Regulation:Industrial facilities across Germany, France, and Italy are accelerating nitrogen system procurement to replace high-global-warming-potential refrigerants in process cooling and accumulator applications.
- Aerospace maintenance expansion:Commercial aviation ground support operations in the United States are mandating nitrogen purity documentation for tire inflation and landing gear servicing, driving certified charging system deployment.
- Membrane separation advancement:Mid-pressure manufacturing applications in automotive hydraulics are adopting membrane-based nitrogen generation to reduce energy consumption versus cryogenic alternatives.
Market Restraints
- Stainless steel and specialty alloy volatility:High-pressure vessel fabrication depends on 316L stainless steel and Inconel components, with price swings directly pressuring system manufacturing margins.
- Compressor supplier concentration:Oil-free high-pressure compressor technology remains concentrated among German and Japanese suppliers, creating single-source vulnerability for system integrators.
- REACH chemical compliance friction:Lubricant and seal material selections for nitrogen generation equipment face extended ECHA registration timelines, delaying product certification cycles.
Strategic Opportunities
- Indian automotive manufacturing:PLI scheme incentives for advanced automotive component production are creating first-mover advantage for nitrogen charging system providers establishing local assembly.
- Offshore wind hydraulic maintenance:Floating turbine installations require portable accumulator charging capabilities at sea, opening marine-certified system development pathways.
- ISO 8573 Class 0 air purity:Food and pharmaceutical packaging applications are mandating oil-free nitrogen generation, expanding addressable market beyond traditional industrial hydraulics.
Industry Challenges
- High-pressure certification expertise shortage:ASME BPVC and PED compliance documentation requires specialized pressure vessel engineering talent that remains scarce in emerging manufacturing hubs.
- Legacy pneumatic infrastructure integration:Brownfield facilities face compressed air network reconfiguration costs when retrofitting nitrogen generation systems alongside existing plant air distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charging Nitrogen Gas Systems Market |
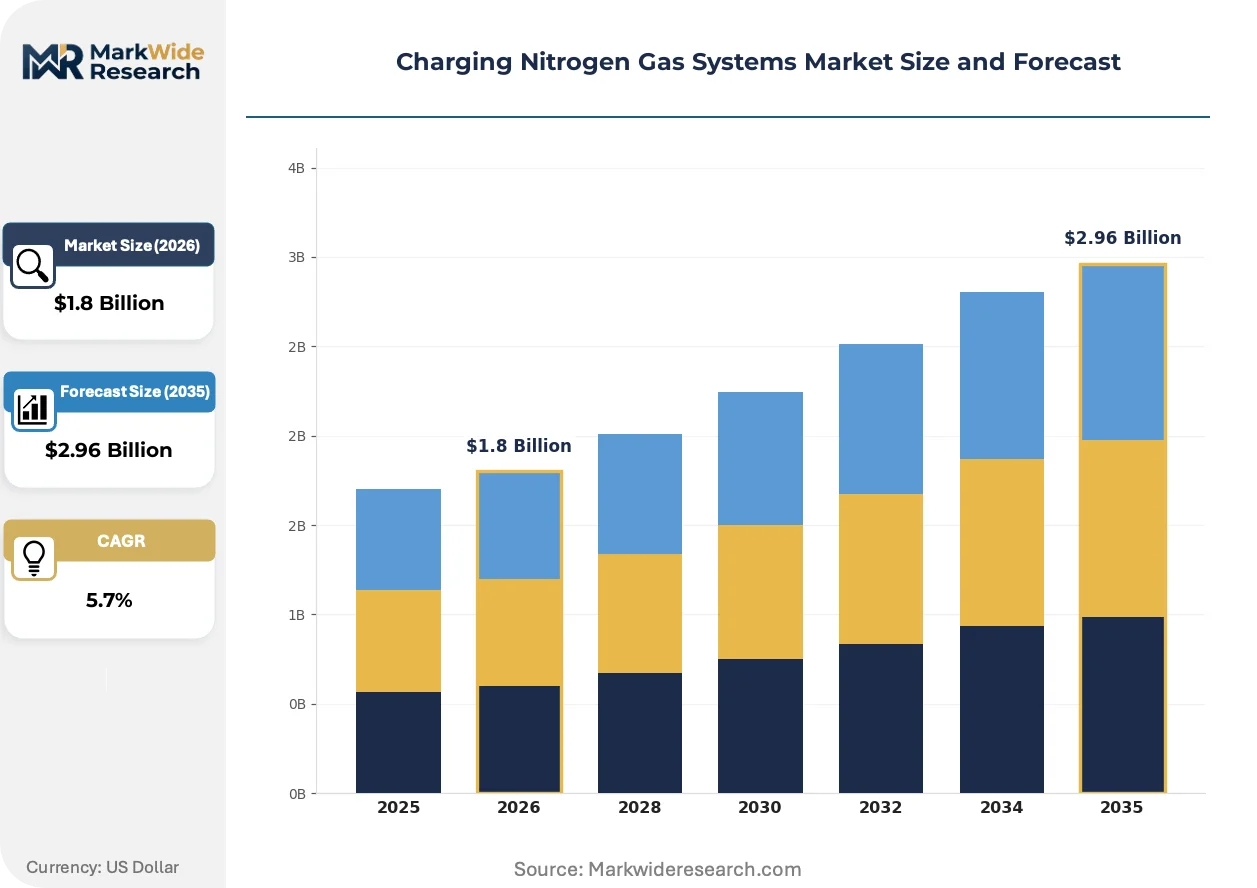
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Portable Units, Fixed Systems, Integrated Solutions, Custom Configurations End User: Manufacturing, Oil & Gas, Aerospace, Food Processing Pressure Rating: Low Pressure, Medium Pressure, High Pressure, Ultra High Pressure Technology: Cryogenic Technology, Membrane Separation, Pressure Swing Adsorption, Absorption |
| Companies Covered | Hale Hamilton, Maximator GmbH, Hydrotechnik UK Ltd, HYDAC International GmbH, Hydraulics International, Inc., Accudyne Industries, Semmco Limited, Air Products and Chemicals, Inc., Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charging Nitrogen Gas Systems Market Emerging Trajectories
Digital pressure monitoring and automated purity verification are displacing manual gauge reading and paper-based documentation workflows across nitrogen charging operations. Equipment suppliers are embedding IoT-enabled diagnostics to capture recurring service revenue and compress response times for distributed maintenance fleets.
Membrane nitrogen generation is consolidating mid-pressure industrial applications where 95-99.5% purity suffices for hydraulic accumulator pre-charging and tire inflation. Automotive tier-one suppliers in Germany and the United States are standardizing membrane-based systems for plant-wide nitrogen distribution, reducing dependency on liquid bulk deliveries. This technology is consolidating supplier relationships as integrated membrane-booster architectures disassemble the previously separate generation and compression procurement decisions.
The EU F-Gas Regulation is forcing refrigerant phase-down timelines that accelerate nitrogen adoption as a process cooling alternative in precision manufacturing. Equipment vendors must now certify systems for F-Gas-compliant refrigerant recovery and nitrogen backfill protocols. German automotive clusters are responding fastest, with OEM procurement specifications already embedding F-Gas transition compliance as a mandatory vendor qualification criterion.
Maintenance departments are unbundling nitrogen charging from bundled gas supply contracts, bringing accumulator servicing and tire inflation capabilities in-house. This pattern is most visible in United States aerospace MRO facilities and German automotive component plants, where fleet scale justifies capital deployment for portable charging units. Third-party gas distributors are responding by repositioning toward equipment leasing and certification training services rather than commodity molecule delivery.
Charging Nitrogen Gas Systems Market Segmentation
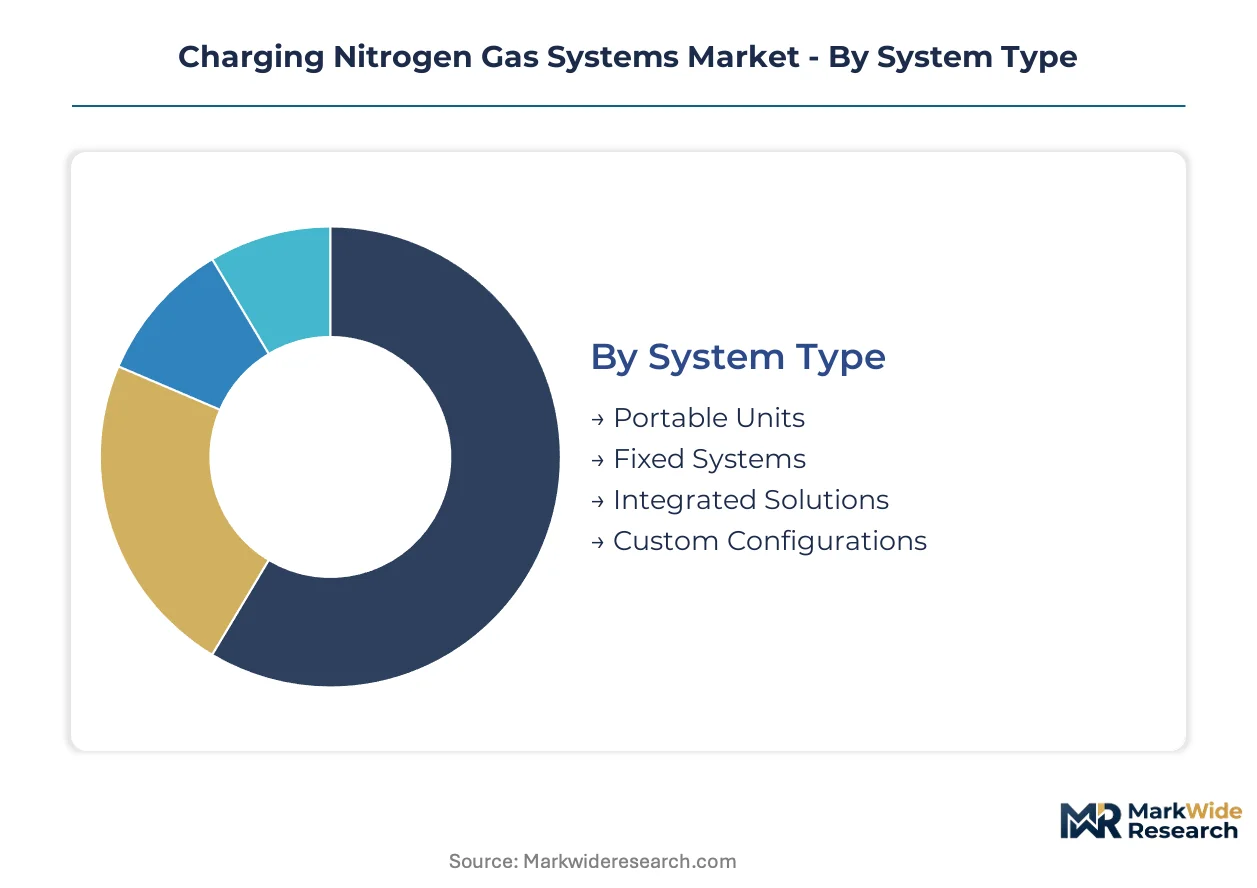
Equipment replacement cycles and facility upgrade timelines vary sharply across nitrogen charging applications, with aerospace MRO departments refreshing portable fleets faster than manufacturing plants overhaul fixed infrastructure. Understanding these divergent renewal patterns is essential for aligning product development and service scheduling with actual procurement windows.
System Type:
Upgrade cycles differentiate sharply between mobile maintenance departments and centralized plant engineering teams, with capital approval thresholds determining refresh timing more than equipment age alone.
- Portable Units:Compact, field-deployable charging systems with wheeled frames and self-contained power supplies enable distributed accumulator servicing across equipment fleets. United States aerospace MRO facilities are refreshing these units on compressed schedules as FAA documentation requirements tighten purity verification protocols for tire inflation operations.
- Fixed Systems:Permanent installations integrate with plant compressed air networks and centralized nitrogen generation, requiring substantial foundation work and piping infrastructure. German automotive component plants favor these configurations for high-volume hydraulic production lines where continuous availability outweighs mobility requirements.
- Integrated Solutions:Combined generation-booster architectures from single suppliers reduce interface complexity for brownfield retrofits.
- Custom Configurations:Engineered-to-order systems address non-standard pressure specifications or hazardous location classifications.
Volume placements concentrate in Fixed Systems; the faster expansion belongs to Portable Units.
End User:
Customer procurement sophistication spans from commodity gas buyers to certified equipment specifiers, with documentation requirements and purity standards fragmenting vendor relationships.
- Manufacturing:Automotive hydraulics and metal forming operations consume nitrogen for accumulator pre-charge and press safety systems. German tier-one suppliers are consolidating membrane-based generation with in-house charging to eliminate bulk liquid delivery contracts.
- Oil & Gas:Offshore platforms and pipeline compressor stations require marine-certified charging units for subsea accumulator maintenance. Floating wind turbine installations are emerging as a specialized demand pocket requiring salt-resistant portable systems.
- Aerospace:Commercial aviation ground support mandates nitrogen purity documentation for landing gear and tire servicing per FAA maintenance protocols.
- Food Processing:Modified atmosphere packaging and oil-free generation requirements are expanding addressable demand beyond traditional industrial hydraulics.
Manufacturing commands the largest installed base; Food Processing is climbing the fastest as ISO 8573 Class 0 specifications penetrate packaging operations.
Pressure Rating:
Application specifications and safety certification burdens escalate disproportionately above 10,000 psi, compressing supplier pools and extending lead times for specialized components.
- High Pressure:Systems delivering 3,000–10,000 psi serve mainstream hydraulic accumulators and commercial aircraft tire inflation, representing the procurement sweet spot for standardization and supplier competition. German automotive clusters specify this range for plant-wide accumulator banks.
- Ultra High Pressure:Output above 10,000 psi addresses military aerospace accumulators, specialized test benches, and research applications requiring ASME BPVC Section VIII certification. Inconel vessel fabrication and specialized compressor sourcing constrain supplier availability.
- Low Pressure:Tire inflation and general industrial purging applications with reduced purity requirements.
- Medium Pressure:Intermediate specifications for food packaging and select manufacturing processes.
High Pressure dominates current procurement volumes; Ultra High Pressure is gaining share fastest as defense aerospace maintenance expands.
Technology:
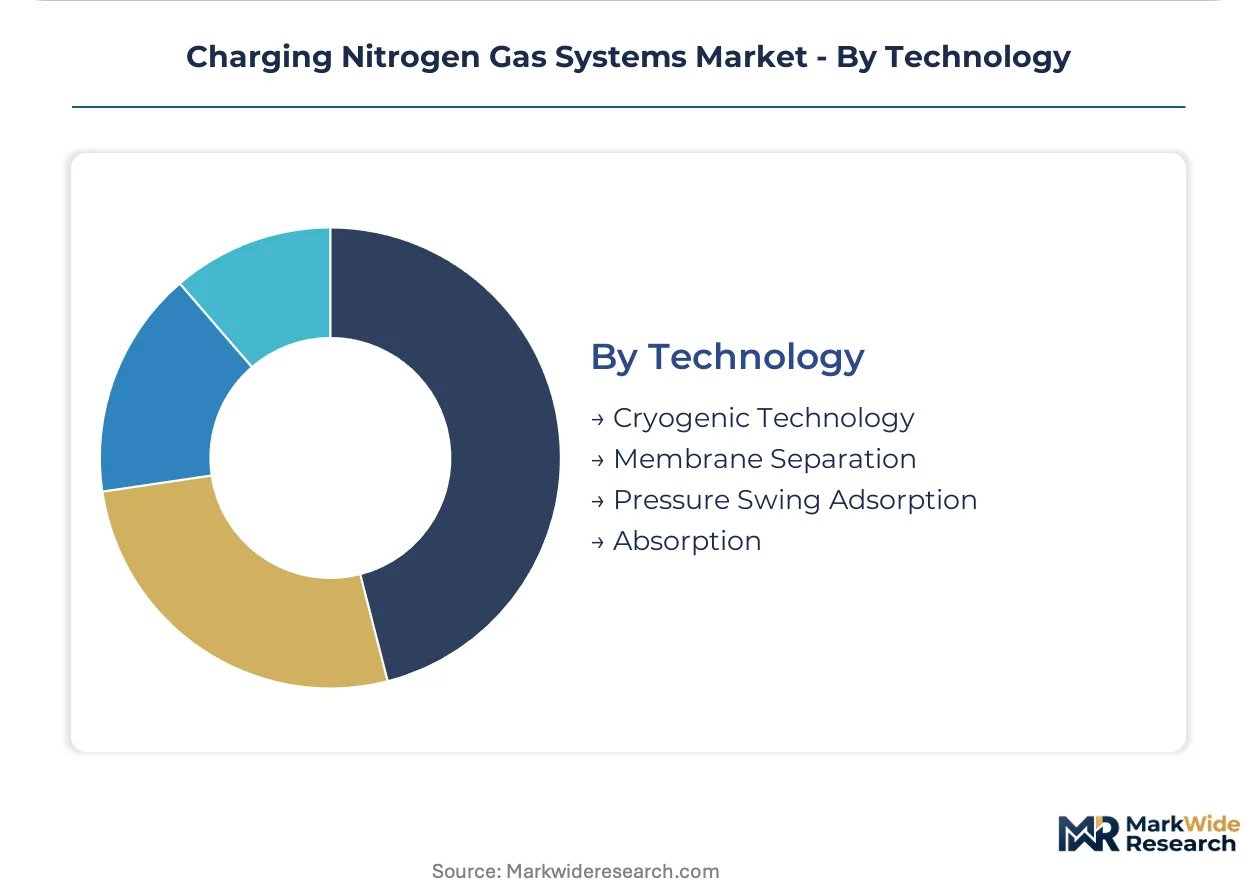
Energy efficiency and purity trade-offs are reconfiguring technology selection criteria, with membrane separation displacing cryogenic alternatives in mid-pressure manufacturing segments.
- Cryogenic Technology:Liquid nitrogen vaporization and compression achieves ultra-high purity for aerospace and specialty chemical applications. German industrial gas majors anchor revenue here through bundled supply contracts, though on-site generation is eroding this position.
- Membrane Separation:Hollow-fiber polymer membranes separate nitrogen from compressed air at 95–99.5% purity, consuming less energy than cryogenic alternatives. United States automotive suppliers are standardizing this technology for plant-wide nitrogen distribution to reduce utility costs.
- Pressure Swing Adsorption:Carbon molecular sieve systems offer purity flexibility between membrane and cryogenic performance.
- Absorption:Chemical scrubbing approaches retain niche applications where specific contaminant removal is required.
Cryogenic Technology retains the revenue base; Membrane Separation is expanding most quickly in mid-pressure manufacturing conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for charging nitrogen gas systems concentrates in industrial clusters with dense aerospace maintenance and automotive hydraulic equipment footprints. Germany, the United States, and emerging manufacturing hubs in India and China anchor procurement volumes. Regulatory pressure from the EU F-Gas Regulation and FAA maintenance protocols is accelerating system upgrades across these markets.
Germany
Automotive tier-one suppliers and hydraulic equipment manufacturers drive consistent demand for membrane-based nitrogen generation systems. The EU F-Gas Regulation compels facilities in Stuttgart and Wolfsburg clusters to replace refrigerant-dependent process cooling with nitrogen alternatives. Bavaria's automotive engineering corridor is standardizing integrated booster-charging architectures to eliminate bulk liquid nitrogen contracts.
United States
Commercial aviation ground support operations and aerospace MRO facilities mandate nitrogen purity documentation for tire inflation and landing gear servicing. FAA maintenance protocols require certified charging systems with automated documentation workflows. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters are refreshing portable charging unit fleets faster than manufacturing plants overhaul fixed infrastructure.
China
Automotive manufacturing expansion and industrial hydraulic equipment production create demand for mid-pressure nitrogen charging capabilities. The country's dual carbon goals pressure facilities toward energy-efficient membrane separation over cryogenic alternatives. Yangtze River Delta manufacturing hubs are adopting on-site generation to reduce dependency on imported bulk gas supplies.
India
PLI scheme incentives for advanced automotive component production attract nitrogen charging system providers establishing local assembly operations. Tamil Nadu and Maharashtra automotive corridors represent first-mover opportunity as tier-one suppliers consolidate membrane-based plant-wide nitrogen distribution. Central pollution control mandates are beginning to constrain refrigerant-based process cooling in favor of nitrogen alternatives.
United Kingdom
North Sea offshore platforms and emerging floating wind installations require marine-certified portable charging units for subsea accumulator maintenance. REACH chemical compliance friction extends lubricant and seal material certification timelines for equipment sold across British manufacturing. Midlands aerospace maintenance facilities are unbundling nitrogen charging from bundled gas supply contracts to bring capabilities in-house.
Charging Nitrogen Gas Systems Market Vendor Landscape
Portfolio diversification dominates the current landscape as equipment manufacturers expand from pure-play charging systems into integrated generation-booster architectures. The vendor base organizes around three strategic archetypes: German-engineered precision fabricators, British portable equipment specialists, and diversified industrial gas majors with bundled supply heritage. M&A activity concentrates on membrane technology acquisitions and regional system integrator roll-ups. Technology licensing agreements are proliferating as mid-tier competitors seek access to oil-free high-pressure compressor designs.
Within the precision-engineering tier, Hale Hamilton and Maximator GmbH exemplify divergent positioning strategies. Hale Hamilton leverages its heritage in high-pressure valve engineering to sustain premium positioning in defense and aerospace charging applications. Maximator GmbH anchors its presence through integrated booster-charging system architectures that reduce external dependency for automotive clients. Hydrotechnik UK Ltd occupies a distinct service mobility segment where portable calibration and charging unit portability proves decisive against fixed infrastructure economics.
| Leading Market Players |
|---|
| Hale Hamilton |
| Maximator GmbH |
| Hydrotechnik UK Ltd |
| HYDAC International GmbH |
| Hydraulics International, Inc. |
| Accudyne Industries |
| Semmco Limited |
| Air Products and Chemicals, Inc. |
| Linde plc |
| Others |
Supply Flow & Price Mechanics
Membrane separation adoption in mid-pressure automotive applications is simultaneously compressing energy costs and redistributing supplier power toward integrated generation-booster architects, narrowing procurement options for German tier-one buyers who previously sourced generation and compression separately.
Pricing Analysis
Warranty and certification bundling separates premium-tier charging system vendors from commodity competitors, with ASME BPVC and PED documentation compliance commanding substantial premiums over uncertified alternatives. Pricing stratifies across certified premium, standard industrial, and economy portable tiers, with certification grade and after-sales service intensity as primary differentiation drivers. Cost compression in the economy portable tier is intensifying because MRO departments are unbundling nitrogen charging from legacy gas supply contracts. Small-scale maintenance operations exhibit highest price sensitivity, while defense aerospace procurement demonstrates lowest sensitivity due to documentation mandates.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese oil-free high-pressure compressor suppliers, constraining system integrator flexibility and extending lead times during demand surges. Component fabrication draws from Germany, Japan, and the United States for 316L stainless steel vessels, Inconel pressure components, and specialized polymer membranes. Tariff exposure on specialty alloys represents the dominant structural risk, with price volatility directly pressuring manufacturing margins. Distribution runs through authorized system integrators and direct OEM relationships, with aftermarket service contracts capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a durable cost-of-compliance moat, with refrigerant phase-down timelines forcing facility upgrades that only certified equipment vendors can service.
For Market Incumbents: Cement ASME BPVC and PED certification depth as non-replicable assets, extending documentation capabilities into emerging marine-certified portable segments before specialized competitors establish footholds. Backward integration into membrane manufacturing reduces dependency on hollow-fiber polymer suppliers concentrated in Japan and the United States. Capacity addition in India captures PLI scheme automotive incentives before tier-one suppliers consolidate procurement relationships. For New Entrants and Emerging Players: Floating wind turbine maintenance operators represent an underserved buyer archetype requiring salt-resistant portable accumulator charging capabilities that incumbent marine certification portfolios currently lack. Offshore hydraulic maintenance in the North Sea and emerging Asian wind clusters offers the most penetrable geographic pocket. Partnership with established marine classification societies accelerates certification timelines and de-risks market entry. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial gas majors seeking membrane technology integration and regional system integrator roll-ups. The five-to-ten year viability window favors targets with established F-Gas transition compliance credentials and automotive OEM procurement relationships. Watch for inflection when FAA maintenance protocols expand purity documentation requirements beyond tire inflation into additional ground support equipment categories.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Acquisition | Captures energy-efficient nitrogen generation share from cryogenic incumbents in automotive hydraulics. |
| Marine Certification Investment | Unlocks offshore wind and subsea accumulator maintenance demand in North Sea clusters. |
| Backward Integration into Compressor Manufacturing | Reduces single-source vulnerability to German and Japanese oil-free high-pressure suppliers. |
| Regional System Integrator Roll-up | Consolidates fragmented service networks in India and China automotive corridors. |
| IoT-Enabled Diagnostics Platform | Captures recurring service revenue from distributed aerospace MRO fleet maintenance contracts. |
Methodological Framework
Multi-period observation of membrane adoption rates, F-Gas compliance timelines, and aerospace MRO fleet refresh cycles anchored the trend analysis, supplemented by interviews with plant engineers at German automotive tier-one suppliers, maintenance directors at United States aerospace facilities, procurement leads at offshore wind developers, aftermarket service heads at nitrogen system distributors, and technical R&D directors at membrane manufacturers. Secondary validation drew from SEC filings of industrial gas majors, ECHA REACH registration databases, FAA maintenance protocol documentation, customs trade data on high-pressure vessel imports, and ISO 8573 air purity certification records. Bottom-up equipment shipment tracking and top-down industrial gas market sizing were triangulated to constrain forecast variance.
The input-output matrix mapped nitrogen generation technology selection to end-use purity requirements, pressure specifications, and energy cost structures across the projection horizon. Segmentation dimensions modeled include system mobility classification, pressure rating tier, generation technology type, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and facility upgrade timeline elasticity. Industry-specific forecast inputs incorporated EU F-Gas refrigerant phase-down schedules and FAA documentation protocol expansion trajectories.
Revisions become necessary when specialty alloy price volatility exceeds historical bands, when compressor supplier concentration shifts through acquisition or capacity expansion, or when REACH chemical compliance timelines extend beyond current ECHA registration trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Power Stacker Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
AC Motor Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Germany AC Motor Market