
 Belgium Electric Vehicle Charging Equipment Market | 2026-2036
Belgium Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Electric Vehicle Charging Equipment Market Insights
Vehicle-to-grid bidirectional power flow is tilting charger architecture toward embedded energy management systems. ABB Ltd leverages its traction in high-power DC hardware to anchor utility-scale depot installations. Tesla Inc. competes through proprietary connector ecosystems and destination charging density along Belgian motorway corridors. Alfen N.V. specializes in modular grid integration, sustaining market presence through scalable load-balancing firmware.
Electric vehicle charging equipment comprises power conversion, control, and connectivity subsystems engineered to deliver controlled electrical energy to onboard battery packs, typically spanning output ratings from 3.7 kW residential AC to 350 kW commercial DC. The primary purpose centers on replenishing stored electrochemical energy while managing thermal constraints, grid harmonics, and user authentication protocols. DC fast chargers command premium positioning due to capital intensity and site preparation requirements, whereas residential AC units occupy volume leadership through distributed private ownership. Smart charging technology segments attract R&D allocation as utilities and fleet operators seek dynamic load modulation to avoid peak-demand penalties.
Flanders enforces building-code pre-wiring mandates for new residential construction, while Brussels-Capital operates regional subsidy schemes administered through Brussels Environment. The EU Green Deal and national transposition through Belgium's federal energy efficiency obligations shape product efficiency benchmarks and interoperability certification. Stakeholders must monitor pending revisions to the EU Alternative Fuels Infrastructure Regulation and their Belgian implementation timeline, as these will determine minimum power-output requirements at public charging sites and influence capital deployment priorities across private and public capital stacks.
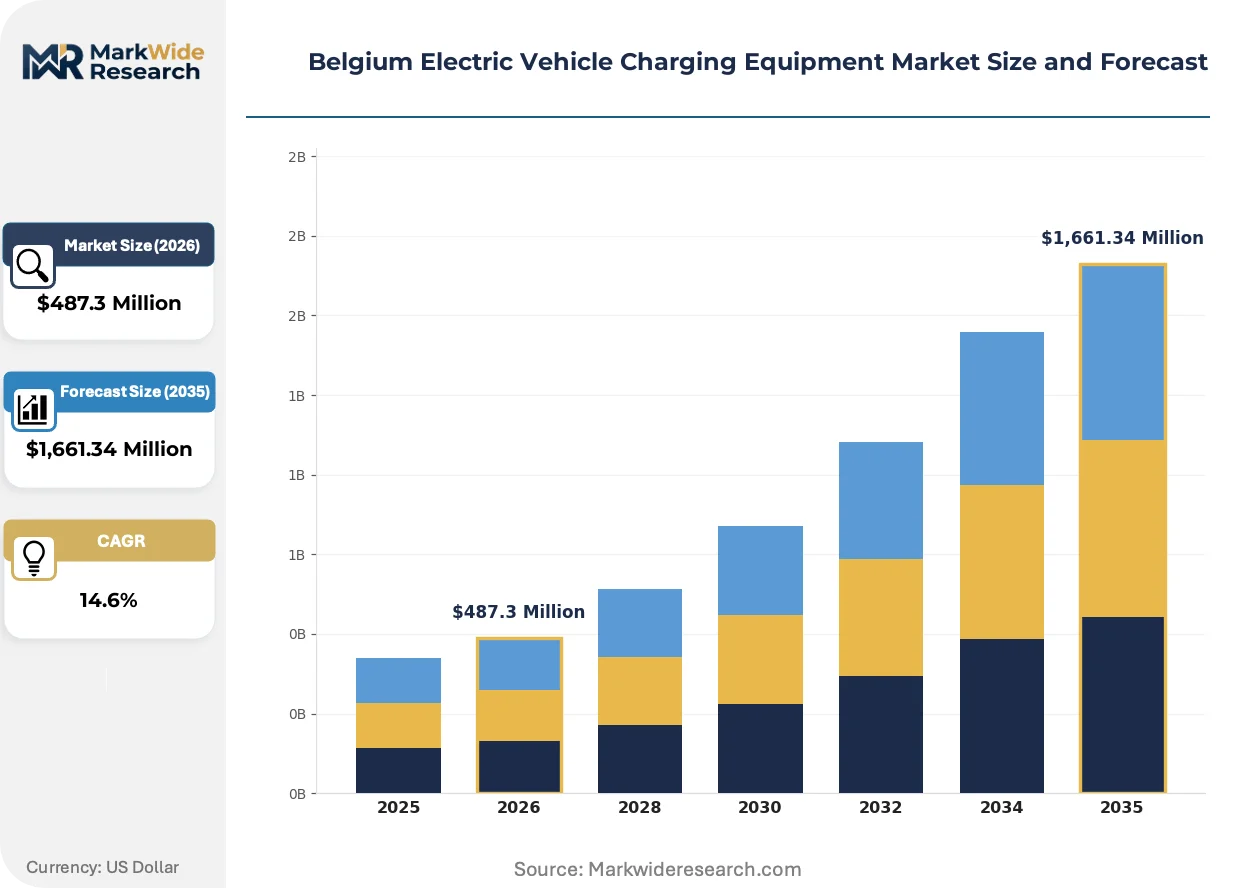
Market Dynamics
Vehicle-to-grid bidirectional power flow is collapsing charger architecture toward embedded energy management systems, forcing hardware vendors to integrate software-defined load balancing or cede positioning to grid-technology specialists.
Growth Catalysts
- EU Green Deal transposition:Belgium's federal energy efficiency obligations mandate interoperability certification and product efficiency benchmarks, accelerating replacement cycles for legacy AC units.
- Flanders building-code pre-wiring:New residential construction must include EV-ready electrical infrastructure, embedding charging capacity into housing stock before vehicle ownership materializes.
- Last-mile delivery electrification:Ride-hail and urban logistics operators in Brussels-Capital are scaling DC fast charger deployment to minimize fleet downtime.
Market Restraints
- Copper and silicon carbide cost volatility:Power electronics input prices fluctuate with commodity markets, compressing margins on high-wattage DC hardware.
- Site preparation capital intensity:Grid connection upgrades and civil works for commercial DC installations absorb 40-60% of project budgets, deterring smaller operators.
- Pending AFIR revision uncertainty:The EU Alternative Fuels Infrastructure Regulation's minimum power-output requirements remain unresolved, freezing some public-site investment decisions.
Strategic Opportunities
- Wallonia fleet depot electrification:Corporate logistics hubs outside Brussels-Capital show lower charger density, offering first-mover positioning for utility-scale installations.
- Dynamic load modulation firmware:Smart charging technology segments attract R&D allocation as utilities seek peak-demand penalty avoidance through software-controlled power curves.
- Brussels Environment subsidy schemes:Regional capital support for public charging infrastructure reduces payback periods for qualified deployment projects.
Industry Challenges
- Grid harmonics engineering scarcity:Specialized power-quality expertise for high-voltage connection compliance remains concentrated among incumbent electrical contractors.
- Legacy payment system integration:Roaming interoperability between proprietary authentication protocols and open-network standards requires middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Electric Vehicle Charging Equipment Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Inductive Chargers Charging Technology: Plug-in, Conductive, Inductive, Battery Swapping, Smart Charging Installation Site: Residential, Commercial Facilities, Public Parking, Workplace, Fleet Depots End User: Private Owners, Corporate Fleets, Public Transit Authorities, Car Rental Companies, Delivery Services |
| Companies Covered | ABB Ltd, Tesla Inc., Wallbox Chargers, S.L., Alfen N.V., EV-Box, Allego, TotalEnergies, Heliox, IONITY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Electric Vehicle Charging Equipment Market Trends and Innovations
Belgium's charging equipment market is experiencing compressed technology cycles where hardware commoditization and software differentiation are occurring simultaneously, reshaping vendor competitive moats.
Silicon carbide power semiconductors are collapsing thermal management requirements in high-frequency conversion stages. Fleet operators deploying 150-350 kW DC hardware are specifying SiC-based designs to reduce cooling system footprint and site preparation costs. This compression is enabling smaller-footprint urban installations previously constrained by ventilation infrastructure.
EU Green Deal implementation through Belgium's federal structure is creating divergent regional compliance timelines. Flanders enforces building-code mandates earlier than Wallonia's voluntary incentive structures, fragmenting product certification requirements across the national territory. Charger vendors must maintain dual SKU configurations or absorb customization costs.
Service unbundling is separating hardware procurement from software subscriptions and maintenance contracts. Fleet managers in Antwerp and Ghent are negotiating multi-year service agreements independent of initial capital purchases, shifting vendor revenue toward recurring streams. This restructuring favors providers with captive software development rather than pure hardware manufacturers.
Belgium Electric Vehicle Charging Equipment Market Segmentation
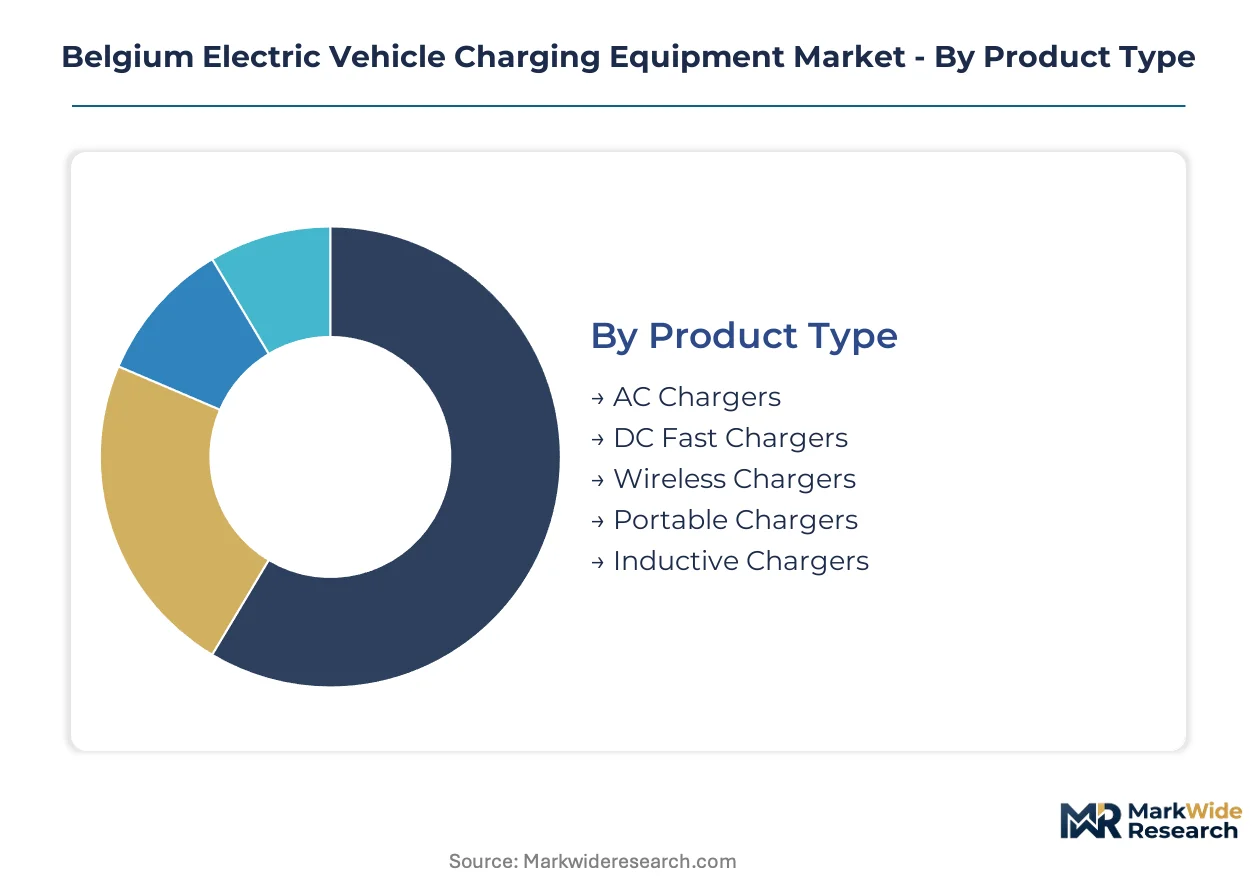
Segmentation in Belgium's charging equipment market exposes divergent capital deployment patterns across power ratings, installation complexity, and ownership models. Understanding these divides reveals where hardware commoditization pressures concentrate versus where software and service premiums persist.
Product Type:
Power output specifications and thermal management requirements fragment the hardware landscape across use cases from overnight residential replenishment to fleet turnaround operations.
- AC Chargers:Single-phase and three-phase alternating current units deliver 3.7 kW to 22 kW through onboard vehicle rectifiers. Flanders building-code pre-wiring mandates embed these into new residential construction before vehicle ownership materializes, creating latent infrastructure capacity.
- DC Fast Chargers:Direct current hardware bypasses onboard conversion to deliver 50 kW to 350 kW through high-power electronics. Brussels-Capital ride-hail and last-mile delivery operators specify these for sub-30-minute turnaround, absorbing 40-60% of project budgets in grid upgrades and civil works.
- Wireless Chargers:Inductive power transfer systems eliminate connector wear in automated fleet environments.
- Portable Chargers:Mobile emergency units address range anxiety in early EV adoption phases.
- Inductive Chargers:Embedded road-surface systems remain pilot-stage for bus rapid transit corridors.
Established volume favors AC Chargers; emerging adoption favors DC Fast Chargers.
Charging Technology:
Interface protocols and energy management intelligence separate commodity hardware from value-added service platforms.
- Plug-in:Physical connector systems dominate current deployment, with CCS2 and Type 2 standards mandated by EU interoperability certification. Brussels Environment subsidy schemes require open-network protocol compliance, freezing out proprietary authentication systems from public funding.
- Smart Charging:Software-defined load modulation enables dynamic power curve adjustment based on grid conditions, electricity pricing signals, and fleet dispatch schedules. Utilities and fleet operators allocate R&D toward this segment to avoid peak-demand penalties and reduce connection upgrade costs.
- Conductive:Direct electrical contact through standardized connectors.
- Inductive:Electromagnetic field transfer without physical connection.
- Battery Swapping:Stationary exchange of depleted packs for charged units, limited to commercial vehicle pilots.
Plug-in systems anchor near-term deployment; Smart Charging commands the steepest expansion trajectory as grid integration tightens.
Installation Site:
Site preparation requirements and utilization patterns determine capital recovery timelines and ownership structures.
- Residential:Private parking installations leverage existing electrical connections for overnight charging. Flanders mandates EV-ready pre-wiring in new construction, embedding capacity ahead of demand.
- Fleet Depots:Centralized high-power hubs serve corporate logistics and public transit with scheduled charging windows. Wallonia shows lower charger density here, offering first-mover positioning for utility-scale installations.
- Commercial Facilities:Retail and hospitality destination charging attracts dwell-time customers.
- Public Parking:Curbside and garage installations face roaming interoperability complexity between proprietary and open-network standards.
- Workplace:Employer-subsidized charging extends daily electric range for commuters.
Residential deployment scales through regulatory embedding; Fleet Depots concentrate investment as electrification mandates tighten.
End User:
Ownership models and utilization intensity separate price-sensitive individual purchasers from Total Cost of Ownership-driven fleet managers.
- Corporate Fleets:Logistics operators and ride-hail platforms negotiate multi-year service agreements independent of hardware procurement, shifting vendor revenue toward recurring software and maintenance streams. Antwerp and Ghent deployments favor providers with captive firmware development.
- Delivery Services:Urban last-mile operators in Brussels-Capital deploy DC fast charging to minimize vehicle downtime between shifts, with dense urban deployment patterns constraining site selection.
- Private Owners:Individual households dominate unit volume but fragment purchasing decisions.
- Public Transit Authorities:Municipal bus and tram electrification programs specify depot-based overnight charging.
- Car Rental Companies:Short-term vehicle providers face utilization uncertainty in charging infrastructure planning.
Private Owners drive AC hardware volume; Corporate Fleets and Delivery Services concentrate DC fast charging investment and software subscription value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German charging hardware exports flow into Belgian fleet depots and motorway corridors, anchoring cross-border supply relationships that shape procurement patterns in Flanders and Wallonia.
Flanders
Corporate logistics operators and port authorities drive depot electrification around Antwerp and Ghent. The region enforces building-code pre-wiring mandates for new residential construction through its provincial implementation of federal energy efficiency obligations. High-power DC clusters concentrate along the E17 and E40 motorway corridors serving international freight flows.
Brussels-Capital
Ride-hail platforms and last-mile delivery services generate concentrated demand for sub-30-minute turnaround infrastructure. Brussels Environment administers regional subsidy schemes that require open-network protocol compliance for public funding eligibility. Dense urban deployment of 150-350 kW hardware characterizes the Pentagon and European Quarter districts.
Wallonia
Industrial zones around Liège and Charleroi show lower charger density, creating first-mover positioning for utility-scale installations serving manufacturing supply chains. The region operates voluntary incentive structures rather than mandatory building codes, fragmenting compliance timelines against Flanders. Logistics hubs along the Sambre-Meuse valley attract fleet electrification investment.
Netherlands
Cross-border procurement patterns see Dutch hardware vendors and installation contractors serve Belgian demand through integrated Benelux supply chains. The country's national charging infrastructure registry provides interoperability models that Belgian regulators reference in AFIR transposition planning. Rotterdam-Antwerp port corridor electrification programs coordinate depot charging standards.
France
French energy majors and equipment suppliers compete for positioning in Belgian public charging through motorway service station partnerships. The country's national low-emission zone regulations provide regulatory precedent that Brussels and Antwerp authorities adapt for local implementation. Lille metropolitan area charging networks extend service coverage into Hainaut province.
Belgium Electric Vehicle Charging Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware procurement, software integration, and long-term service contracting. The market exhibits tiered concentration where scale-driven electrical conglomerates anchor high-power DC installations while modular specialists capture residential and light commercial segments. Three archetypes dominate: integrated energy-hardware conglomerates, pure-play charging technology developers, and grid-technology specialists with captive firmware capabilities. Competitive moves center on multi-year service agreement unbundling and silicon carbide power electronics transitions that compress thermal management footprints.
Within the integrated conglomerate tier, ABB Ltd and TotalEnergies occupy positions spanning high-power hardware manufacturing through to site preparation and grid connection contracting. Tesla Inc. exemplifies the ecosystem-locked archetype through proprietary connector deployment and destination charging density along Belgian motorway corridors. Alfen N.V. sits within the grid-technology specialist tier, representing modular integration approaches that emphasize scalable load-balancing firmware over pure hardware specifications.
| Leading Market Players |
|---|
| ABB Ltd |
| Tesla Inc. |
| Wallbox Chargers, S.L. |
| Alfen N.V. |
| EV-Box |
| Allego |
| TotalEnergies |
| Heliox |
| IONITY |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp port corridor's freight cost dynamics concentrate supply-side power among German and Dutch electrical conglomerates while forcing three-tier pricing stratification across premium silicon carbide hardware, standard silicon-based units, and economy-grade residential AC equipment.
Pricing Analysis
Silicon carbide versus silicon-based power electronics pricing gaps separate current-generation 350 kW DC hardware from prior-generation 150 kW units and emerging 500 kW next-generation prototypes. Project-based contracting dominates high-power DC installations, with price differentiation resting on CE certification tier and after-sales service bundling. Cost compression in economy AC tiers is intensifying because Flanders building-code mandates commoditize basic residential units. Private owners show highest price sensitivity; corporate fleet managers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
EU dual-use export controls on wide-bandgap semiconductor manufacturing equipment limit flows of silicon carbide wafer production technology to Chinese foundries, reshaping sourcing patterns. Power electronics supply concentrates in Germany, the Netherlands, and Taiwan for high-frequency conversion modules. Raw material dependencies center on copper busbars, silicon carbide substrates, and rare-earth magnetic components. Single-source vulnerability in silicon carbide wafer supply creates structural risk for 150-350 kW DC charger production. Distribution runs through integrated electrical contractors who bundle hardware procurement with grid connection and civil works.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent charging equipment vendors face substitution pressure from grid-technology specialists embedding software-defined load balancing, requiring defensive repositioning to protect hardware margins against firmware-centric competitors.
For Market Incumbents: Entrench positioning through backward integration into silicon carbide power semiconductor sourcing and captive development of dynamic load modulation firmware. ABB Ltd and Alfen N.V. demonstrate this defensive pattern by anchoring utility-scale depot installations while building software subscription revenue streams. Threat from Tesla Inc.'s proprietary connector ecosystem requires interoperability certification investment to maintain public funding eligibility under Brussels Environment schemes.
For New Entrants and Emerging Players: Wallonia fleet depot electrification offers the most penetrable white-space target, with industrial zones around Liège and Charleroi showing 40-60% lower charger density than Flanders counterparts. Target corporate logistics hubs along the Sambre-Meuse valley with utility-scale installation capabilities. Go-to-market angle should emphasize multi-year service agreement unbundling separate from hardware procurement, mirroring Antwerp and Ghent fleet manager purchasing patterns.
For Investors and Strategic Acquirers: Grid-technology specialists with captive firmware capabilities represent the priority acquisition archetype, as hardware commoditization accelerates software differentiation. Long-term viability across the projection horizon hinges on silicon carbide transition completion and AFIR regulatory clarity. Watch pending EU Alternative Fuels Infrastructure Regulation minimum power-output requirements as the critical inflection signal determining capital deployment priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Transition | Reduces thermal management footprint and site preparation costs for 350 kW urban installations. |
| Dynamic Load Modulation Firmware Development | Enables utilities and fleet operators to avoid peak-demand penalties through software-controlled power curves. |
| Wallonia Fleet Depot Electrification Expansion | Captures first-mover positioning in underpenetrated industrial zones around Liège and Charleroi. |
| AFIR Compliance Certification Investment | Secures public funding eligibility under Brussels Environment subsidy schemes requiring open-network protocols. |
| Multi-Year Service Agreement Unbundling | Shifts vendor revenue toward recurring software and maintenance streams independent of hardware procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with charging equipment procurement managers at corporate fleet operators, grid integration engineers at distribution system operators, and site preparation contractors across Flanders and Wallonia; and secondary validation against EU Green Deal implementation documents, Flanders building-code regulatory filings, Brussels Environment subsidy scheme disclosures, and silicon carbide supply chain trade data. Bottom-up unit deployment estimates triangulated against top-down federal energy efficiency obligation spending allocations.
Forecast inputs considered power output specifications, installation site categories, and end-user ownership models across the analysis window. Segmentation dimensions modeled included AC versus DC hardware types, smart charging technology adoption curves, and regional regulatory framework clusters. CAGRs derived from installed base growth trajectories, replacement cycle acceleration under efficiency mandates, and fleet electrification program commitments. Industry-specific inputs incorporated AFIR transposition timelines and silicon carbide cost curve projections.
Practitioners should monitor EU Alternative Fuels Infrastructure Regulation revision outcomes and silicon carbide substrate supply disruptions for early signals of forecast deviation. Forecasts reflect assumptions regarding federal energy efficiency obligation continuity and regional subsidy scheme funding levels. Material shifts in copper commodity pricing or grid connection upgrade cost inflation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market