
 Japan AC Motor Market | 2026-2036
Japan AC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Japan AC Motor Market Insights
OEM-direct supply contracts is rewriting procurement pathways for Japanese AC motor manufacturers. Nidec Corporation leverages its dominant position in hard disk drive spindle motors to cross-sell industrial AC solutions. Yaskawa Electric Corporation anchors the servo and motion control segment through deep integration with robotics OEMs. Mitsubishi Electric Corporation competes on system-level sales combining AC motors with inverters and PLCs.
An AC motor converts alternating current into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, typically operating at fixed or variable speeds depending on pole configuration and supply frequency control. These machines power conveyor systems, pumps, compressors, and machine tools across Japanese manufacturing facilities. Induction motors occupy the largest installed base due to decades of standardization in general industrial applications, while servo motors capture the fastest expansion as semiconductor and electronics assembly lines demand precise position control. Variable frequency drives paired with AC motors are displacing fixed-speed installations in HVAC and process industries, creating margin pools for integrated motor-drive packages.
METI enforces motor efficiency regulations through the Top Runner Program, compelling manufacturers to meet progressively stricter IE4 and IE5 performance tiers. JIS standards govern dimensional interchangeability and testing protocols, while PMDA oversight applies where motors interface with certified medical devices. Stakeholders must monitor how METI's carbon neutrality roadmap tightens efficiency mandates and whether domestic semiconductor shortages constrain variable frequency drive production.
Market Dynamics
METI's Top Runner Program is compressing replacement cycles across Japanese industrial facilities, compelling manufacturers to retire IE2 and IE3 motors ahead of schedule. This regulatory pressure is restructuring procurement priorities toward integrated motor-drive systems.
Growth Catalysts
- Factory automation investments:Toyota and Honda are expanding servo motor procurement for precision assembly lines. This capital deployment is pulling demand from general-purpose induction motors toward high-response servo systems.
- METI Top Runner Program:The efficiency mandate is accelerating premium motor replacements in process industries. Compliance deadlines are forcing compressed upgrade timelines across steel and chemical plants.
- Kanto industrial corridor concentration:Manufacturing density across Tokyo, Kanagawa, and Chiba prefectures is creating logistics advantages for just-in-time motor delivery. Proximity to end-users reduces inventory carrying costs for distributors.
Market Restraints
- Copper and rare-earth price volatility:NdFeB magnet costs fluctuate with Chinese export quotas. Japanese motor manufacturers face margin compression when yen depreciation coincides with raw material spikes.
- Semiconductor supply concentration:Variable frequency drive production depends on IGBT and SiC module availability from limited Asian foundries. Bottlenecks constrain integrated motor-drive package output.
- IE5 technical limitation:Synchronous reluctance motor efficiency gains require specialized rotor laminations. Manufacturing complexity limits scalable production for mid-power ranges.
Strategic Opportunities
- Carbon neutrality roadmap alignment:METI's 2050 net-zero targets will tighten efficiency mandates beyond current IE4 tiers. Early compliance positioning creates specification advantages in public procurement.
- HVAC electrification:Heat pump deployment in residential and commercial buildings is expanding variable-speed compressor motor demand. Building energy codes are mandating inverter-driven systems.
- Predictive maintenance convergence:Vibration sensors and edge analytics are enabling condition-based motor replacement. Integration with existing SCADA infrastructure creates aftermarket service revenue pools.
Industry Challenges
- Power electronics integration complexity:Combining motors with drives requires thermal management and EMI shielding expertise. Japanese OEMs face skill gaps in mechatronics systems engineering.
- JIS certification timelines:Revised testing protocols for high-efficiency motors extend approval cycles. Product launch delays risk missing seasonal procurement windows.
- Legacy equipment interoperability:New IE4 motors must interface with existing inverter installations dating to the 1990s. Parameter mismatch causes commissioning failures and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan AC Motor Market |
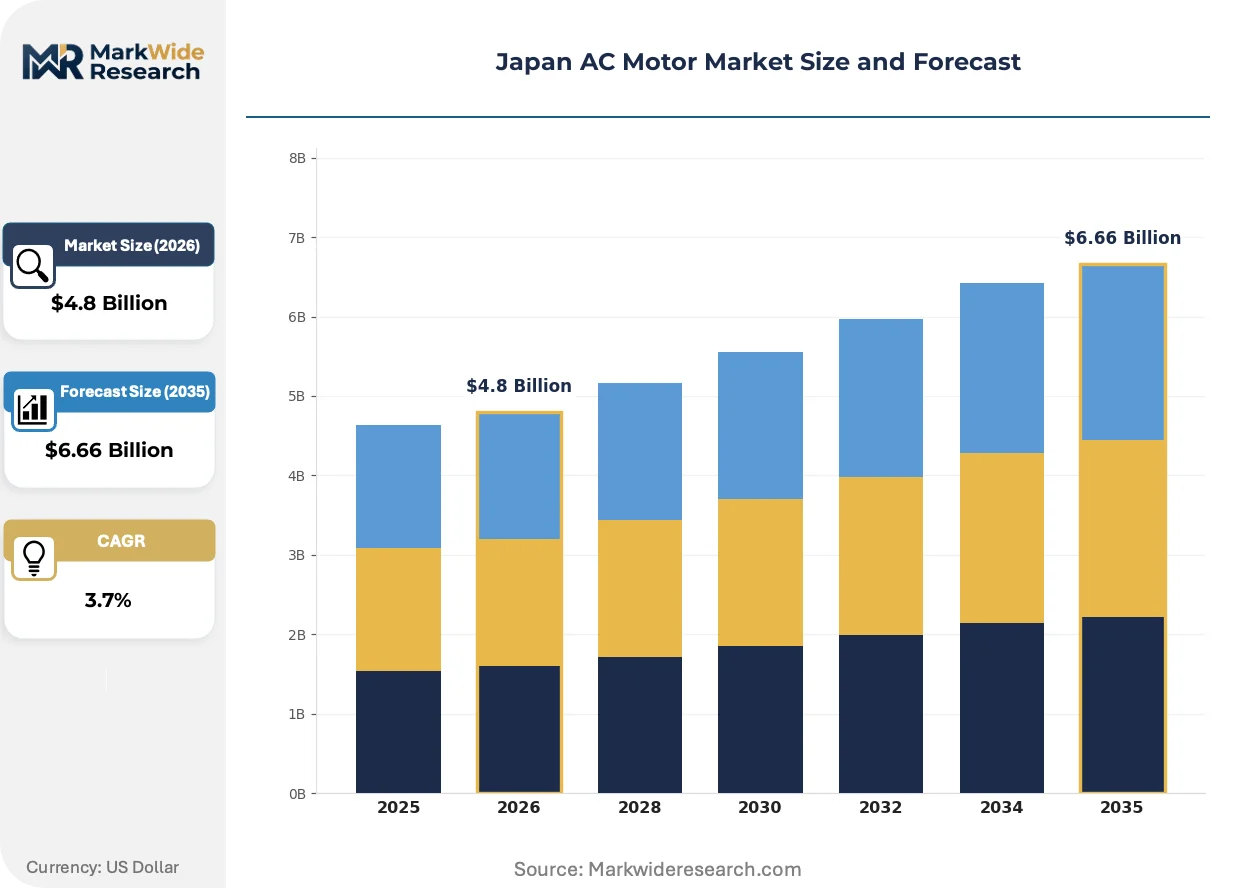
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction, Synchronous, Servo, Variable Frequency End User: Manufacturing, HVAC, Automotive, Consumer Appliances Installation Type: Indoor, Outdoor, Wall-Mounted, Floor-Installed Control Method: Direct-On-Line, Star-Delta, Soft Start, V/F Control |
| Companies Covered | Nidec Corporation, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Toshiba Corporation, Fuji Electric Co Ltd, Panasonic Corporation, Hitachi Industrial Equipment Systems Co Ltd, Meidensha Corporation, Oriental Motor Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan AC Motor Market Trends and Innovations
Electrification of thermal processes and precision manufacturing requirements are reshaping motor specifications across Japanese industry. Technology migration, regulatory compression, and procurement model evolution are the three forces restructuring competitive positioning.
Permanent magnet synchronous motors are migrating from servo applications into general-purpose industrial drives. Food processing and packaging machinery OEMs are adopting these systems for their torque density and partial-load efficiency advantages. The technology is migrating from premium niche positioning toward mid-market standard equipment, compressing induction motor share in the 1-15 kW range.
METI's 2023 amendment to the Energy Conservation Act tightened motor efficiency benchmarks effective 2025. Manufacturers must now certify IE4 performance for motors above 0.75 kW, eliminating IE2 and IE3 from new installations. Process industries in the Keihin and Chukyo industrial zones are responding with accelerated depreciation schedules for legacy equipment.
Direct OEM contracting is displacing traditional distributor channels for large-volume servo motor procurement. Automotive and semiconductor equipment builders are consolidating supplier relationships to secure allocation priority during supply constraints. This pattern is most visible in Aichi and Osaka prefectures, where Toyota and Panasonic procurement teams have established vendor-managed inventory programs with Nidec and Yaskawa.
Japan AC Motor Market Segmentation
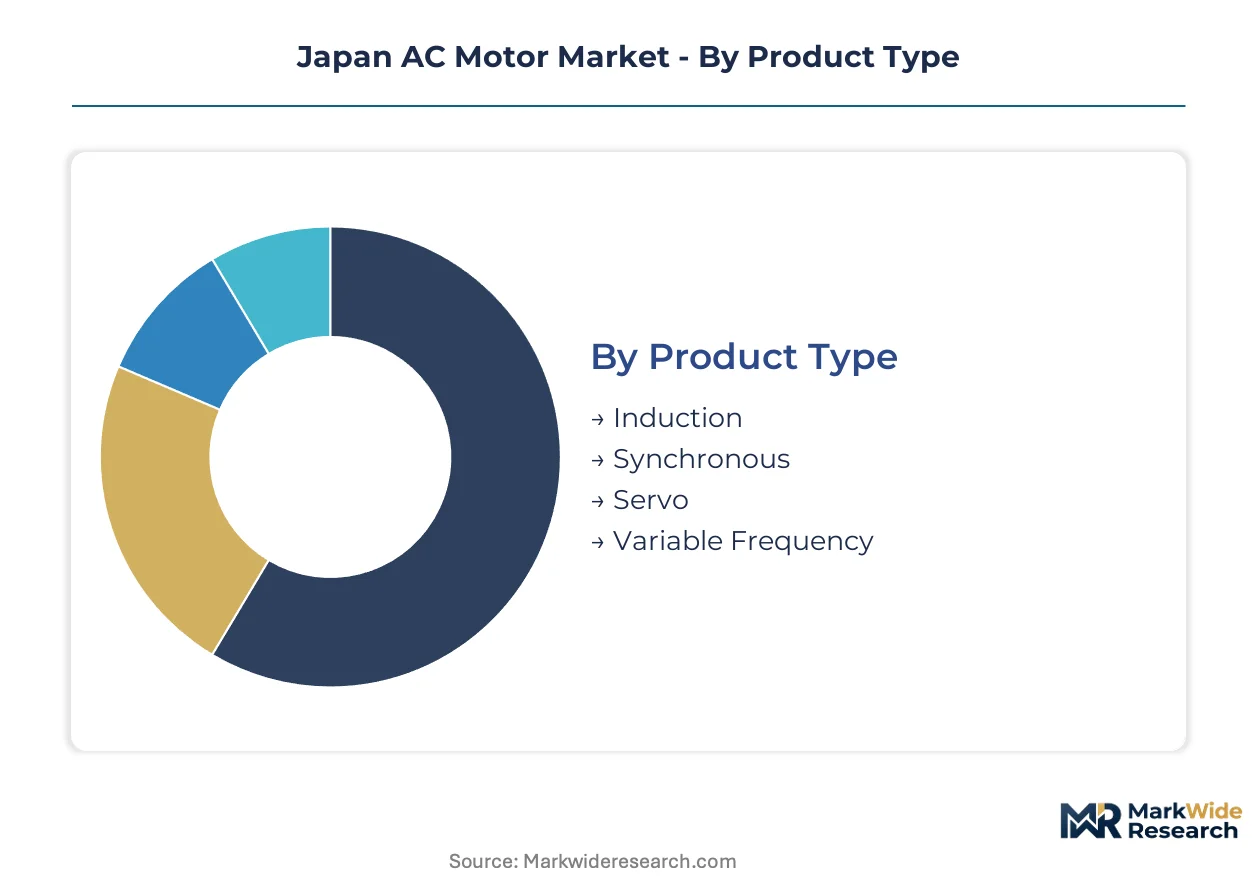
Japanese AC motor procurement patterns diverge sharply across application environments, with METI efficiency mandates and factory automation investments creating distinct demand profiles. Understanding these segment boundaries clarifies where integrated motor-drive systems displace legacy installations versus where standardized induction units retain dominance.
Product Type:
Use-case spectrum spans fixed-speed general industrial drives through precision motion control systems, with efficiency tier and response requirements determining technology selection.
- Induction:Squirrel-cage rotor designs dominate conveyor, pump, and compressor installations across steel and chemical plants in the Keihin industrial zone. METI's IE4 mandate is forcing premature retirement of IE2 and IE3 units in these process-heavy facilities.
- Servo:Permanent magnet synchronous motors with closed-loop position feedback enable sub-micron accuracy for semiconductor pick-and-place equipment and automotive assembly robotics. Toyota and Honda procurement teams in Aichi prefecture are consolidating supplier relationships for these high-response systems.
- Synchronous:Reluctance and PM-assisted designs deliver premium efficiency for fan and blower applications where constant speed operation prevails.
- Variable Frequency:Integrated motor-drive packages pair induction or PM motors with inverter electronics for HVAC and process control flexibility.
The dominant share belongs to Induction motors, while Servo systems are closing the gap fastest through automotive and electronics manufacturing automation.
End User:
Customer archetypes range from capital-intensive process industries through distributed building systems, with procurement scale and technical sophistication varying accordingly.
- Manufacturing:Machine tool builders and factory automation integrators in the Kanto and Chukyo corridors specify motors for robotics, conveyors, and precision positioning equipment. Just-in-time delivery requirements favor suppliers with regional distribution centers.
- HVAC:Heat pump and chiller OEMs demand variable-speed compressor motors compliant with building energy codes. Residential and commercial electrification trends in Tokyo and Osaka metropolitan areas are expanding inverter-driven system procurement.
- Automotive:Tier-1 suppliers and OEM assembly plants require servo motors for welding, painting, and powertrain assembly lines.
- Consumer Appliances:Washing machine and air conditioner manufacturers source high-volume, cost-optimized induction and PM motor platforms.
Manufacturing commands the largest procurement volume, though HVAC is expanding most quickly through building electrification mandates.
Installation Type:
Physical mounting constraints determine enclosure ratings, thermal management requirements, and maintenance accessibility across industrial and commercial environments.
- Indoor:TEFC and ODP enclosures protect windings in climate-controlled factory floors and mechanical rooms. Food processing facilities in Osaka prefecture specify washdown-rated variants for hygiene compliance.
- Outdoor:Weatherproof housings with enhanced sealing withstand exposure at wastewater treatment plants and remote pumping stations. Coastal installations in Chiba prefecture require corrosion-resistant coatings.
- Wall-Mounted:Compact frame designs optimize floor space in crowded equipment rooms and small manufacturing cells.
- Floor-Installed:Rigid base mounting accommodates large-frame motors above 75 kW for steel mill drives and power generation auxiliaries.
Indoor configurations hold the majority position, yet Outdoor specifications are climbing fastest through infrastructure resilience investments.
Control Method:
Starting and speed regulation approaches reflect trade-offs between capital cost, energy efficiency, and mechanical stress on driven equipment.
- Direct-On-Line:Full-voltage starting remains prevalent for small motors below 5 kW where inrush current does not disrupt distribution systems. Cost-sensitive consumer appliance and small machine tool applications in regional manufacturing clusters favor this simplicity.
- Star-Delta:Reduced-voltage starting limits torque surge for medium-power pumps and compressors in water treatment and chemical processing facilities.
- Soft Start:Thyristor-based voltage ramping protects conveyor belts and gearboxes from mechanical shock in material handling systems.
- V/F Control:Variable frequency drives enable precise speed matching for HVAC fans, pumps, and energy-efficient process control across METI-regulated industrial sites.
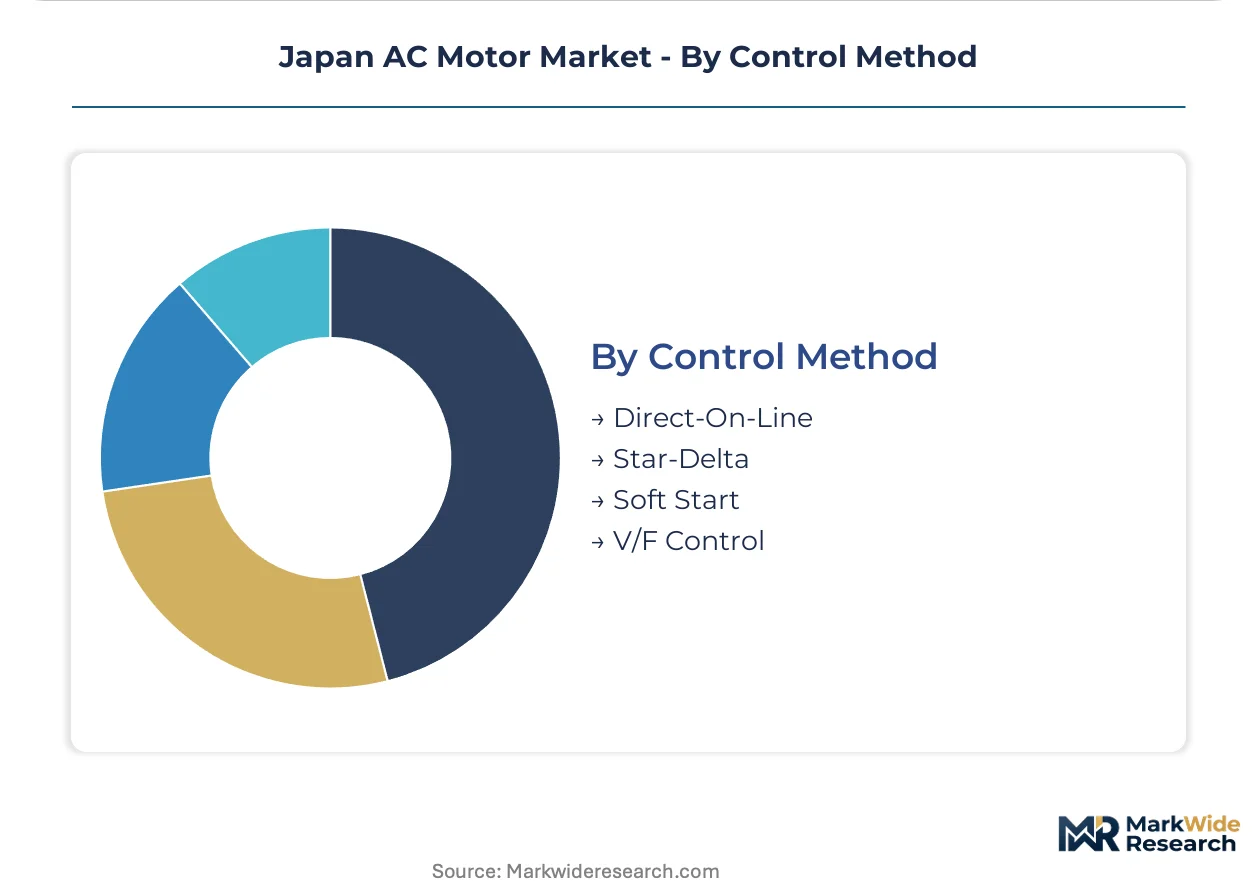
Direct-On-Line retains prevalence in low-power segments, while V/F Control is gaining share fastest through integrated motor-drive package adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama anchors Kanto's industrial logistics, enabling just-in-time motor delivery to manufacturing clusters across Tokyo, Kanagawa, and Chiba prefectures. This maritime infrastructure underwrites Japan's position as the dominant AC motor demand center in Asia-Pacific.
Kanto/Tokyo
Semiconductor equipment builders and automotive Tier-1 suppliers drive servo motor procurement across the Greater Tokyo area. METI's Top Runner Program enforces IE4 efficiency standards for motors above 0.75 kW. The Keihin industrial zone spanning Kawasaki and Yokohama hosts steel and chemical plants executing compressed replacement cycles for legacy IE2 and IE3 units.
Kansai/Osaka
Food processing machinery OEMs and packaging equipment manufacturers specify washdown-rated TEFC motors for hygiene compliance. JIS standards govern dimensional interchangeability across Osaka prefecture's supplier base. The Sakai-Senba industrial corridor concentrates motor distributors serving small and mid-size machine tool builders with regional distribution centers.
Chubu/Nagoya
Toyota's assembly plants and supplier parks in Aichi prefecture consolidate servo motor procurement through vendor-managed inventory programs. METI's carbon neutrality roadmap tightens efficiency mandates beyond current IE4 tiers for automotive powertrain manufacturing. The Chukyo industrial zone encompasses precision machining clusters in Okazaki and Anjo cities.
Kyushu
Semiconductor fabrication facilities in Kumamoto and Fukuoka prefectures demand high-response servo systems for wafer handling equipment. The country's national industrial efficiency regulator extends Top Runner compliance deadlines for process industries with extended depreciation schedules. The northern Kyushu tech corridor attracts motor suppliers establishing satellite technical service centers.
Hokkaido
Food processing and cold chain logistics operators specify outdoor-rated motors with corrosion-resistant coatings for coastal installations. Building energy codes mandate inverter-driven HVAC systems for commercial electrification in Sapporo's metropolitan area. The Tomakomai port zone supports heavy industrial motor applications in pulp and paper processing facilities.
Japan AC Motor Market Competitive Landscape
On the supply side, the industry is consolidated around integrated electromechanical conglomerates with captive inverter and control electronics capabilities. Three strategic archetypes dominate: full-system integrators combining motors with drives and PLCs; component specialists leveraging spindle motor expertise into industrial cross-selling; and precision motion control houses anchored in robotics OEM relationships. Capacity expansion in SiC module production and strategic partnerships for rare-earth magnet supply security represent the dominant competitive vectors.
Among Japan-based electromechanical manufacturers, Nidec Corporation, Yaskawa Electric Corporation, and Mitsubishi Electric Corporation occupy positions exemplifying distinct competitive archetypes. Nidec represents the component-to-systems cross-sell model, translating spindle motor scale into industrial AC solutions. Yaskawa exemplifies the precision motion specialist archetype through deep robotics integration. Mitsubishi sits within the full-system integrator tier, bundling motors with inverters and programmable controllers. These three entities anchor the competitive structure through differentiated channel access and technology positioning rather than undifferentiated scale competition.
| Leading Market Players |
|---|
| Nidec Corporation |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Fuji Electric Co Ltd |
| Panasonic Corporation |
| Hitachi Industrial Equipment Systems Co Ltd |
| Meidensha Corporation |
| Oriental Motor Co Ltd |
| Others |
Pricing and Supply Chain Analysis
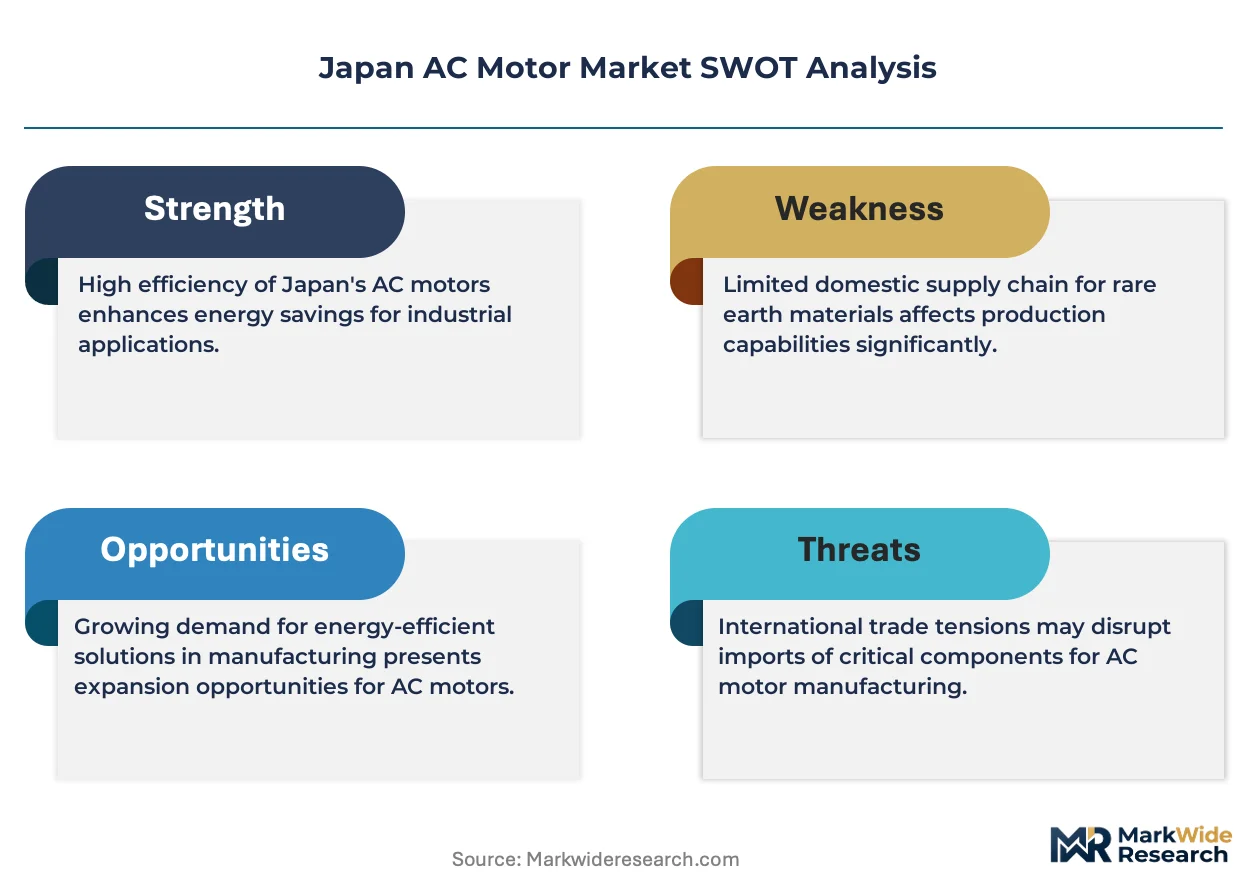
Undercapacity in Japanese SiC module fabrication is compressing margins across integrated motor-drive packages while amplifying pricing power for suppliers with captive power electronics capacity. This utilization squeeze forces buyers into longer-term contracting and tiered volume commitments to secure allocation.
Pricing Analysis
Three-tier pricing structure across premium IE5, standard IE4, and economy IE3 remnant levels stratifies procurement. Price differentiation rests on METI certification tier and annual volume scale, with automotive OEMs commanding steepest discounts through vendor-managed inventory programs. Cost compression in mid-power induction segments is intensifying because Chinese competitors are cross-shipping into Kanto industrial corridors. Small machine tool builders in regional manufacturing clusters exhibit highest price sensitivity, while semiconductor equipment OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Copper cathode and NdFeB magnet feedstock draws from Chilean mining operations and Chinese rare-earth processing complexes respectively. Japanese motor manufacturing rests on Taiwanese foundry capacity for IGBT modules and South Korean suppliers for SiC wafers. Single-source vulnerability in rare-earth magnet supply creates exposure to Chinese export quota fluctuations. Distribution runs through authorized distributors in the Sakai-Senba corridor serving machine tool builders, with direct OEM contracting displacing traditional channels for large-volume servo procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's AC motor market sits in early-cycle expansion as METI's IE4 mandate forces premature replacement of installed IE2 and IE3 bases ahead of regulatory deadlines.
For Market Incumbents: Insulate servo motor margins by locking in multi-year supply agreements with Toyota and Honda procurement teams before Chinese competitors establish technical service presence in Aichi prefecture. Backward integration into SiC module sourcing through partnerships with Taiwanese foundries secures allocation priority during supply constraints. For New Entrants and Emerging Players: Build out predictive maintenance service capabilities targeting steel and chemical plants in the Keihin industrial zone where legacy motor populations exceed depreciation schedules. The most penetrable segment lies in aftermarket vibration monitoring integration with existing SCADA infrastructure, using condition-based replacement triggers to displace incumbent distributors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated motor-drive manufacturing as SiC module fabrication requires specialized cleanroom capacity. Long-term viability favors acquirers targeting precision motion control specialists with established robotics OEM relationships rather than commodity induction motor assemblers. The signal to watch is METI's timeline for IE5 mandate introduction, which would obsolete current IE4-dominant production lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Module Sourcing | Captive semiconductor supply secures allocation priority for integrated motor-drive packages during foundry constraints. |
| Vendor-Managed Inventory Programs | Toyota and Honda procurement consolidation creates locked-in demand streams with reduced price volatility exposure. |
| Predictive Maintenance Platform Development | Vibration sensor integration with existing SCADA infrastructure opens recurring aftermarket revenue pools in process industries. |
| IE5 Synchronous Reluctance R&D Investment | Early compliance positioning ahead of METI's next efficiency tier creates specification advantages in public procurement. |
| Regional Technical Service Center Expansion | Satellite facilities in Kyushu's semiconductor corridor reduce response times for wafer handling equipment downtime. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at Toyota and Honda assembly facilities, procurement managers at Nidec and Yaskawa distribution centers, and maintenance directors at Keihin zone steel plants. Secondary validation drew from METI efficiency standard filings, JIS certification registries, customs trade data for copper and rare-earth imports, and SEC disclosures from listed electromechanical manufacturers. Bottom-up motor shipment tallies by prefecture were triangulated against top-down industrial electricity consumption patterns.
Calibration against historical replacement cycle data and METI compliance deadline phasing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include motor technology type, end-use industry, efficiency certification tier, and control method complexity. CAGRs were derived from regression analysis of capital expenditure patterns at named automotive and semiconductor OEMs, cross-checked against HVAC equipment shipment correlations with building energy code adoption timelines.
Stress conditions across yen depreciation rates, Chinese rare-earth export quota volatility, and SiC foundry utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding METI regulatory timeline adherence and automotive production stability. Cross-checking against Japan Electrical Manufacturers Association shipment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Gear Motor Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
Global Permanent Magnet Motor Market