
 AC Motor Market | 2026-2036
AC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
AC Motor Market Analysis
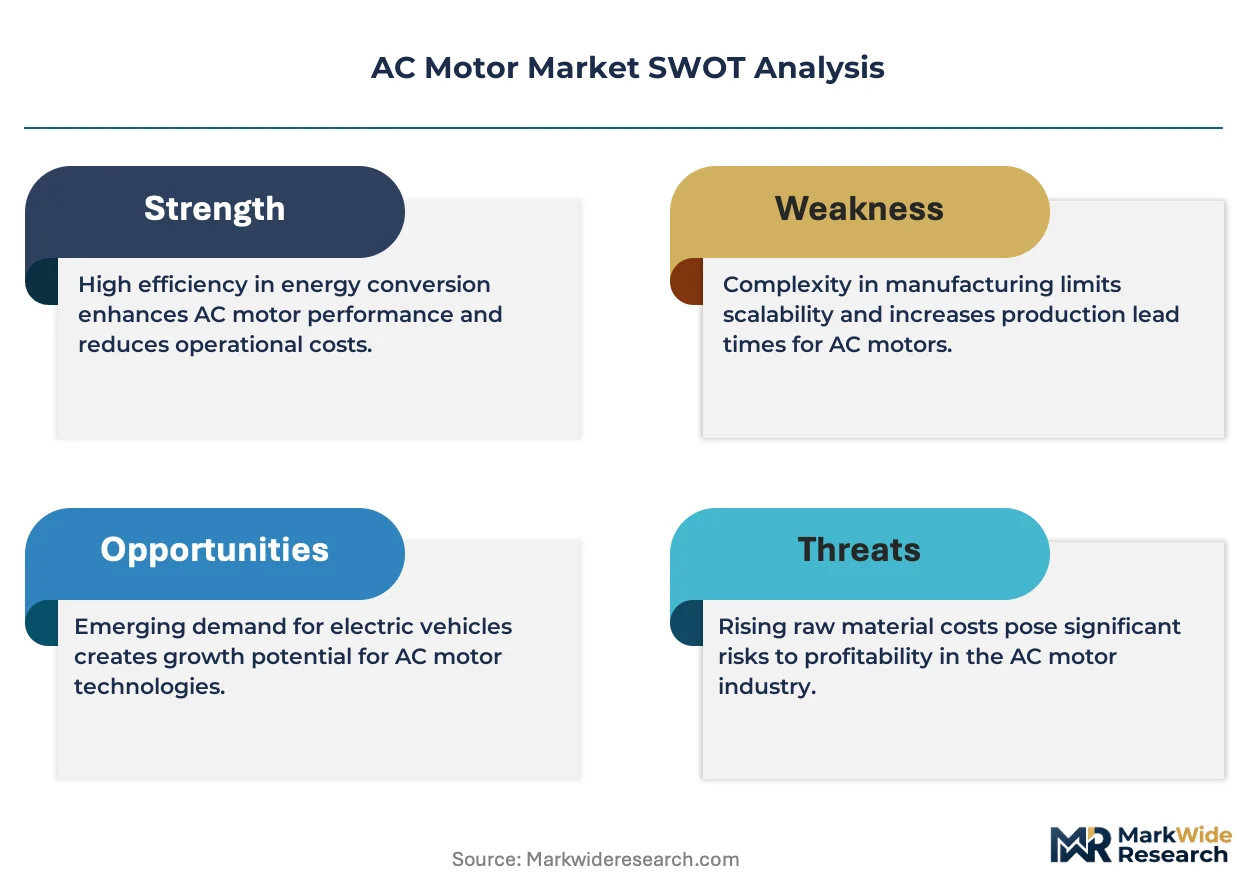
A capital-intensity divergence between integrated manufacturers and assembly-focused competitors is rotating competitive advantage toward firms with in-house lamination and magnet supply chains. ABB leverages captive rare-earth sourcing to sustain margin resilience across medium-power industrial lines. Siemens anchors European demand through localized IEC premium-efficiency production. WEG competes aggressively in Latin American infrastructure projects where import substitution policies favor regional manufacturing footprints.
An AC motor converts alternating electrical current into mechanical rotation through electromagnetic induction, typically operating at fixed or variable speeds determined by supply frequency and pole count, with squirrel-cage and wound-rotor configurations defining torque characteristics for load-matched performance. Its primary purpose spans industrial process automation, thermal management, and fluid handling systems where reliable electromechanical energy conversion under sustained duty cycles remains critical. Induction motors occupy the mature volume core across HVAC and pumping applications where cost optimization outweighs precision requirements. Synchronous architectures are gaining share in conveyor and positioning systems demanding exact speed holding. Automotive end-use represents the fastest-expanding margin pool as traction motor integration into electric drivetrains redefines power density benchmarks.
The US Department of Energy enforces minimum efficiency standards under NEMA MG 1, while the EU Ecodesign Directive and IEC 60034-30-1 frame premium-efficiency tiers that restrict market access for non-compliant imports. China's GB 18613 standard and MIIT energy-efficiency labeling create parallel compliance obligations for manufacturers serving domestic industrial modernization programs. Stakeholders must monitor evolving magnet supply chain regulations and efficiency tier migrations to align product portfolios with jurisdiction-specific certification requirements.
Market Dynamics
Factory electrification programs and IEC efficiency tier migrations are compressing legacy motor economics while concentrating procurement authority among industrial automation buyers with captive maintenance networks.
Growth Catalysts
- NEMA MG 1 efficiency mandates:The US Department of Energy's updated minimum efficiency standards are forcing premature replacement cycles across aging HVAC and pumping infrastructure.
- Permanent magnet material innovations:Advanced ferrite and rare-earth-reduced magnet compositions are collapsing cost premiums for synchronous architectures in conveyor and positioning systems.
- Automotive traction motor integration:Electric drivetrain programs are pulling high-power density motor demand from industrial suppliers into qualified automotive tier-1 supply chains.
Market Restraints
- Rare-earth supply concentration:China's dominance in neodymium and dysprosium processing creates vulnerability for manufacturers dependent on premium magnet grades.
- Copper price volatility:Lamination and winding material cost swings compress margin predictability for build-to-order motor producers without forward commodity hedging.
- Legacy infrastructure lock-in:Existing squirrel-cage motor populations in process industries resist capital replacement despite efficiency tier gaps.
Strategic Opportunities
- EU Ecodesign Directive expansion:The EU's tightening premium-efficiency tiers create regulatory tailwinds for IEC 60034-30-1 IE4 and IE5 certified product lines.
- India industrial modernization:PLI scheme incentives for domestic manufacturing are opening import-substitution pathways for regional production footprints.
- Digital twin integration:Convergence of motor-drive systems with predictive maintenance software is creating outcome-based service revenue pools.
Industry Challenges
- Magnet supply chain reconfiguration:Geopolitical sourcing restrictions are forcing rapid supplier qualification timelines that strain quality assurance protocols.
- IEC certification complexity:Multi-jurisdiction efficiency testing requirements extend product launch cycles and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Motor Market |
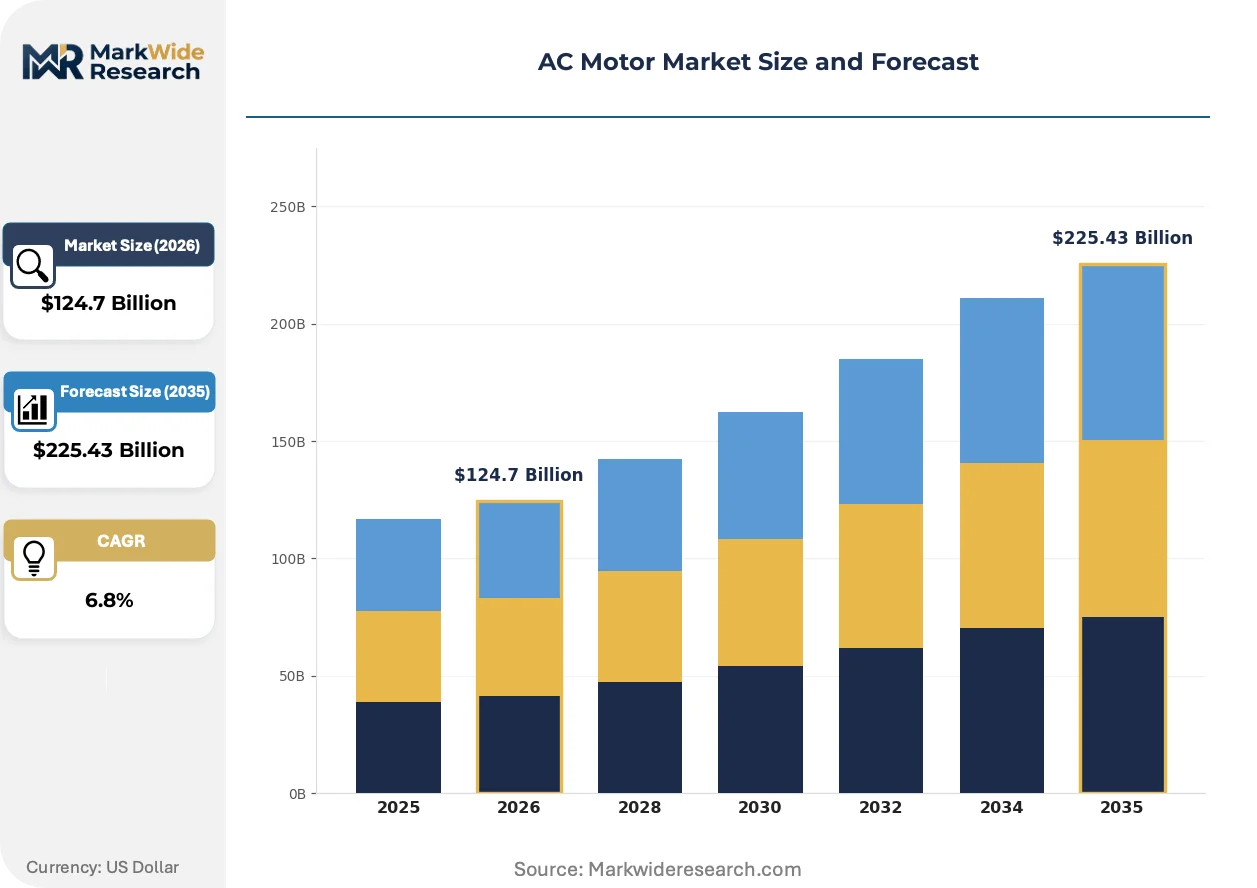
| Market Size in 2026 | $124.7 Billion |
| Market Size in 2035 | $225.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synchronous, Asynchronous, Universal, Induction End User: Industrial, Commercial, Residential, Automotive Application: HVAC, Pumps, Conveyors, Home Appliances Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | ABB, Siemens, Nidec Corporation, WEG, GE Vernova, Emerson Electric Co., Rockwell Automation, Toshiba Corporation, Johnson Electric Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Motor Market Emerging Trajectories
Electromagnetic design software and additive manufacturing are collapsing prototyping cycles while fragmenting traditional scale advantages in lamination production.
Hairpin winding technology is fragmenting conventional round-wire motor architectures by enabling higher slot fill factors and improved thermal performance. Automotive traction programs are adopting hairpin designs at volume scale previously reserved for aerospace applications. The technology is fragmenting established supplier hierarchies by allowing tier-2 stator producers to compete on power density metrics.
The EU F-Gas Regulation is accelerating refrigerant transition timelines that cascade into compressor motor redesign requirements. Industrial HVAC OEMs must revalidate motor-hermetic sealing compatibility with lower-global-warming-potential refrigerants. European cold-chain infrastructure represents the most affected end-use vertical, with contractors pre-specifying compliant motor-compressor packages.
Buyers are consolidating procurement authority through integrated facility management contracts that bundle motor specification with predictive maintenance obligations. Traditional distributor channels face disintermediation as energy service companies capture specification influence through guaranteed efficiency performance contracts. Germany's industrial energy audit subsidy programs are accelerating this consolidation in manufacturing clusters.
AC Motor Market Segmentation
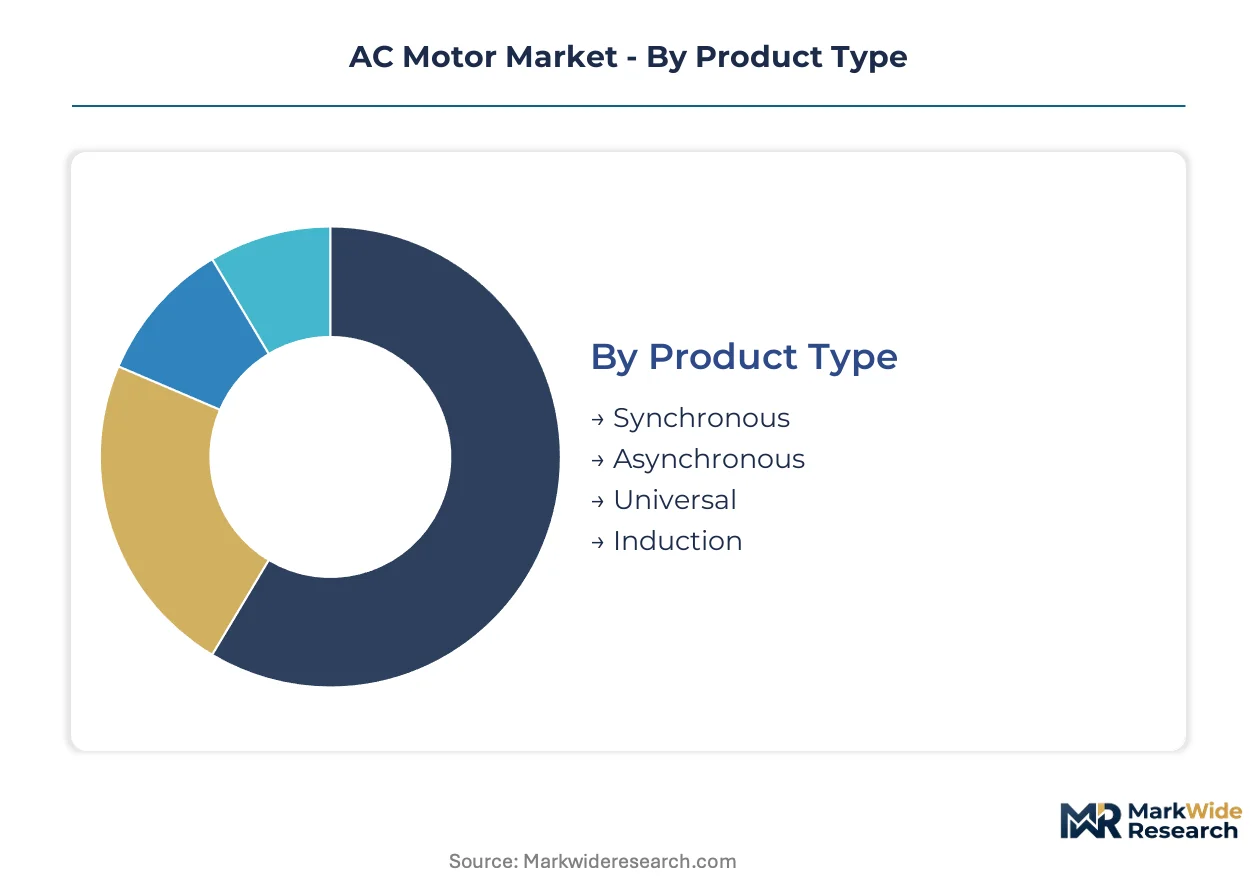
AC motor procurement patterns fragment sharply across efficiency tiers and duty-cycle requirements. Regulatory mandates in major manufacturing economies compress allowable operating-cost differentials between segments.
Product Type:
NEMA MG 1 and IEC 60034-30-1 efficiency tiers create divergent compliance obligations that reshape competitive positioning across motor architectures.
- Synchronous:Permanent magnet rotors deliver exact speed holding for positioning systems and precision conveyors. Demand concentrates in German automotive manufacturing and Chinese electric vehicle drivetrain programs where IEC IE4 certification gates supplier qualification.
- Induction:Squirrel-cage configurations dominate HVAC and pumping infrastructure through mature cost optimization. US commercial building retrofits under Department of Energy mandates sustain replacement volume despite efficiency tier compression.
- Asynchronous:Wound-rotor designs address heavy starting torque requirements in mining and cement processing applications.
- Universal:Series-wound commutator motors persist in portable power tools and domestic appliances where variable-speed control outweighs efficiency priorities.
Established volume favors Induction; emerging adoption favors Synchronous.
End User:
Customer procurement authority concentrates with industrial automation buyers possessing captive maintenance networks and energy-audit capabilities.
- Industrial:Process automation buyers specify medium-power units for pumping and compressor duty. Factory electrification programs in China and Germany accelerate IE3 and IE4 tier migration.
- Automotive:Traction motor integration into electric drivetrains pulls high-power density demand from industrial suppliers. Tier-1 supplier qualification timelines favor synchronous architectures with hairpin winding technology.
- Commercial:Facility management contracts bundle HVAC motor specification with predictive maintenance obligations.
- Residential:Home appliance OEMs prioritize cost-optimized induction units for washing machines and refrigeration compressors.
Procurement consolidation favors Industrial; margin expansion favors Automotive.
Application:
Duty-cycle intensity and thermal management requirements determine motor architecture selection across end-use verticals.
- HVAC:Hermetic compressor motors face redesign pressure from EU F-Gas Regulation refrigerant transitions. European cold-chain infrastructure contractors pre-specify compliant motor-compressor packages.
- Pumps:Municipal water infrastructure and agricultural irrigation sustain medium-power induction demand across India and Latin America.
- Conveyors:Material handling systems in logistics and mining specify synchronous units for exact speed holding under variable load.
- Home Appliances:Washing machine and dishwasher OEMs in China and Southeast Asia drive universal motor volume for spin-cycle applications.
Regulatory pressure favors HVAC; infrastructure investment favors Pumps.
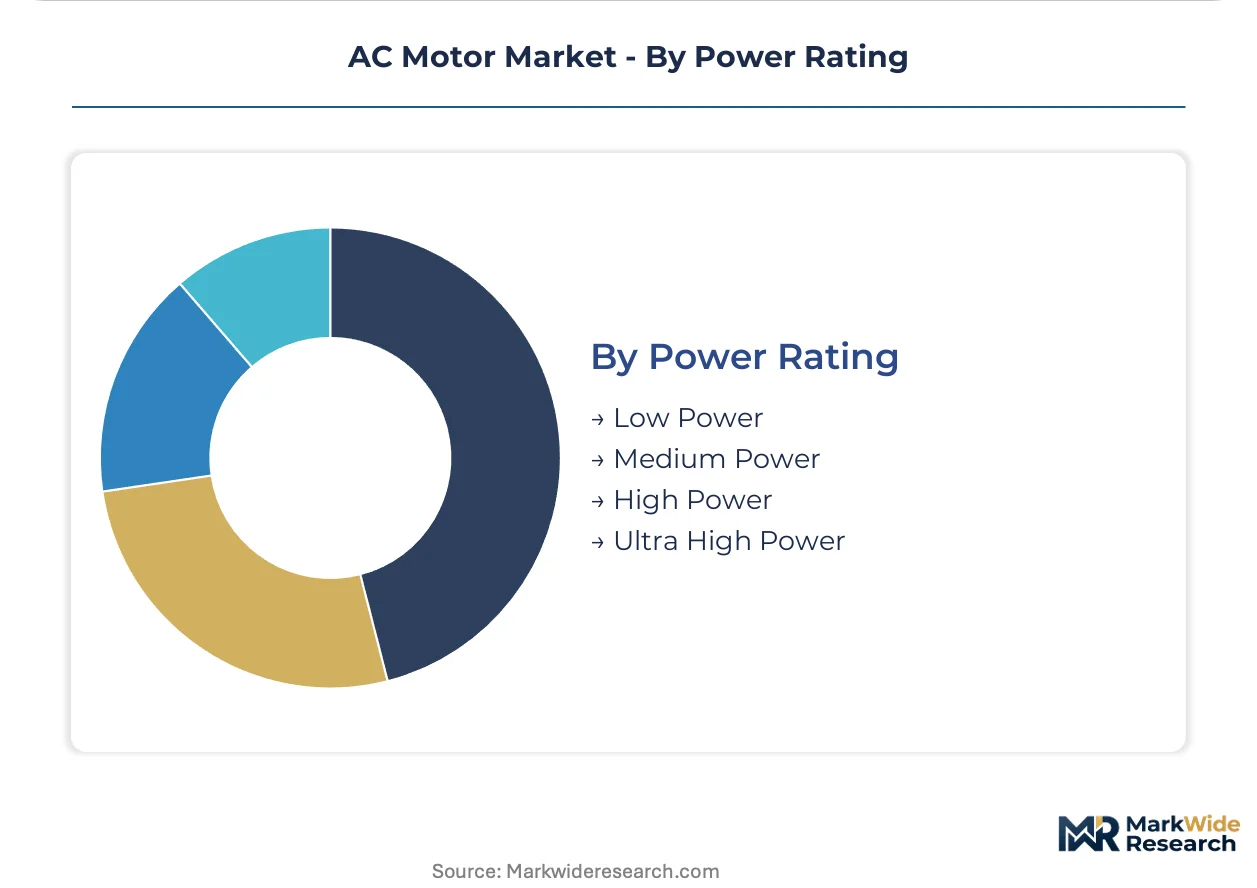
Power Rating:
Copper and magnet material intensity scales nonlinearly with power tier, concentrating margin pressure on build-to-order producers without commodity hedging.
- Medium Power:Industrial process automation and commercial HVAC sustain the core revenue pool. ABB and Siemens compete through captive lamination supply and localized IEC production.
- High Power:Traction motor programs in electric drivetrains redefine power density benchmarks. Automotive tier-1 qualification requirements fragment traditional industrial supplier hierarchies.
- Low Power:Residential appliances and small commercial equipment prioritize cost-optimized designs with minimal efficiency tier compliance overhead.
- Ultra High Power:Heavy industry and marine propulsion applications specify custom wound-rotor designs with extended lead times.
Volume concentration favors Medium Power; technology disruption favors High Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for AC motors tilt toward manufacturing surplus in Germany and China against deficit positions in the United States and India. Duty-cycle standardization and efficiency tier harmonization are compressing cross-border arbitrage opportunities. Regional production footprints increasingly determine supplier qualification for electrification programs.
United States
Commercial HVAC retrofits and automotive battery plant construction drive medium-power unit procurement. The Department of Energy enforces NEMA MG 1 efficiency mandates that accelerate replacement cycles. Industrial clusters in Michigan and Ohio concentrate electric drivetrain motor demand from Detroit automakers.
Germany
Factory electrification programs and conveyor system modernization sustain synchronous motor demand. The EU Ecodesign Directive and IEC 60034-30-1 frame premium-efficiency tiers restricting non-compliant imports. The Baden-Württemberg automotive belt anchors IE4-certified supplier qualification for precision manufacturing lines.
China
Domestic electric vehicle production and industrial modernization programs absorb high-volume synchronous and induction output. MIIT energy-efficiency labeling under GB 18613 creates parallel compliance obligations for manufacturers. The Yangtze River Delta concentration of motor producers serves both export markets and captive automotive demand.
India
Agricultural irrigation infrastructure and municipal water pumping sustain medium-power induction motor procurement. PLI scheme incentives for domestic manufacturing open import-substitution pathways for regional footprints. Gujarat and Maharashtra industrial corridors concentrate textile and chemical processing demand for duty-rated units.
Brazil
Mining material handling and sugar-ethanol processing equipment drive wound-rotor and high-torque induction demand. Import substitution policies favor regional manufacturing footprints for infrastructure tenders. The São Paulo industrial belt anchors supplier relationships with Latin American mining operators.
AC Motor Market Vendor Landscape
Concentration sits with diversified electromechanical conglomerates possessing captive magnet supply and localized IEC certification capabilities. The vendor base spans three tiers: integrated manufacturers with in-house lamination and rare-earth sourcing, assembly-focused competitors dependent on external magnet supply, and regional specialists serving import-substitution markets. Strategic moves center on backward integration into permanent magnet supply chains and geographic expansion through qualified local production to satisfy jurisdiction-specific efficiency certification.
Within the integrated manufacturer tier, ABB leverages captive rare-earth sourcing to sustain margin resilience across medium-power industrial lines. Siemens anchors European demand through localized IEC premium-efficiency production. WEG competes aggressively in Latin American infrastructure projects where regional manufacturing footprints satisfy import substitution requirements.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Nidec Corporation |
| WEG |
| GE Vernova |
| Emerson Electric Co. |
| Rockwell Automation |
| Toshiba Corporation |
| Johnson Electric Holdings Limited |
| Others |
Supply Flow & Price Mechanics
NEMA MG 1 and IEC 60034-30-1 efficiency certification gates simultaneously determine supplier qualification eligibility and price differentiation thresholds across AC motor procurement. Buyers without captive maintenance networks face compressed negotiation leverage as compliance overhead concentrates pricing power with integrated manufacturers possessing in-house testing facilities.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard catalog units, particularly for IE4 and IE5 synchronous architectures with hairpin winding specifications. Three-tier pricing structure across premium, standard, and economy levels segments by efficiency certification grade and after-sales service bundling. Cost compression in medium-power induction tiers is intensifying because copper price volatility erodes margin predictability for build-to-order producers. Industrial automation buyers with energy-audit capabilities exhibit lowest price sensitivity, while residential appliance OEMs prioritize cost-optimized designs.
Supply Chain Analysis
Extended lamination and magnet inventory cycles are stretching lead times for premium-efficiency units as geopolitical sourcing restrictions strain supplier qualification timelines. Rare-earth processing concentrates in China, with secondary magnet finishing capabilities in Japan and Germany. Copper winding supply draws from Chilean mining output and German semi-finished wire production. Single-source vulnerability in neodymium processing creates exposure for synchronous motor producers. Distribution runs through authorized industrial distributors and direct OEM supply agreements, with energy service companies capturing specification influence through performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AC motor procurement is consolidating around platform-economics logic as predictive maintenance software convergence transforms hardware vendors into outcome-based service providers. The interoperability shift between motor-drive systems and digital twin platforms redefines competitive moats beyond physical manufacturing scale.
For Market Incumbents: Secure captive rare-earth sourcing through backward integration or long-term offtake agreements to defend margin resilience against magnet supply concentration. Anchor regional production footprints in Germany and China to satisfy IEC certification proximity requirements for automotive tier-1 qualification. Counter emerging hairpin winding specialists by accelerating stator prototyping capabilities through additive manufacturing investment. For New Entrants and Emerging Players: IEC 60034-30-1 IE4 fast-track certification offers entry pathway into German automotive manufacturing and Chinese electric vehicle supply chains where incumbent qualification timelines create procurement gaps. Target India's PLI scheme incentives for domestic motor manufacturing as import-substitution policies favor regional footprints. Pursue white-label stator production partnerships with established drive system integrators to bypass direct OEM qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-power traction motor segments as automotive power density requirements demand specialized lamination and winding equipment. Five-to-ten year viability favors vertically integrated mid-cap specialists with captive magnet supply and localized IEC certification capabilities. Monitor hairpin winding technology adoption curves as inflection indicator for supplier hierarchy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates margin resilience against Chinese processing concentration. |
| Localized IEC Premium-Efficiency Production | Regional manufacturing footprints satisfy EU Ecodesign Directive proximity requirements for automotive qualification. |
| Hairpin Winding Technology Adoption | Advanced stator architectures enable power density competition against established round-wire hierarchies. |
| Digital Twin Platform Integration | Predictive maintenance software convergence creates recurring service revenue beyond hardware transactions. |
| PLI Scheme Manufacturing Footprint Expansion | Indian domestic production incentives open import-substitution pathways for regional infrastructure tenders. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC manufacturing disclosures, IEC certification registries, and national energy-efficiency labeling databases. Primary interviews engaged plant engineers at automotive OEMs, procurement leads at industrial automation buyers, maintenance directors at process facilities, and aftermarket service heads at distributor networks. Bottom-up unit shipment estimates triangulate against top-down value projections derived from disclosed contract values and import-export balances.
Segmentation dimensions modeled include motor architecture type, efficiency certification tier, power rating band, end-use vertical, and regional production cluster across the projection horizon. CAGRs derive from regression analysis of historical shipment trajectories adjusted for regulatory mandate implementation schedules and factory electrification program commitments. Forecast inputs incorporate copper price futures curves, rare-earth oxide supply projections, and automotive traction motor content-per-vehicle assumptions.
Decision-makers should treat outputs as directional under sustained efficiency tier migration timelines and stable geopolitical trade frameworks; material deviation in magnet supply chain reconfiguration or regulatory acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Spargers Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Smart Motors Market